
 Smart Personal Safety and Security Device Market | 2026-2036
Smart Personal Safety and Security Device Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Personal Safety and Security Device Market Intelligence
The EU Green Deal is pivoting procurement criteria across European industrial employers toward energy-efficient safety hardware with embedded carbon disclosure. ASSA ABLOY AB leverages its access-control heritage to dominate commercial building integration. Samsung Electronics Co., Ltd. competes through cellular-enabled wearable form factors that anchor its Galaxy ecosystem. Garmin Ltd. specializes in ruggedized GPS tracking for outdoor workforce segments.
Smart personal safety and security devices encompass networked hardware and software systems designed to detect threats, transmit distress signals, and enable remote intervention, typically incorporating accelerometers, biometric sensors, and low-power wide-area radio modules operating on sub-1 GHz or licensed cellular bands. Their primary purpose is to reduce emergency response latency while creating auditable duty-of-care records for employers and insurers. Wearable alarms and personal GPS trackers currently occupy the highest-margin tiers, as enterprise buyers prioritize worker-compensation risk reduction over consumer convenience. Bluetooth and cellular connectivity segments are expanding fastest, displacing Wi-Fi-dependent architectures that fail outside building perimeters.
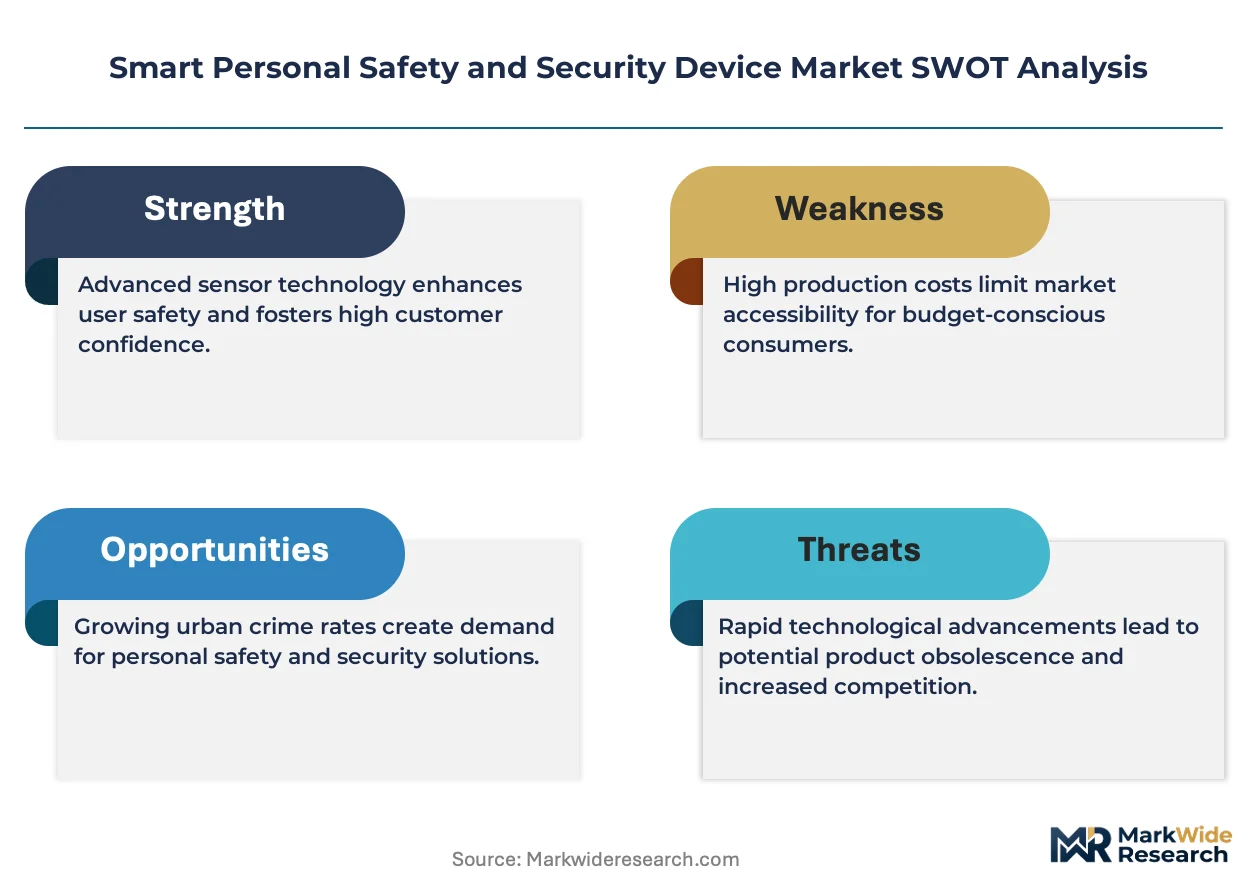
The EU AI Act and GDPR jointly constrain facial-recognition and behavioral-analytics features, forcing redesigns of surveillance cameras and smartphone apps sold into Europe. The FCC in the United States enforces Part 15 emissions rules and E-911 location-accuracy mandates that shape hardware certification timelines and module selection. Stakeholders must decide whether to maintain parallel product SKUs for divergent regulatory zones or pursue unified designs that sacrifice feature depth for compliance breadth.
Market Dynamics
Enterprise procurement of connected worker safety systems is compressing sales cycles and forcing vendors to bundle hardware with cloud-based incident-management platforms. Industrial employers now mandate auditable duty-of-care documentation, shifting purchase authority from facility managers to risk-compliance officers.
Growth Catalysts
- Germany's lone-worker protection mandates:Industrial employers in manufacturing and utilities must equip isolated personnel with distress-signaling hardware, creating baseline demand for cellular-enabled wearables.
- EU AI Act transparency requirements:Biometric-enabled safety devices face mandatory algorithmic disclosure rules, accelerating redesigns toward explainable edge-computing architectures.
- Bluetooth Low Energy 5.3 adoption:Sub-1 GHz mesh networks are extending coverage into underground mining and remote construction sites where cellular fails.
Market Restraints
- GNSS module cost volatility:Multi-constellation GPS receivers consume 18-25% of bill-of-materials in personal trackers, squeezing margins on economy-tier SKUs.
- South Korean battery cell concentration:Cylindrical lithium-ion supply for ruggedized wearables depends on three dominant producers, creating single-source vulnerability.
- GDPR biometric processing friction:Continuous heart-rate and voice-stress monitoring triggers data-controller obligations that slow European rollout of advanced analytics features.
Strategic Opportunities
- India's construction safety enforcement gap:The country's 48 million informal construction workers lack mandated protection, presenting volume potential if BIS certification timelines compress.
- CSRD carbon disclosure alignment:European corporates must report Scope 3 emissions from safety hardware procurement, favoring vendors with embedded lifecycle carbon tracking.
- Ultra-wideband indoor positioning convergence:UWB anchor networks deployed for asset tracking are being repurposed for centimeter-accurate worker location in warehousing and logistics.
Industry Challenges
- FCC Part 15 certification bottlenecks:Sub-1 GHz wearable radios face 14-22 week approval timelines that delay product launches and freeze engineering resources.
- Legacy SCADA integration complexity:Oil and gas operators require safety wearables to feed alarm data into decades-old distributed control systems with proprietary protocols.
- Embedded firmware talent scarcity:Low-power RTOS development for multi-sensor fusion exceeds available supply of engineers with both radio and biometric signal-processing expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Personal Safety and Security Device Market |
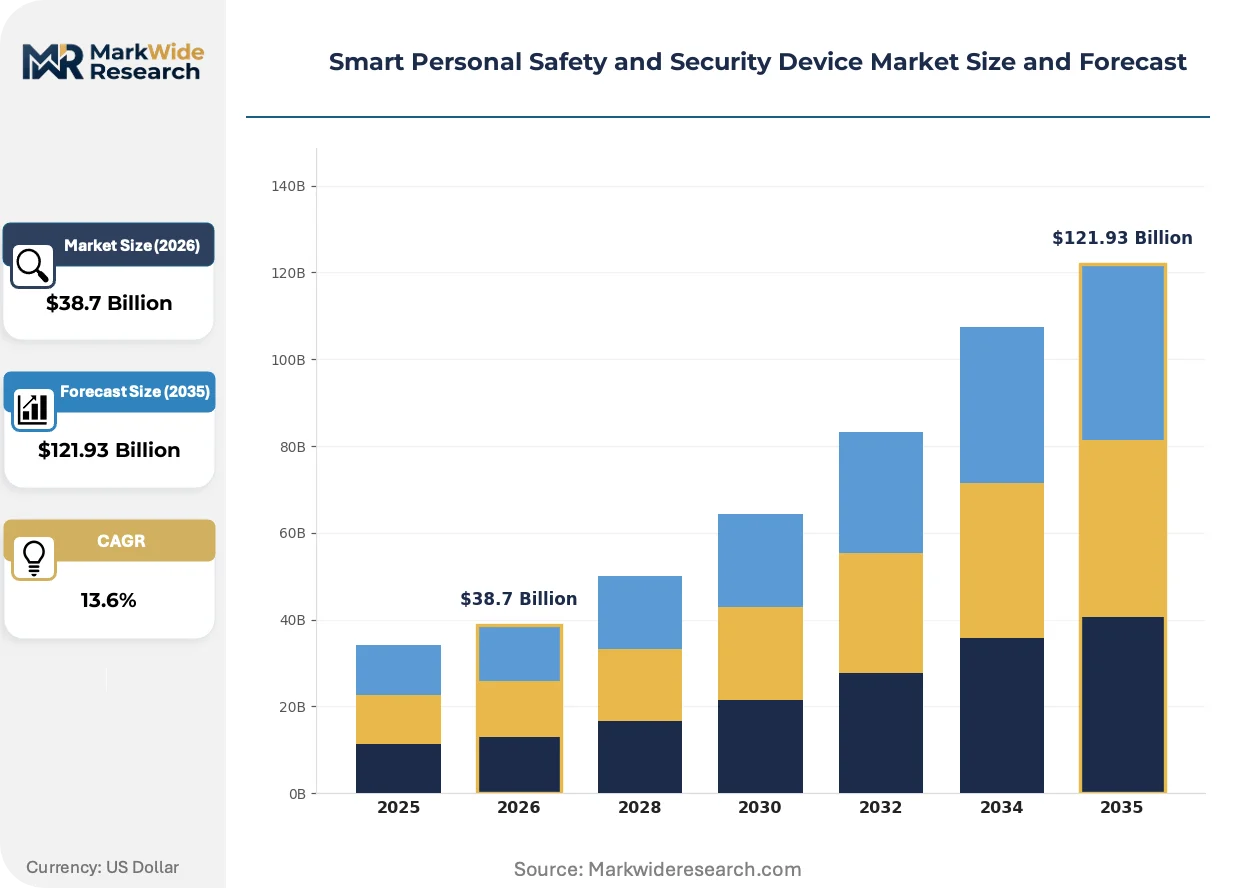
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $121.93 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Alarms, Smartphone Apps, Surveillance Cameras, Personal GPS Trackers Technology: Bluetooth, RFID, Wi-Fi, Cellular End User: Individuals, Families, Security Firms, Corporate Offices Feature: Real-Time Alerts, Remote Monitoring, Location Tracking, Emergency SOS |
| Companies Covered | ASSA ABLOY AB, ADT Inc., Apple, Inc., Fitbit, Arlo Technologies, Inc., Samsung Electronics Co., Ltd., Garmin Ltd., Buddi Limited, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Personal Safety and Security Device Market Strategic Shifts & Innovations
Edge AI inference is migrating onto safety wearables, enabling real-time anomaly detection without cloud dependency. This shift is compressing emergency response latency while creating new hardware-software bundling requirements.
Multi-sensor fusion combining accelerometers, barometric pressure, and UWB ranging is automating fall detection and confined-space entrapment alerts in industrial settings. Mining operators in Australia and Canada are deploying these systems at scale. The technology is automating incident verification that previously required human dispatcher judgment, reducing false-alarm rates below 3%.
The EU AI Act's risk-classification framework is forcing biometric-enabled devices into third-party conformity assessment. Manufacturers must now document training data provenance and model performance across demographic subgroups. Surveillance-integrated safety cameras sold into Europe are being redesigned with on-device processing to limit personal data transmission.
Enterprise buyers are consolidating safety device procurement through integrated facilities-management contracts. Channel intermediaries that previously sold hardware alone are being displaced by vendors offering subscription-based incident-response services. This pattern is most visible in Germany, where industrial employers bundle lone-worker protection with building access control and fire safety systems under single-vendor frameworks.
Smart Personal Safety and Security Device Market Segmentation
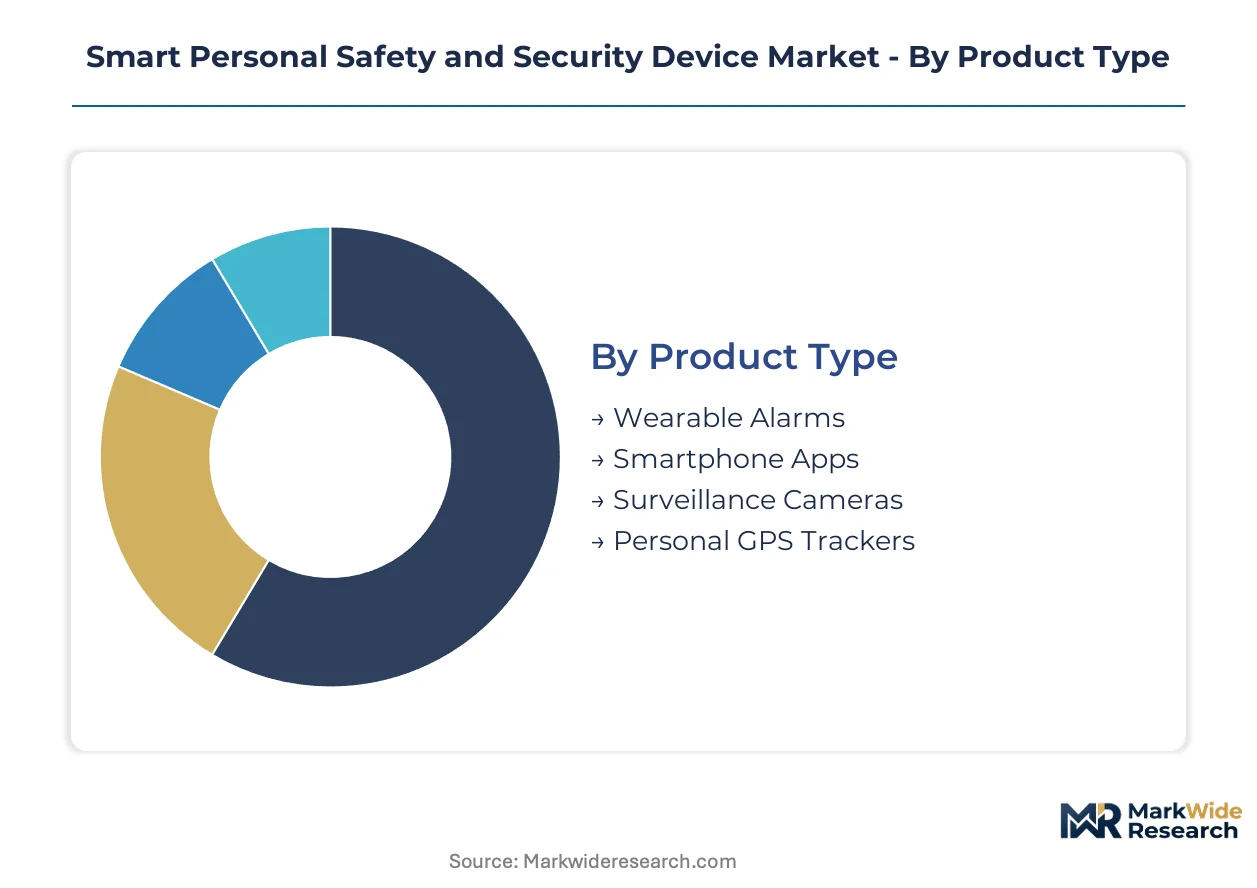
Segmentation in smart personal safety devices reveals how procurement authority, connectivity architecture, and feature bundling reshape vendor economics. Enterprise buyers prioritize integrated incident-management platforms over standalone hardware, compressing margins for single-function suppliers.
Product Type:
Capital intensity varies sharply across form factors, with cellular-enabled wearables demanding the highest upfront investment in RF certification and biometric sensor integration.
- Wearable Alarms:Battery-powered pendants and wristbands incorporating accelerometers and sub-1 GHz radios for lone-worker distress signaling. German industrial employers mandate these for isolated personnel in manufacturing and utilities, driving baseline demand through regulatory compliance rather than discretionary purchase.
- Personal GPS Trackers:Ruggedized devices with multi-constellation GNSS receivers and IP67+ enclosures for outdoor workforce segments. Mining operators in Australia and Canada deploy these at scale for confined-space entrapment alerts, with multi-sensor fusion automating incident verification.
- Smartphone Apps:Software layers leveraging native device sensors and Bluetooth tethering to external beacons.
- Surveillance Cameras:Fixed and pan-tilt units with edge AI processing to limit personal data transmission under GDPR constraints.
Most installed capacity flows through Wearable Alarms. Expansion is steepest in Personal GPS Trackers.
Technology:
Connectivity choice determines coverage boundaries and recurring revenue potential, with licensed cellular commanding premium subscription economics.
- Cellular:Licensed-band modules operating on LTE-M and NB-IoT networks, enabling distress signaling beyond building perimeters where Wi-Fi fails. FCC E-911 location-accuracy mandates shape hardware certification timelines and module selection for devices sold into the United States.
- Bluetooth:Low Energy 5.3 mesh networks extending coverage into underground mining and remote construction sites. Sub-1 GHz variants displace Wi-Fi-dependent architectures in European industrial deployments.
- Wi-Fi:Building-centric connectivity constrained to perimetered environments with existing infrastructure.
- RFID:Passive and active tagging systems for asset-adjacent worker location in warehousing and logistics.
Bluetooth dominates unit volume through mesh network cost advantages. Cellular captures the steepest expansion trajectory as enterprise buyers prioritize outdoor coverage reliability.
End User:
Customer type dictates sales cycle length and bundling requirements, with corporate procurement compressing vendor margins through integrated facilities-management contracts.
- Corporate Offices:Risk-compliance officers now hold purchase authority for connected worker safety systems, mandating auditable duty-of-care documentation. These buyers consolidate procurement through single-vendor frameworks combining lone-worker protection with building access control and fire safety systems.
- Security Firms:Service providers reselling hardware with subscription-based incident-response services, displacing channel intermediaries that previously sold equipment alone.
- Individuals:Consumer purchasers prioritizing convenience features over enterprise-grade reliability.
- Families:Household buyers seeking location tracking for vulnerable members.
Corporate Offices absorb the majority of installed base investment. Security Firms are climbing the fastest as outsourced safety management expands.
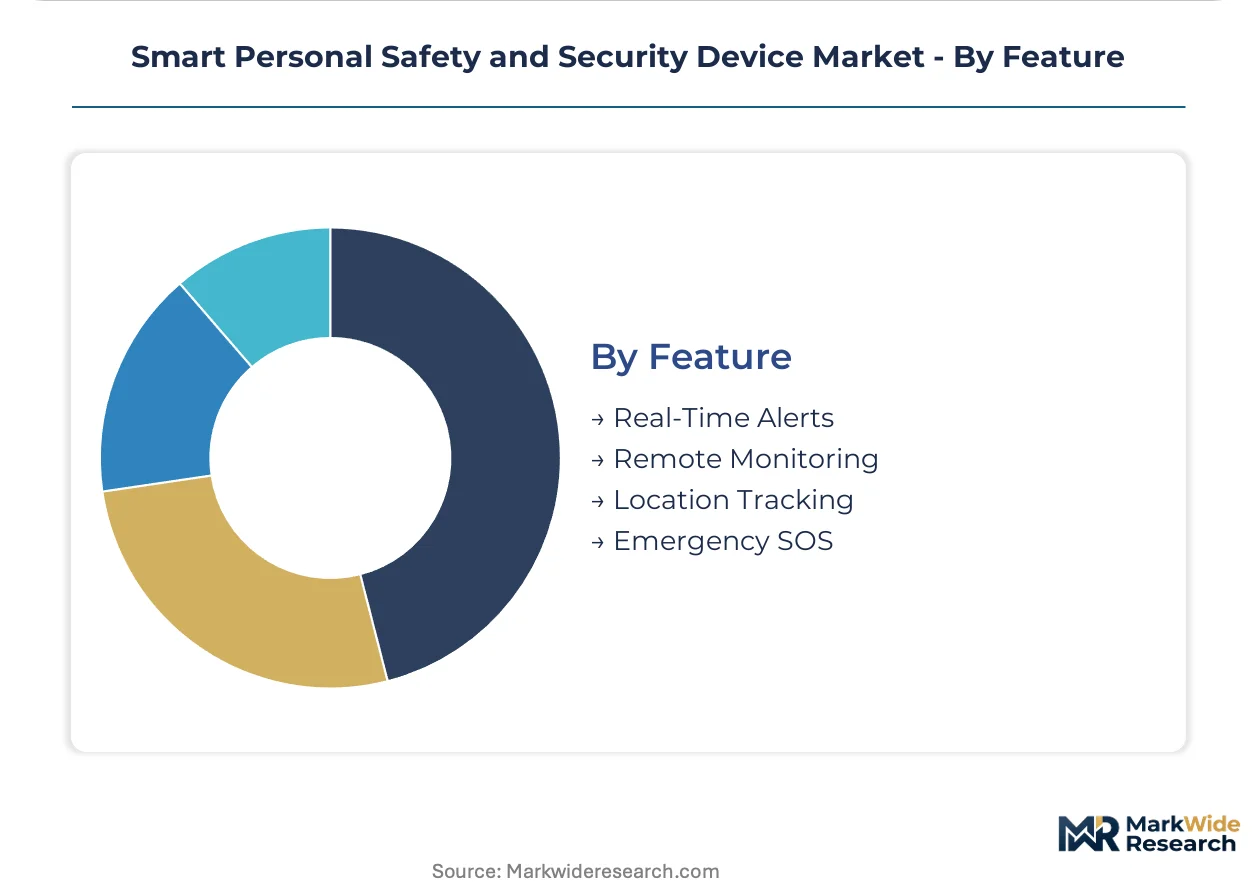
Feature:
Functionality bundling determines hardware-software margin allocation, with real-time processing migrating to edge devices to reduce cloud dependency and response latency.
- Real-Time Alerts:Edge AI inference enabling anomaly detection without network connectivity, compressing emergency response latency. EU AI Act transparency requirements force redesigns toward explainable architectures for biometric-enabled triggers.
- Location Tracking:UWB anchor networks repurposed from asset tracking for centimeter-accurate worker positioning in warehousing and logistics, with multi-constellation GNSS for outdoor segments.
- Emergency SOS:Manual and automated distress signaling with dispatcher integration.
- Remote Monitoring:Cloud-based incident-management platforms bundled with hardware procurement.
Real-Time Alerts command the deepest integration investment. Location Tracking is expanding most quickly through UWB infrastructure convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial safety hardware originated in German mining and heavy manufacturing during the 1970s, establishing regulatory templates that spread across European industrial economies. Contemporary demand concentrates where lone-worker protection mandates intersect with cellular infrastructure buildouts and corporate risk-compliance expansion.
Germany
Industrial employers in manufacturing and utilities must equip isolated personnel with distress-signaling hardware under lone-worker protection protocols. The EU AI Act tightens algorithmic transparency requirements for biometric-enabled devices sold into German facilities. Bavaria's automotive supplier clusters drive procurement of integrated access-control and worker-safety systems under single-vendor frameworks.
United States
Corporate offices expand procurement of connected worker safety systems as risk-compliance officers assume purchase authority from facility managers. FCC Part 15 emissions rules and E-911 location-accuracy mandates shape hardware certification timelines and module selection. Texas and California industrial corridors concentrate deployment of cellular-enabled wearables for oilfield and logistics workforce protection.
China
Construction and mining operators scale deployment of ruggedized GPS trackers with multi-sensor fusion for confined-space entrapment alerts. MIIT regulates sub-1 GHz radio modules and cellular certification timelines for industrial wearable devices. Yangtze River Delta manufacturing hubs anchor production of Bluetooth Low Energy mesh network components for underground coverage extension.
Australia
Mining operators deploy personal GPS trackers at scale for fall detection and confined-space monitoring in remote extraction sites. The country's national safety regulator enforces duty-of-care documentation requirements that compress vendor sales cycles toward bundled hardware-platform contracts. Western Australia's Pilbara iron ore region drives demand for satellite-backup cellular wearables where terrestrial networks fail.
India
Construction safety enforcement gaps leave 48 million informal workers without mandated protection, presenting volume potential if BIS certification timelines compress. The country's national standards body regulates safety hardware imports through mandatory testing protocols. Maharashtra and Gujarat industrial corridors concentrate early procurement of lone-worker devices among formal-sector manufacturing employers.
Smart Personal Safety and Security Device Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the smart personal safety device market, creating tiered competitive dynamics. The vendor base spans diversified electronics conglomerates, specialized access-control heritage firms, and ruggedized outdoor equipment specialists. Three strategic archetypes dominate: ecosystem-anchored consumer electronics brands, industrial safety heritage players, and GPS-specialized outdoor equipment manufacturers. Competitive moves concentrate on integrated facilities-management contract consolidation and cloud-based incident-management platform bundling.
Among heritage access-control specialists, ASSA ABLOY AB exemplifies the commercial building integration archetype. Samsung Electronics Co., Ltd. and Garmin Ltd. represent contrasting positioning vectors—ecosystem-anchored cellular wearables versus ruggedized outdoor GPS specialization. These three companies occupy positions that illustrate the market's structural segmentation between consumer-electronics scale economies and industrial-application reliability requirements.
| Leading Market Players |
|---|
| ASSA ABLOY AB |
| ADT Inc. |
| Apple, Inc. |
| Fitbit |
| Arlo Technologies, Inc. |
| Samsung Electronics Co., Ltd. |
| Garmin Ltd. |
| Buddi Limited |
| Honeywell International Inc. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up access-control specialists now dominate commercial building integration, concentrating procurement leverage among three German industrial distributors and compressing hardware margins through volume-based annual rebate structures. Their ownership structure enforces quarterly EBITDA targets that accelerate cost pass-through negotiations with South Korean battery suppliers and Taiwanese RF module vendors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FCC-certified cellular wearables with E-911 compliance from Bluetooth mesh devices and unlicensed RF pendants. Price differentiation rests on certification grade and after-sales platform bundling, with enterprise buyers absorbing premium tiers for auditable duty-of-care documentation. Cost compression in economy-tier GPS trackers is intensifying because GNSS module suppliers face multi-constellation receiver shortages. Security firms exhibit highest price sensitivity, while corporate risk-compliance officers prioritize reliability over unit cost.
Supply Chain Analysis
Reverse-logistics flows for ruggedized wearables concentrate refurbishment operations in Shenzhen and Penang, where IP67+ enclosure reconditioning extends product lifecycles for Australian mining operators. Component sourcing draws from South Korea for cylindrical lithium-ion cells, Taiwan for multi-constellation GNSS receivers, and Yangtze River Delta facilities for Bluetooth Low Energy mesh chipsets. Single-source vulnerability in South Korean battery cell concentration threatens supply continuity for European lone-worker mandates. Distribution runs through integrated facilities-management contractors in Germany and security service resellers in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: India's 48 million informal construction workers face negligible regulatory protection versus Germany's mandatory lone-worker equipment mandates, creating volume-cost advantages for BIS-certified suppliers.
For Market Incumbents: Extend cloud-based incident-management platform bundling to displace hardware-only channel intermediaries, while deepening backward integration into sub-1 GHz RF module design to offset FCC Part 15 certification bottlenecks. ASSA ABLOY's access-control heritage provides defensive moats against Samsung's ecosystem-anchored cellular wearables. For New Entrants and Emerging Players: Small-to-mid construction contractors in Maharashtra and Gujarat represent the most penetrable buyer archetype, lacking mandated protection but exposed to formal-sector safety audits. Target this segment with Bluetooth mesh devices priced below cellular alternatives, leveraging Yangtze River Delta component sourcing and local BIS certification partnerships. For Investors and Strategic Acquirers: Valuations sit cheapest among ruggedized GPS specialists with Australian mining deployment track records and proprietary multi-sensor fusion firmware. Long-term viability hinges on EU AI Act compliance infrastructure and CSRD carbon disclosure alignment. Monitor FCC Part 15 approval timeline extensions as early signals of working capital stress across module-dependent vendors.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Infrastructure | Third-party conformity assessment for biometric-enabled devices becomes mandatory for German industrial sales. |
| CSRD Carbon Disclosure Alignment | Embedded lifecycle carbon tracking differentiates vendors for European corporate Scope 3 reporting obligations. |
| Ultra-wideband Indoor Positioning Convergence | UWB anchor network repurposing enables centimeter-accurate worker location in warehousing and logistics. |
| Bluetooth Low Energy 5.3 Mesh Expansion | Sub-1 GHz networks extend coverage into underground mining and remote construction sites where cellular fails. |
| Edge AI Inference Migration | Real-time anomaly detection without cloud dependency compresses emergency response latency for lone-worker applications. |
Research Approach
Multiple input streams — primary interviews with risk-compliance officers, embedded firmware engineers, and security firm procurement leads; secondary validation through FCC equipment authorization databases, EU AI Act implementation guidance, and customs records for RF module imports — were reconciled against bottom-up vendor shipment estimates and top-down industrial safety equipment expenditure analysis.
Data-stream reconciliation applied across the analysis window modeled segmentation by connectivity architecture, end-user procurement authority, and feature bundling intensity, with CAGRs derived from trend extrapolation of regulatory mandate adoption curves and cellular infrastructure buildout schedules. Forecast inputs incorporated EU Green Deal procurement pivot timelines and BIS certification compression scenarios for Indian market entry.
Underlying measurement precision varies by segment; cellular-enabled wearables with established FCC and CE certification pathways carry tighter precision than emerging UWB positioning applications. Forecasts reflect assumptions around lone-worker mandate enforcement intensity and GNSS module supply continuity. Practitioners should monitor EU AI Act third-party assessment queue lengths and South Korean battery cell allocation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Child Safety Seat Market
Personal Safety
Pepper Sprays Market
Personal Safety
Global Self Defense Products Market
Personal Safety
Global Personal Emergency Response Systems (PERS) Market
Personal Safety
Life Jacket Market
Personal Safety
Personal Safety Alarms Market
Personal Safety
Night Vision Goggles Market
Personal Safety
Smart Home Safety Market
Personal Safety
Fall Detection System Market
Personal Safety
Child Leash Market
Personal Safety
China Travel Safety Kits Market
Personal Safety
Global Medical Alert System/Personal Emergency Response System Market
Personal Safety
Pedestrian Protection Airbag Market
Personal Safety
Concealable Vest Market
Personal Safety
Personal Safety Apps for Women Market
Personal Safety
Road Safety Market