
 Life Jacket Market | 2026-2036
Life Jacket Market Size, Share, and Industry Trends Forecast 2026-2036
Life Jacket Market Outlook
Asian foam and fabric producers is shifting toward higher-buoyancy material output to serve Western brand orders. Survitec Group Ltd. leverages its maritime safety heritage across commercial and defense channels. Mustang Survival anchors its position through cold-water immersion technology developed for professional rescue applications. VIKING LIFE SAVING EQUIPMENT AS dominates European commercial fleet contracts with type-approved offshore solutions.
A life jacket is a personal flotation device engineered with closed-cell foam, inflatable chambers, or hybrid constructions to provide buoyancy and prevent drowning in aquatic environments. Manufacturing involves heat-sealed nylon shells, polyethylene foam layering, or CO2-triggered inflation mechanisms tested to specific Newton ratings. The inflatable product type captures premium positioning among yacht owners and professional mariners seeking minimal bulk. Neoprene and nylon material grades split the market between cost-driven mass retail and performance-oriented water sports channels. Coast Guard Approved and CE certification tiers create distinct margin pools, with regulatory-grade products commanding higher price realization than recreational equivalents.
The U.S. Coast Guard, ISO technical committees, and EU CE marking authorities enforce buoyancy standards, testing protocols, and labeling requirements that determine market access across jurisdictions. Non-compliance blocks distribution channels and exposes manufacturers to liability exposure in personal injury litigation. Stakeholders must monitor evolving harmonization between regional certification regimes to optimize product development spend and avoid redundant testing costs.
Market Dynamics
The U.S. Coast Guard's updated flotation device standards are tightening certification requirements, forcing manufacturers to redesign buoyancy systems and consolidate testing protocols across multiple approval tiers.
Growth Catalysts
- Coast Guard Approved certification tiers:Regulatory-grade products command higher price realization than recreational equivalents, pulling investment toward compliant manufacturing capacity.
- Recreational boaters:Leisure marine activity expansion in coastal U.S. states with high boating participation rates generates sustained replacement demand for inflatable and hybrid constructions.
- Closed-cell foam layering:Heat-sealed nylon shells paired with polyethylene foam layering enable lighter-weight designs that satisfy professional mariner requirements for minimal bulk.
Market Restraints
- CO2 cartridge supply concentration:Inflation mechanism components face sourcing risk from limited specialty chemical suppliers in East Asian manufacturing clusters.
- Neoprene input cost volatility:Petroleum-derived synthetic rubber pricing fluctuates with crude oil markets, compressing margins for cost-driven mass retail channels.
- CE marking harmonization delays:Divergent testing protocols between EU authorities and ISO technical committees create redundant certification expenses for cross-border distribution.
Strategic Opportunities
- Cold-water immersion technology:Professional rescue applications developed for Arctic and North Atlantic conditions offer technology transfer potential into yacht owner premium segments.
- Direct-to-marina distribution:Bypassing traditional retail channels through harbor-based outfitters captures high-margin replacement sales from captive boating populations.
- Inflatable-hybrid convergence:Combining CO2-triggered inflation with fixed foam backup addresses liability concerns while reducing wearable bulk for extended voyages.
Industry Challenges
- Newton rating calibration expertise:Specialized buoyancy testing engineers are scarce relative to expanding certification demand across multiple jurisdiction standards.
- Heat-sealed seam durability validation:Accelerated lifecycle testing for nylon shell integrity requires extended capex commitments to environmental simulation equipment.
- Multi-jurisdiction labeling complexity:Simultaneous compliance with Coast Guard, ISO, and CE marking authorities demands dedicated regulatory affairs staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Life Jacket Market |
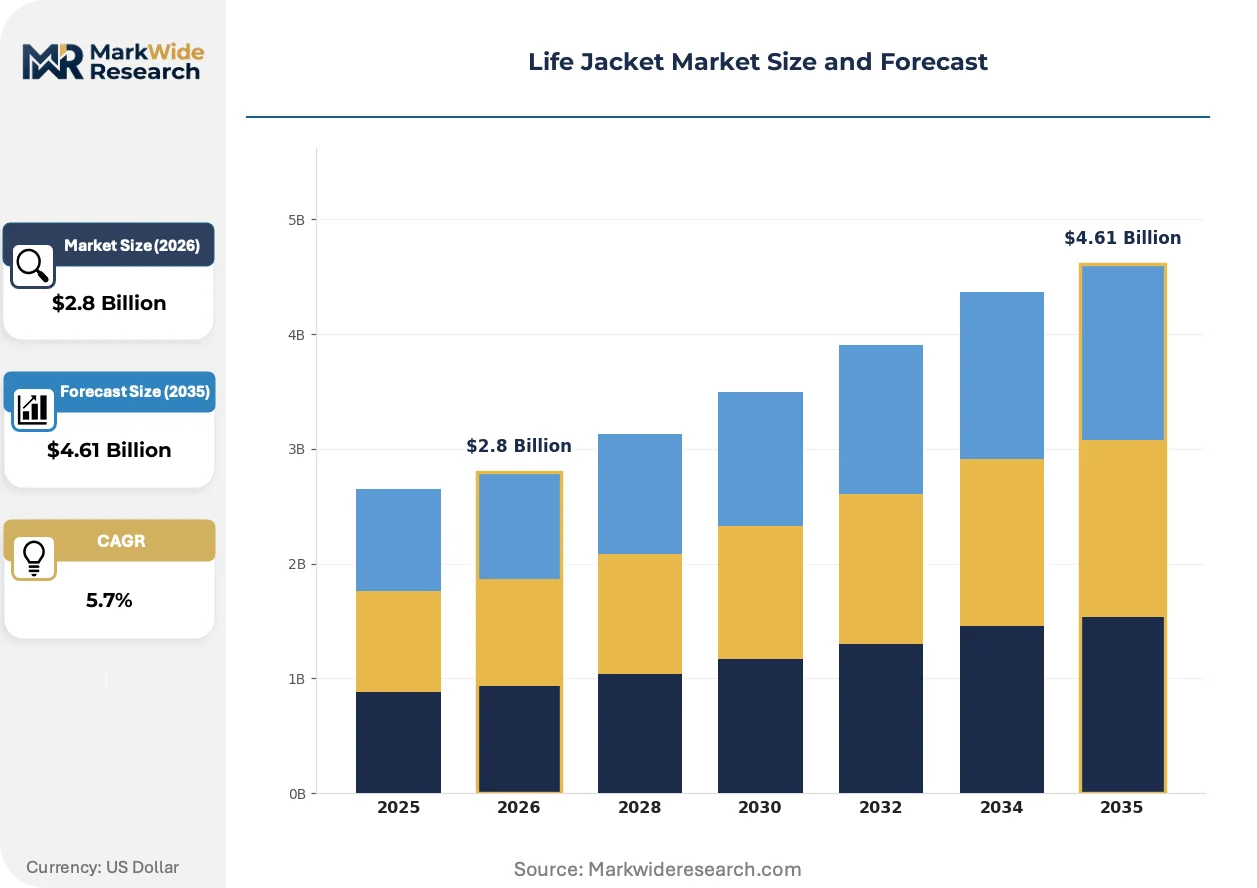
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inshore, Offshore, Inflatable, Hybrid End User: Recreational Boaters, Commercial Fishermen, Emergency Services, Water Sports Enthusiasts Material: Nylon, Polyethylene, Neoprene, Vinyl Certification: ISO, UL, CE, Coast Guard Approved |
| Companies Covered | Survitec Group Ltd., Mustang Survival, Absolute Outdoor Inc., KENT Safety Products, NRS (Northwest River Supplies), Johnson Outdoors Inc., VIKING LIFE SAVING EQUIPMENT AS, Spinlock Ltd., Newell Brands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Life Jacket Market Strategic Shifts
Material science advances and regulatory harmonization pressures are compressing product development cycles while opening premium positioning for integrated safety systems.
Smart sensor integration is converging with traditional flotation architecture. Yacht owners and commercial fleet operators are adopting GPS-enabled man-overboard detection at accelerating rates. This convergence is compressing the addressable market for basic non-connected devices while expanding service revenue pools for integrated maritime safety platforms.
EU CE marking authorities are tightening type-approval documentation for offshore solutions. Manufacturers must now submit extended traceability records for polyethylene foam sourcing and CO2 cartridge lot validation. European commercial fleet contracts are absorbing these compliance costs through multi-year procurement agreements that lock in approved supplier relationships.
Marina-based outfitters are displacing big-box retail as the preferred channel for professional-grade replacements. Coastal U.S. states with high boating density show the most pronounced shift, where harbor staff provide fit consultation and on-water testing that remote e-commerce cannot replicate. This channel rotation favors brands with dedicated maritime distribution infrastructure over mass-market entrants.
Life Jacket Market Segmentation
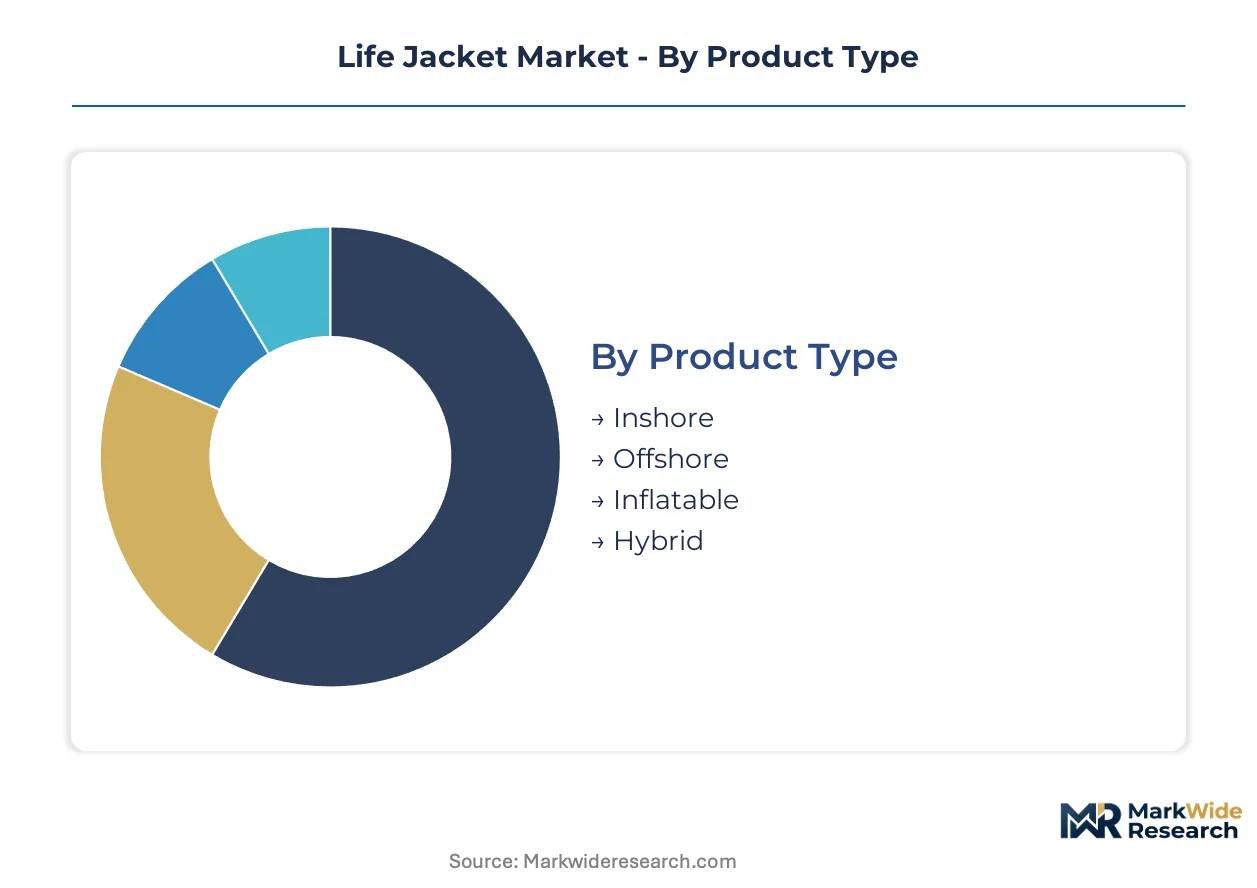
Life jacket procurement patterns split sharply between mass retail channels serving weekend boaters and specialized distributors outfitting commercial fleets. Certification tiers create distinct margin pools that reshape competitive positioning across each segment boundary. Material selection and inflation technology choices cascade through pricing, replacement cycles, and regulatory compliance requirements.
Product Type:
Volume concentrates in basic foam constructions for rental fleets and mass retail, while premium positioning belongs to inflatable and hybrid systems minimizing wearable bulk.
- Offshore:Engineered with high-visibility shells and 275N+ buoyancy ratings for severe sea states. Demand clusters around North Sea commercial fleets and Alaska crab operations where cold-water immersion survival dictates specification. Regulatory-grade testing costs limit supplier participation to established maritime safety specialists.
- Inflatable:CO2-triggered chambers deploy automatically upon water contact, reducing wearer fatigue during extended voyages. Yacht owners in Florida and California marinas drive replacement demand for slim-profile designs that preserve mobility. Coast Guard Approved certification tiers command substantial price premiums over recreational equivalents.
- Inshore:Fixed-foam constructions rated for protected waters dominate rental inventory and entry-level retail. Cost-driven procurement by harbor concessionaires favors polyethylene foam layering in heat-sealed nylon shells.
- Hybrid:Combines fixed foam backup with inflatable primary chambers, addressing liability concerns while reducing bulk. Professional rescue applications in the Pacific Northwest and New England favor this architecture for cold-water operations.
Mature deployment sits with Inshore products in rental and instructional fleets. Newer deployment is concentrated in Hybrid systems gaining share fastest among professional mariners.
End User:
Customer type determines channel access, certification requirements, and replacement cadence more than any other segmentation dimension.
- Commercial Fishermen:Mandatory carriage requirements under Coast Guard regulations create steady replacement demand. Alaska, Louisiana, and Massachusetts fleets absorb type-approved offshore solutions through cooperative purchasing agreements. Durability specifications exceed recreational standards by substantial margins.
- Emergency Services:Professional rescue teams demand cold-water immersion technology with integrated tethering points and strobe compatibility. Municipal fire departments in coastal U.S. states issue multi-year procurement tenders locking in approved supplier relationships.
- Recreational Boaters:Leisure marine activity expansion in coastal U.S. states generates sustained demand for inflatable and hybrid constructions. Harbor-based outfitters displace big-box retail as the preferred channel for professional-grade replacements.
- Water Sports Enthusiasts:Wakeboarders and kite surfers favor neoprene-integrated designs combining flotation with thermal protection. Specialty retailers in Florida and California serve this segment through fit consultation and on-water testing.
Procurement centralization dominates Commercial Fishermen and Emergency Services through multi-year agreements. Fragmented purchasing across Recreational Boaters and Water Sports Enthusiasts sustains diverse brand competition.
Material:
Input cost volatility and performance specifications split sourcing between petroleum-derived synthetics and specialized polymer grades.
- Neoprene:Petroleum-derived synthetic rubber provides thermal insulation for cold-water immersion applications. Pricing fluctuates with crude oil markets, compressing margins for cost-driven mass retail channels serving water sports participants.
- Polyethylene:Closed-cell foam layering enables lighter-weight designs satisfying professional mariner requirements for minimal bulk. Asian foam producers are shifting toward higher-buoyancy material output to serve Western brand orders.
- Nylon:Heat-sealed shells form the protective barrier across inflatable and fixed-foam constructions alike. Accelerated lifecycle testing for seam durability requires extended capital commitments to environmental simulation equipment.
- Vinyl:Cost-effective outer layer for rental fleet inventory and instructional programs where abrasion resistance outweighs weight considerations. Harbor concessionaires in high-turnover markets favor vinyl for ease of sanitization between users.
Established supply relationships anchor Polyethylene and Nylon procurement for major manufacturers. Vinyl sourcing is expanding most quickly among rental fleet operators prioritizing unit economics over performance specifications.
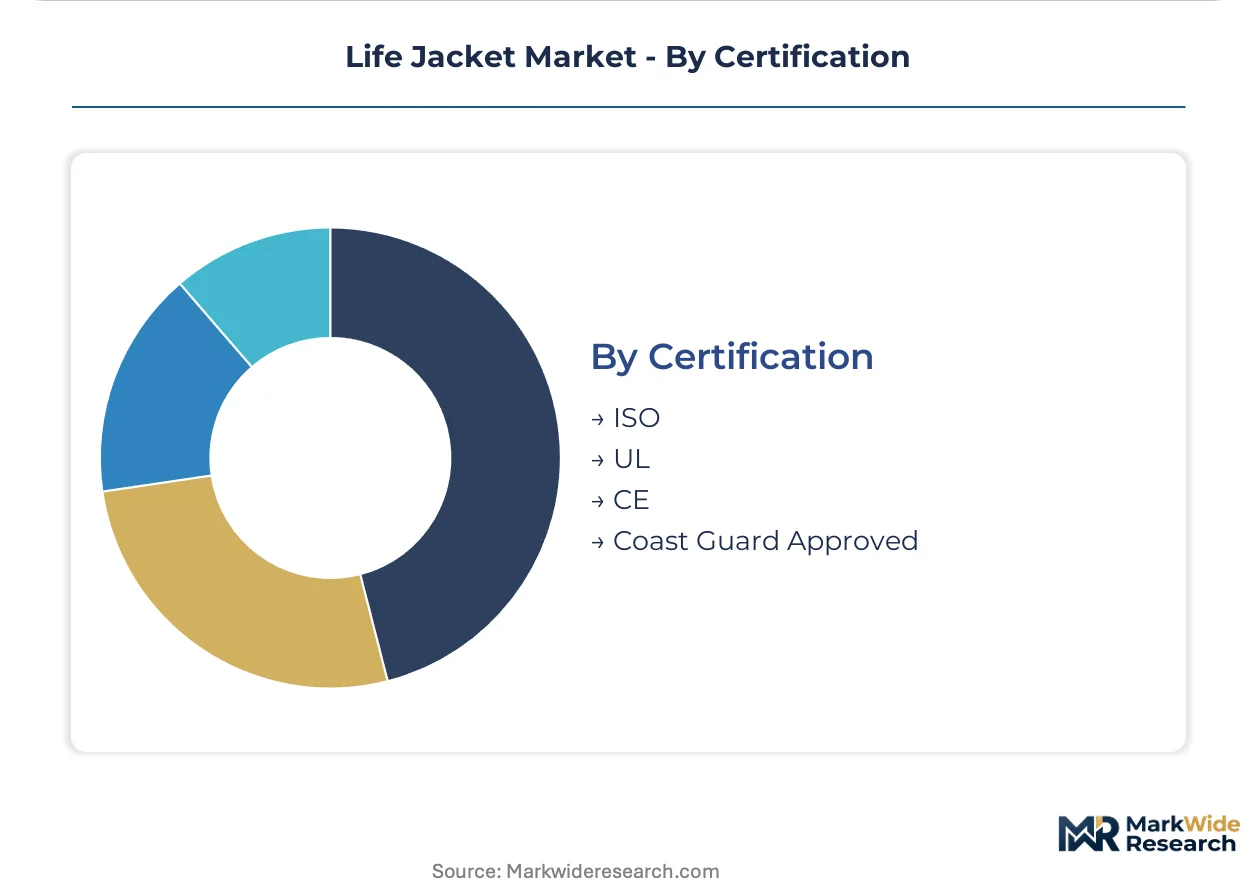
Certification:
Approval tiers create distinct market access barriers and margin structures that reshape competitive positioning across distribution channels.
- Coast Guard Approved:U.S. enforcement of updated flotation device standards tightens certification requirements, forcing manufacturers to redesign buoyancy systems. Regulatory-grade products command higher price realization than recreational equivalents in commercial fleet procurement.
- CE:EU marking authorities enforce type-approval documentation for offshore solutions, demanding extended traceability records for foam sourcing and CO2 cartridge validation. European commercial fleet contracts absorb these compliance costs through multi-year procurement agreements.
- ISO:Technical committee standards provide harmonization reference points for manufacturers seeking multi-jurisdiction distribution. Divergent testing protocols between EU authorities and ISO committees create redundant certification expenses.
- UL:Electrical safety certification applies to integrated GPS-enabled man-overboard detection systems converging with traditional flotation architecture. Yacht owners and commercial fleet operators are adopting smart sensor integration at accelerating rates.
Coast Guard Approved and CE marking dominate commercial fleet procurement with locked-in supplier relationships. ISO and UL certifications are climbing fastest as manufacturers pursue cross-border distribution and smart sensor integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Closed-cell foam and nylon fabric production clusters in East Asia supply Western brand orders, while certification requirements concentrate demand in coastal jurisdictions with active maritime enforcement.
United States
Recreational boaters in Florida and California marinas drive replacement demand for inflatable constructions. The U.S. Coast Guard's updated flotation device standards tighten certification requirements for buoyancy systems. Harbor-based outfitters in coastal states displace big-box retail as the preferred channel for professional-grade replacements.
United Kingdom
North Sea commercial fleets and professional rescue services absorb type-approved offshore solutions. CE marking authorities enforce extended traceability documentation for foam sourcing and CO2 cartridge validation. Southampton and Plymouth maritime clusters anchor distribution infrastructure for North Atlantic operations.
Germany
Baltic Sea commercial shipping and inland waterway operators generate steady procurement of regulatory-grade equipment. The country's national maritime safety regulator aligns type-approval protocols with EU harmonization frameworks. Hamburg and Bremen port complexes concentrate supplier relationships for European fleet contracts.
China
Domestic leisure marine activity expansion and Western brand contract manufacturing reshape production priorities. GB standards and MIIT oversight govern product safety for domestic distribution and export certification. Guangdong and Zhejiang manufacturing clusters shift toward higher-buoyancy material output to serve international orders.
Canada
Arctic and Pacific Northwest commercial fishing fleets mandate cold-water immersion technology with enhanced survival specifications. Health Canada and Transport Canada enforce carriage requirements under harmonized North American protocols. Vancouver and Halifax maritime centers anchor procurement networks for harsh-environment operations.
Life Jacket Market Competitive Environment
Global majors compete with regional champions across certification tiers and distribution channel access. The supplier base consolidates around maritime safety heritage, cold-water technology specialization, and commercial fleet procurement relationships. Three archetypes dominate: integrated safety conglomerates with defense and commercial portfolios, specialist manufacturers focused on professional rescue applications, and diversified outdoor recreation brands leveraging retail scale. Competitive moves center on multi-year fleet procurement agreements and direct-to-marina distribution bypassing traditional retail.
Within the integrated safety tier, Survitec Group Ltd. and VIKING LIFE SAVING EQUIPMENT AS occupy positions spanning commercial and defense channels. Mustang Survival exemplifies the specialist archetype, anchoring its market presence through professional rescue applications. These three entities represent the concentration of regulatory-grade certification expertise and maritime distribution infrastructure.
| Leading Market Players |
|---|
| Survitec Group Ltd. |
| Mustang Survival |
| Absolute Outdoor Inc. |
| KENT Safety Products |
| NRS (Northwest River Supplies) |
| Johnson Outdoors Inc. |
| VIKING LIFE SAVING EQUIPMENT AS |
| Spinlock Ltd. |
| Newell Brands Inc. |
| Others |
Value Chain & Pricing Dynamics
Specialized buoyancy testing engineers concentrated in coastal U.S. states and North Sea maritime clusters command wage premiums that cascade through three-tier pricing structure across premium, standard, and economy levels. Labor-cost differentials between certified testing facilities and general manufacturing widen spreads between Coast Guard Approved and recreational-grade products.
Pricing Analysis
Service-bundling separates warranty-backed commercial fleet contracts from unbundled retail purchases. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales support depth. Pricing pressure stems from neoprene input cost volatility compressing margins for mass retail channels. Weekend boaters exhibit highest price sensitivity; commercial fishermen under mandatory carriage requirements show lowest.
Supply Chain Analysis
Workforce availability constraints in Guangdong and Zhejiang manufacturing clusters limit expansion of heat-sealed nylon shell production. Supply concentrates in China, Vietnam, and South Korea for polyethylene foam and CO2 cartridge components. Raw material dependencies rest on petroleum-derived synthetics, specialty chemical inflation triggers, and high-visibility fabric treatments. Single-source vulnerability around East Asian CO2 cartridge suppliers threatens inflatable product lines. Distribution runs through harbor-based outfitters displacing traditional retail in coastal U.S. states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The U.S. Coast Guard's updated flotation device standards erect a cost-of-compliance barrier that favors incumbents with existing certification infrastructure and locks out undercapitalized entrants.
For Market Incumbents:Hedge against neoprene cost volatility through backward integration into closed-cell foam production or long-term polyethylene supply agreements. Defensive consolidation of Newton rating calibration expertise in coastal testing clusters protects against specialist engineer scarcity. Channel control through direct-to-marina distribution agreements locks in replacement demand from captive boating populations.
For New Entrants and Emerging Players:Direct-to-consumer digital routes bypass incumbent maritime distribution infrastructure for water sports enthusiast segments. White-space targets include neoprene-integrated designs for wakeboarders and kite surfers in Florida and California specialty retail. Most penetrable segment: recreational boaters seeking slim-profile inflatable alternatives through harbor-based outfitters lacking brand exclusivity.
For Investors and Strategic Acquirers:Re-rating potential sits with cold-water immersion technology specialists given Arctic and North Atlantic fleet procurement acceleration. Long-term viability favors manufacturers with locked-in European commercial fleet contracts absorbing CE marking compliance costs. Acquisition target archetype: professional rescue application developers with transferable yacht owner premium segment technology. Signal to watch: multi-year municipal fire department tender awards indicating procurement centralization momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Fleet Procurement Agreement | Locks in approved supplier relationships with Alaska and Louisiana commercial fishing cooperatives. |
| Cold-Water Technology Transfer | Professional rescue applications migrate into yacht owner premium segments. |
| Direct-to-Marina Distribution Buildout | Harbor-based outfitters in Florida and California capture high-margin replacement sales. |
| Backward Integration into Foam Production | In-house polyethylene sourcing insulates margins from Asian supplier pricing volatility. |
| Smart Sensor Platform Integration | GPS-enabled man-overboard detection converges with Coast Guard Approved inflatable architectures. |
Study Parameters
Independent corroboration across maritime safety product managers, Coast Guard regulatory affairs officers, and harbor outfitter procurement leads underwrites the qualitative findings. Secondary validation draws from U.S. Coast Guard carriage requirement databases, CE marking authority type-approval records, and commercial fleet cooperative purchasing agreement filings. Bottom-up demand modeling across end-user segments triangulates against top-down market sizing from trade customs data and manufacturer capacity disclosures.
Rate-of-change decomposition separates volume growth from pricing dynamics across the analysis window. Segmentation dimensions modeled include product type architecture, certification tier, material grade, and regional regulatory cluster. CAGRs derive from fitted trend extrapolation adjusted for regulatory harmonization milestones and fleet replacement cycle phasing. Industry-specific inputs incorporate Coast Guard standard revision implementation timelines and EU traceability documentation phase-in schedules.
The model holds under stable regulatory enforcement intensity and intact supply chain corridors; deviation in tariff escalation or CO2 cartridge supply disruption would shift volume and value trajectories. Forecasts reflect documented assumptions regarding certification harmonization progress and marina channel expansion rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Personal Safety Alarms Market
Personal Safety
Bulletproof Vest Market
Personal Safety
Night Vision Goggles Market
Personal Safety
Smart Home Safety Market
Personal Safety
Pedestrian Protection Airbag Market
Personal Safety
Asia-Pacific People Screening Market
Personal Safety
China Travel Safety Kits Market
Personal Safety
Smart Personal Safety and Security Device Market
Personal Safety
Fall Detection System Market
Personal Safety
Pepper Sprays Market
Personal Safety
Global Personal Emergency Response Systems (PERS) Market
Personal Safety
Personal Safety Apps for Women Market
Personal Safety
Global Medical Alert System/Personal Emergency Response System Market
Personal Safety
Body Armor and Personal Protection Market
Personal Safety
Road Safety Market
Personal Safety
Child Safety Seat Market