
 User Retention Software Market | 2026-2036
User Retention Software Market Size, Share, and Industry Trends Forecast 2026-2036
User Retention Software Market Analytics
The user retention software tier is consolidating around two distinct value propositions. Enterprise-grade platforms command premium pricing through real-time behavioral orchestration and predictive churn modeling, while stripped-down engagement utilities compete on per-seat cost. Braze leverages cross-channel automation to dominate high-complexity retail and media environments. Mixpanel sustains technology leadership in event-based analytics architecture. Klaviyo anchors its position through deep commerce integrations that tie retention directly to revenue attribution.
User retention software encompasses applications that instrument product interactions, segment audiences by behavioral signals, and trigger personalized re-engagement workflows through push notifications, email, or in-app messaging. Core functional parameters include event ingestion throughput exceeding tens of thousands of events per second, identity resolution across anonymous and authenticated states, and machine learning models that score propensity to churn within defined lookback windows. Engagement Tools capture the largest current revenue pool as brands prioritize activation over acquisition, while Analytics Platforms represent the fastest-growing segment as product-led growth methodologies demand granular funnel visibility. Cloud-Based deployment leads volume due to elastic scaling and reduced infrastructure overhead, though Hybrid configurations gain traction among financial services firms with data residency requirements.
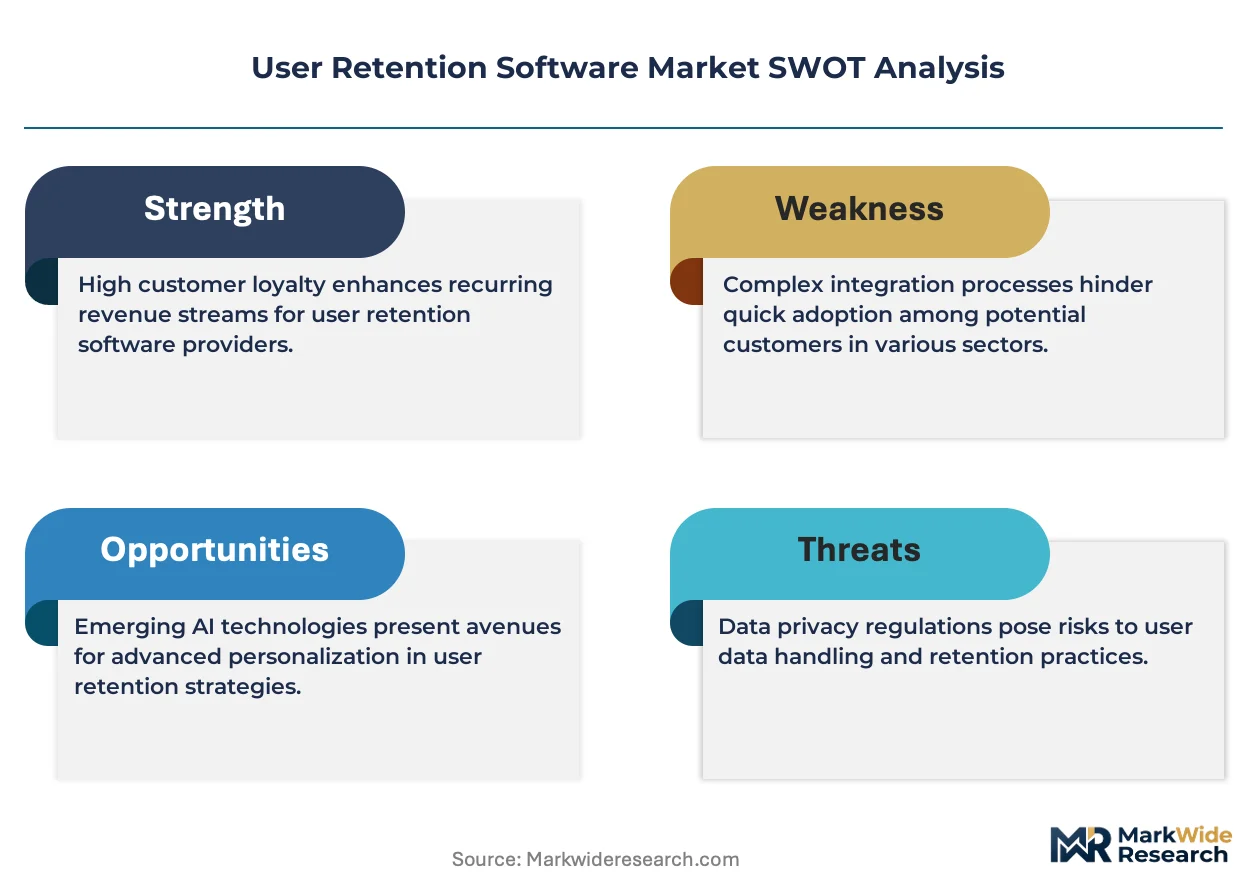
GDPR in Europe, the California Consumer Privacy Act, and sector-specific frameworks such as HIPAA for healthcare-adjacent SaaS vendors shape how retention platforms collect, store, and activate user data. These regulations force architectural investments in consent management, data minimization, and cross-border transfer mechanisms that raise barriers for smaller entrants. Stakeholders must monitor evolving enforcement patterns and decide whether to build compliant infrastructure natively or embed third-party privacy tools that consume margin but accelerate time-to-market.
Market Dynamics
Subscription SaaS providers now face customer acquisition costs that exceed lifetime value thresholds, forcing a structural pivot toward predictive churn intervention and automated lifecycle orchestration as core competitive infrastructure.
Growth Catalysts
- GDPR Consent Architecture:European privacy mandates compel vendors to rebuild analytics pipelines around first-party data collection, creating demand for compliant retention infrastructure that preserves signal fidelity while respecting user sovereignty.
- Healthcare SaaS Vertical:HIPAA-covered entities require retention platforms with audit-grade data lineage and breach notification automation, expanding addressable market into regulated clinical workflows.
- Real-Time Event Streaming:Apache Kafka and cloud-native ingestion layers enable behavioral signal processing at sub-second latency, unlocking trigger-based engagement that responds to intent rather than scheduled campaigns.
Market Restraints
- Identity Resolution Fragmentation:Cross-device graph construction requires probabilistic matching against deterministic authentication states, degrading accuracy for anonymous user cohorts and inflating data engineering overhead.
- Cloud Concentration Risk:AWS, Google Cloud, and Azure control elastic compute pricing for retention workloads, exposing margin compression when egress fees or reserved instance costs reset.
- California Privacy Friction:CCPA deletion requests force architectural investments in data minimization and retention scheduling that consume engineering resources without direct revenue attribution.
Strategic Opportunities
- India PLI Incentives:Production-linked incentive schemes for data center infrastructure reduce cloud hosting costs for retention platforms serving South Asian SaaS markets.
- Embedded Finance Convergence:Banking-as-a-service integrations enable retention tools to trigger interventions based on payment failure risk, subscription pause patterns, and credit-adjusted pricing elasticity.
- Partner-Marketplace Distribution:Salesforce AppExchange, HubSpot Ecosystem, and Shopify App Store provide pre-qualified buyer access with reduced sales cycle friction for vertical-specific retention modules.
Industry Challenges
- Machine Learning Operations Gap:Churn propensity models require continuous retraining against labeled outcome data, demanding scarce data science talent and MLOps infrastructure that mid-market vendors struggle to staff.
- Cross-Border Data Transfer Complexity:Schrems II invalidation of Privacy Shield forces retention platforms to maintain EU-isolated processing environments or adopt Standard Contractual Clauses with enhanced technical safeguards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | User Retention Software Market |
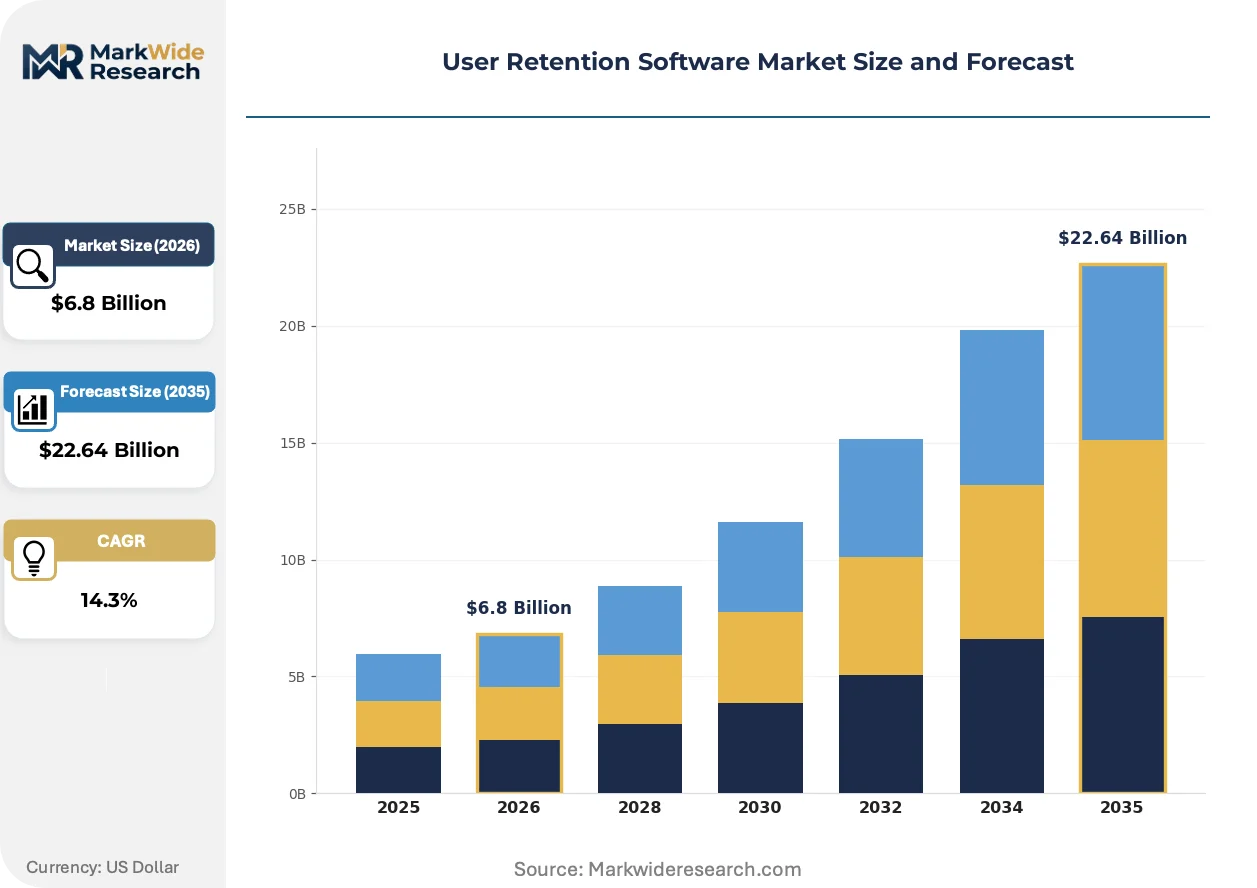
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.64 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engagement Tools, Analytics Platforms, Retargeting Solutions, Customer Feedback Systems Deployment: Cloud-Based, On-Premise, Hybrid, Software as a Service End User: E-commerce, Mobile Apps, SaaS, Gaming Integration Level: API Integrations, Out-of-the-Box Solutions, Custom Solutions, Third-Party Tools |
| Companies Covered | Mixpanel, MoEngage, Braze, ActiveCampaign, Klaviyo, Zendesk, CleverTap, Userpilot, HubSpot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
User Retention Software Market Evolving Landscape
Behavioral data infrastructure is converging with activation layers, collapsing the traditional separation between analytics warehouses and engagement execution into unified real-time systems.
Generative AI is automating message personalization at scale, synthesizing behavioral context into dynamic content variants that adapt to individual user trajectories without manual template construction. Retail and media SaaS adopters are deploying these capabilities across push, email, and in-app channels within single-digit quarter timelines. The technology is automating creative production workflows that previously required dedicated growth marketing teams, compressing headcount-per-campaign metrics by an order of magnitude.
EU AI Act risk classification rules now subject high-risk automated decision systems to conformity assessment and human oversight mandates, directly impacting retention platforms that deploy algorithmic churn scoring or dynamic pricing interventions. Vendors must maintain technical documentation, bias monitoring protocols, and audit trails that satisfy notified body scrutiny. Financial services and healthcare SaaS segments in Germany, France, and the Netherlands are front-loading compliance investments ahead of enforcement windows.
Product-led growth methodologies have inverted traditional sales-assist models, with procurement authority migrating to end-users who evaluate retention tools through self-serve trials and usage-based pricing rather than enterprise procurement cycles. Freemium tiers with transparent feature gates now function as primary demand generation channels. This pattern concentrates among Series B and C SaaS companies headquartered in San Francisco, New York, and London clusters where product operations teams hold vendor selection authority.
User Retention Software Market Segmentation
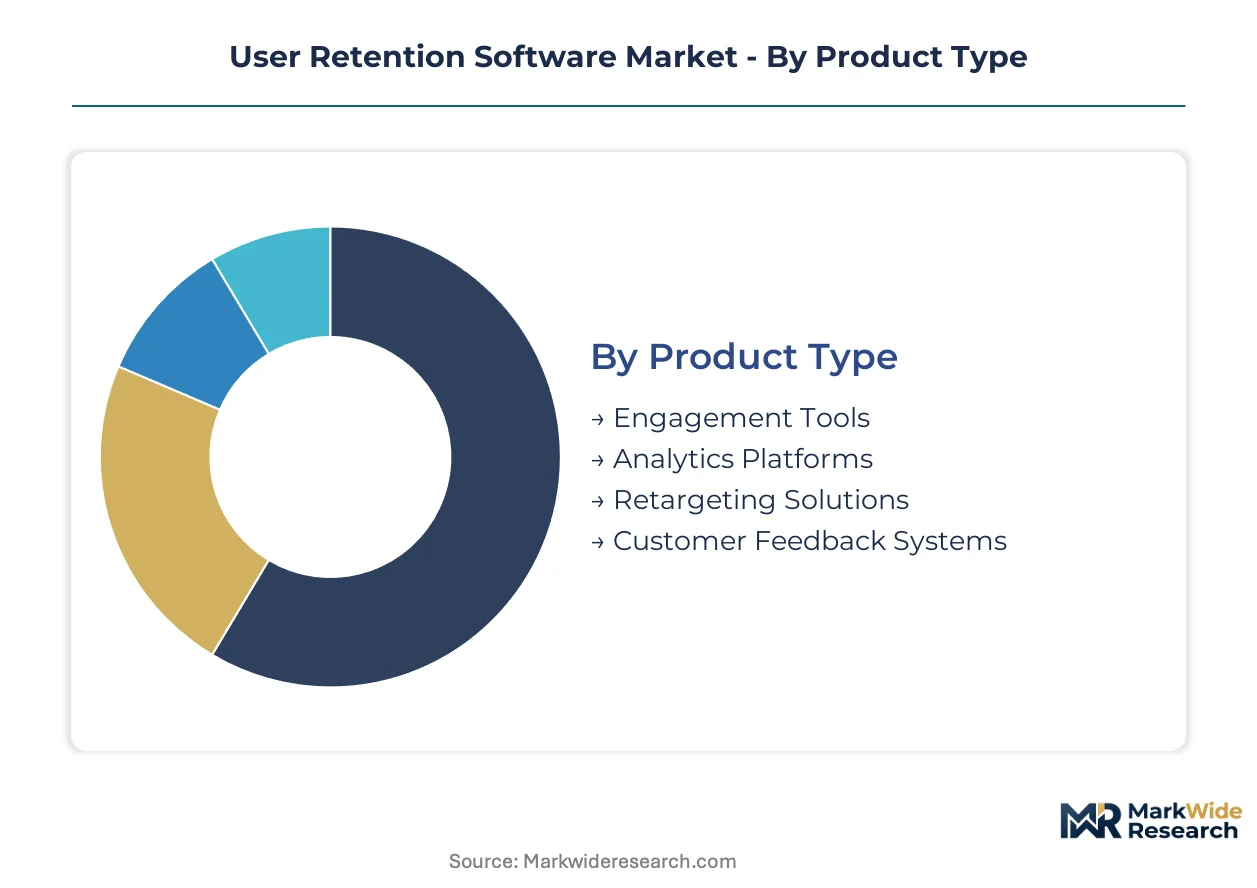
Retention software buyers diverge sharply by technical maturity and regulatory exposure. Deployment choices reflect data sovereignty requirements, while integration preferences separate developer-led organizations from marketing-centric adopters.
Product Type:
Pricing tolerance and functional depth separate buyers across this dimension.
- Engagement Tools:Orchestrate push notifications, email sequences, and in-app messaging through visual workflow builders. Demand concentrates among mid-market retailers and subscription box operators seeking activation velocity without engineering overhead. GDPR consent threading and real-time personalization engines command premium pricing tiers.
- Analytics Platforms:Ingest event streams exceeding tens of thousands of events per second, enabling funnel analysis and cohort retention curves. Product-led growth SaaS companies in San Francisco and New York clusters drive procurement, prioritizing self-serve data exploration over managed services.
- Retargeting Solutions:Sync behavioral segments to advertising platforms for off-channel re-engagement.
- Customer Feedback Systems:Capture NPS, CSAT, and qualitative signals through embedded micro-surveys.
Volume sits with Engagement Tools; growth tilts toward Analytics Platforms.
Deployment:
Data residency mandates and infrastructure control preferences shape selection patterns.
- Cloud-Based:Elastic scaling through AWS, Google Cloud, or Azure eliminates capital expenditure and accelerates time-to-value. European SaaS vendors face Schrems II compliance overhead, forcing EU-isolated processing environments or Standard Contractual Clause adoption.
- Hybrid:Sensitive behavioral data remains on-premise while activation layers leverage cloud elasticity. Financial services firms in Frankfurt and Singapore deploy this architecture to satisfy national banking regulators.
- On-Premise:Complete infrastructure control for defense contractors and classified government systems.
- Software as a Service:Fully managed multi-tenant platforms with usage-based pricing and zero maintenance burden.
Cloud-Based deployments capture current volume; Hybrid configurations climb the fastest as regulated verticals expand.
End User:
Customer lifecycle complexity and transaction frequency determine feature requirements.
- SaaS:Subscription renewal cycles and expansion revenue metrics demand predictive churn scoring and automated health scoring. Series B and C companies prioritize product analytics integration and sales-assist workflow triggers.
- E-commerce:High-velocity purchase funnels require real-time cart abandonment recovery and post-purchase replenishment timing. Shopify and BigCommerce ecosystems concentrate demand among direct-to-consumer brands.
- Mobile Apps:Push notification permission rates and in-app purchase conversion drive tooling selection.
- Gaming:Session-based engagement patterns and battle pass monetization require specialized event taxonomy.
SaaS commands current spending; E-commerce shows the steepest expansion trajectory.
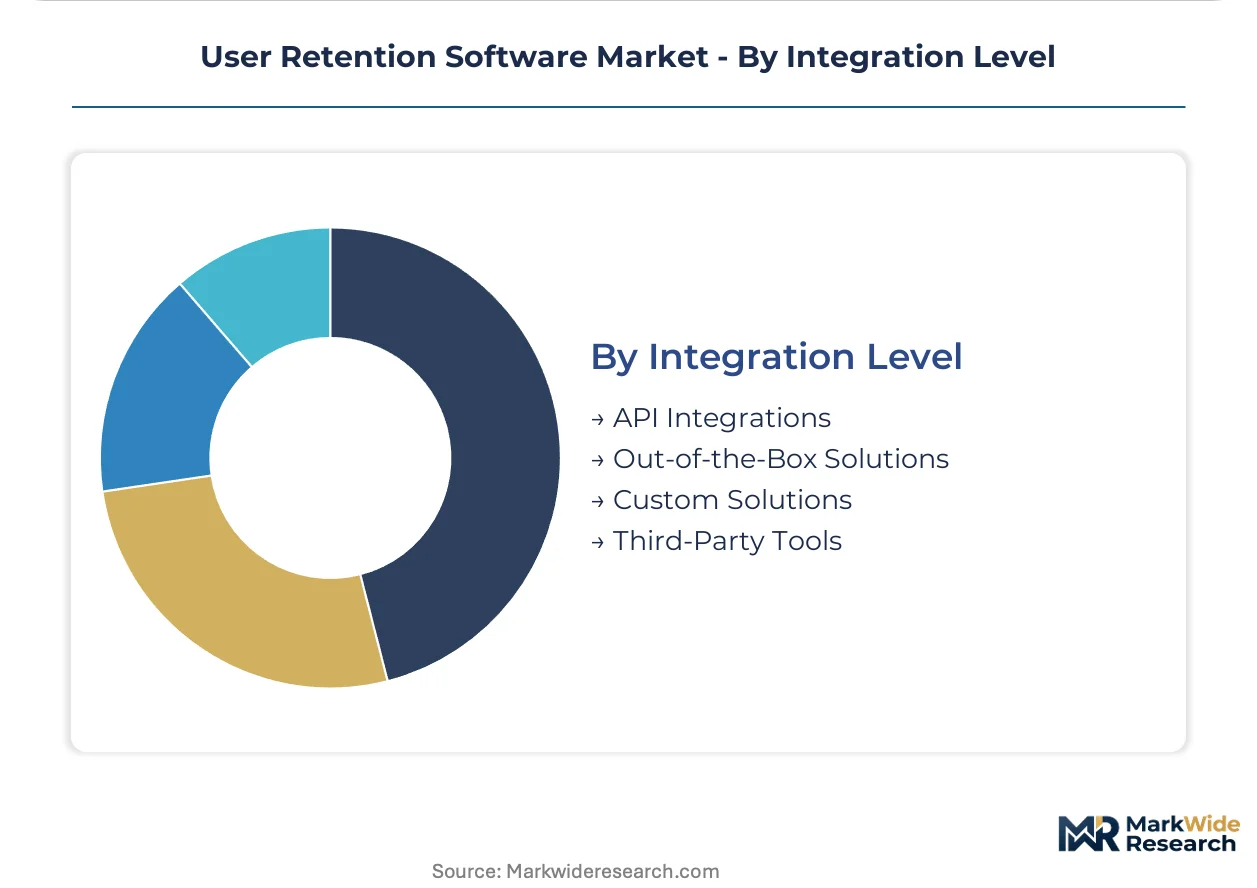
Integration Level:
Technical staffing and time-to-market pressure determine build-versus-buy calculus.
- API Integrations:REST and GraphQL endpoints enable custom data pipelines into proprietary data warehouses. Engineering-led organizations in London and Berlin clusters favor this approach for identity resolution flexibility.
- Out-of-the-Box Solutions:Pre-built connectors to Salesforce, HubSpot, and Segment reduce implementation to hours. Marketing operations teams with constrained developer access drive procurement.
- Custom Solutions:Bespoke implementations for enterprise data architectures and legacy system coexistence.
- Third-Party Tools:Embedded functionality through partner marketplaces and iPaaS platforms.
Out-of-the-Box Solutions dominate volume; API Integrations gain share fastest as data engineering teams expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors global demand for user retention software, with venture-backed SaaS clusters in the Bay Area and New York City driving procurement of predictive churn and lifecycle orchestration platforms.
United States
Enterprise software spending on lifecycle management tools outpaces other national markets, with CCPA deletion requests forcing architectural investments in data minimization. HIPAA-covered entities in Boston and Austin demand audit-grade data lineage for clinical workflow retention platforms.
Germany
Frankfurt-based financial services firms deploy hybrid architectures to satisfy national banking regulators, while EU AI Act conformity assessments reshape algorithmic churn scoring deployments. Munich and Berlin clusters concentrate product-led growth SaaS procurement authority.
United Kingdom
London's fintech density drives demand for embedded finance convergence in retention tooling, with GDPR consent threading commanding premium pricing tiers. The city's product operations teams hold vendor selection authority through self-serve trial evaluation.
India
Production-linked incentive schemes for data center infrastructure reduce cloud hosting costs for retention platforms serving South Asian SaaS markets. Bengaluru and Hyderabad clusters concentrate engineering-led organizations favoring API integration flexibility.
Japan
Tokyo's mobile app economy drives push notification permission optimization tooling, with METI guidelines shaping data residency requirements for behavioral analytics. Osaka-based retailers prioritize real-time cart abandonment recovery systems.
User Retention Software Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light orchestration designers across the user retention software tier. Enterprise-grade platforms command premium pricing through real-time behavioral processing, while stripped-down engagement utilities compete on per-seat cost. Three strategic archetypes dominate: cross-channel automation specialists, event-based analytics architects, and commerce-integrated retention engines. Competitive moves concentrate on partner-marketplace distribution and generative AI personalization capabilities.
Within the cross-channel automation tier, Braze exemplifies high-complexity retail and media positioning, while MoEngage occupies a comparable position serving emerging market mobile-first environments. Mixpanel anchors the event-based analytics architecture segment with developer-centric tooling. Klaviyo sits within the commerce-integrated archetype, tying retention directly to revenue attribution through deep platform embedding.
| Leading Market Players |
|---|
| Mixpanel |
| MoEngage |
| Braze |
| ActiveCampaign |
| Klaviyo |
| Zendesk |
| CleverTap |
| Userpilot |
| HubSpot |
| Others |
Value Network & Pricing Analysis
EU AI Act conformity assessments gate qualified supply for algorithmic churn-scoring modules, restricting premium-tier pricing access to vendors with documented bias-monitoring protocols and notified-body certifications. This regulatory filter concentrates pricing power among established platforms while elevating compliance costs as a structural barrier for mid-market entrants.
Pricing Analysis
Value-based pricing anchored to event-ingestion throughput and predictive model accuracy dominates enterprise negotiations. Three-tier pricing structure across premium, standard, and economy levels separates real-time behavioral orchestration from batch-processed engagement utilities. Cost compression in the mid-market tier intensifies because AWS and Azure egress fee resets compress margins for cloud-native vendors. Series B SaaS companies exhibit highest price sensitivity, while HIPAA-covered healthcare entities accept premium rates for audit-grade data lineage.
Supply Chain Analysis
India's PLI scheme for data center infrastructure reshapes sourcing patterns for South Asian deployment footprints. Compute hardware concentrates in Taiwan, South Korea, and the United States, while Apache Kafka streaming infrastructure and cloud-native ingestion layers draw from open-source ecosystems and hyperscaler marketplaces. Single-source vulnerability in NVIDIA GPU supply for ML training workloads threatens churn-model development timelines. Distribution runs through Salesforce AppExchange, HubSpot Ecosystem, and Shopify App Store partner marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GDPR and EU AI Act compliance architecture functions as a cost-of-compliance moat, with documentation and audit-trail investments creating sustainable barriers against undercapitalized entrants. The regulatory burden privileges incumbent platforms with dedicated privacy engineering teams.
For Market Incumbents: Anticipate margin pressure from generative AI personalization automation by consolidating MLOps talent and acquiring specialized churn-prediction startups. Defensive positioning requires EU-isolated processing environments ahead of Schrems II enforcement tightening. Vertical integration into consent-management tooling preserves pricing power against modular competitors. For New Entrants and Emerging Players: Launch via embedded finance convergence in the Shopify and BigCommerce ecosystems, where banking-as-a-service integrations remain underdeveloped. The most penetrable white space sits in HIPAA-compliant retention modules for clinical workflow SaaS, with API-first architectures targeting Boston and Austin healthtech clusters. Freemium tiers with transparent feature gates accelerate self-serve adoption velocity. For Investors and Strategic Acquirers: EU AI Act notified-body certifications for high-risk algorithmic systems is the leading indicator that regulatory moats are crystallizing around compliant platforms. Long-term viability favors asset-light orchestration designers with partner-marketplace distribution over capital-heavy infrastructure builders. Acquisition targets should display embedded finance integrations and generative AI personalization pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Notified-body approval unlocks high-risk algorithmic churn-scoring deployments in German and French financial services. |
| Generative AI Personalization Engine | Dynamic content synthesis compresses headcount-per-campaign metrics for retail and media SaaS adopters. |
| Embedded Finance Integration | Banking-as-a-service triggers enable payment-failure-risk interventions for subscription SaaS operators. |
| Partner-Markplace Distribution | Salesforce AppExchange and Shopify App Store access reduces sales-cycle friction for vertical modules. |
| Hybrid Deployment Architecture | On-premise sensitive data with cloud activation layers satisfies Frankfurt and Singapore banking regulators. |
Research Methodology
Multi-period observation of event-ingestion throughput benchmarks and churn-model deployment timelines anchored the trend analysis, supplemented by interviews with CTOs at Series B and C SaaS companies, platform engineers managing real-time streaming infrastructure, and privacy officers navigating GDPR consent architecture. Bottom-up triangulation against SEC filings from publicly traded retention vendors, hyperscaler capex disclosures from AWS and Google Cloud, and App Annie mobile engagement metrics validated primary fieldwork.
Segment-weighting across deployment model, organization size, vertical industry, and integration complexity shaped the analytical framework. CAGRs were derived from elasticity modeling of subscription SaaS customer acquisition cost trajectories and predictive churn intervention adoption curves. Apache Kafka adoption rates and generative AI personalization deployment timelines fed industry-specific forecast inputs throughout the projection horizon.
The model assumes a particular technology adoption path for real-time event streaming; alternative pathways for batch-processed behavioral analytics would alter the outlook for mid-market vendor competitiveness. Forecasts reflect assumptions regarding Schrems II enforcement patterns and EU AI Act implementation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Recruiting Software Market
Software & Services
Low Code Development Platform Market
Software & Services
Lighting Control Software Market
Software & Services
Customer Self-Service Software Market
Software & Services
Global Furniture Manufacturing Software Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
App Building Software Market
Software & Services
Enterprise Search Software Market
Software & Services
Radio Propagation Software Market
Software & Services
Electromagnetic Simulation Software Market
Software & Services
Software Testing Tools Market
Software & Services
Global Smartphone Operating System (OS) Market
Software & Services
Global Core Banking Software Market
Software & Services
Software-Defined Machine Market
Software & Services
HR Management Software (Personnel and Organization) Market
Software & Services
Relational Database Management System Market