
 Camera Tracking Software Market | 2026-2036
Camera Tracking Software Market Size, Share, and Industry Trends Forecast 2026-2036
Camera Tracking Software Market Outlook
Direct-to-studio licensing is fragmenting as cloud-based subscription models erode perpetual-license dominance across post-production houses. Autodesk sustains technology leadership through deep integration with Maya and Flame workflows. Blackmagic Design leverages hardware-software bundling to control price positioning in mid-market film and television segments. The Foundry Visionmongers specializes in node-based compositing pipelines that anchor premium VFX studio relationships.
Camera tracking software computes camera motion paths from video sequences using feature detection algorithms, optical flow vectors, and photogrammetric reconstruction to synchronize virtual elements with live-action footage. The technology operates at sub-pixel precision thresholds, typically resolving translation errors below 0.5 pixels per frame for seamless compositing. 3D tracking and virtual camera segments command the highest margin pools where real-time engine integration commands premium pricing from film production and AR/VR development end users. Cloud-based deployment is accelerating fastest among gaming industry customers who require distributed team collaboration across multiple development sites.
The Federal Communications Commission in the United States governs broadcast transmission standards that shape live event tracking requirements, while the EU AI Act imposes algorithmic transparency obligations on automated tracking systems deployed in European media markets. ISO 27001 certification has become a de facto market access requirement for cloud-based platforms serving enterprise film studios. Stakeholders must monitor evolving data residency mandates and real-time rendering standards to anticipate deployment architecture shifts.
Market Dynamics
Real-time virtual production pipelines are compressing post-production timelines and forcing camera tracking vendors to integrate directly with game engines and LED volume systems.
Growth Catalysts
- Unreal Engine integration:Film production studios in Hollywood and Bollywood demand seamless real-time compositing workflows that eliminate offline rendering bottlenecks.
- EU AI Act compliance:Algorithmic transparency mandates are accelerating on-premises deployment architectures that prioritize data sovereignty over cloud convenience.
- South Korean broadcast infrastructure:Elevated investment in K-content production facilities is creating concentrated demand for sub-pixel precision tracking systems.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in AI-accelerated rendering hardware creates input cost volatility for real-time tracking software vendors.
- GDPR data residency friction:Cross-border cloud collaboration faces structural barriers that fragment development team coordination across European and non-European studios.
- Photogrammetric reconstruction limitations:Featureless surfaces and motion blur continue to degrade tracking accuracy in low-texture environments.
Strategic Opportunities
- India post-production expansion:Underpenetrated VFX service markets in Mumbai and Hyderabad offer white space for cloud-native tracking platforms.
- NeRF-3D Gaussian Splatting convergence:Emerging neural radiance field techniques are opening volumetric capture applications beyond traditional film and television.
- FCC broadcast modernization:Live event tracking requirements under evolving transmission standards create regulatory tailwinds for real-time precision systems.
Industry Challenges
- Computer vision specialist scarcity:The talent gap in optical flow algorithm development constrains R&D velocity for mid-tier software vendors.
- ISO 27001 certification timelines:Enterprise studio procurement mandates create 12-18 month sales cycle friction for cloud platform entrants.
- Maya-Flame pipeline integration complexity:Legacy compositing workflows resist modular tracking tool insertion without extensive API customization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camera Tracking Software Market |
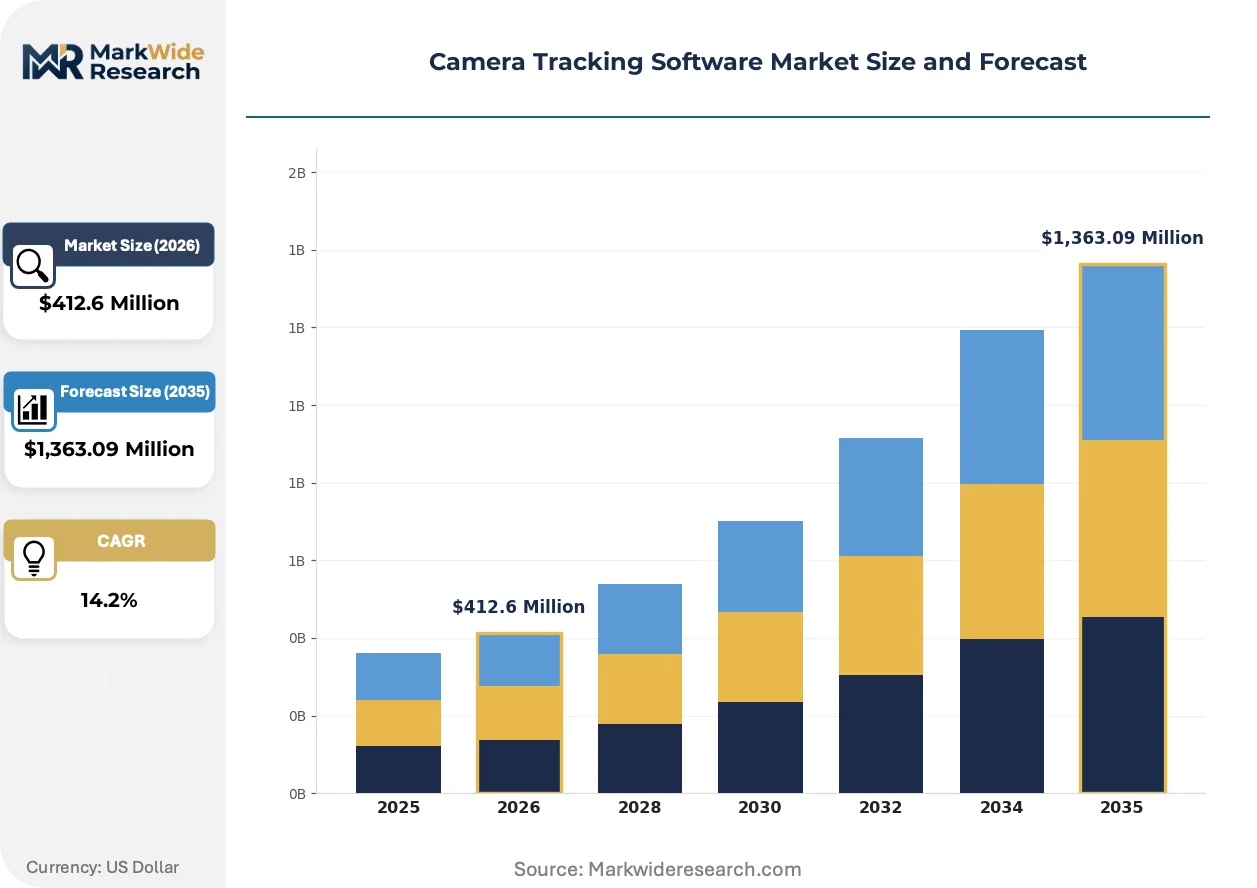
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,363.09 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Tracking, 3D Tracking, Virtual Camera, Object Tracking Technology: Optical Flow, Stereoscopic, Depth Sensing, Feature Matching End User: Film Production, Gaming Industry, AR/VR Development, Live Events Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Application |
| Companies Covered | Adobe, Autodesk, Blackmagic Design, Boris FX, Maxon Computer, MO-SYS Engineering, Ncam, The Foundry Visionmongers, Vicon Motion Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camera Tracking Software Market Strategic Shifts
Neural rendering techniques and edge-compute architectures are redrawing performance benchmarks for camera tracking accuracy and latency. These shifts are compressing the gap between acquisition and final pixel.
Markerless motion capture systems powered by deep learning feature detection are rendering obsolete traditional optical tracking rigs that require controlled studio environments and extensive calibration protocols. Independent filmmakers and mid-budget television productions are adopting these systems fastest, lured by reduced equipment rental overhead and location flexibility. The structural consequence is a compression in the addressable market for hardware-rental-dependent tracking services.
The EU AI Act's algorithmic transparency obligations are forcing automated tracking system vendors to document decision pathways for feature classification and motion prediction. This industrial consequence elevates engineering documentation costs and extends validation cycles for European market entry. VFX studios serving streaming platforms with European distribution are responding by segregating European project data onto on-premises infrastructure.
Subscription-based licensing is displacing perpetual-seat agreements across post-production houses that prioritize cash-flow flexibility over capital depreciation. The channel being disrupted is traditional value-added reseller networks that relied on upfront license commissions. This pattern is most visible in the United States and United Kingdom where cloud infrastructure investments have normalized distributed team collaboration.
Camera Tracking Software Market Segmentation
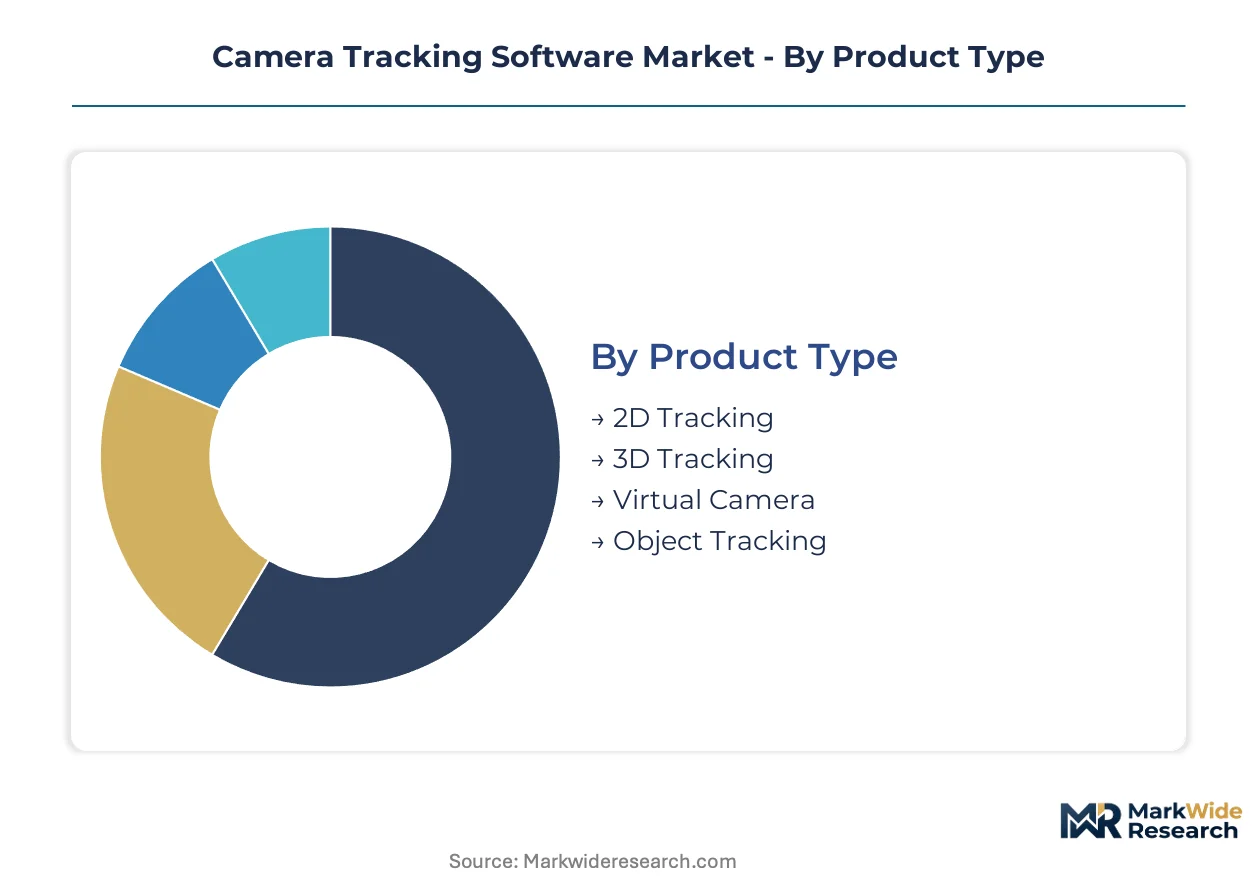
Camera tracking software vendors structure their portfolios across four intersecting dimensions. Product type and deployment architecture determine margin profiles, while technology choice and end-user vertical shape R&D investment priorities.
Product Type:
Mature compositing workflows coexist with emerging real-time engine integration, creating divergent performance requirements across the product spectrum.
- 2D Tracking:Planar tracking algorithms resolve translation, rotation, and scale parameters for screen replacement and rotoscoping tasks. Post-production houses in the United Kingdom deploy these tools for episodic television where budget constraints limit 3D pipeline investment.
- 3D Tracking:Photogrammetric reconstruction calculates camera position in volumetric space using feature triangulation across multiple frames. Hollywood film production studios command sub-pixel precision thresholds below 0.5 pixels per frame for seamless virtual set integration.
- Virtual Camera:Real-time viewport manipulation enables cinematographers to previsualize shots within game engine environments.
- Object Tracking:Rigid and deformable surface tracking isolates moving elements from camera motion for selective compositing.
2D Tracking retains volume leadership across installed seats; 3D Tracking holds the steepest expansion curve as virtual production pipelines proliferate.
Technology:
Cost tier differentiation separates premium algorithmic approaches from commodity implementations in the competitive landscape.
- Optical Flow:Dense motion vector fields interpolate pixel displacement between frames for smooth temporal tracking. Gaming industry customers in South Korea leverage GPU-accelerated optical flow for distributed team collaboration across multiple development sites.
- Stereoscopic:Disparity mapping between calibrated camera pairs enables depth extraction without active illumination. AR/VR development studios demand this technology for immersive content where spatial accuracy determines user comfort.
- Depth Sensing:Time-of-flight and structured light sensors capture metric distance data for occlusion handling.
- Feature Matching:Scale-invariant keypoint descriptors establish correspondence across viewpoint variations.
Optical Flow dominates current licensing revenue; Stereoscopic gains share fastest as headset penetration accelerates.
End User:
Application intensity varies dramatically across customer verticals, with premium pricing concentrated where real-time constraints dominate.
- Film Production:Virtual production pipelines integrate camera tracking with LED volumes and game engines for in-camera visual effects. Bollywood studios in Mumbai are expanding real-time workflows that compress traditional post-production timelines.
- Gaming Industry:Cinematics teams require cinematic camera motion for narrative sequences within interactive environments. Cloud-based deployment architectures serve distributed development teams across North American and Asian studios.
- AR/VR Development:Spatial computing applications demand six-degree-of-freedom tracking for immersive experiences.
- Live Events:Broadcast augmentation systems overlay graphics on sports and entertainment programming in real time.
Film Production commands the highest average contract values; Gaming Industry shows the most rapid subscription conversion.
Deployment:
Customer type preferences split between capital-intensive studio infrastructure and flexible operational expenditure models.
- On-Premises:Local hardware installation satisfies GDPR data residency requirements and EU AI Act algorithmic transparency mandates. European VFX studios segregate project data onto owned infrastructure to avoid cross-border compliance friction.
- Cloud-Based:Distributed rendering and collaboration tools enable remote team coordination without physical facility investment. ISO 27001 certification has become a de facto procurement requirement for enterprise film studios evaluating SaaS platforms.
- Hybrid:Sensitive processing remains local while non-critical workloads burst to cloud resources.
- Mobile Application:Tablet and smartphone-based tracking serves location scouts and independent creators.
On-Premises maintains dominance in European regulated markets; Cloud-Based climbs fastest among gaming and mid-market post-production customers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in South Korea by substantial margins, reflecting divergent studio infrastructure maturity and broadcast investment cycles across these production hubs.
United States
Hollywood studios drive premium demand for real-time virtual production pipelines integrating LED volumes with game engines. The Federal Communications Commission governs broadcast transmission standards that shape live event tracking precision requirements. Los Angeles and New York anchor the highest concentration of post-production facilities deploying sub-pixel precision systems.
United Kingdom
London post-production houses prioritize cloud-based subscription models over perpetual licensing for cash-flow flexibility. GDPR compliance mandates push developers toward hybrid deployment architectures with local data processing. Soho's VFX cluster concentrates episodic television work where budget constraints favor 2D planar tracking over full 3D pipelines.
South Korea
K-content production facilities command elevated investment in broadcast infrastructure and real-time tracking systems. The country's media regulator enforces technical standards for domestic streaming platforms that propagate to software procurement specifications. Seoul's Gangnam district hosts gaming industry customers leveraging GPU-accelerated optical flow for distributed team collaboration.
India
Bollywood studios in Mumbai and Hyderabad expand real-time workflows that compress traditional post-production timelines. The Bureau of Indian Standards certifies broadcast equipment imports that affect tracking hardware-software bundle acceptance. Mumbai's Andheri West cluster represents underpenetrated white space for cloud-native tracking platforms targeting mid-budget productions.
Germany
European VFX studios segregate project data onto on-premises infrastructure to avoid cross-border compliance friction under EU AI Act algorithmic transparency mandates. The country's federal data protection authority enforces strict interpretation of GDPR data residency requirements. Berlin's emerging media tech cluster attracts real-time engine integration specialists serving continental European film co-productions.
Camera Tracking Software Market Competitive Environment
Integrated platform vendors and specialized compositing toolmakers split the market between workflow consolidation and precision segmentation strategies. Autodesk sustains technology leadership through deep integration with established 3D and compositing pipelines. Blackmagic Design leverages hardware-software bundling to control price positioning in mid-market segments. Competitive moves concentrate on strategic partnerships with game engine developers and vertical integration into LED volume control systems.
Within the integrated platform tier, Autodesk and Adobe occupy positions exemplifying end-to-end workflow dominance, while The Foundry Visionmongers anchors the specialized compositing archetype with node-based pipeline relationships. These three entities represent divergent strategic bets on whether customers prioritize seamless tool integration or modular precision capabilities.
| Leading Market Players |
|---|
| Adobe |
| Autodesk |
| Blackmagic Design |
| Boris FX |
| Maxon Computer |
| MO-SYS Engineering |
| Ncam |
| The Foundry Visionmongers |
| Vicon Motion Systems |
| Others |
Value Chain & Pricing Dynamics
Los Angeles post-production clusters concentrate GPU-accelerated rendering capacity that feeds downstream pricing power to Autodesk and Blackmagic Design. Cloud-native entrants face margin compression against these hardware-software bundling advantages.
Pricing Analysis
The customization-premium spread separates perpetual-license configurations from standardized SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with ISO 27001 certification tier and real-time engine integration depth as primary differentiation drivers. Cost compression in mid-market segments is intensifying because Blackmagic Design's hardware bundling removes standalone software purchasing flexibility. Independent filmmakers and episodic television houses exhibit highest price sensitivity; Hollywood virtual production studios show least sensitivity where sub-pixel precision thresholds command premium positioning.
Supply Chain Analysis
Export-control regimes restricting AI-accelerated chip flows to Chinese entities fragment GPU procurement channels for tracking software vendors. Supply concentrates in Taiwan, South Korea, and the United States for advanced semiconductor fabrication. NVIDIA's CUDA ecosystem and AMD's ROCm stack serve as critical software-hardware dependencies. Single-source vulnerability around NVIDIA's AI training silicon creates procurement risk concentration. Distribution runs through direct-to-studio enterprise sales teams and cloud marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camera tracking software functions as a service-attach opportunity where subscription renewals and integration consulting expand faster than perpetual license transactions. Recurring revenue layers from real-time engine support contracts outpace hardware-dependent tracking rig rentals.
For Market Incumbents: Pre-empt NeRF-3D Gaussian Splatting convergence by acquiring volumetric capture specialists before neural rendering commoditizes traditional photogrammetry. Deepen backward integration into LED volume control systems to defend against game engine vendors expanding downstream. The EU AI Act's documentation mandates threaten margin structures; ISO 27001 certification investment locks in European studio procurement preference. For New Entrants and Emerging Players: Mid-budget Bollywood productions in Mumbai's Andheri West cluster represent the most penetrable entry point for cloud-native tracking platforms lacking legacy Maya-Flame integration. South Korean gaming cinematics teams offer secondary white space where GPU-accelerated optical flow demand exceeds local vendor capacity. A channel partnership with Unreal Engine marketplace distribution accelerates customer acquisition without direct Autodesk competitive confrontation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized node-based compositing toolmakers with entrenched VFX studio relationships over horizontal platform consolidation plays. The five-to-ten-year viability window rewards acquisition targets possessing proprietary optical flow algorithms and European on-premises deployment expertise. Watch for inflection when FCC broadcast modernization rules mandate real-time precision thresholds that obsolete legacy 2D tracking installations.| Strategic Initiative | Industry Significance |
|---|---|
| Game Engine Partnership | Unreal Engine integration secures virtual production pipeline anchoring for LED volume deployments. |
| Neural Rendering Acquisition | 3D Gaussian Splatting specialists enable volumetric capture expansion beyond traditional film applications. |
| On-Premises Certification | ISO 27001 and EU AI Act compliance unlock European enterprise studio procurement channels. |
| Hardware-Software Bundling | Camera tracking modules bundled with capture hardware defend mid-market price positioning. |
| Cloud-Native Platform Launch | SaaS architectures penetrate distributed gaming development teams across Asian production hubs. |
Study Parameters
Initial hypotheses were tested against primary input from VFX pipeline supervisors, broadcast engineering directors, game engine integration specialists, and post-production facility CTOs and refined through secondary validation against SEC filings from Autodesk and Adobe, hyperscaler capex disclosures, and FCC broadcast equipment certification databases. Bottom-up triangulation across deployment model adoption rates and top-down reconciliation against aggregate studio infrastructure spending anchored volume estimates.
Demand-supply-balance framing modeled software licensing velocity against GPU hardware availability and studio capacity expansion across the projection horizon. Segmentation dimensions included product type, deployment architecture, end-user vertical, and regional regulatory cluster. CAGRs derived from installed base growth rates and pricing trajectory assumptions, with real-time engine penetration and GDPR compliance friction as industry-specific forecast inputs.
Stress conditions across GPU supply concentration, EU AI Act enforcement intensity, and virtual production pipeline adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cloud migration velocity and broadcast infrastructure investment cycles. Material shifts in export-control regime stringency or neural rendering technology maturation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Global Subscription Billing Software Market
Software & Services
In-Memory Data Grids Software Market
Software & Services
Sports Production Software Market
Software & Services
North America Telecom Expense Management Services Software Market
Software & Services
Global Open Source Services Market
Software & Services
Asia-Pacific Digital Signage Software Market
Software & Services
Construction Suites Software Market
Software & Services
US Software Consulting Market
Software & Services
Consignment Software Market
Software & Services
Software-Defined Machine Market
Software & Services
Global Managed Application Services Market
Software & Services
Global Trade Promotion Management Software Market
Software & Services
3PL Software Market
Software & Services
Artwork Management Software Market
Software & Services
B2B Gateway Software Market