
 Global Mobile Identification Market | 2026-2036
Global Mobile Identification Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Identification Market Foresight
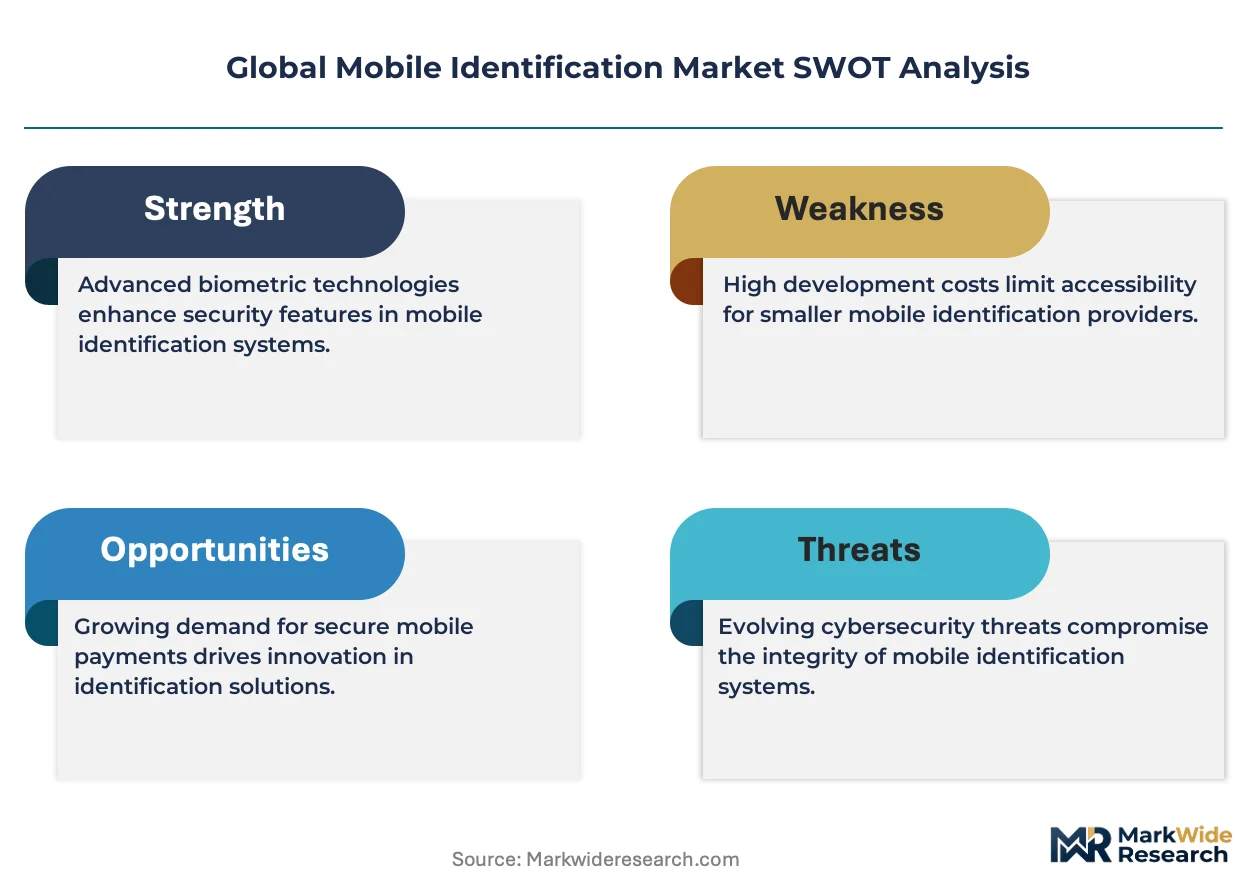
FIDO2 certification tier is bifurcating the competitive landscape as vendors race to meet phishing-resistant authentication benchmarks. Thales Group leverages its hardware security module heritage to anchor high-assurance government contracts across multiple continents. IDEMIA specializes in biometric enrollment systems that sustain its position in national identity programs. Okta, Inc. competes through cloud-native identity orchestration that extends enterprise mobile access control into consumer-facing deployments.
Mobile identification encompasses portable digital identity verification systems that bind cryptographic credentials to smartphone hardware through secure enclaves, Trusted Execution Environments, or embedded SIM modules, primarily enabling passwordless authentication and remote identity proofing for regulated transactions. Biometrics and NFC currently occupy the largest addressable segments, while QR code and voice recognition represent faster-growing niches where lower infrastructure requirements accelerate emerging market penetration. The application dimension shows contactless payments and e-governance absorbing the majority of deployment capital, with IoT device security emerging as a margin-rich frontier where hardware-rooted trust anchors command pricing premiums.
FDA guidelines on software as a medical device intersect with WHO digital health identity standards to shape product validation requirements for healthcare-adjacent mobile ID systems, while GDPR and the EU AI Act impose algorithmic transparency mandates on biometric processing across European deployments. India's BIS certification and PLI scheme for electronics manufacturing create localized compliance thresholds that influence component sourcing decisions. Stakeholders must monitor the divergence between hardware-anchored and purely software-based trust models as regulatory bodies finalize liability frameworks for credential compromise.
Market Dynamics
Phishing-resistant authentication mandates from financial regulators are compressing procurement timelines and forcing credential architecture redesigns across enterprise and government verticals simultaneously.
Growth Catalysts
- FIDO2 Mandates:Financial regulators in Singapore and Australia now require phishing-resistant authentication for high-value transactions, accelerating hardware-backed credential deployments.
- India's Digital Public Infrastructure:The Aadhaar-linked mobile ID ecosystem enables instant identity verification for 1.3 billion residents, creating template demand across emerging economies.
- Biometric Liveness Detection:Presentation attack detection algorithms now meet ISO/IEC 30107-3 standards, unlocking regulated healthcare and border control applications.
Market Restraints
- Secure Element Supply Concentration:Three East Asian foundries fabricate over 80 percent of eSE and eUICC chips, creating single-source vulnerability for credential hardware.
- GDPR Algorithmic Transparency Requirements:The EU AI Act's biometric identification classification imposes conformity assessment burdens that extend European deployment cycles.
- Legacy PKI Infrastructure Lock-in:Enterprises with sunk investments in smart card systems face high switching costs to mobile-native credential architectures.
Strategic Opportunities
- Brazil's Gov.br Expansion:The national digital identity program targets 120 million mobile credentials by 2028, creating concentrated procurement demand for biometric enrollment systems.
- IoT Device Onboarding:Connected vehicle and industrial sensor networks require hardware-rooted identity for mutual authentication, commanding premium pricing over consumer deployments.
- Privacy-Preserving Cryptography:Zero-knowledge proof implementations enable selective disclosure that satisfies GDPR data minimization while preserving verification utility.
Industry Challenges
- Embedded Systems Security Engineering Talent:Shortage of specialists combining secure enclave architecture with mobile OS integration delays product validation timelines.
- Cross-Border Certification Fragmentation:Divergent national requirements for eIDAS, BIS, and FIPS 140-3 compliance force redundant testing cycles for multi-jurisdiction deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Identification Market |
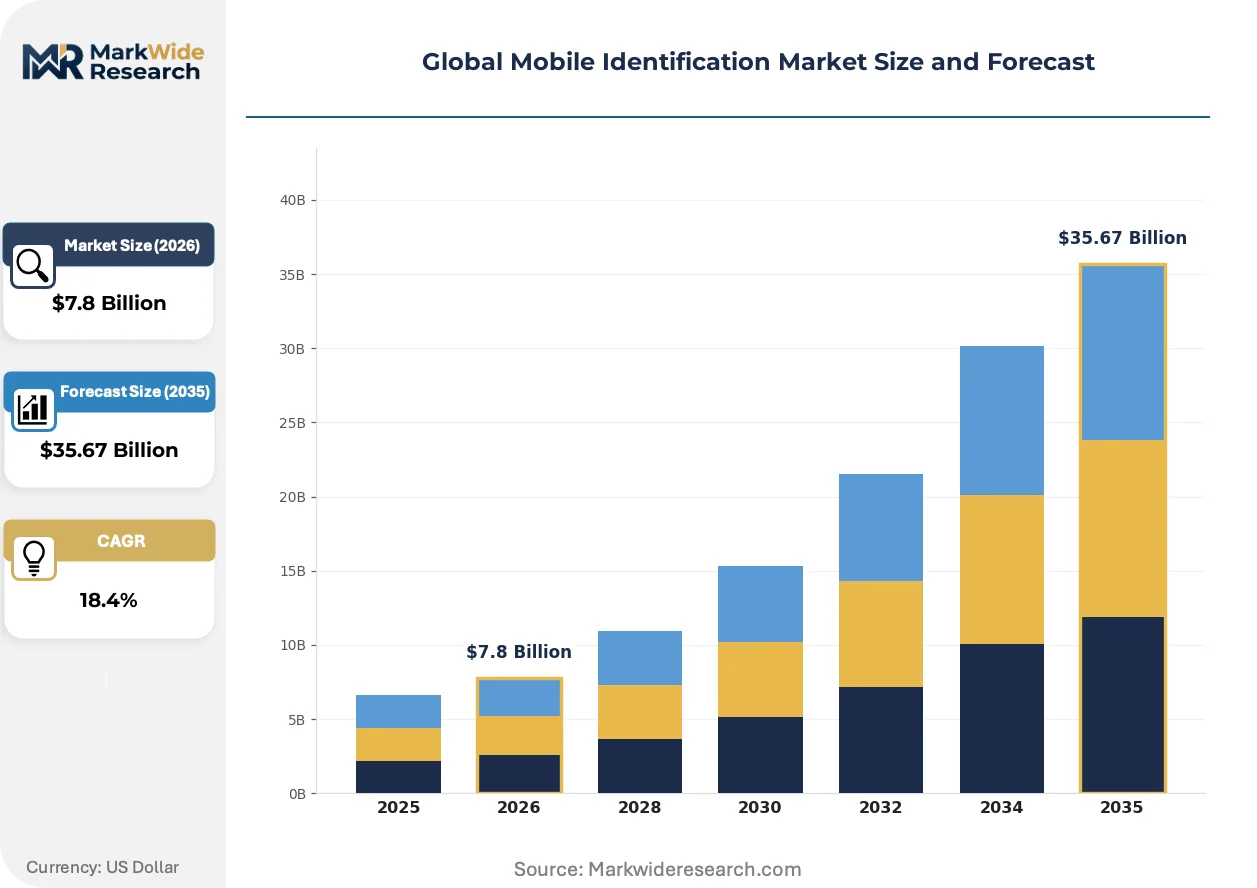
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $35.67 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biometrics, NFC, QR Code, SIM-Based Authentication, Two-Factor Authentication, Voice Recognition Application: Contactless Payments, Access Control, E-Governance, Employee Verification, Event Management, IoT Device Security End User: Banking & Financial Institutions, Telecommunications Providers, Government Agencies, Retail Chains, Transportation Operators, Educational Institutions Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Thales Group, IBM Corporation, IDEMIA, OneLogin, SecureAuth Corporation, Micro Focus, Okta, Inc., NEC Corporation, HID Global Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Identification Market Shifts & Advancements
Credential binding mechanisms are migrating from centralized server storage to device-anchored cryptographic proofs, fundamentally altering liability distribution and trust model economics.
Passkey implementations built on WebAuthn standards are displacing SMS one-time passwords and knowledge-based authentication across consumer banking applications. Major retail banks in the United Kingdom and South Korea now mandate passkey enrollment for mobile account access. This displacement collapses phishing attack surfaces while shifting fraud liability from consumers to credential issuers.
The EU AI Act's biometric identification system classification triggers mandatory third-party conformity assessment for real-time facial recognition deployments. European border agencies and law enforcement procurement specifications now embed these assessment timelines. Vendors are responding by pre-certifying liveness detection modules against harmonized standards to compress deployment schedules.
Enterprise buyers now demand outcome-based identity verification contracts that tie vendor payments to fraud rate thresholds rather than per-transaction licensing. This restructuring concentrates risk with platform providers and favors vendors with captive biometric algorithm development. Financial services procurement in Germany and Canada exhibits this pattern most visibly, with three-year performance guarantees replacing annual software subscriptions.
Global Mobile Identification Market Segmentation
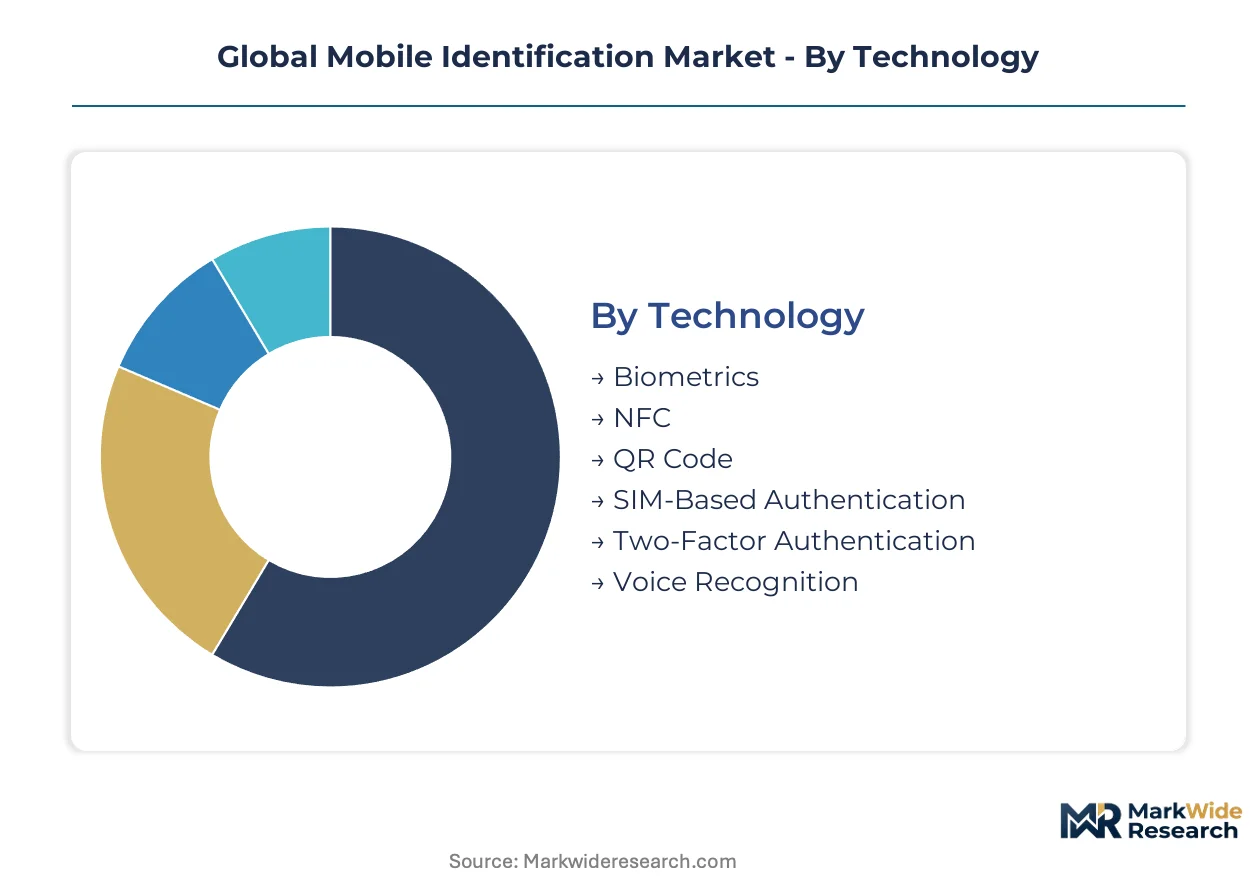
Mobile identification markets fragment across four dimensions that determine procurement patterns and vendor profitability. Technology choices dictate hardware requirements and certification burdens. Application verticals shape regulatory exposure and integration complexity. Deployment models determine recurring revenue potential versus upfront license structures.
Technology:
Margin pools concentrate in modalities requiring specialized sensor hardware and liveness detection certification, where pricing power exceeds commoditized software-only alternatives.
- Biometrics:Fingerprint, facial, and iris recognition systems bind credentials to physiological characteristics through ISO/IEC 30107-3 certified presentation attack detection. Financial institutions in Singapore and Australia mandate biometric liveness for high-value transaction authorization, compressing vendor certification timelines.
- NFC:Near-field communication enables contactless credential exchange between smartphones and verified readers using secure element-backed cryptographic protocols. Transit authorities in London and São Paulo deploy NFC mobile IDs for fare collection, creating concentrated demand for EMVCo-certified implementations.
- QR Code:Optical codes support offline verification with minimal infrastructure requirements. Retail chains in India and Brazil leverage QR-based mobile credentials for customer loyalty and payment authentication.
- SIM-Based Authentication:Embedded SIM and integrated SIM modules anchor identity to cellular network infrastructure. Telecommunications providers favor this modality for subscriber verification and roaming authentication.
- Two-Factor Authentication:Time-based one-time passwords and push notification systems supplement primary credentials. Enterprise IT departments deploy 2FA for workforce access control with lower per-user cost than biometric alternatives.
- Voice Recognition:Speaker identification algorithms enable hands-free authentication for automotive and smart home integrations. Automotive OEMs in Germany and South Korea integrate voice biometrics for driver profile activation.
Biometrics holds installed capacity. Voice recognition is rotating up the share rankings.
Application:
Volume concentration tracks regulatory mandates and transaction frequency, with payment and government verticals absorbing disproportionate deployment capital.
- Contactless Payments:EMVCo-compliant mobile wallets leverage tokenized credentials and biometric verification for point-of-sale transactions. Retail banks in the United Kingdom and South Korea now mandate passkey enrollment, displacing SMS authentication.
- Access Control:Physical and logical access systems authenticate employees, visitors, and devices against centralized policy engines. Corporate campuses in Singapore and Dubai deploy mobile badges for building entry and network access.
- E-Governance:National digital identity programs enable tax filing, benefit distribution, and document signing through government-issued mobile credentials. India's Aadhaar-linked ecosystem provides template demand for emerging economies.
- Employee Verification:Workforce identity systems integrate with HR platforms for onboarding, background checks, and privilege management. Multinational corporations standardize on mobile credentials for cross-border personnel authentication.
- Event Management:Ticketing and credentialing for conferences, sports venues, and entertainment facilities. Stadium operators in Qatar and Japan deploy mobile IDs for fan entry and concession payments.
- IoT Device Security:Mutual authentication protocols for connected vehicles, industrial sensors, and medical devices. Automotive manufacturers command premium pricing for hardware-rooted trust anchors in vehicle-to-infrastructure communications.
E-Governance dominates procurement volume. IoT Device Security commands the steepest expansion trajectory.
End User:
Customer sophistication determines contract structure complexity, with financial services and government buyers demanding outcome-based performance guarantees.
- Banking & Financial Institutions:Regulated entities deploy phishing-resistant authentication for customer onboarding and transaction authorization. German and Canadian banks now structure three-year fraud rate guarantees replacing annual software subscriptions.
- Telecommunications Providers:Mobile network operators integrate SIM-based identity for subscriber verification and fraud prevention. Brazilian carriers support Gov.br credential provisioning at scale.
- Government Agencies:National identity authorities issue mobile credentials for citizen services and border control. EU border agencies embed EU AI Act conformity timelines into procurement specifications.
- Retail Chains:Merchants deploy mobile loyalty and payment credentials to reduce checkout friction.
- Transportation Operators:Airlines, railways, and urban transit systems authenticate passengers and staff through mobile passes.
- Educational Institutions:Universities issue mobile credentials for campus access, library services, and examination verification.
Government Agencies anchor long-term contract value. Banking & Financial Institutions are gaining share fastest.
Deployment:
Architecture choices distribute operational risk between vendor and customer, with cloud models concentrating recurring revenue and edge deployments minimizing latency.
- Cloud-Based:Multi-tenant SaaS platforms deliver identity verification through API integration with customer applications. Okta and cloud-native vendors compete through orchestration capabilities extending enterprise access control into consumer deployments.
- On-Premises:Dedicated infrastructure within customer data centers satisfies data residency requirements and air-gapped security policies. Defense and intelligence agencies mandate on-premises deployment for classified credential systems.
- Hybrid:Split architectures process sensitive biometric data locally while leveraging cloud orchestration for policy management. European enterprises adopt hybrid models to satisfy GDPR data minimization while maintaining scalability.
- Edge Computing:Distributed processing nodes authenticate devices and users with minimal round-trip latency. Connected vehicle networks and industrial IoT deployments require edge-resident identity for real-time mutual authentication.
Cloud-Based holds subscriber volume. Edge Computing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Indian and Brazilian buyers prioritize low-cost QR-based deployments, while German and Singaporean procurement specifications command premium pricing for FIDO2-certified hardware security modules.
United States
Financial institutions drive phishing-resistant authentication mandates. The SEC and FFIEC pressure banks to abandon SMS-based verification. New York and San Francisco clusters concentrate fintech procurement for passkey infrastructure.
Germany
Automotive OEMs integrate voice biometrics for driver authentication. The BSI and EU AI Act impose conformity assessment burdens on facial recognition deployments. Munich and Stuttgart engineering centers lead connected vehicle identity standardization.
India
Aadhaar-linked mobile credentials enable instant verification for 1.3 billion residents. The BIS certification and PLI scheme localize component sourcing requirements. Bangalore and Hyderabad host concentrated biometric algorithm development operations.
Brazil
Gov.br targets 120 million mobile credentials by 2028. ANVISA and the central bank align digital health and financial identity standards. São Paulo anchors national procurement for biometric enrollment systems.
Singapore
MAS mandates phishing-resistant authentication for high-value transactions. The city-state's Smart Nation initiative funds hardware-backed credential pilots. Fintech procurement concentrates in the Marina Bay financial district.
Global Mobile Identification Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Hardware security module specialists command premium pricing in government contracts, while cloud-native orchestration vendors capture enterprise recurring revenue through API-based delivery. The market organizes around three strategic archetypes: defense-heritage conglomerates with captive semiconductor fabrication, biometric algorithm specialists with ISO/IEC 30107-3 certified liveness detection, and SaaS-native platforms extending enterprise access control into consumer deployments. Dominant competitive moves include FIDO2 pre-certification to compress procurement timelines and strategic partnerships with telecommunications carriers for SIM-based credential distribution.
Within the defense-heritage tier, Thales Group and IDEMIA exemplify vendors leveraging hardware security module heritage to anchor high-assurance government contracts. Thales Group occupies a position anchored in multi-continent government credentialing programs, while IDEMIA represents the biometric enrollment specialist archetype sustaining presence in national identity infrastructure. Okta, Inc. sits within the cloud-native orchestration tier, competing through identity orchestration capabilities that extend enterprise mobile access control into consumer-facing deployments.
| Leading Market Players |
|---|
| Thales Group |
| IBM Corporation |
| IDEMIA |
| OneLogin |
| SecureAuth Corporation |
| Micro Focus |
| Okta, Inc. |
| NEC Corporation |
| HID Global Corporation |
| Others |
Supply & Pricing Matrix
Passkey migration displacing SMS-based authentication simultaneously redraws component sourcing maps toward FIDO2-certified secure element foundries and compresses margins on legacy OTP hardware tiers. This substitution dynamic concentrates pricing power with East Asian semiconductor fabricators while forcing European and North American vendors toward software-centric orchestration layers to preserve margin.
Pricing Analysis
Post-deployment service contracts and biometric algorithm updates drive lifetime value capture across government and financial verticals. Pricing stratifies across FIDO2-certified hardware modules, ISO/IEC 30107-3 liveness detection tiers, and basic QR-credential software licenses. Cost compression in commoditized QR and voice recognition tiers intensifies because Indian and Brazilian procurement specifications prioritize low-cost scalability over certification depth. Banking and financial institutions exhibit lowest price sensitivity due to regulatory liability transfer requirements, while retail chains and educational institutions demand economy-tier deployments.
Supply Chain Analysis
Extended lead times for embedded secure element chips now stretch eighteen to twenty-four months at major East Asian foundries. Component fabrication concentrates in Taiwan, South Korea, and Japan, with biometric sensor module assembly anchored in China and Vietnam. The supply chain draws from silicon wafers, cryptographic co-processor IP, and NFC antenna substrates. Single-source vulnerability for eSE and eUICC production creates concentration risk. Distribution runs through telecommunications carrier partnerships for SIM-based credentials and direct enterprise sales for cloud-native orchestration platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across GDPR, EU AI Act, and national digital identity programs fragments procurement specifications, creating specialized vendor niches around compliance archetypes rather than consolidated platform dominance.
For Market Incumbents: Fortify position through captive biometric algorithm development and FIDO2 pre-certification investments that compress European procurement timelines. Acquire liveness detection specialists to offset margin pressure from cloud-native competitors. Deepen backward integration into secure element supply through foundry partnerships in Taiwan and South Korea. For New Entrants and Emerging Players: Anchor in Brazil's Gov.br ecosystem and India's Aadhaar-linked credential expansion, where government digital identity programs create template demand with lower incumbent saturation. Target voice recognition for automotive OEM integrations in Germany and South Korea. Pursue carrier partnerships for SIM-based credential distribution as the primary go-to-market channel. For Investors and Strategic Acquirers: Capital is best deployed toward biometric algorithm specialists with ISO/IEC 30107-3 certification and established government contract track records. Long-term viability favors vendors combining hardware-rooted trust anchors with privacy-preserving cryptography capabilities. Monitor EU AI Act conformity assessment timeline compression as the signal for accelerated European procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FIDO2 Pre-Certification Investment | Compresses procurement timelines for European banking and government contracts under MAS and EU AI Act mandates. |
| Biometric Algorithm Acquisition | Captures margin from outcome-based fraud rate guarantee contracts replacing per-transaction licensing in German and Canadian banking. |
| Telecommunications Carrier Partnership | Enables SIM-based credential distribution at scale for Brazil's Gov.br and India's Aadhaar-linked mobile ID programs. |
| Privacy-Preserving Cryptography Development | Satisfies GDPR data minimization requirements while preserving verification utility for European hybrid cloud deployments. |
| Automotive Voice Biometrics Integration | Penetrates connected vehicle identity market commanding premium pricing for driver profile activation in Germany and South Korea. |
Research Methodology
Operator-level perspectives from identity platform CTOs, government digital identity program directors, financial services fraud prevention executives, and telecommunications carrier security architects anchored the qualitative base. These primary interviews combined with secondary validation against FIDO Alliance certification databases, EU AI Act implementation guidance, and national digital identity program procurement disclosures. Bottom-up credential deployment estimates triangulated against top-down market sizing from hardware security module shipment data and cloud identity platform revenue disclosures.
Sensitivity analysis tested forecast outputs against alternative scenarios for FIDO2 mandate adoption velocity and secure element supply concentration resolution. The analytical framework modeled technology modality, application vertical, deployment architecture, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from logistic diffusion curves fitted to government program enrollment trajectories and banking authentication replacement cycles. Industry-specific inputs included biometric liveness detection certification timelines and eSIM penetration rates in target markets.
Material uncertainties — regulatory timeline delays, secure element supply disruptions, and biometric algorithm liability rulings — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
AI Security Platforms Market
Security Software
Intrusion Detection System / Intrusion Prevention System (IDS / IPS) Market
Security Software
Security Information and Event Management Software Market
Security Software
User Provisioning Software Market
Security Software
Privileged Access Management (PAM) Market
Security Software
Network Camera Market
Security Software
SSL Inspection Solution Market
Security Software
Encryption As A Service Market
Security Software
Cloud File Security Software Market
Security Software
Software Protection Dongle Market
Security Software
Vsaas Market
Security Software
Biometric POS Terminals Market
Security Software
Application Control Software Market
Security Software
Latin America Fraud Detection and Prevention Market
Security Software
United States Lawful Interception Market
Security Software
Italy Endpoint Detection and Response Market