
 Advanced Product Quality Planning (APQP) Software Market | 2026-2036
Advanced Product Quality Planning (APQP) Software Market Size, Share, and Industry Trends Forecast 2026-2036
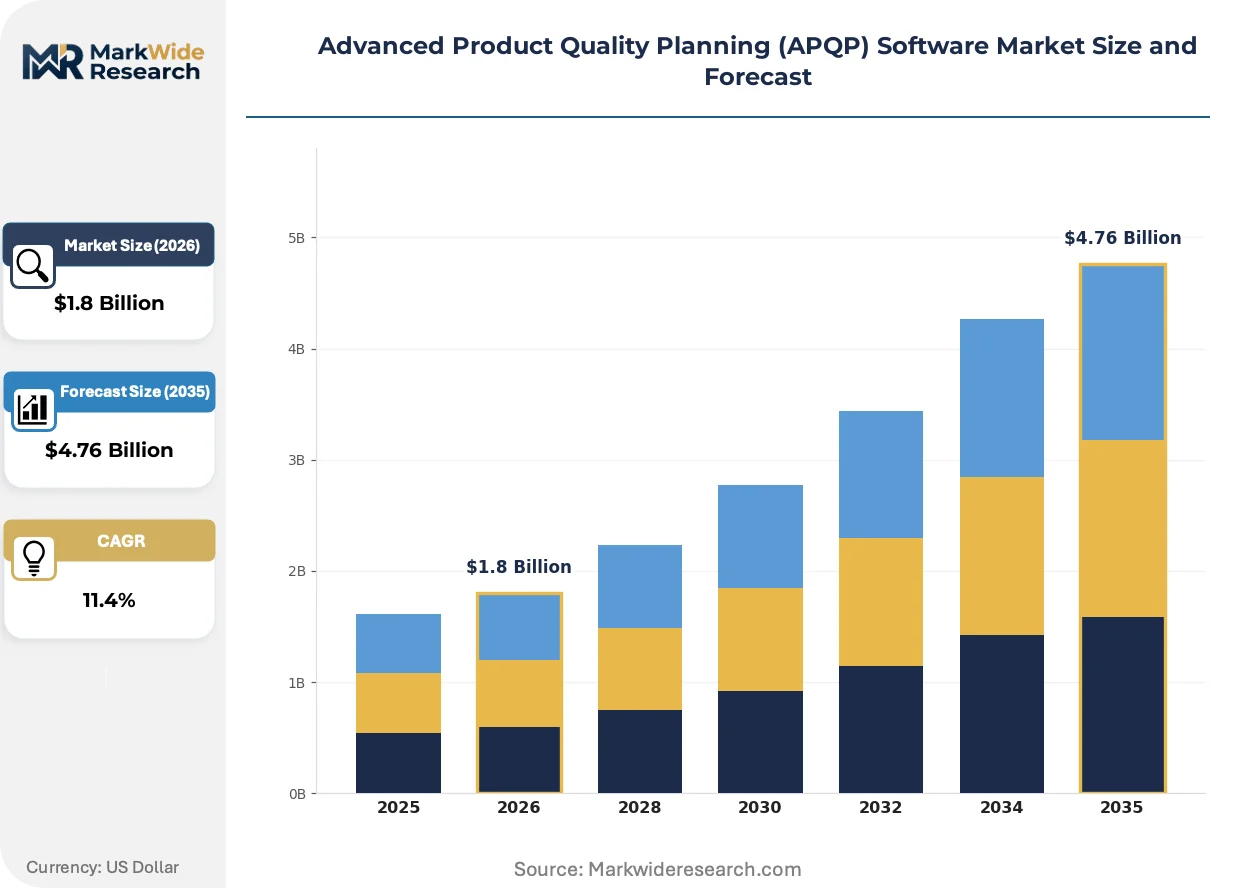
Advanced Product Quality Planning (APQP) Software Market Outlook
Subscription-based SaaS financing is rewriting competitive entry barriers for APQP software vendors, allowing mid-tier manufacturers to access enterprise-grade quality planning tools without capital-intensive on-premise deployments. Omnex leverages its consulting heritage to anchor integrated training-software bundles for automotive clients. IQMS sustains manufacturing execution system adjacencies that extend its quality modules into shop-floor data collection. SoftExpert Software differentiates through multi-standard compliance platforms spanning ISO 9001, IATF 16949, and AS9100 frameworks.
Advanced Product Quality Planning software constitutes a structured methodology platform for product design verification, process validation, and risk mitigation across five phased quality gates from planning through feedback loops. The system automates failure mode and effects analysis (FMEA), control plan generation, and measurement system analysis (MSA) to preempt defects before production ramp. Cloud-based deployments now lead segment momentum as automotive and aerospace supply chains demand real-time collaboration across dispersed engineering teams. Enterprise Solutions capture concentrated margin pools where multi-plant manufacturers require centralized audit trails and regulatory documentation repositories.
IATF 16949 enforcement through Germany's KBA and Japan's METI shapes product requirements for automotive APQP modules, while FDA 21 CFR Part 820 and EU MDR extend compliance burdens into medical device verticals. The FAA's delegation authority for aerospace suppliers adds AS9100-aligned functionality as a market access prerequisite. Stakeholders must monitor how AI-enabled predictive quality modules reshape vendor selection criteria before procurement cycles finalize.
Market Dynamics
Automotive OEMs are consolidating supplier quality management onto unified cloud platforms, compressing deployment cycles from eighteen months to under six months as IATF 16949 audit frequencies intensify across tier-one networks.
Growth Catalysts
- IATF 16949 Mandates:Germany's KBA and Japan's METI enforcement actions require documented APQP gates for supplier qualification, forcing tier-two and tier-three manufacturers onto certified platforms.
- AI-Enabled Predictive Modules:Machine learning algorithms trained on historical FMEA databases now flag design flaws before prototype stage, reducing engineering change orders by half in pilot deployments.
- Aerospace Supply Chain Expansion:FAA delegation authority requirements for AS9100 compliance are extending APQP methodologies from automotive into commercial aviation component sourcing.
Market Restraints
- Implementation Cost Barriers:Full APQP suite deployment including MSA and control plan modules demands six-figure upfront investment, excluding smaller stamping and molding shops.
- Data Architecture Fragmentation:Legacy ERP systems at mid-tier suppliers lack API compatibility, requiring manual data bridges that degrade real-time collaboration value.
- Specialized Talent Scarcity:Certified quality engineers capable of configuring FMEA workflows command premium salaries that inflate total cost of ownership for software buyers.
Strategic Opportunities
- Medical Device Vertical Expansion:FDA 21 CFR Part 820 design controls overlap with APQP phase-gate structures, creating cross-selling pathways for vendors with automotive heritage.
- Subscription Tier Penetration:Modular SaaS pricing for single-plant manufacturers opens addressable market segments previously served by spreadsheet-based quality tracking.
- Digital Twin Convergence:Integration between APQP platforms and process simulation software enables virtual validation of control plans before physical tooling commitment.
Industry Challenges
- Multi-Standard Certification Complexity:Suppliers serving automotive, aerospace, and medical device markets simultaneously face conflicting documentation formats between IATF 16949, AS9100, and ISO 13485.
- Supplier Onboarding Friction:Tier-one manufacturers struggle to enforce APQP compliance across dispersed global supply bases with varying digital maturity levels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Product Quality Planning (APQP) Software Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Enterprise Solutions Deployment Model: Public Cloud, Private Cloud, SaaS, PaaS End User: Manufacturers, Suppliers, OEMs, Quality Assurance Teams Industry Vertical: Automotive, Aerospace, Electronics, Medical Devices |
| Companies Covered | Blulink, DISCUS Software Company, Rocket Software, Omnex, IQMS, SoftExpert Software, SCR Soft Technologies, Quality-One International, CEBOS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Product Quality Planning (APQP) Software Market Strategic Shifts
Quality planning software architectures are pivoting from document repositories to active decision-support systems, embedding predictive analytics directly into engineering workflows rather than treating compliance as a retrospective audit function.
Generative AI for control plan authoring is migrating from experimental pilots to production deployment at major automotive OEMs. The technology parses CAD metadata and process flow diagrams to draft preliminary control plans, compressing engineering hours by sixty percent. Tier-one seating and powertrain suppliers in Michigan and Stuttgart are adopting these modules fastest, though human validation remains mandatory for IATF submission.
EU AI Act risk classification rules are reshaping vendor liability frameworks for automated quality decision tools. High-risk applications in safety-critical automotive components now require algorithmic transparency documentation and human-in-the-loop overrides. German and French automotive quality departments are demanding explainable AI modules before procurement approval, slowing deployment of black-box predictive systems.
Buyer preference is consolidating around outcome-based licensing models that tie subscription fees to measurable quality metrics rather than seat counts. Tier-one suppliers in Japan and the United States are piloting contracts where APQP platform costs scale with reduction in customer complaint rates or warranty claims. This restructures vendor incentives toward continuous feature development rather than static license maintenance.
Advanced Product Quality Planning (APQP) Software Market Segmentation
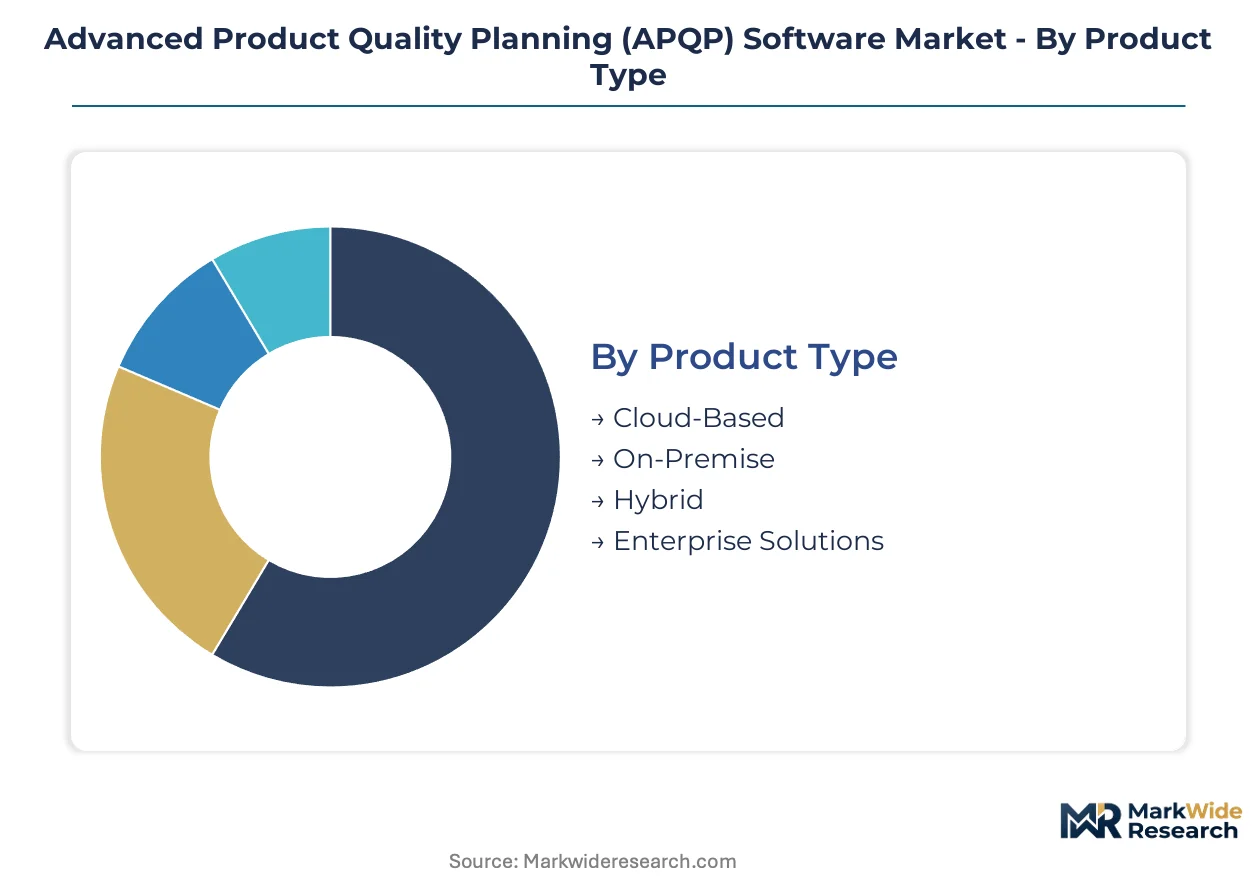
APQP software segmentation reflects divergent digital maturity across manufacturing tiers, with deployment architecture choices directly constraining supplier network integration depth and compliance audit readiness.
Product Type:
Cloud-based configurations now span single-plant implementations through multi-site enterprise orchestration, reshaping how quality gates propagate across dispersed engineering teams.
- Cloud-Based:Browser-accessible platforms with centralized FMEA databases enable real-time collaboration between Detroit automotive clusters and Stuttgart engineering centers. Tier-one seating suppliers in Michigan prioritize these deployments to compress IATF 16949 audit preparation cycles.
- On-Premise:Dedicated server installations retain air-gapped security for defense-aerospace contractors facing ITAR data sovereignty requirements. Legacy control plan archives at Japanese powertrain manufacturers often mandate this architecture for backward compatibility.
- Hybrid:Split configurations process sensitive design data locally while pushing anonymized quality metrics to cloud analytics engines. German medical device firms leverage this model to satisfy both EU MDR documentation retention and AI-enabled predictive module access.
- Enterprise Solutions:Multi-tenant platforms with centralized audit trails serve OEMs coordinating tier-two supplier networks across three continents. These systems integrate MSA, control plan generation, and corrective action tracking into unified regulatory repositories.
The dominant share belongs to Cloud-Based deployments, while Hybrid architectures are closing the gap fastest as dual-jurisdiction compliance burdens intensify.
Deployment Model:
Financing structure and infrastructure control trade-offs segment buyer preferences, with subscription elasticity competing against customization depth for procurement committee attention.
- Public Cloud:Shared infrastructure delivers lowest per-seat economics for mid-tier stamping and molding shops entering formalized quality planning. AWS and Azure regions in Frankfurt and Tokyo host the majority of automotive supplier instances.
- Private Cloud:Single-tenant environments isolate proprietary process parameters from competitor visibility in concentrated aerospace supply bases. FAA delegation authority audits increasingly require this isolation for AS9100 certification maintenance.
- SaaS:Pre-configured modules with standardized FMEA templates accelerate deployment for manufacturers transitioning from spreadsheet-based tracking. Monthly billing aligns quality software costs with production volume fluctuations.
- PaaS:Developer-accessible frameworks allow in-house quality engineers to embed custom measurement system analysis algorithms. Japanese automotive electronics suppliers favor this model for integrating proprietary SPC routines.
Public Cloud captures volume concentration among new entrants, though Private Cloud deployments are expanding most quickly in defense-adjacent verticals.
End User:
Organizational role determines functional requirements, with quality gate accountability distributed unevenly across the manufacturing value chain.
- Manufacturers:Plant-level quality departments deploy APQP platforms to automate control plan generation and PPAP submission workflows. Mexican automotive assembly operations utilize these tools to coordinate with US-based tier-one suppliers.
- Suppliers:Component and sub-assembly providers face OEM-mandated platform adoption to maintain approved vendor status. Korean battery manufacturers serving German OEMs exemplify this pressure.
- OEMs:Vehicle and equipment assemblers enforce standardized quality gate documentation across tiered supply networks. Centralized dashboards at Detroit and Stuttgart headquarters monitor supplier APQP completion rates.
- Quality Assurance Teams:Cross-functional audit groups leverage platform analytics to identify systemic failure mode patterns before prototype commitment. FDA 21 CFR Part 820 compliance in Minnesota medical device clusters depends on these capabilities.
OEMs command the largest implementation footprint, while Supplier-facing deployments are climbing the fastest as qualification requirements cascade downstream.
Industry Vertical:
Regulatory jurisdiction and product liability exposure create distinct feature priorities across safety-critical manufacturing domains.
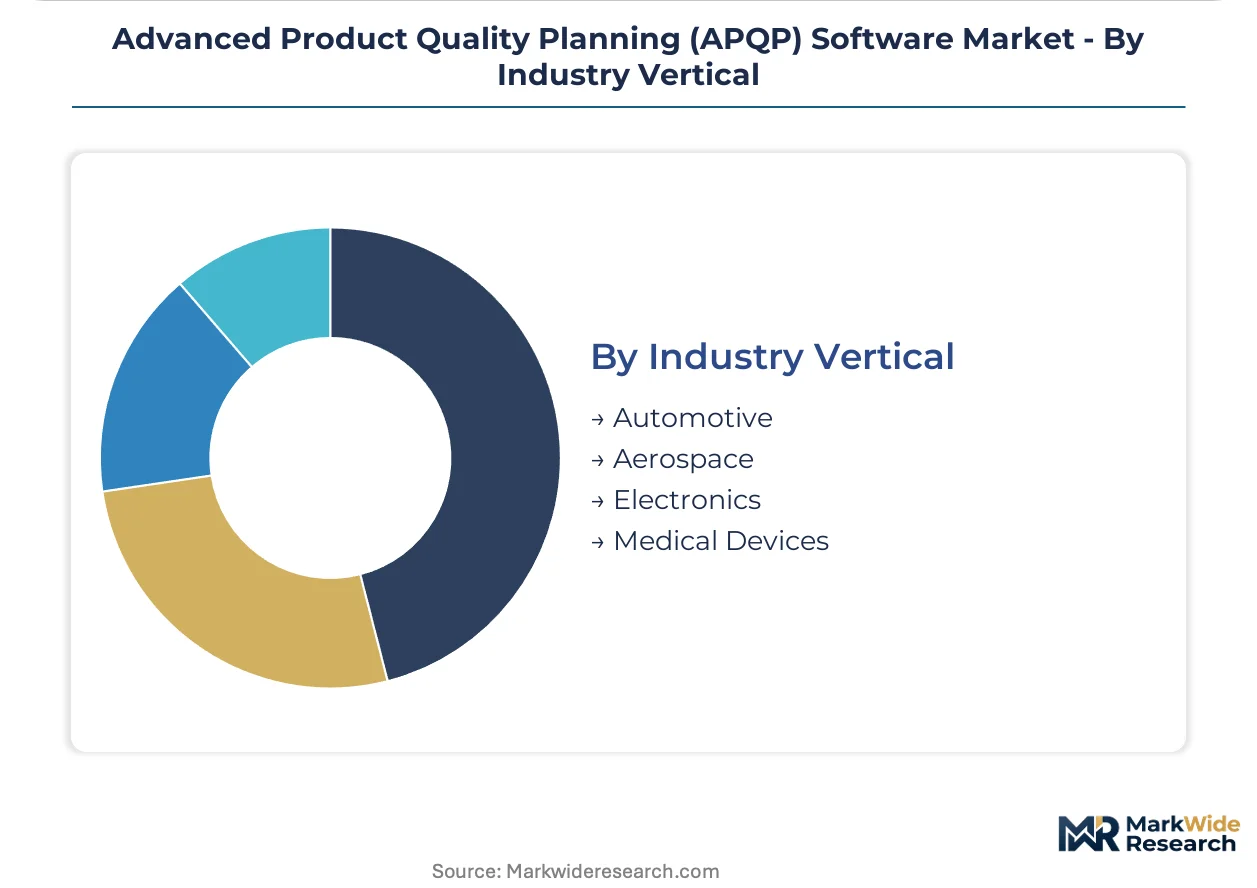
- Automotive:IATF 16949-mandated phase gates dominate requirements, with KBA and METI enforcement driving platform standardization across German and Japanese supplier networks. Electric powertrain transitions are accelerating FMEA refresh cycles.
- Aerospace:AS9100-aligned functionality with FAA delegation authority documentation supports commercial aviation component sourcing. Seattle and Toulouse engineering centers demand integration with PLM systems for configuration management.
- Electronics:RoHS and REACH substance tracking overlays traditional APQP structures for semiconductor and PCB manufacturers. Taiwanese contract manufacturers are adopting these modules for EU market access.
- Medical Devices:FDA 21 CFR Part 820 design controls and EU MDR technical documentation requirements extend APQP methodologies into healthcare technology. Boston and Minneapolis device clusters show strongest adoption velocity.
Automotive retains the dominant vertical position, though Medical Devices is gaining share fastest as cross-selling from automotive heritage platforms accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA enforcement of IATF 16949 supplier qualification requirements is accelerating platform standardization across European automotive networks. Japan's METI directives and FDA design control mandates in the United States are compressing deployment timelines for quality planning software.
United States
FDA 21 CFR Part 820 design controls and NHTSA safety reporting requirements drive APQP adoption across medical device and automotive clusters. The Minneapolis medical device corridor and Detroit automotive belt represent concentrated demand zones where tier-one suppliers coordinate multi-plant quality gates through cloud-based platforms.
Germany
KBA audit intensification and EU AI Act risk classification rules reshape vendor selection criteria for automotive quality departments. Stuttgart engineering centers and Bavarian powertrain clusters enforce standardized APQP documentation across tier-two networks, with explainable AI modules now mandatory for procurement approval.
Japan
METI enforcement actions and JIS quality standards mandate documented phase gates for supplier qualification. Nagoya automotive electronics manufacturers and Kanto region OEM headquarters deploy hybrid architectures to satisfy both data sovereignty requirements and predictive analytics access.
China
GB standards alignment with international quality frameworks and MIIT smart manufacturing initiatives accelerate platform localization. Yangtze River Delta battery manufacturers and Pearl River Delta electronics assemblers adopt SaaS modules to coordinate with German and US-based tier-one customers.
South Korea
MFDS medical device regulations and automotive export compliance requirements extend APQP methodologies into healthcare technology. Seoul Capital Area battery suppliers serving German OEMs exemplify downstream platform adoption pressure cascading from customer qualification mandates.
Advanced Product Quality Planning (APQP) Software Market Competitive Environment
On the supply side, the industry is consolidating around three strategic archetypes: consulting-heritage firms bundling training with software, manufacturing execution system vendors extending quality modules, and multi-standard compliance specialists spanning automotive, aerospace, and medical device frameworks. M&A activity concentrates on predictive analytics capabilities, while strategic partnerships with PLM providers reshape integration roadmaps.
Among consulting-heritage platforms, Omnex and Quality-One International exemplify the integrated training-software model, anchoring customer relationships through certification programs. IQMS represents the manufacturing execution system adjacency archetype, extending shop-floor data collection into quality planning workflows. SoftExpert Software occupies the multi-standard compliance tier, spanning IATF 16949, AS9100, and ISO 13485 frameworks within unified platforms.
| Leading Market Players |
|---|
| Blulink |
| DISCUS Software Company |
| Rocket Software |
| Omnex |
| IQMS |
| SoftExpert Software |
| SCR Soft Technologies |
| Quality-One International |
| CEBOS |
| Others |
Value Chain & Pricing Dynamics
Stuttgart's dense concentration of tier-one automotive engineering centers concentrates platform procurement power, compressing SaaS pricing for APQP modules while elevating premium tiers for multi-standard compliance bundles serving aerospace and medical device adjacencies.
Pricing Analysis
Certification level creates the primary spread between entry-level SaaS tiers and enterprise-grade deployments, with IATF 16949-grade modules commanding substantial premiums over basic FMEA automation. Subscription elasticity favors mid-tier manufacturers, though customization for AS9100 and FDA 21 CFR Part 820 compliance inflates professional services attach rates. Price differentiation intensifies as cloud-native entrants undercut legacy on-premise vendors, eroding maintenance revenue pools. Tier-two stamping suppliers exhibit acute price sensitivity, while OEM procurement committees prioritize audit-ready documentation over per-seat economics.
Supply Chain Analysis
Extended payment terms from tier-one automotive buyers strain APQP software vendor cash cycles, accelerating reliance on supply-chain finance facilities to bridge deployment-to-recognition gaps. Development talent concentrates in Germany, the United States, and India, with Bangalore-based engineering centers feeding white-label platform components to Western vendors. Cloud infrastructure dependencies rest on AWS and Azure regions in Frankfurt, Tokyo, and Virginia, exposing subscription pricing to hyperscaler cost pass-through. Single-source vulnerability concentrates in AI-enabled predictive modules trained on proprietary FMEA databases. Distribution runs through direct enterprise sales teams supplemented by consulting-heritage training bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified quality engineers capable of configuring cross-standard FMEA workflows remain scarce relative to platform deployment timelines, creating persistent bottlenecks for vendors scaling beyond automotive into medical device and aerospace verticals.
For Market Incumbents: Entrench multi-standard compliance leadership by accelerating AS9100 and ISO 13485 module development ahead of aerospace and medical device procurement cycles. Deepen vertical integration into training certification ecosystems to lock in switching costs. Prioritize explainable AI investment before EU AI Act enforcement hardens procurement criteria in German automotive clusters. For New Entrants and Emerging Players: Establish a beachhead in mid-tier medical device manufacturers transitioning from spreadsheet-based quality tracking, where FDA 21 CFR Part 820 documentation burdens outpace IT sophistication. Target Korean battery suppliers facing German OEM qualification pressure as the most penetrable supplier segment. Lead with modular SaaS pricing tied to PPAP submission volume rather than enterprise seat counts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with embedded predictive analytics capabilities over document-repository incumbents, as AI-enabled quality modules reshape vendor selection criteria. Long-term viability hinges on outcome-based licensing traction and PLM integration depth. Watch for tier-one automotive procurement committees mandating human-in-the-loop AI documentation as the inflection signal for explainable quality tools.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Compliance Platform Expansion | AS9100 and ISO 13485 modules unlock aerospace and medical device procurement committees previously blocked by automotive-only heritage. |
| Explainable AI Module Development | Algorithmic transparency documentation satisfies EU AI Act risk classification rules demanded by German KBA audit preparation workflows. |
| Outcome-Based Licensing Pilots | Subscription fees tied to customer complaint rate reduction align vendor incentives with tier-one supplier quality metrics in Japan and the United States. |
| PLM System Integration Partnerships | Native connectivity with Siemens Teamcenter and Dassault ENOVIA accelerates control plan generation for Stuttgart and Detroit engineering centers. |
| Training Certification Ecosystem Lock-In | Integrated consulting-software bundles create switching costs that defend maintenance revenue against cloud-native price undercutting. |
Study Parameters
Desk research of regulatory filing databases, hyperscaler capex disclosures, and automotive production statistics preceded structured interviews with APQP platform product managers, tier-one supplier quality directors, OEM procurement officers, and FAA delegation authority auditors. Secondary validation drew from IATF 16949 audit documentation, FDA 21 CFR Part 820 design control filings, and EU MDR technical documentation repositories. Bottom-up deployment estimates across cloud, on-premise, and hybrid architectures were cross-checked against top-down software spend allocations from manufacturing verticals.
Assumptions held IATF 16949 enforcement intensity, EU AI Act implementation timelines, and cloud infrastructure cost trajectories constant across the analysis window, while varying AI adoption curves, medical device vertical penetration rates, and aerospace supply chain expansion velocity. Segmentation modeling spanned deployment architecture, organization size tier, industry vertical, and geographic regulatory cluster. CAGRs were derived from installed base growth and average revenue per account expansion across the projection horizon, with electric powertrain transition intensity and FMEA refresh cycle compression as key demand inputs.
Sensitivities concentrate around regulatory enforcement variance, AI liability framework evolution, and tier-two supplier digital readiness gaps. Forecasts reflect documented assumptions regarding compliance mandate propagation and cloud migration velocity. Macroeconomic contraction, accelerated EU AI Act risk reclassification, or breakthrough generative AI capabilities would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Content Management Software Market
Software & Services
Legal Software Market
Software & Services
Driver Updater Software Market
Software & Services
Global Data Entry Software Market
Software & Services
ID Photo Software Market
Software & Services
SAP HANA and S4HANA Market
Software & Services
Global Accounts Receivable Software Market
Software & Services
Poland IT Software and Service Market
Software & Services
Global Server Management Software Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
HR Saas Market
Software & Services
Global App Design Software Market
Software & Services
Event Management Software Market
Software & Services
Global Lead Capture Software Market
Software & Services
Performance Management Software Market
Software & Services
Russian IT Software and Services Market