
 Sales Platforms Software Market | 2026-2036
Sales Platforms Software Market Size, Share, and Industry Trends Forecast 2026-2036
Sales Platforms Software Market Analytics
Mid-market enterprises is redrawing demand patterns in sales platforms software as these buyers shift from fragmented point solutions toward unified revenue stacks. Salesforce anchors the high end through deep ecosystem integration and extensive ISV marketplace density. Gong differentiates via proprietary conversation intelligence that captures and analyzes buyer-seller interactions at scale. Pipedrive competes on usability-led design for smaller sales teams seeking rapid deployment without heavy consulting overhead.
Sales platforms software encompasses cloud-native and on-premise applications that orchestrate customer relationship data, pipeline workflows, and revenue forecasting through configurable automation rules and API-connected data layers. These systems process structured deal records alongside unstructured communication signals to generate predictive scoring and quota attainment visibility. Cloud-Based deployment leads in new customer acquisition velocity due to lower capital requirements and faster time-to-value cycles. Sales Analytics functionality captures disproportionate R&D investment as vendors race to embed generative reasoning across forecasting and pipeline inspection workflows. API Integration represents the highest-margin configuration tier because enterprise buyers demand bidirectional synchronization with existing ERP and data warehouse investments.
The EU AI Act imposes risk-classification requirements on automated decision-making within sales scoring algorithms, compelling platform architects to build explainability layers and human-in-the-loop checkpoints. The SEC's escalating disclosure mandates around revenue recognition timing create downstream pressure for audit-grade pipeline data integrity in platforms serving publicly traded customers. Stakeholders must evaluate whether their current architecture can absorb emerging compliance obligations without fragmenting the user experience or inflating implementation timelines.
Market Dynamics
Mid-market enterprises are consolidating fragmented point solutions into unified revenue stacks, forcing vendors to absorb adjacent workflow layers or cede wallet share to platform consolidators.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification requirements for automated scoring algorithms are accelerating procurement of explainable automation platforms with built-in audit trails and human-in-the-loop checkpoints.
- Cloud-native architecture migration:Lower capital requirements and compressed time-to-value cycles are pulling mid-market buyers away from on-premise deployments toward subscription-based delivery models.
- Sales Analytics R&D concentration:Vendors are embedding generative reasoning across forecasting workflows, capturing disproportionate investment as buyers demand predictive pipeline visibility.
Market Restraints
- API integration cost inflation:Enterprise buyers demand bidirectional synchronization with ERP and data warehouse investments, inflating professional services margins and extending implementation timelines.
- GDPR data residency friction:Cross-border data flow restrictions are fragmenting platform architectures and forcing redundant infrastructure deployment across European jurisdictions.
- Legacy system technical debt:Proprietary on-premise CRM installations resist cloud migration, creating sticky incumbent positions that slow replacement cycles in established accounts.
Strategic Opportunities
- India digital sales infrastructure buildout:Enterprise software penetration remains below saturation in domestic mid-market segments, creating first-mover advantage for localized deployment support.
- Conversation intelligence convergence:Unstructured communication signal capture is merging with structured deal records, enabling new pricing tiers for predictive engagement scoring.
- SEC disclosure mandate tailwinds:Escalating revenue recognition timing requirements are pushing publicly traded customers toward audit-grade pipeline data integrity modules.
Industry Challenges
- Machine learning operations talent scarcity:Platform vendors struggle to hire engineers capable of deploying explainable AI pipelines that satisfy regulatory interrogation without degrading inference latency.
- Multi-tenant security certification complexity:SOC 2 Type II and ISO 27001 attestation timelines stretch 9-14 months, delaying market entry for emerging vendors targeting regulated industries.
- Workflow integration fragmentation:Buyer environments span dozens of adjacent SaaS tools, forcing vendors to maintain brittle connector libraries that drain engineering capacity from core product differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sales Platforms Software Market |
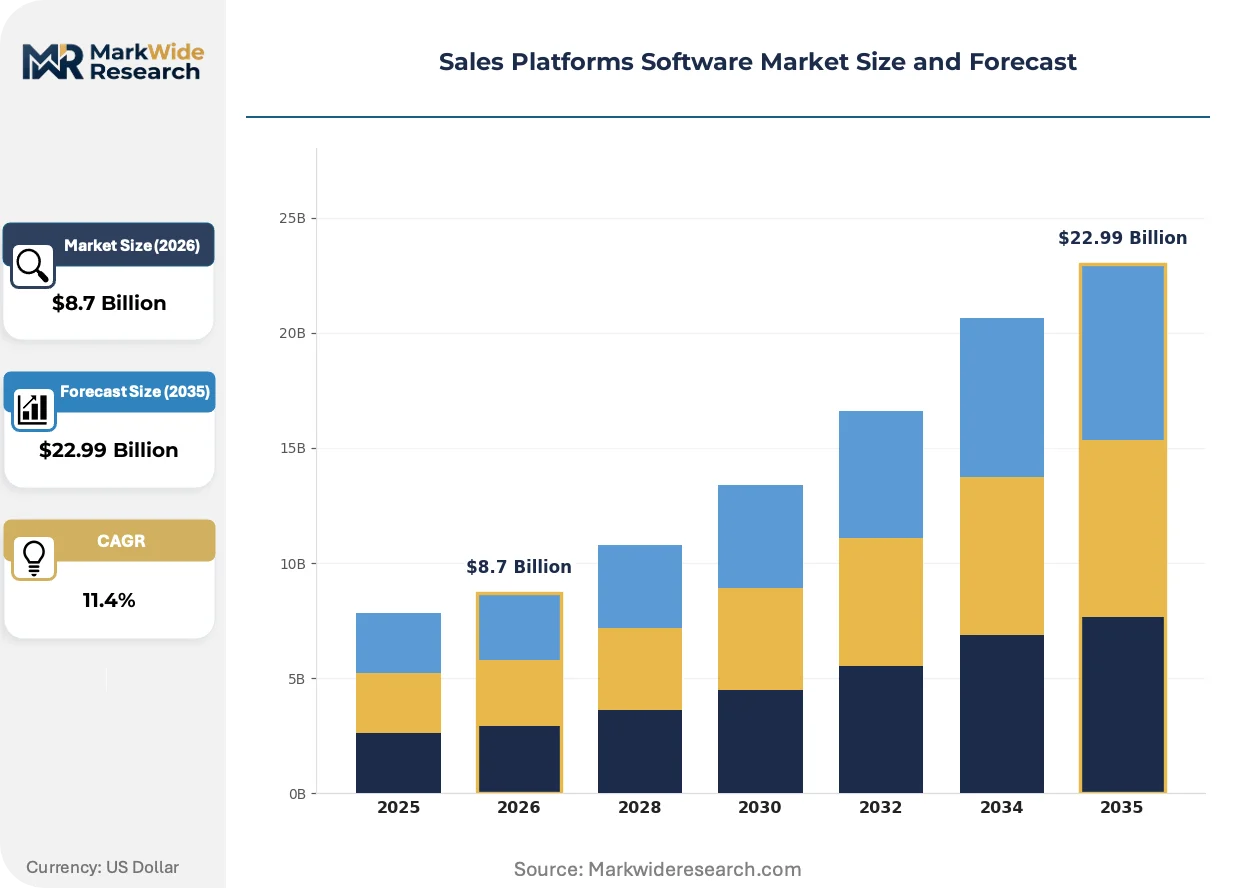
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Customer Type: Small Businesses, Enterprises, Startups, Independent Professionals Functionality: CRM Tools, Sales Analytics, Lead Management, Payment Processing Integration Level: API Integration, ERP Integration, E-commerce Integration, Social Media Integration |
| Companies Covered | Apollo.io, Gong, Salesforce, Salesloft, Pipedrive, HubSpot, Clari, Forecastio, Outreach, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sales Platforms Software Market Evolving Landscape
Generative reasoning capabilities are compressing the traditional boundary between CRM data layers and predictive analytics engines, forcing architectural redesigns across incumbent platforms.
Large language model orchestration is decomposing monolithic sales automation into modular reasoning agents that handle specific pipeline inspection tasks. Mid-market teams in the United States are piloting these agentic workflows for quota attainment forecasting and deal risk scoring. The technology is decomposing established vendor moats built on proprietary forecasting algorithms, lowering switching costs for buyers willing to compose best-of-breed components.
The EU AI Act's risk-classification framework is mandating algorithmic impact assessments for automated lead scoring systems above defined thresholds. Platform architects must now embed documentation layers that trace training data provenance and decision logic for regulatory examination. Vendors serving German automotive and industrial equipment sectors are responding fastest, embedding compliance tooling as premium-priced configuration tiers.
Subscription fatigue among software buyers is compressing vendor evaluation cycles and elevating proof-of-concept demands. Procurement committees now require demonstrable ROI within 90-day windows before committing to annual contracts. This pattern concentrates most visibly among United States-based SaaS-native companies with lean revenue operations teams and limited implementation bandwidth.
Sales Platforms Software Market Segmentation
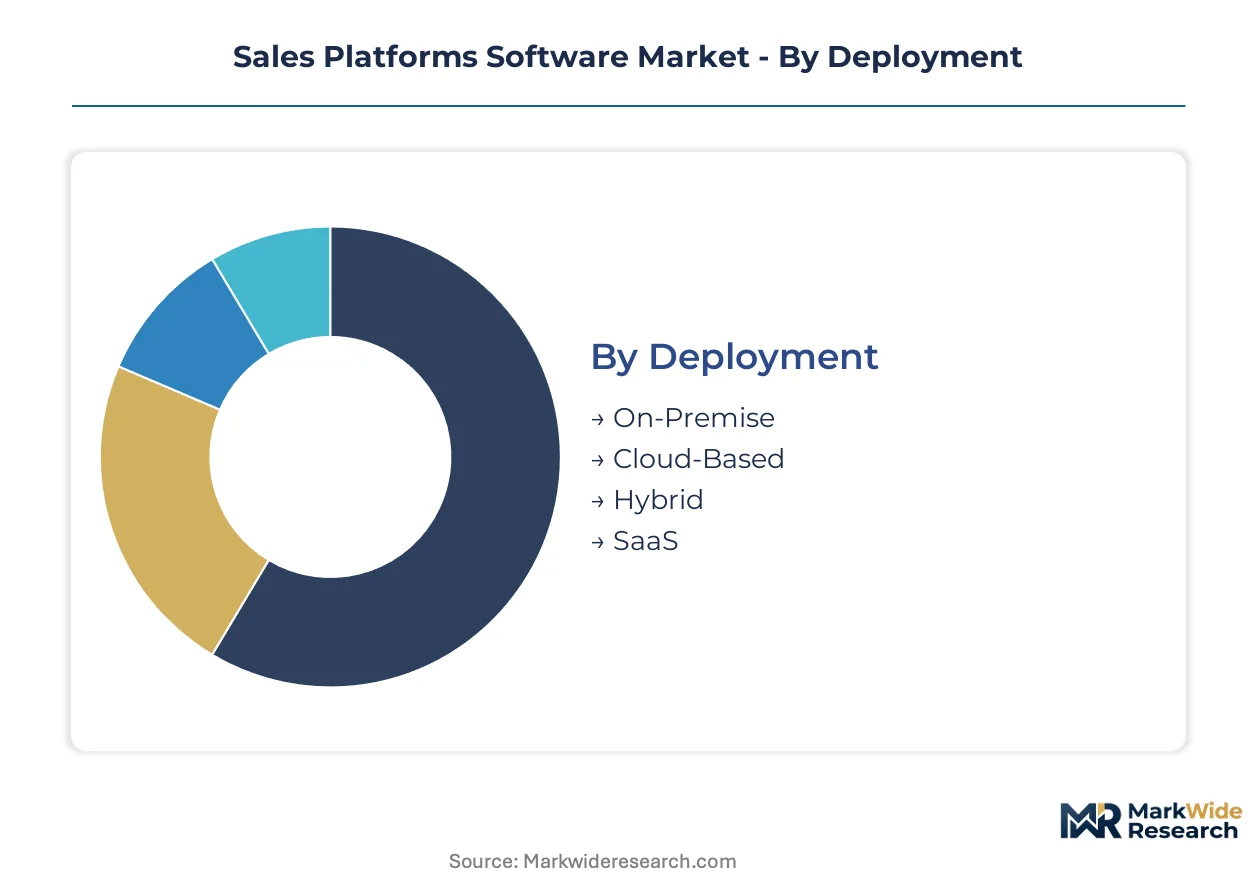
Deployment architecture determines how sales platforms software reaches buyers and what implementation constraints shape purchasing decisions. Customer type and functionality layers further stratify vendor positioning across implementation complexity and workflow depth requirements.
Deployment:
Cloud-native delivery channels dominate new customer acquisition, while legacy infrastructure sustains recurring revenue from established accounts with sunk capital in on-premise systems.
- Cloud-Based:Multi-tenant architectures eliminate server maintenance overhead and compress implementation timelines from months to weeks. Demand concentrates among mid-market enterprises in Germany and India seeking unified revenue stacks without capital expenditure burdens. GDPR data residency requirements are forcing vendors to deploy regional cloud instances, fragmenting infrastructure strategies.
- SaaS:Subscription billing aligns vendor incentives with customer success outcomes through usage-based pricing tiers. United States-based SaaS-native companies with lean revenue operations teams are driving procurement velocity through 90-day ROI proof-of-concept requirements. The EU AI Act's risk-classification framework is embedding compliance tooling as premium-priced configuration tiers.
- On-Premise:Proprietary installations resist migration due to customized workflow integrations and regulatory data custody requirements.
- Hybrid:Split architectures accommodate sensitive deal data on-premise while leveraging cloud analytics layers for forecasting workloads.
On-Premise dominates installed base. SaaS is where expansion concentrates.
Customer Type:
Organizational scale dictates feature depth requirements and sales cycle complexity, with procurement authority distributed differently across hierarchy levels.
- Enterprises:Complex approval workflows and multi-stakeholder committees demand audit-grade pipeline data integrity modules. Publicly traded customers in the United States face SEC disclosure mandates around revenue recognition timing, pushing procurement toward platforms with built-in compliance documentation. API integration requirements inflate professional services margins and extend implementation timelines.
- Small Businesses:Limited implementation bandwidth favors usability-led design with rapid deployment without heavy consulting overhead. Pipedrive and similar vendors compete on intuitive interfaces that reduce training requirements for lean sales teams. Subscription fatigue is compressing evaluation cycles and elevating proof-of-concept demands.
- Startups:Venture-backed growth trajectories prioritize scalable pricing that aligns with headcount expansion rather than upfront commitments.
- Independent Professionals:Solopreneur workflows require stripped-down functionality with mobile-first access and minimal configuration overhead.
Enterprises command highest annual contract values. Small Businesses are climbing the fastest.
Functionality:
Feature module selection reflects buyer maturity in data-driven selling, with advanced analytics commanding premium positioning.
- Sales Analytics:Generative reasoning capabilities are embedding across forecasting and pipeline inspection workflows, capturing disproportionate R&D investment. Mid-market teams in the United States are piloting agentic workflows for quota attainment forecasting and deal risk scoring. Vendors race to deploy explainable AI pipelines that satisfy regulatory interrogation without degrading inference latency.
- CRM Tools:Core customer relationship data orchestration remains the entry point for platform adoption, with Salesforce anchoring the high end through ecosystem integration density. Structured deal records form the foundation upon which predictive layers are constructed. Legacy system technical debt creates sticky incumbent positions that slow replacement cycles.
- Lead Management:Automated scoring algorithms face EU AI Act risk-classification requirements mandating human-in-the-loop checkpoints.
- Payment Processing:Native transaction capabilities reduce friction in quote-to-cash workflows for subscription-heavy business models.
CRM Tools dominate installed base. Sales Analytics is gaining share fastest.
Integration Level:
Connectivity depth determines platform stickiness and switching costs, with bidirectional synchronization becoming table stakes for enterprise procurement.
- API Integration:Bidirectional data flows with ERP and data warehouse investments represent the highest-margin configuration tier. Enterprise buyers demand real-time synchronization that maintains single-source-of-truth integrity across financial and operational systems. Engineering capacity drains from core product differentiation into maintaining brittle connector libraries spanning dozens of adjacent SaaS tools.
- ERP Integration:Direct connectivity with SAP, Oracle, and Microsoft Dynamics environments anchors platforms within established technology stacks. German automotive and industrial equipment sectors prioritize seamless financial data reconciliation. Multi-tenant security certification complexity stretches 9-14 months for SOC 2 Type II and ISO 27001 attestation.
- E-commerce Integration:Shopify and Magento connectors enable unified customer views across digital and direct sales channels.
- Social Media Integration:LinkedIn and Twitter connectivity supports social selling workflows and prospect research automation.
API Integration commands premium pricing. ERP Integration anchors renewal rates.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based vendors export cloud-native sales platforms to German automotive clusters and Indian mid-market enterprises, establishing a transatlantic-Asia-Pacific trade corridor that channels subscription revenue toward compliance-heavy European jurisdictions and digitally transforming Asian markets.
United States
SEC disclosure mandates around revenue recognition timing push publicly traded enterprises toward audit-grade pipeline data integrity modules. The FTC monitors subscription billing practices as SaaS procurement velocity accelerates through compressed 90-day ROI proof-of-concept requirements. Silicon Valley and Greater Boston anchor vendor R&D concentration for generative reasoning capabilities embedding across forecasting workflows.
Germany
Automotive and industrial equipment sectors demand seamless ERP synchronization with SAP environments, inflating professional services margins for bidirectional data flow implementations. The EU AI Act risk-classification framework mandates algorithmic impact assessments for automated lead scoring systems above defined thresholds. Baden-Württemberg and Bavaria host dense clusters of manufacturing exporters seeking explainable automation platforms with built-in audit trails.
India
Domestic mid-market segments below software saturation create first-mover advantage for localized deployment support and regional cloud instances. RBI guidelines on data localization intersect with enterprise procurement preferences for sovereign infrastructure hosting. Karnataka and Maharashtra build out digital sales infrastructure as SaaS-native companies in Bangalore and Mumbai pilot agentic workflows for quota attainment forecasting.
United Kingdom
Post-Brexit regulatory divergence creates dual compliance obligations for vendors serving both UK and EU customers from London headquarters. The Information Commissioner's Office enforces GDPR-aligned data protection standards that fragment platform architectures across Channel-crossing data flows. London's fintech concentration drives demand for real-time pipeline visibility tools among venture-backed growth companies.
Japan
Enterprise software procurement cycles favor established vendor relationships with extensive customization capabilities and local implementation partners. METI initiatives around digital transformation subsidize mid-market adoption of cloud-based revenue operations platforms. Tokyo and Osaka metropolitan areas concentrate headquarters of manufacturing exporters requiring bidirectional synchronization with legacy ERP investments.
Sales Platforms Software Market Competitive Landscape
Player mix skews toward ecosystem-anchored incumbents with dense ISV marketplaces, conversation intelligence specialists capturing unstructured communication signals, and usability-focused challengers serving lean implementation bandwidth constraints. Strategic archetypes include platform consolidators absorbing adjacent workflow layers, vertical specialists embedding industry-specific compliance tooling, and API-native upstarts attacking integration cost inflation. Dominant competitive moves center on M&A absorption of point-solution vendors and geographic expansion through regional cloud instance deployment.
Within the ecosystem-anchored tier, Salesforce occupies a position exemplifying deep marketplace density and extensive ISV integration. Gong and Clari represent the conversation intelligence specialization vector, capturing buyer-seller interaction signals at scale. Pipedrive anchors the usability-led challenger archetype for rapid deployment without heavy consulting overhead.
| Leading Market Players |
|---|
| Apollo.io |
| Gong |
| Salesforce |
| Salesloft |
| Pipedrive |
| HubSpot |
| Clari |
| Forecastio |
| Outreach |
| Others |
Value Network & Pricing Analysis
SOC 2 Type II and ISO 27001 certification timelines stretching 9-14 months gate both vendor qualification and subscription tier differentiation, compressing margins for emerging entrants while anchoring premium pricing for established platforms with attestation in place.
Pricing Analysis
Legacy on-premise licensing, current SaaS subscription tiers, and emerging agentic workflow bundles define a three-generation pricing spread that stratifies buyer access. Pricing stratifies across enterprise-grade API integration tiers, mid-market usability-led packages, and small-team entry-level configurations, with SOC 2 certification status as a sharp price divider. Cost compression in the mid-market segment intensifies because procurement committees now mandate 90-day ROI proof-of-concept windows before annual commitments. Small businesses exhibit highest price sensitivity, while publicly traded enterprises absorbing SEC disclosure mandates show lowest sensitivity to compliance-premium pricing.
Supply Chain Analysis
Hyperscaler cloud regions in the United States, Germany, and India anchor platform delivery infrastructure, creating geographic chokepoints for data residency compliance. Vendor operations draw from NVIDIA GPU clusters for inference workloads, proprietary conversation intelligence training datasets, and ERP connector libraries maintained across SAP, Oracle, and Microsoft Dynamics environments. Single-source vulnerability concentrates in hyperscaler dependency, where AWS, Azure, or GCP outages cascade to tenant platforms. Distribution runs through direct enterprise sales teams, self-service digital channels, and value-added reseller networks serving localized implementation demands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative reasoning capabilities embedded in forecasting workflows pose acute substitution risk to proprietary algorithm moats, forcing incumbents to defend against modular agentic systems that decompose traditional platform value.
For Market Incumbents: Compound ecosystem density through deeper ISV marketplace integration and captive API connector development, neutralizing the threat from best-of-breed composability. Prioritize backward integration into conversation intelligence training data pipelines to secure proprietary signal capture advantages against Gong and Clari specialization. For New Entrants and Emerging Players: Anchor in India's domestic mid-market segments below software saturation, where localized deployment support creates first-mover positioning before Salesforce and HubSpot regional cloud expansion. Target lean revenue operations teams in United States SaaS-native companies with 90-day proof-of-concept positioning that incumbents cannot match without consulting overhead. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertical specialists embedding EU AI Act compliance tooling as premium-priced configuration tiers for German automotive and industrial equipment sectors. Monitor SEC revenue recognition disclosure mandate enforcement intensity as the inflection signal for audit-grade pipeline data integrity module demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Absorbing adjacent workflow layers prevents point-solution vendors from capturing wallet share in unified revenue stack procurement. |
| Acquisition of Specialist Firm | Conversation intelligence capabilities from targets like Gong-trained teams accelerate explainable AI pipeline deployment for EU AI Act compliance. |
| Geographic Expansion | Regional cloud instances in Karnataka and Maharashtra address RBI data localization intersecting with enterprise sovereign hosting preferences. |
| Strategic Partnership | SAP environment synchronization partnerships secure renewal anchoring in Baden-Württemberg manufacturing exporter clusters. |
| Product Launch | Agentic workflow modules for quota attainment forecasting capture disproportionate R&D investment as generative reasoning compresses CRM-analytics boundaries. |
Research Methodology
Operator-level perspectives from revenue operations leaders, CRM platform engineers, IT procurement officers, and integration specialists anchored the qualitative base, cross-referenced against SEC 10-K filings, hyperscaler capex disclosures, EU AI Act regulatory documentation, and App Annie/Sensor Tower adoption metrics. Bottom-up deployment counts and top-down vendor revenue estimates were triangulated to constrain segmentation outputs.
Sensitivity analysis across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern shaped the analytical framework throughout the projection horizon. CAGRs were derived from fitted growth curves against historical penetration rates, with EU AI Act compliance timeline acceleration and SEC disclosure mandate escalation as scenario-dependent inputs.
Decision-makers should treat outputs as directional under sustained mid-market cloud migration and regulatory compliance investment assumptions; material deviation in hyperscaler pricing or GDPR enforcement intensity would warrant model refresh. Practitioners should keep alternative scenarios live as agentic workflow adoption curves and subscription fatigue patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Predictive Dialer Software Market
Software & Services
Search and Discovery Software Market
Software & Services
Load Balancing Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Mobile Device Management (MDM) Market
Software & Services
Outsourced Software Testing Services Market
Software & Services
Global Email Software Market
Software & Services
Feedback Management Software Market
Software & Services
Dealer Management System Market
Software & Services
Specification Management Software Market
Software & Services
Global Food Traceability Software Market
Software & Services
Braking Systems Software Market
Software & Services
Custom Software Development Market
Software & Services
Spain Sports Management Software Market
Software & Services
Digital Sculpture Software Market
Software & Services
Device Tracking Software Market