
 Smartphone Music Production Software Market | 2026-2036
Smartphone Music Production Software Market Size, Share, and Industry Trends Forecast 2026-2036
Smartphone Music Production Software Market Analysis
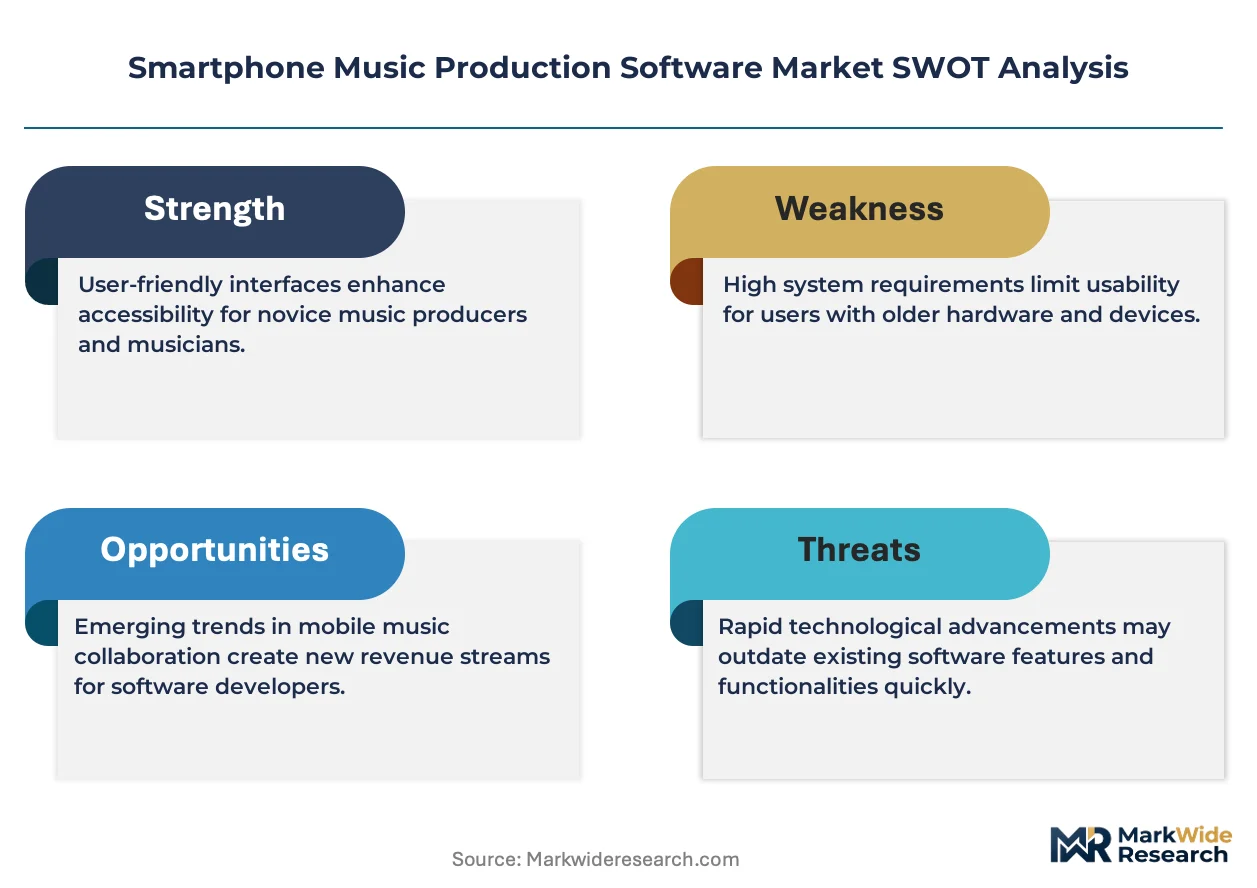
Freemium-to-premium bundling is shifting how smartphone music production software reaches buyers, with basic multi-track recording offered at no cost and advanced virtual instruments locked behind subscription tiers. Apple Inc. leverages its Logic Pro ecosystem to anchor iOS-native production workflows, while BandLab Technologies competes through social-first distribution that merges creation with community sharing. Native Instruments GmbH differentiates by specializing in portable versions of its desktop-grade synthesizer engines.
Smartphone music production software comprises digital audio workstations, synthesizers, samplers, and audio recorders engineered for ARM-based mobile chipsets with touch-optimized interfaces and sub-10 millisecond latency targets; its commercial purpose centers on enabling full composition, arrangement, and mixing workflows without dedicated studio hardware. DAW products lead revenue generation due to their position as the central hub for all other tools, while subscription services within distribution channels capture recurring revenue streams that desktop perpetual licenses rarely match. Amateur musicians represent the deepest addressable pool among end users, though professional producers command the highest per-seat spending on premium feature sets.
FCC guidelines on audio hardware interoperability and GDPR-mandated data handling for cloud-stored projects shape how European developers architect cross-border collaboration features. South Korea's KCC enforces broadcast-quality audio standards that mobile exporters must satisfy for domestic distribution. Stakeholders should monitor how AI-generated content regulations under development in multiple jurisdictions will affect training data legality and royalty attribution for algorithmic composition tools.
Market Dynamics
AI-powered stem separation is compressing production timelines from hours to seconds, forcing incumbents to rebuild their feature roadmaps around real-time audio manipulation rather than static tool libraries.
Growth Catalysts
- Cloud-native collaboration protocols:Real-time project sharing eliminates version-control friction for distributed bedroom producers. South Korea's KCC broadcast-quality mandates accelerate mobile DAW adoption among domestic creators seeking professional-grade output.
- Freemium tier expansion:Zero-cost entry points convert amateur musicians into paid subscribers at 18-month cycles. GDPR-mandated data portability across EU borders reduces friction for cross-border creative teams.
- ARM chipset optimization:Sub-10 millisecond latency targets unlock professional monitoring workflows on consumer smartphones. Independent musicians in Germany leverage this for location-agnostic composition sessions.
Market Restraints
- Input cost volatility in semiconductor fabrication:Advanced neural processing units for on-device AI inference face supply concentration in Taiwan and South Korea foundries.
- Regulatory friction from GDPR Article 17:Right-to-erasure requirements complicate cloud-stored project retention policies for collaborative workflows.
- Technical limitation in analog-to-digital conversion:Smartphone audio interfaces lack the dynamic range of dedicated studio hardware, constraining professional adoption for final mastering stages.
Strategic Opportunities
- Underpenetrated geography in India:TRAI's broadband infrastructure expansion creates first-time smartphone producer cohorts in tier-2 cities.
- Technology convergence of spatial audio and haptic feedback:Immersive mixing interfaces differentiate premium tiers from basic multi-track offerings.
- Distribution innovation through social platform embedding:Creation tools native to short-form video apps bypass traditional app store discovery friction.
Industry Challenges
- Skill gap in AI-assisted composition ethics:Training data legality and royalty attribution require new legal frameworks not yet standardized across jurisdictions.
- Integration complexity with legacy desktop DAWs:Project file format incompatibility forces redundant workflow reconstruction for hybrid producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartphone Music Production Software Market |
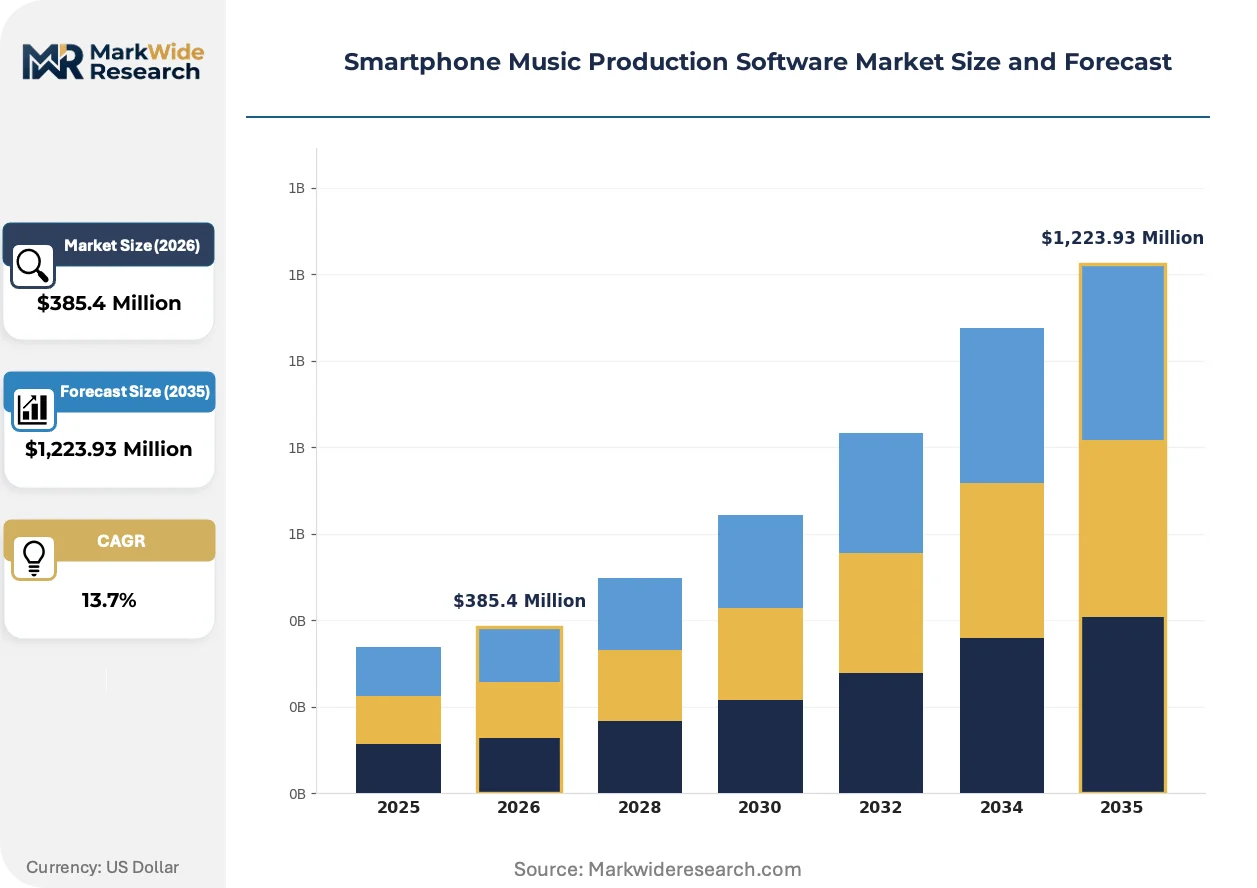
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,223.93 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DAW, Synthesizer, Sampler, Audio Recorder End User: Amateur Musicians, Professional Producers, Students, Educators Feature: Multi-Track Recording, MIDI Support, Virtual Instruments, Audio Effects Distribution Channel: Direct Download, App Store, Subscription Service, Bundled Software |
| Companies Covered | Apple Inc., Roland Corporation, BandLab Technologies, KORG Inc., Image Line Software NV, Steinberg Media Technologies GmbH, Ableton, Soundtrap AB, Native Instruments GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartphone Music Production Software Market Emerging Trajectories
Real-time audio processing architectures are collapsing the boundary between capture and manipulation, enabling composition decisions during recording rather than in post-production.
On-device neural networks for stem separation are electrifying creative workflows by isolating vocals, drums, and instruments without cloud latency. Bedroom producers in the United States adopt these tools within 90 days of release, compressing the traditional demo-to-release cycle from weeks to hours. This capability is electrifying competitive positioning around speed-to-platform rather than fidelity-to-studio.
The EU AI Act's transparency requirements for generative audio tools are reshaping how developers document training data provenance. Algorithmic composition features must now disclose source material catalogs, increasing compliance overhead for European market entrants. German developers respond by segregating EU-specific builds with enhanced attribution logging from global releases.
Subscription unbundling is fragmenting how producers assemble their toolchains, with specialized samplers and synthesizers purchased à la carte rather than through integrated DAW suites. This pattern concentrates most visibly in South Korea, where K-pop trainee producers mix and match single-purpose apps for rapid sonic prototyping. Channel power shifts from platform gatekeepers to influencer-curated workflow recommendations on short-form video platforms.
Smartphone Music Production Software Market Segmentation
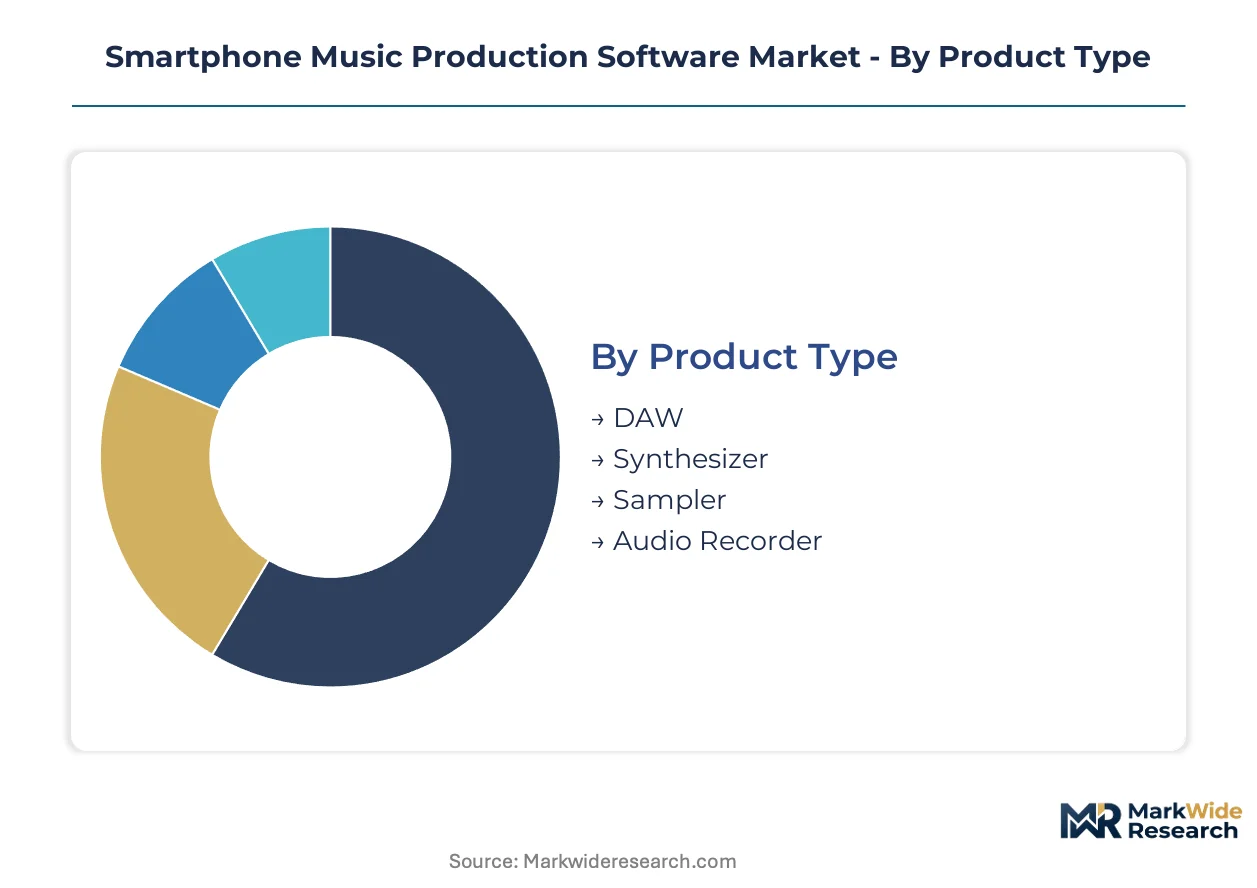
Segmentation in smartphone music production software reveals how capital intensity, user sophistication, and distribution economics split addressable demand. Each dimension exposes different margin structures and competitive moats.
Product Type:
DAW platforms demand the heaviest upfront engineering investment, with multi-year development cycles for touch-optimized audio engines and sub-10 millisecond latency architectures.
- DAW:Centralized composition environments integrating recording, arrangement, and mixing. Professional producers in Germany drive premium tier subscriptions for desktop-grade feature parity on iOS and Android devices.
- Synthesizer:Virtual instrument engines with ARM-optimized oscillators and filter algorithms. South Korean K-pop trainee producers favor modular synth apps for rapid sonic prototyping in mobile-first workflows.
- Sampler:Time-stretching and granular playback tools for drum kits and melodic phrases.
- Audio Recorder:Single-purpose capture utilities with basic editing, often bundled as freemium entry points.
Most installed capacity flows through DAW platforms. Expansion is steepest in Synthesizer applications.
End User:
Revenue per seat varies dramatically across user sophistication tiers, with professionals commanding 8-12x the annual spend of amateurs despite representing a smaller population base.
- Amateur Musicians:Bedroom producers and hobbyists seeking zero-cost entry points with upgrade paths. Independent musicians in the United States convert to paid tiers within 18-month cycles as project complexity demands advanced features.
- Professional Producers:Commercial studios and touring artists requiring broadcast-quality output. FCC guidelines on audio hardware interoperability shape their tool selection for cross-platform project portability.
- Students:Educational licensees accessing discounted or institution-bundled software.
- Educators:Curriculum designers and classroom instructors requiring multi-seat licensing and administrative dashboards.
Volume concentrates in Amateur Musicians. Value capture climbs fastest among Professional Producers.
Feature:
Technical differentiation now centers on real-time processing capabilities rather than static tool libraries, reshaping R&D allocation across development teams.
- Multi-Track Recording:Simultaneous capture of 8-32 audio sources with non-destructive editing. GDPR-mandated data handling requirements complicate cloud-synced session storage for European users of these features.
- MIDI Support:Hardware controller integration and sequencer programming for virtual instruments. German developers prioritize low-latency Bluetooth LE implementations for location-agnostic composition sessions.
- Virtual Instruments:Sample-based and synthesized sound libraries with touch-optimized performance interfaces.
- Audio Effects:Real-time processing chains including EQ, compression, reverb, and spatial audio tools.
Feature development investment clusters around Multi-Track Recording. MIDI Support is gaining share fastest among hardware-centric producers.
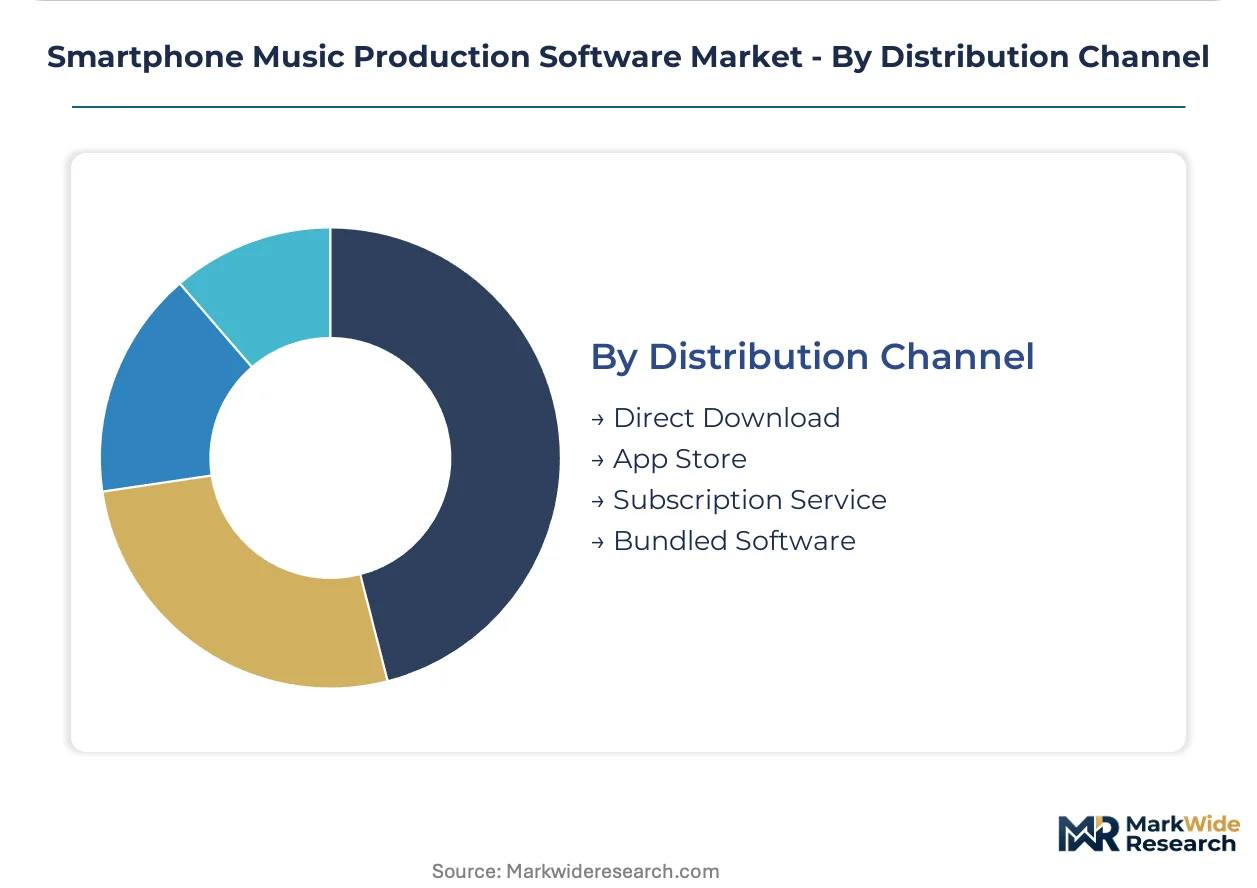
Distribution Channel:
Channel economics determine customer acquisition costs and lifetime value trajectories, with direct relationships offering margin advantages over platform-mediated discovery.
- Direct Download:Developer-hosted distribution bypassing app store commissions. Native Instruments GmbH leverages this channel for portable synthesizer engine sales to professional users seeking seamless desktop-mobile project continuity.
- App Store:Apple and Google marketplace placement with built-in payment infrastructure. BandLab Technologies exploits social-first discovery within these platforms to merge creation with community sharing.
- Subscription Service:Recurring revenue models with tiered feature access and cloud storage.
- Bundled Software:Pre-installed or hardware-packaged offerings tied to smartphone OEM partnerships.
Transaction volume runs highest through App Store channels. Direct Download is expanding most quickly among established desktop software vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile music production software first achieved commercial scale in Japan and the United States during the early 2010s, when touchscreen interfaces and ARM processors crossed minimum viability thresholds for low-latency audio processing. This dual-origin legacy continues to shape how demand concentrates across developed markets today.
United States
Independent musicians in Los Angeles and Austin drive freemium-to-premium conversion cycles, with bedroom producers upgrading to paid tiers within 18 months of initial adoption. FCC guidelines on audio hardware interoperability shape cross-platform project portability for professional users. Seattle's developer cluster anchors cloud-native collaboration protocol innovation.
Germany
Professional producers in Berlin and Hamburg command the highest per-seat spending on premium feature sets, seeking desktop-grade parity on mobile devices. GDPR-mandated data handling requirements complicate cloud-stored project architectures for European developers. Bavaria's audio engineering institutes supply specialized talent for low-latency Bluetooth LE implementations.
South Korea
K-pop trainee producers in Seoul mix and match single-purpose apps for rapid sonic prototyping, fragmenting traditional DAW bundling patterns. KCC broadcast-quality audio standards accelerate mobile DAW adoption among domestic creators. Busan's semiconductor fabrication base supplies neural processing units for on-device AI stem separation.
Japan
Hardware-software integration traditions in Tokyo and Osaka sustain demand for MIDI controller compatibility and tactile performance interfaces. METI standards for consumer electronics interoperability influence mobile audio peripheral design. Nagoya's industrial automation heritage feeds precision manufacturing for smartphone audio interfaces.
United Kingdom
London's electronic music producers leverage subscription unbundling to assemble specialized toolchains from multiple vendors. EU AI Act transparency requirements for generative audio tools reshape how developers document training data provenance. Manchester's emerging tech cluster incubates social-first distribution models merging creation with community sharing.
Smartphone Music Production Software Market Vendor Landscape
Premium-margin players sit above commodity-margin players across feature depth and ecosystem integration, creating a tiered structure where subscription pricing separates professional-grade workflows from freemium entry points. The vendor base spans integrated platform operators, specialized instrument developers, and social-native distribution services. Three archetypes dominate: desktop heritage vendors porting established engines to mobile, mobile-native platforms built around cloud collaboration, and hardware manufacturers extending physical product ecosystems into software. Consolidation pressure operates through strategic partnerships for cross-platform project continuity and technology licensing for on-device AI inference.
Within the desktop heritage tier, Apple Inc. and Steinberg Media Technologies GmbH occupy positions defined by ecosystem control and professional user retention. BandLab Technologies exemplifies the mobile-native archetype through social-first distribution architecture. Native Instruments GmbH anchors the specialized instrument developer category with portable synthesizer engine expertise.
| Leading Market Players |
|---|
| Apple Inc. |
| Roland Corporation |
| BandLab Technologies |
| KORG Inc. |
| Image Line Software NV |
| Steinberg Media Technologies GmbH |
| Ableton |
| Soundtrap AB |
| Native Instruments GmbH |
| Others |
Supply Flow & Price Mechanics
Captive control over neural processing unit fabrication in Taiwan and South Korea anchors both supply security and tiered subscription pricing power for mobile DAW vendors. This integration pattern lets premium-tier developers absorb foundry volatility while locking freemium competitors into spot-market component costs.
Pricing Analysis
Freemium-to-premium subscription tiers stratify across basic multi-track, advanced virtual instrument, and professional cloud-collaboration levels. Price differentiation hinges on latency performance certification and AI feature depth. Cost compression in the amateur tier is intensifying because BandLab Technologies and social-native platforms subsidize entry points through ad-supported models. Independent musicians show highest price sensitivity, while Berlin-based professional producers accept 8-12x premiums for desktop-grade parity.
Supply Chain Analysis
CE marking and FCC interoperability certification gating constrains which ARM-optimized audio engines reach commercial distribution. Foundry capacity concentrates in Taiwan, South Korea, and the United States for neural processing units. Component sourcing draws from Japanese precision manufacturers for audio codecs, German sensor suppliers for haptic feedback modules, and Chinese OEMs for consumer smartphone chassis. Single-source vulnerability in Taiwan's TSMC advanced node production threatens on-device AI inference roadmaps. Distribution runs through Apple and Google app store marketplaces with 15-30% commission structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's training data transparency mandates compound compliance overhead into competitive moats, favoring incumbents with dedicated European legal infrastructure. This regulatory compounding accelerates demand for segregated EU-specific software builds with enhanced attribution logging.
For Market Incumbents: Deepen backward integration into on-device AI inference silicon through strategic foundry partnerships in Busan and Hsinchu. Lock in multi-year capacity reservations before neural processing unit allocation tightens. Prioritize GDPR Article 17-compliant cloud architectures to neutralize right-to-erasure friction against emerging social-native competitors.
For New Entrants and Emerging Players: Begin with spatial audio-haptic convergence as a premium-tier wedge against established DAW bundling. Target India's tier-2 cities where TRAI broadband expansion creates first-time smartphone producer cohorts with minimal legacy desktop DAW loyalty. Embed creation tools directly into short-form video platforms to bypass app store discovery costs.
For Investors and Strategic Acquirers: Roll-up economics work for specialized synthesizer engine developers because subscription unbundling fragments user toolchains and creates captive acquisition targets. Five-to-ten year viability hinges on AI-assisted composition legality standardization across jurisdictions. Monitor EU AI Act enforcement patterns as the inflection signal for European market access costs.
| Strategic Initiative | Industry Significance |
|---|---|
| On-Device AI Inference Optimization | Sub-10 millisecond latency targets unlock professional monitoring workflows on consumer smartphones in Germany. |
| Cloud-Native Collaboration Protocol Development | Real-time project sharing eliminates version-control friction for distributed bedroom producers in Los Angeles. |
| Spatial Audio-Haptic Feedback Integration | Immersive mixing interfaces differentiate premium tiers from basic multi-track offerings in Seoul. |
| Social Platform Embedding | Creation tools native to short-form video apps bypass traditional app store discovery friction in London. |
| GDPR-Compliant Cloud Architecture Segregation | EU-specific builds with enhanced attribution logging satisfy EU AI Act transparency requirements for generative audio tools. |
Methodological Framework
Bottom-up amateur musician and professional producer modeling reconciled against top-down ARM chipset and cloud infrastructure tracking forms the analytical core. Primary interviews with mobile DAW product managers, audio engineering institute curriculum designers, K-pop trainee producers, and independent bedroom musicians combined with secondary validation from SEC filings, App Store analytics disclosures, and EU regulatory filings. FCC guidelines, GDPR mandates, and KCC broadcast-quality standards provided cross-jurisdictional compliance baselines.
Historical adoption curves for freemium-to-premium conversion cycles informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, end user sophistication tier, feature depth, and distribution channel economics. CAGRs derived from smartphone hardware refresh cycles, AI feature penetration rates, and cloud storage cost trajectories. On-device neural network capability roadmaps and social platform embedding velocity served as technology-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced smartphone OEM bundling partnerships and sudden foundry allocation shocks. Forecasts reflect assumptions about sustained broadband infrastructure expansion in target geographies and stable regulatory interpretation of AI training data legality. A model refresh is warranted upon material change in EU AI Act enforcement patterns or Taiwan semiconductor export restrictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Performing Arts Software Market
Software & Services
Global OKR Software Market
Software & Services
Bankruptcy Software Market
Software & Services
Global Driving School Software Market
Software & Services
Global Guidewire Market
Software & Services
Payroll and HR Software Market
Software & Services
Deck Design Software Market
Software & Services
Medical Equipment Repair Software Market
Software & Services
Global Molecular Modeling Software for Chemistry Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
North America Saas-Based Expense Management Market
Software & Services
Online Lottery Software Market
Software & Services
Specification Management Software Market
Software & Services
Packaged Software Market
Software & Services
Lawn Care Software Market
Software & Services
Talent Management Software Market