
 Sales Force Automation Software Market | 2026-2036
Sales Force Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Sales Force Automation Software Market Intelligence
The capability gap between AI-native platforms and legacy CRM extensions is bifurcating competitive dynamics in sales force automation. Gong leverages proprietary conversation intelligence to anchor premium pricing in enterprise accounts. Salesforce Sales Cloud sustains dominant market presence through extensive third-party integration ecosystems. HubSpot Sales Hub competes aggressively on inbound methodology alignment and freemium user acquisition.
Sales force automation software encompasses applications that streamline prospecting, pipeline management, forecasting, and revenue operations through workflow automation, predictive analytics, and native mobile interfaces. Cloud-based deployments lead segment share as enterprises prioritize elastic scalability and reduced infrastructure overhead, while hybrid architectures gain traction among regulated financial services firms requiring partitioned data sovereignty. The SMB customer type represents the fastest-expanding addressable pool, though enterprise accounts retain disproportionate margin concentration due to multi-module subscriptions and dedicated implementation services.
The US SEC's cybersecurity disclosure rules and Europe's GDPR framework compel vendors to engineer granular data residency controls and audit-ready access logging, reshaping product roadmaps and procurement evaluation criteria. ISO 27001 certification has become a baseline qualifier for RFP shortlists across healthcare and financial services verticals. Stakeholders must weigh the trade-off between AI feature velocity and compliance architecture rigor when selecting platform partners for long-term deployment.
Market Dynamics
The bifurcation between AI-native platforms and legacy CRM extensions is compressing vendor margins while elevating buyer expectations for predictive analytics and automated coaching workflows.
Growth Catalysts
- GDPR data residency mandates:European enterprises must replace on-premises stacks with cloud architectures featuring granular sovereignty controls, accelerating replacement cycles among regulated pharmaceutical and financial services firms.
- AI-powered conversation intelligence:Enterprise sales organizations deploy real-time coaching modules that analyze call transcripts and prescribe behavioral adjustments, embedding automation into daily rep workflows.
- SEC cybersecurity disclosure rules:US-listed companies face audit-ready access logging requirements that favor vendors with ISO 27001 certification and native compliance tooling.
Market Restraints
- Cloud infrastructure cost volatility:Elastic compute and storage pricing from hyperscalers compresses SaaS gross margins, particularly for vendors serving price-sensitive SMB segments.
- Technical debt in legacy CRM migrations:Custom field mappings, workflow automations, and third-party integrations create multi-quarter implementation timelines that delay revenue recognition.
- Substitution by bundled ERP modules:SAP and Oracle embed sales force automation capabilities within broader enterprise suites, capturing procurement budgets through consolidated vendor relationships.
Strategic Opportunities
- Underpenetrated mid-market manufacturing:Industrial distributors in Germany and Japan lack purpose-built SFA tools, presenting white space for verticalized solutions with native ERP connectors.
- EU AI Act compliance tooling:Automated documentation of algorithmic decision-making and bias auditing features create premium pricing tiers for vendors serving European life sciences accounts.
- Mobile-first field sales enablement:Native offline functionality and geolocation-aware routing address the connectivity constraints of emerging market field forces in Brazil and India.
Industry Challenges
- Revenue operations talent scarcity:Organizations struggle to hire professionals fluent in both Salesforce administration and Python-based forecasting model deployment.
- Cross-border data synchronization complexity:Multi-tenant architectures must maintain referential integrity across GDPR-governed EU instances and SEC-audited US instances without latency degradation.
- API versioning and integration maintenance:Frequent platform updates from ecosystem partners break custom connectors, requiring dedicated engineering resources for continuous remediation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sales Force Automation Software Market |
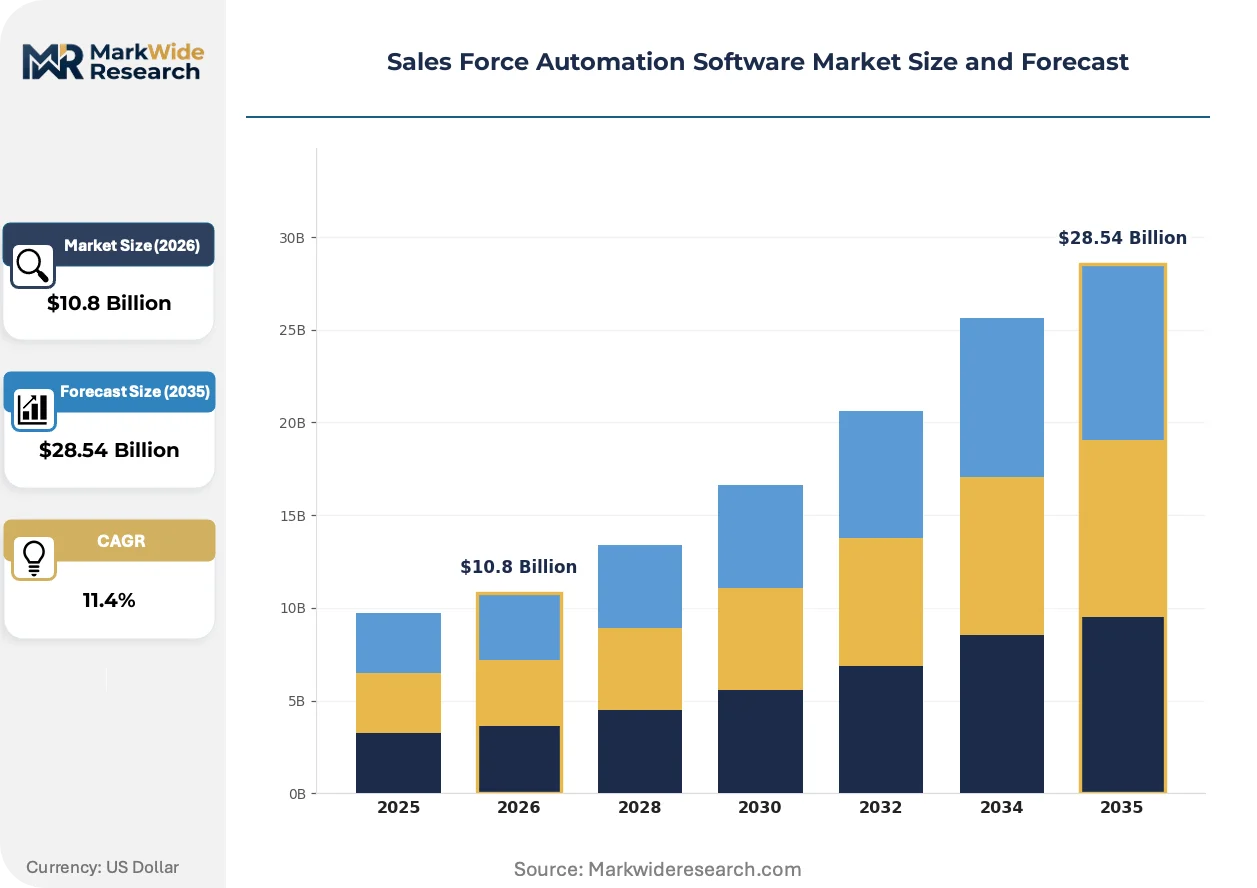
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $28.54 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premises, Hybrid, Mobile Customer Type: SMBs, Enterprises, Startups, Freelancers Deployment: Public Cloud, Private Cloud, Multi-tenancy, Dedicated Industry Vertical: Retail, Manufacturing, Financial Services, Healthcare |
| Companies Covered | Gong, ZoomInfo Sales, Salesforce Sales Cloud, Consensus, Zendesk, HubSpot Sales Hub, PandaDoc, Botree Software, Pipedrive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sales Force Automation Software Market Strategic Shifts & Innovations
Generative AI is compressing the traditional sales enablement stack by automating content personalization, call preparation, and follow-up drafting at scale.
Large language model integration is fragmenting the competitive landscape between horizontal CRM platforms and specialized conversation intelligence vendors. Enterprise procurement teams evaluate whether embedded AI features from incumbent providers suffice or whether best-of-breed point solutions deliver superior inference quality. The technology is fragmenting vendor market positions by elevating data moat and model training differentiation above traditional integration breadth.
The EU AI Act's risk classification framework imposes documentation and human oversight requirements on high-risk AI applications including automated sales scoring and compensation optimization. Vendors must engineer explainability dashboards and audit trails that satisfy notified body assessments before deployment in European pharmaceutical accounts. Life sciences sales operations teams in France and Germany are prioritizing vendors with pre-certified conformity assessment pathways.
Buyer committees now mandate outcome-based pricing validation during SFA procurement, replacing seat-based subscription models with metrics tied to pipeline velocity improvement or forecast accuracy gains. Vendor sales cycles elongate as finance and procurement stakeholders demand pilot programs with defined success criteria. This behavioral shift concentrates most acutely among US enterprise healthcare providers navigating margin pressure from Medicare reimbursement compression.
Sales Force Automation Software Market Segmentation
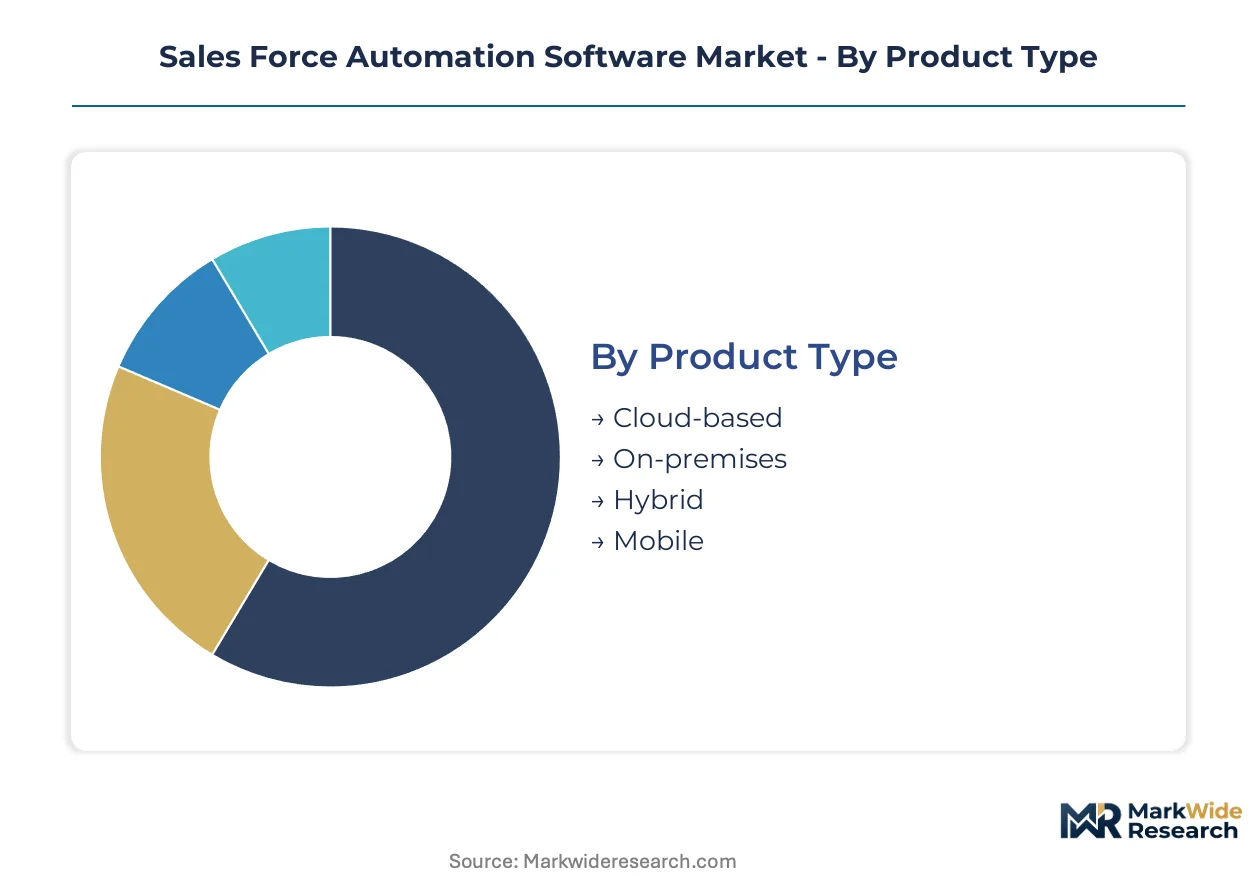
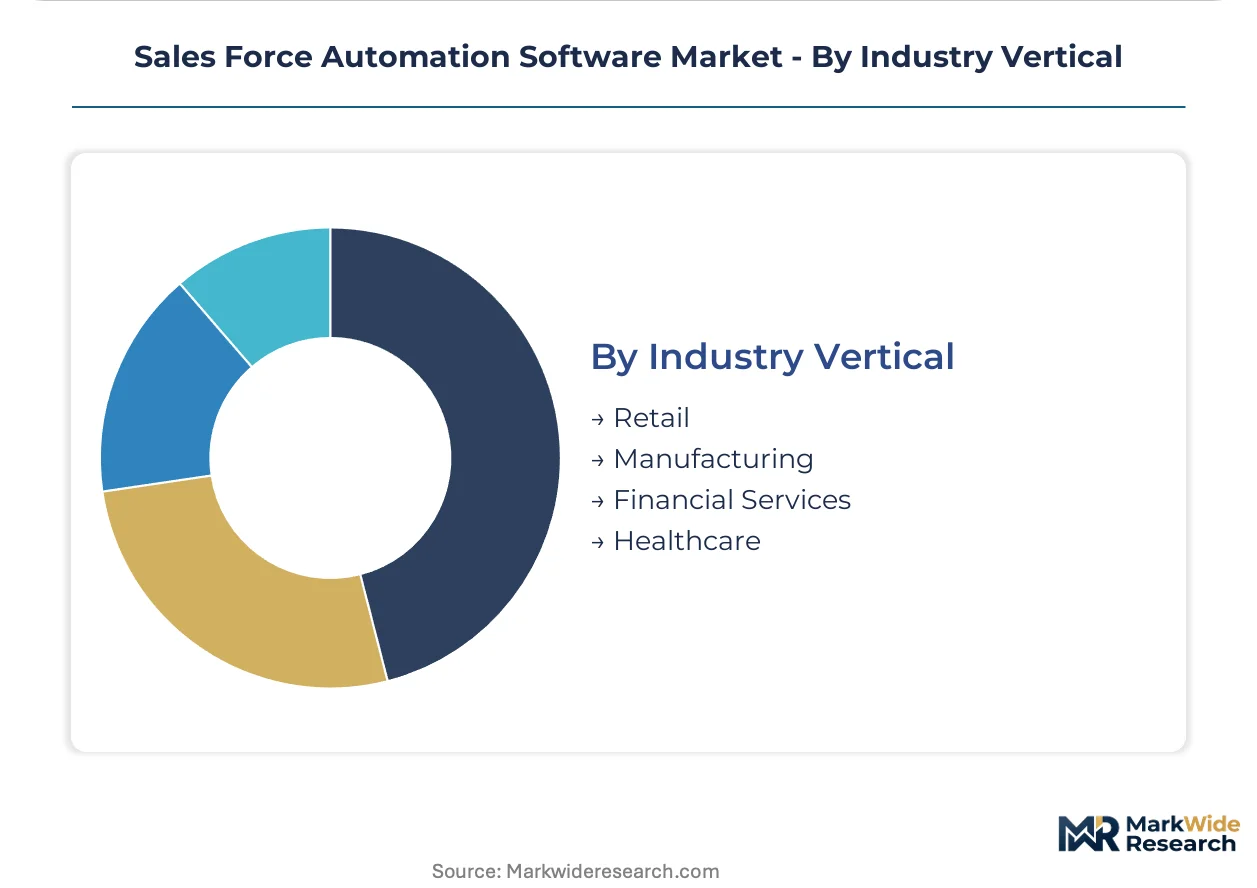
Sales force automation software procurement diverges sharply across organizational scale and technical architecture, with compliance requirements and integration complexity dictating platform selection. Vendors must engineer distinct value propositions for each segment cluster to capture margin concentration and defend against substitution.
Product Type:
Margin pools concentrate in cloud-native architectures that command premium subscription tiers through elastic scalability and reduced infrastructure overhead.
- Cloud-based:Multi-tenant SaaS architectures deliver automatic feature updates and API extensibility without client-side maintenance. Pharmaceutical sales teams in Germany and the United States prioritize these deployments to satisfy GDPR data residency controls and SEC audit logging mandates simultaneously.
- On-premises:Legacy server installations persist in defense contracting and classified government accounts where air-gapped networks are mandatory. These deployments carry elevated professional services margins but face accelerating replacement cycles as vendors sunset support for older codebases.
- Hybrid:Partitioned architectures route sensitive customer data through private infrastructure while leveraging public cloud for analytics workloads. Financial services firms in Switzerland and Singapore adopt this model to reconcile regulatory sovereignty with AI feature velocity.
- Mobile:Native iOS and Android applications with offline synchronization address field sales connectivity constraints. Emerging market distributors in Brazil and India drive adoption where cellular coverage remains intermittent.
The dominant share belongs to cloud-based deployments, while hybrid architectures are gaining share fastest as regulated enterprises seek architectural compromise.
Customer Type:
Revenue concentration tilts toward enterprise accounts despite their smaller absolute count, reflecting multi-module subscriptions and dedicated implementation services.
- SMBs:Organizations with under 500 employees gravitate toward freemium tiers and self-service onboarding to minimize procurement friction. Life sciences startups in Boston and Basel cluster here, upgrading to paid tiers only when pipeline volume necessitates forecasting automation.
- Enterprises:Global sales organizations with 10,000+ seats negotiate custom SLAs, dedicated customer success managers, and private model training for AI features. These accounts generate disproportionate margin through professional services attach rates exceeding 40% of subscription value.
- Startups:Venture-backed companies prioritize rapid deployment and CRM integration over customization depth. Y Combinator and Techstars portfolio companies in San Francisco and London represent concentrated demand pockets.
- Freelancers:Individual contributors and micro-agencies utilize basic contact management and proposal generation tools. This segment exhibits highest churn and lowest lifetime value, prompting most vendors to deprioritize dedicated feature roadmaps.
Enterprise accounts retain the dominant revenue share, though SMBs are expanding most quickly as vendor self-service capabilities mature.
Deployment:
Architecture choices directly determine compliance posture and total cost of ownership across multi-jurisdictional sales operations.
- Public Cloud:Shared infrastructure from AWS, Azure, or Google Cloud delivers lowest unit economics for standardized workloads. US healthcare providers facing Medicare reimbursement compression favor this model to minimize IT overhead.
- Private Cloud:Single-tenant environments with dedicated compute resources address data sovereignty requirements in France and Germany under CNIL and BfDI guidance. These deployments carry 30-50% pricing premiums over public alternatives.
- Multi-tenancy:Logical isolation within shared physical infrastructure balances cost efficiency with customization depth. This architecture dominates mid-market manufacturing in Japan and South Korea.
- Dedicated:Physically segregated hardware reserved for single clients serves central bank and sovereign wealth fund requirements. Swiss and UAE financial regulators mandate this tier for certain transaction data categories.
Public cloud holds the dominant installation base, while private cloud is climbing the fastest as European data localization requirements harden.
Industry Vertical:
Vertical-specific compliance workflows and sales cycle characteristics fragment platform requirements across end-use sectors.
- Retail:Omnichannel order management and seasonal demand forecasting dominate functional requirements. Fast-fashion distributors in Italy and Spain prioritize real-time inventory synchronization across digital and physical channels.
- Manufacturing:Complex configure-price-quote engines and distributor portal integration characterize demand. Industrial equipment vendors in Germany and Japan require native ERP connectors to SAP and Oracle systems.
- Financial Services:Audit trails, suitability documentation, and compensation disclosure automation are mandatory. SEC-registered broker-dealers and FCA-regulated wealth managers in London and New York drive specification intensity.
- Healthcare:HIPAA-compliant access controls and Sunshine Act reporting integration shape procurement criteria. Hospital systems and medical device manufacturers in the United States concentrate investment here.
Financial services commands the dominant vertical share, with healthcare showing the steepest expansion trajectory as provider margin pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity, absorbing premium tiers for AI-native coaching modules, while emerging market procurement in Brazil and India remains acutely cost-sensitive. European enterprises occupy the middle ground, trading feature depth for compliance architecture rigor.
United States
Enterprise healthcare providers and pharmaceutical sales teams drive demand for predictive forecasting and conversation intelligence. The SEC's cybersecurity disclosure rules mandate audit-ready access logging, elevating ISO 27001 certification to a baseline procurement qualifier. Boston's life sciences cluster and San Francisco's SaaS corridor concentrate vendor development and early-adopter deployment.
Germany
Industrial manufacturing distributors seek native ERP connectors to SAP systems alongside configure-price-quote automation. The BfDI enforces strict data localization guidance under GDPR, compelling private cloud or hybrid architectures. Munich and Stuttgart host dense concentrations of automotive and machinery exporters piloting AI-powered sales coaching.
United Kingdom
FCA-regulated wealth managers and insurance brokers prioritize audit trails and suitability documentation automation. The Information Commissioner's Office enforces GDPR-aligned data residency requirements for cross-border sales operations. London's financial services hub dominates procurement volume, with Manchester emerging as a secondary fintech sales operations center.
Japan
Mid-market manufacturers in industrial equipment and electronics components adopt multi-tenant SaaS for distributor portal integration. METI guidelines on data governance shape vendor selection criteria for enterprises with EU export exposure. Osaka's machinery belt and Nagoya's automotive supply chain cluster represent concentrated demand pockets for mobile-first field sales tools.
Brazil
Emerging market distributors in agricultural inputs and industrial supplies demand offline-native mobile applications for intermittent connectivity environments. The country's national data protection authority enforces localization requirements that favor regional cloud infrastructure partners. São Paulo's commercial hub and Rio Grande do Sul's manufacturing corridor lead adoption of geolocation-aware routing and field force management modules.
Sales Force Automation Software Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with AI-native conversation intelligence vendors commanding premium pricing while horizontal CRM incumbents compete on integration breadth and seat-based economics. The market structure bifurcates between specialized point solutions and platform ecosystems, creating tiered procurement evaluation frameworks. Three archetypes dominate: AI-native challengers with proprietary data moats, incumbent CRM platforms with extensive third-party marketplaces, and verticalized specialists serving regulated industries. Consolidation pressure manifests through strategic acquisitions of conversation intelligence startups and geographic expansion via localized compliance engineering.
Within the AI-native tier, Gong exemplifies premium positioning through conversation intelligence specialization, while Salesforce Sales Cloud anchors the platform-ecosystem archetype with extensive integration breadth. HubSpot Sales Hub occupies the inbound-methodology-aligned position, competing aggressively on freemium user acquisition and self-service onboarding velocity.
| Leading Market Players |
|---|
| Gong |
| ZoomInfo Sales |
| Salesforce Sales Cloud |
| Consensus |
| Zendesk |
| HubSpot Sales Hub |
| PandaDoc |
| Botree Software |
| Pipedrive |
| Others |
Cost & Logistics Intelligence
Ninety-day implementation timelines for enterprise CRM migrations compress pricing power for vendors serving regulated healthcare and pharmaceutical accounts in the United States and Germany. Extended professional services engagements anchor lifetime value calculations, allowing AI-native platforms to command premium tiers while horizontal incumbents compete on seat-based economics.
Pricing Analysis
Professional services and dedicated customer success management drive lifetime value concentration in enterprise accounts. SaaS subscription tiers stratify across premium AI-native coaching modules, standard workflow automation, and economy self-service tiers for SMB segments. Price differentiation rests on ISO 27001 certification status and vertical-specific compliance tooling depth. Cost compression in the SMB tier intensifies because hyperscaler infrastructure pricing volatility squeezes gross margins. Freelancers and early-stage startups exhibit highest price sensitivity, while Fortune 500 healthcare providers demonstrate lowest elasticity for predictive forecasting capabilities.
Supply Chain Analysis
Extended lead times for custom AI model training and dedicated instance provisioning characterize vendor-side inventory dynamics. Cloud infrastructure supply concentrates in the United States, Ireland, and Singapore, where hyperscaler regions offer GDPR-aligned data residency controls. Raw material dependencies include GPU compute clusters, proprietary conversation intelligence training data, and API ecosystem partner integrations. Single-source vulnerability runs through NVIDIA hardware allocation for model inference workloads. Distribution runs through direct enterprise sales teams with professional services attach rates exceeding 40 percent of contract value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sales force automation software sits in early-cycle expansion as AI-powered coaching modules penetrate pharmaceutical and life sciences verticals previously served by legacy CRM extensions. Enterprise procurement committees now mandate pilot programs with defined outcome metrics, accelerating replacement of on-premises stacks.
For Market Incumbents: Shield dominant market position by deepening proprietary conversation intelligence data moats and accelerating ISO 27701 privacy certification investments. The threat of AI-native challengers with superior inference quality demands defensive consolidation of third-party integration ecosystems. Vertical integration into dedicated model training infrastructure for European life sciences accounts preserves margin concentration.
For New Entrants and Emerging Players: Lead with white-space targeting of mid-market manufacturing distributors in Germany and Japan lacking native SAP connectors. Underpenetrated industrial equipment vendors in Osaka and Stuttgart represent the most accessible segment for purpose-built configure-price-quote automation. A mobile-first field sales enablement angle with offline-native functionality addresses connectivity constraints in Brazilian agricultural distribution.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-anchored platform consolidation play because regulatory fragmentation between SEC cybersecurity rules and EU AI Act requirements favors vendors with pre-certified conformity pathways. Acquisition targets should exhibit verticalized AI feature depth in healthcare or financial services. The signal to watch is procurement committee composition shifting from IT-led to finance-led evaluation criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded conversation intelligence modules in Salesforce ecosystems capture pharmaceutical procurement budgets. |
| Acquisition of Specialist Firm | Conversation intelligence startups with proprietary transcript databases command premium valuations from horizontal incumbents. |
| Geographic Expansion | Localized compliance engineering for BfDI data sovereignty requirements opens German industrial manufacturing accounts. |
| Product Launch | EU AI Act explainability dashboards create premium pricing tiers for European life sciences sales operations. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure accelerate GDPR-compliant instance provisioning for regulated financial services. |
Research Approach
Initial hypotheses were tested against primary input from sales operations executives, CRM implementation specialists, pharmaceutical IT procurement officers, and revenue operations leaders and refined through secondary validation. Stakeholder interviews drew from 15-20 vendor-side product managers and enterprise buyer committees across Boston life sciences clusters and London financial services hubs. Secondary sources encompassed SEC cybersecurity disclosure filings, EDPB guidance documents on GDPR data residency, EU AI Act implementation timelines, and hyperscaler infrastructure expansion announcements. Bottom-up segment sizing triangulated against top-down market aggregation across deployment models and vertical adoption patterns.
Variance decomposition across the projection horizon isolated adoption curve assumptions, pricing elasticity parameters, and replacement cycle duration as primary uncertainty sources. Segmentation dimensions modeled encompassed cloud-native versus hybrid architectures, enterprise versus SMB organization scale, healthcare versus financial services verticals, and regional regulatory cluster alignment. CAGRs were derived through logistic diffusion modeling of AI feature penetration rates applied to baseline subscription revenue pools. Industry-specific forecast inputs included pharmaceutical sales force headcount projections and Medicare reimbursement compression trajectories affecting healthcare provider IT budgets.
The analysis sits within stated boundaries; outcomes outside sustained cloud migration mandates or accelerated EU AI Act enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding enterprise procurement committee behavior and vendor certification achievement rates. Regulatory fragmentation, hyperscaler pricing volatility, and talent scarcity in revenue operations roles constitute primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Bankruptcy Software Market
Software & Services
Global Wedding Invitations Software Market
Software & Services
Personal Budgeting Software Market
Software & Services
Global Florist Software Market
Software & Services
3D Animation Production Software Market
Software & Services
Global Core Banking Software Market
Software & Services
Strategy Management Software Market
Software & Services
Global Legal Case Management Software Market
Software & Services
Construction Software Market
Software & Services
United Kingdom HR Payroll Software Market
Software & Services
Global Contract Management Software Market
Software & Services
3D Printing Medical Device Software Market
Software & Services
Pet Tracking Software Market
Software & Services
Anti-Plagiarism Software Market
Software & Services
Media Planning Software Market
Software & Services
Disk Space Analyzer Software Market