
 Course Authoring Software Market | 2026-2036
Course Authoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Course Authoring Software Market Outlook
Subscription-based financing is reshaping competitive access in course authoring software by lowering upfront barriers for mid-sized training providers. Articulate 360 leverages its extensive template library to dominate the North American corporate segment. dominKnow anchors its position through strong multi-language localization capabilities for enterprise clients. Elucidat competes by specializing in collaborative authoring workflows that reduce production cycles for distributed teams.
Course authoring software comprises digital tools that enable instructional designers and subject-matter experts to create, edit, and package structured learning content without deep programming expertise, typically supporting SCORM, xAPI, and HTML5 output standards for cross-platform compatibility. Cloud-based tools lead product-type adoption due to real-time collaboration and reduced IT overhead, while subscription-based delivery models capture the fastest growth as organizations shift from perpetual licenses to operational expenditure structures. Corporates represent the deepest margin pool among end users, driven by compliance training mandates and measurable ROI requirements for workforce development programs.
The EU AI Act and GDPR shape European product roadmaps by mandating algorithmic transparency and learner data protection in AI-assisted authoring features. The US Department of Education and FCC influence accessibility standards through Section 508 and WCAG enforcement that determines federal procurement eligibility. Stakeholders must monitor how evolving interoperability requirements between authoring platforms and learning management systems will determine vendor consolidation patterns and enterprise switching costs.
Market Dynamics
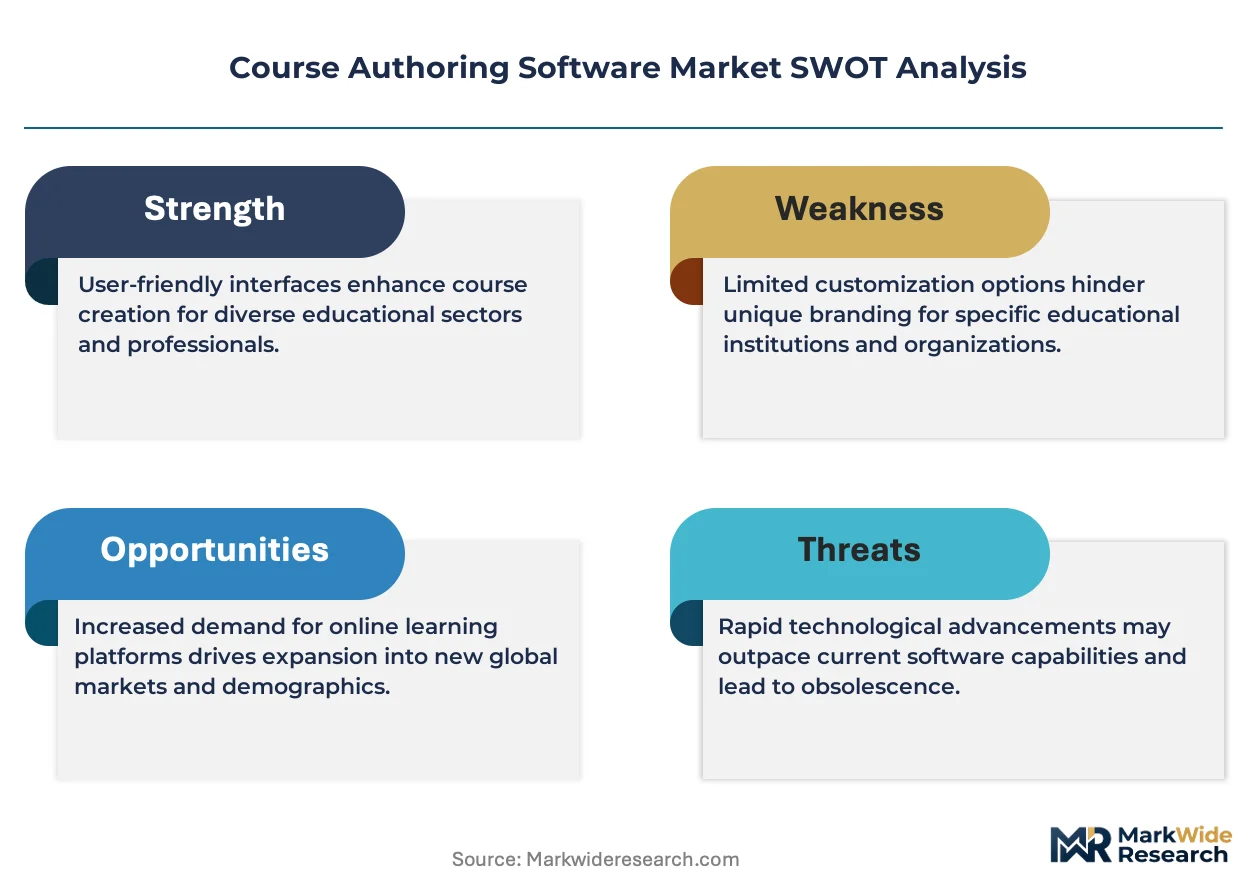
Cloud-based authoring platforms are compressing production cycles and redistributing competitive advantage toward vendors with real-time collaboration infrastructure. The EU AI Act and GDPR compliance mandates are forcing architectural redesigns of AI-assisted content generation tools.
Growth Catalysts
- GDPR Article 17 data erasure mandates:European enterprises are procuring authoring suites with native learner data lifecycle management to avoid regulatory penalties.
- SCORM-to-xAPI migration:Corporate L&D departments are replacing legacy tracking standards to capture granular competency analytics across mobile and VR modalities.
- Japan's workforce digitization targets:METI-backed reskilling programs are accelerating public-sector procurement of multi-language authoring infrastructure.
Market Restraints
- Cloud infrastructure cost volatility:AWS and Azure pricing fluctuations are squeezing margins for SaaS authoring vendors operating on fixed subscription tiers.
- EU AI Act algorithmic transparency requirements:Automated content recommendation engines face mandatory explainability audits that extend development timelines.
- Open-source LRS alternatives:Free Learning Record Store implementations are displacing commercial xAPI hosting revenue for mid-market authoring platforms.
Strategic Opportunities
- Germany's Industrie 4.0 training mandates:Manufacturing consortiums are funding custom authoring toolchains for shop-floor safety simulation content.
- AI-human collaborative authoring:Natural language generation paired with human-in-the-loop review workflows are opening premium pricing tiers for compliance-heavy sectors.
- Mobile-first microlearning formats:Frontline worker training programs in the United States are bypassing desktop-centric legacy tools entirely.
Industry Challenges
- Instructional design talent scarcity:The gap between pedagogical expertise and technical platform proficiency is extending client onboarding cycles.
- WCAG 2.2 accessibility retrofit costs:Legacy content libraries require expensive remediation to maintain federal procurement eligibility under Section 508.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Course Authoring Software Market |
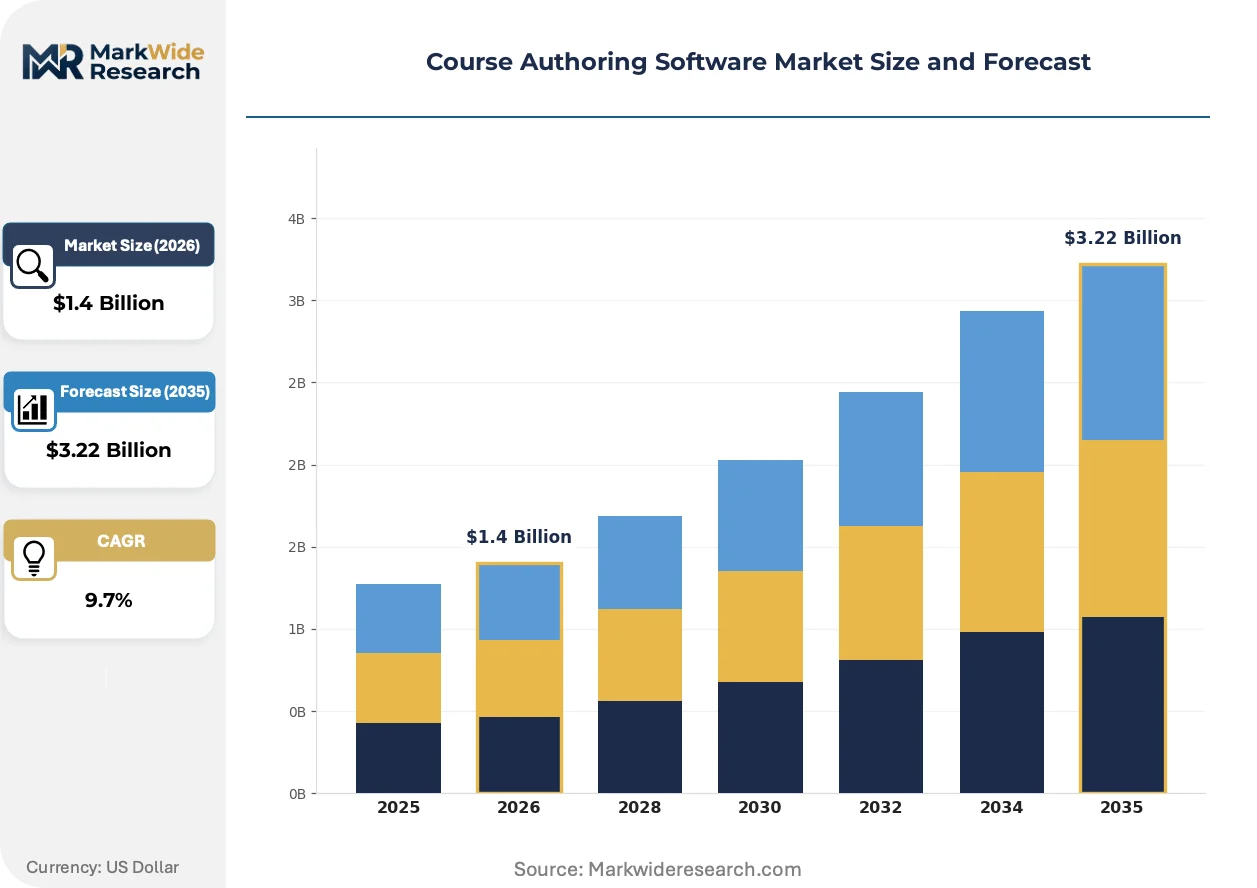
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.22 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Software, Cloud-Based Tools, Mobile Applications, Integration Software Delivery Model: On-Premise, Subscription-Based, Perpetual License, Freemium End User: Educational Institutions, Corporates, Freelancers, Training Providers Feature: Interactive Content, LMS Integration, Video Support, Analytics |
| Companies Covered | iSpring Suite, dominKnow, Articulate 360, Tovuti LMS, Gomo Learning, Elucidat, Lectora, Easygenerator, Adobe Captivate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Course Authoring Software Market Strategic Shifts
Generative AI capabilities are hybridizing with traditional template-based workflows, creating new product categories that blur the boundary between automated and human-directed content creation. Vendors are racing to embed governance layers that satisfy emerging regulatory scrutiny.
AI-assisted content generation is hybridizing rule-based instructional design with probabilistic language models. Fortune 500 L&D teams are piloting these tools for rapid compliance course updates. The technology is hybridizing production economics by collapsing weeks of scripting and asset creation into hours.
The EU AI Act's risk-based classification system is mandating conformity assessments for AI features that personalize learning pathways. Vendors must document training data provenance and bias testing protocols. Enterprise buyers in Germany and France are prioritizing platforms with pre-certified algorithmic transparency modules.
Subscription-to-usage hybrid pricing is displacing pure seat-based models as buyers demand cost alignment with actual content consumption. Mid-sized training providers are negotiating metered contracts tied to learner completions rather than author licenses. This shift is most visible in the United States, where procurement teams face pressure to demonstrate training ROI through granular engagement metrics.
Course Authoring Software Market Segmentation
Segmentation reveals how procurement priorities diverge across technical infrastructure, commercial models, and pedagogical requirements. Understanding these fault lines exposes where vendors can defend margin and where commoditization pressures concentrate.
Product Type:
Deployment architecture determines collaboration capabilities, IT overhead burdens, and integration complexity for instructional design teams.
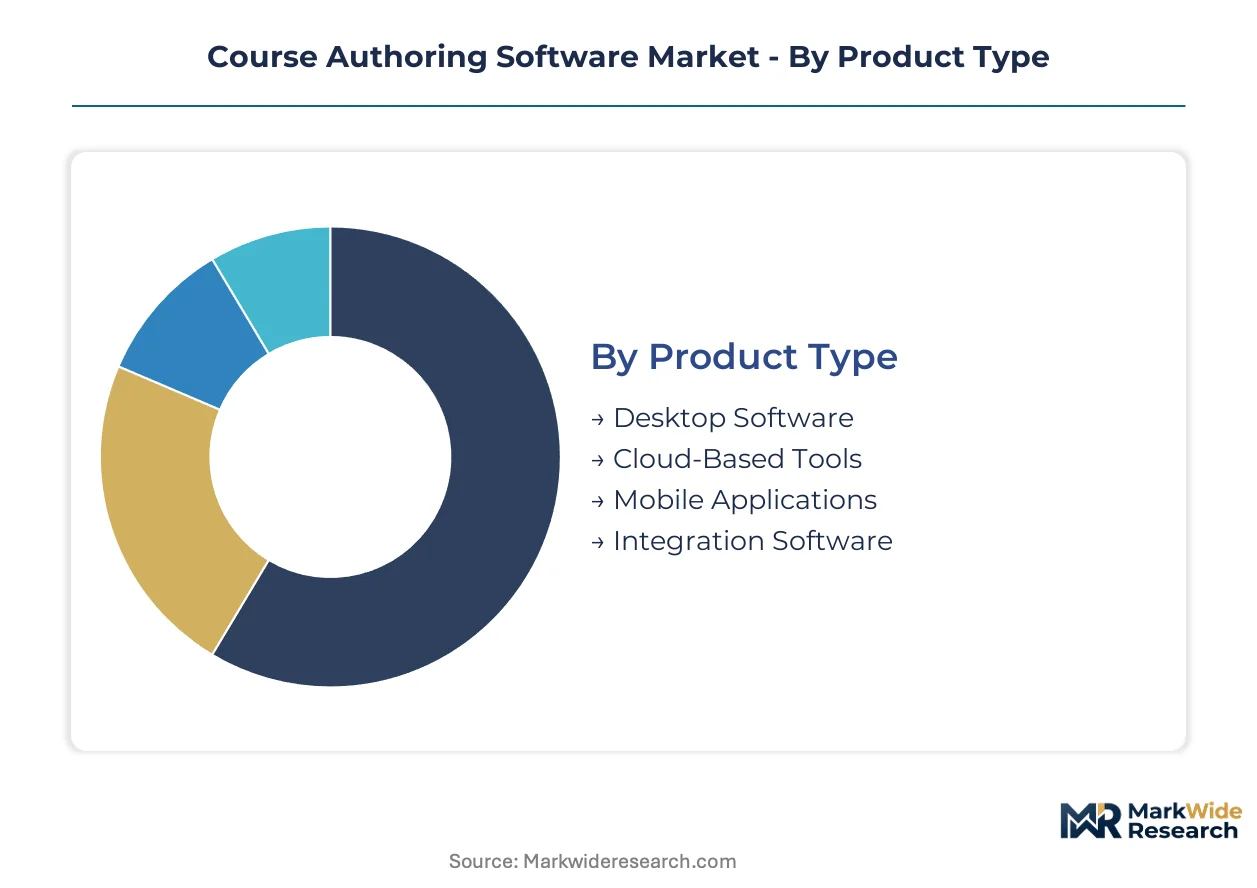
- Cloud-Based Tools:Browser-accessible platforms enable real-time co-authoring and automatic version control across distributed instructional design teams. Corporate L&D departments in the United States and Germany are standardizing on these tools to compress production cycles for compliance training refresh mandates.
- Desktop Software:Locally installed applications offer offline functionality and direct file system access for complex multimedia asset management. Security-conscious financial services firms in Japan prefer desktop deployments to maintain air-gapped content development environments under METI cybersecurity guidelines.
- Mobile Applications:Smartphone-native authoring interfaces support rapid microlearning creation by frontline supervisors without desktop access. These tools are gaining traction among retail and logistics training coordinators who need just-in-time content deployment.
- Integration Software:Middleware solutions connect disparate authoring environments with legacy LMS infrastructure and HR systems. Enterprise IT architects procure these tools to reduce custom API development costs during platform consolidation projects.
The dominant share belongs to Cloud-Based Tools, while Mobile Applications are climbing the fastest as frontline worker training programs bypass traditional desktop workflows entirely.
Delivery Model:
Commercial structures shape customer lifetime value profiles and sales cycle economics for platform vendors.
- Subscription-Based:Recurring revenue models align vendor incentives with ongoing customer success and feature utilization. Mid-sized training providers in the United States negotiate metered contracts tied to learner completions rather than author seat counts.
- Perpetual License:One-time purchase arrangements with annual maintenance fees appeal to public-sector educational institutions with capital budget constraints. State university systems in Germany favor this model to avoid ongoing operational expenditure classification.
- On-Premise:Self-hosted deployments satisfy data residency requirements and custom security audit protocols. Defense contractors and government agencies mandate on-premise installations to maintain physical control over learner data.
- Freemium:Tiered entry points with feature-gated upgrades convert individual instructional designers and small consultancies. Freelancers in Japan leverage free tiers to prototype courses before client commitment.
Subscription-Based arrangements command the revenue concentration, though Freemium conversion funnels are expanding most quickly as vendor customer acquisition costs escalate.
End User:
Buyer sophistication and procurement authority vary dramatically across organizational contexts and budget autonomy.
- Corporates:Enterprise L&D departments with dedicated instructional design teams and measurable ROI mandates represent the deepest margin pool. Compliance training requirements in regulated industries drive premium feature adoption.
- Educational Institutions:Universities and K-12 systems balance pedagogical flexibility against IT standardization pressures. Accessibility requirements under Section 508 and WCAG 2.2 dominate procurement criteria.
- Training Providers:Commercial learning consultancies serving multiple client verticals prioritize white-labeling capabilities and rapid deployment templates. These buyers negotiate volume discounts across client portfolios.
- Freelancers:Independent instructional designers and subject-matter experts operate on constrained budgets with project-based revenue. Template libraries and community support resources influence platform selection heavily.
Corporates retain the dominant procurement volume, while Training Providers are gaining share fastest as outsourced L&D functions expand.
Feature:
Functional capabilities determine competitive differentiation and pricing tier placement in vendor product hierarchies.
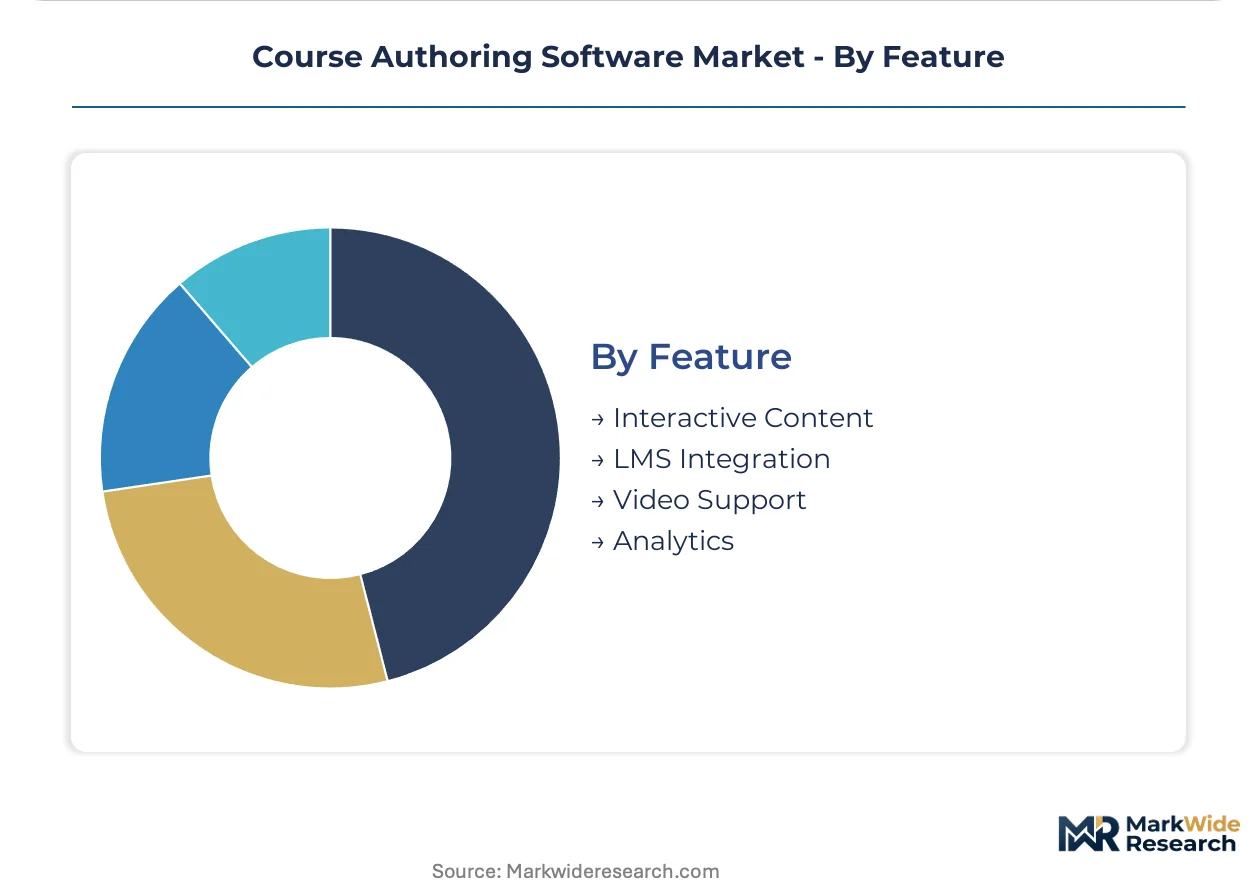
- Interactive Content:Branching scenarios, simulations, and gamification elements elevate learner engagement metrics. Manufacturing safety training programs in Germany demand these capabilities for Industrie 4.0 competency certification.
- Analytics:Granular learning record store integration and competency mapping support ROI demonstration to procurement committees. Corporate buyers require xAPI-compliant tracking to replace legacy SCORM limitations.
- LMS Integration:Pre-built connectors and SCORM/xAPI packaging reduce technical implementation friction. Educational technology administrators prioritize seamless gradebook synchronization and single sign-on compatibility.
- Video Support:Native video editing, transcription, and interactive overlay tools accelerate multimedia production without external software dependencies. Remote workforce training initiatives drive demand for asynchronous video-centric course formats.
Interactive Content holds the dominant feature priority, while Analytics is expanding most quickly as procurement teams face pressure to demonstrate training investment returns through granular engagement metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany, where enterprise procurement teams negotiate feature-rich contracts, while Japanese buyers prioritize data sovereignty over cost optimization. This asymmetry shapes vendor investment priorities across developed markets.
United States
Corporate L&D departments at Fortune 500 firms drive procurement volume for cloud-native authoring suites with xAPI analytics. FCC accessibility enforcement under Section 508 mandates WCAG 2.2 compliance for federal training contracts. Silicon Valley technology clusters and Boston-area biopharma corridors generate concentrated demand for rapid compliance course deployment.
Germany
Industrie 4.0 training mandates from METI-equivalent economic ministries propel investment in simulation-capable authoring platforms. The EU AI Act's risk-based classification system requires conformity assessments for AI-assisted personalization features. Manufacturing safety training programs in Bavaria and Baden-Württemberg fund custom toolchains for shop-floor competency certification.
Japan
METI-backed workforce reskilling initiatives accelerate public-sector procurement of multi-language localization infrastructure. Cybersecurity guidelines favor air-gapped desktop deployments for financial services content development. Tokyo and Osaka metropolitan areas concentrate demand from conglomerate training headquarters managing distributed Asia-Pacific operations.
United Kingdom
Post-Brexit regulatory divergence creates procurement complexity for multinational enterprises maintaining EU and UK training parity. GDPR retention requirements intersect with UK-specific data protection standards for cross-border learner records. London's financial services and Manchester's professional services clusters sustain premium-tier platform adoption.
India
IT services exporters and domestic edtech ventures expand authoring platform deployment for scalable workforce skilling. BIS standards for educational technology interoperability influence platform selection for government digital literacy programs. Bengaluru and Hyderabad technology corridors generate demand for collaborative authoring tools supporting distributed delivery teams.
Course Authoring Software Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower functional scope. The market exhibits moderate consolidation, with three to five vendors capturing disproportionate enterprise procurement volume. Strategic archetypes include template-library aggregators, multi-language localization specialists, and collaborative workflow enablers. Dominant competitive moves encompass API-first partnership ecosystems and vertical-specific content template acquisitions.
Within the template-centric tier, Articulate 360 and iSpring Suite occupy positions emphasizing rapid deployment capabilities for North American corporate segments. Elucidat exemplifies the collaborative workflow archetype, anchoring demand from distributed instructional design teams requiring real-time co-authoring infrastructure. dominKnow represents the localization-specialist position, serving enterprise clients with complex multi-jurisdiction content requirements.
| Leading Market Players |
|---|
| iSpring Suite |
| dominKnow |
| Articulate 360 |
| Tovuti LMS |
| Gomo Learning |
| Elucidat |
| Lectora |
| Easygenerator |
| Adobe Captivate |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in cloud infrastructure regions is compressing margins for SaaS authoring vendors while simultaneously enabling aggressive pricing postures among hyperscaler-dependent platforms. This utilization dynamic forces mid-market vendors toward metered consumption models that pass through infrastructure volatility, reshaping both supplier investment cycles and buyer procurement negotiations across North America and Europe.
Pricing Analysis
The customization-premium spread separates enterprise-configured deployments from standardized SMB tiers by a factor of three to five in annual contract value. Pricing stratifies across premium, standard, and economy tiers, with differentiation anchored in SCORM/xAPI certification depth, multi-language localization scope, and AI-assisted authoring module inclusion. Pricing pressure stems from AWS and Azure cost volatility squeezing fixed-subscription margins, compelling vendors toward usage-based hybrids. Training providers and mid-market consultancies exhibit acute price sensitivity, while Fortune 500 L&D departments prioritize compliance feature depth over unit cost.
Supply Chain Analysis
Contract manufacturing concentration in software-as-a-service remains minimal; instead, infrastructure-as-a-service provisioning centers on Amazon Web Services, Microsoft Azure, and Google Cloud Platform for compute and storage backbone. Geographic supply concentration for AI training clusters draws from the United States, Ireland, and Singapore, while specialized GPU provisioning rests on Taiwan and South Korea foundry capacity. Raw material dependencies span semiconductor substrates, rare earth elements for data center hardware, and licensed training corpora for generative AI features. Single-source vulnerability concentrates in hyperscaler regional outages, with distribution running through direct vendor sales organizations and systems integrator channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Course authoring software represents a service-attach opportunity where implementation consulting and ongoing content production support expand faster than base platform subscriptions. Recurring-revenue layers including managed localization services, compliance audit assistance, and learner analytics interpretation now capture disproportionate margin expansion.
For Market Incumbents: Pre-empt open-source LRS displacement by embedding proprietary analytics as differentiated workflow components rather than standalone modules. Acquire vertical-specific template libraries in regulated sectors—healthcare, financial services, energy—to deepen switching costs. Fortify API partnership ecosystems with dominant LMS platforms to reduce enterprise procurement friction.
For New Entrants and Emerging Players: Build out mobile-native microlearning creation tools targeting frontline supervisor personas in retail, logistics, and manufacturing verticals underserved by desktop-centric incumbents. Penetrate Japan's public-sector reskilling programs through METI-aligned localization partnerships. Pursue land-and-expand go-to-market motions via freemium conversion funnels with explicit upgrade paths to enterprise governance features.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with embedded collaboration infrastructure and native multi-language capabilities, signaling durable customer lifetime value. Target acquisition profiles emphasizing AI-human workflow tools with pre-certified EU AI Act compliance modules. Monitor xAPI adoption velocity across corporate L&D departments as inflection indicator for analytics-centric platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Governance Layer Integration | EU AI Act conformity assessments become procurement gate for German and French enterprise buyers. |
| Vertical Template Library Acquisition | Industrie 4.0 safety certification content commands premium pricing in Bavarian manufacturing clusters. |
| API-First Partnership Ecosystem | Pre-built LMS connectors reduce implementation friction for US federal procurement under Section 508. |
| Mobile-Native Authoring Platform Launch | Frontline worker training programs in US retail bypass desktop workflows entirely. |
| Usage-Based Pricing Transition | Metered contracts tied to learner completions align vendor incentives with demonstrated training ROI. |
Study Parameters
Initial hypotheses were tested against primary input from instructional design directors, corporate L&D procurement officers, LMS integration specialists, and edtech channel partners and refined through secondary validation against SEC SaaS vendor filings, hyperscaler capex disclosures, EU regulatory impact assessments, and BIS educational technology standards. Bottom-up segmentation modeling triangulated with top-down market sizing across deployment architecture, commercial structure, and end-user sophistication tiers.
Demand-supply balance framing anchored the analytical framework, with adoption curves modeled across cloud-based, desktop, mobile, and integration software product types alongside subscription, perpetual license, on-premise, and freemium delivery models. CAGRs derived from fitted growth curves incorporating corporate compliance training refresh cycles, public-sector digitization mandates, and AI feature penetration rates. Segmentation dimensions included organization size, vertical regulatory intensity, and regional data sovereignty requirements.
Stress conditions across hyperscaler pricing volatility, EU AI Act enforcement timelines, and open-source LRS substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding enterprise cloud migration velocity and workforce reskilling program funding continuity. Quarterly review of xAPI adoption metrics, AI governance certification progress, and frontline mobile authoring uptake is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Contract Lifecycle Management (CLM) Solution Market
Software & Services
Global Translation Software Market
Software & Services
HPC Software Market
Software & Services
Air Cargo Software Market
Software & Services
North America Automotive Software Market
Software & Services
Invoice Processing Software Market
Software & Services
Self-Storage Software Market
Software & Services
Pharmacy Billing Software Market
Software & Services
Stone Analysis Software Market
Software & Services
UK Applicant Tracking System Market
Software & Services
Cloud Backup and Recovery Software Market
Software & Services
Enterprise MLC (Emlc) Market
Software & Services
Specification Management Software Market
Software & Services
Investor Relations (IR) Website Builder Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Bank Reconciliation Software Market