
 Global Managed Detection and Response (MDR) Market | 2026-2036
Global Managed Detection and Response (MDR) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Managed Detection and Response (MDR) Market Intelligence
The channel-to-market structure for MDR services is tilting away from direct vendor sales toward integrated delivery through Managed Service Providers (MSPs). This shift favors platforms that enable multi-tenant management and flexible deployment. CrowdStrike leverages its cloud-native Falcon platform to lead in the endpoint security space. Meanwhile, Palo Alto Networks competes with a comprehensive security operations platform, and Arctic Wolf specializes in a concierge model for small and medium-sized enterprises.
Managed Detection and Response (MDR) is an outsourced service providing organizations with 24/7 threat monitoring, detection, and response capabilities. It combines advanced security analytics, threat intelligence, and human expertise to investigate and contain cyber threats that bypass traditional security controls. Cloud-based deployment models are expanding rapidly, offering scalability and faster implementation compared to on-premises solutions. Within solution offerings, endpoint protection and behavioral analytics form the core value proposition, commanding premium service-level agreements.
Regulatory frameworks like the EU's GDPR and the US's HIPAA impose stringent data breach notification and protection requirements, creating non-discretionary demand for continuous monitoring. In parallel, national directives from bodies such as India's CERT-In are establishing localized cybersecurity standards that drive service adoption. Stakeholders must now evaluate how to integrate AI-driven automation into their MDR strategies to manage the escalating volume and sophistication of threats.
Market Dynamics
The failure of traditional, prevention-focused security tools to stop sophisticated cyber attacks is the central force shaping the Managed Detection and Response market. This dynamic is intensified by escalating threats against critical infrastructure, particularly industrial control systems and operational technology.
Growth Catalysts
- Regulatory Mandates:Data protection laws like the EU's GDPR and India's CERT-In directives require continuous monitoring and rapid breach reporting, creating non-discretionary demand for MDR services to ensure compliance.
- OT Security Demand:The manufacturing sector is adopting MDR to protect vulnerable operational technology (OT) and industrial control systems (ICS) from specialized cyber attacks that can halt production.
- Advanced Threat Evasion:The increasing ability of cyber threats to bypass automated security controls forces organizations to invest in human-led threat hunting and outsourced 24/7 response services.
Market Restraints
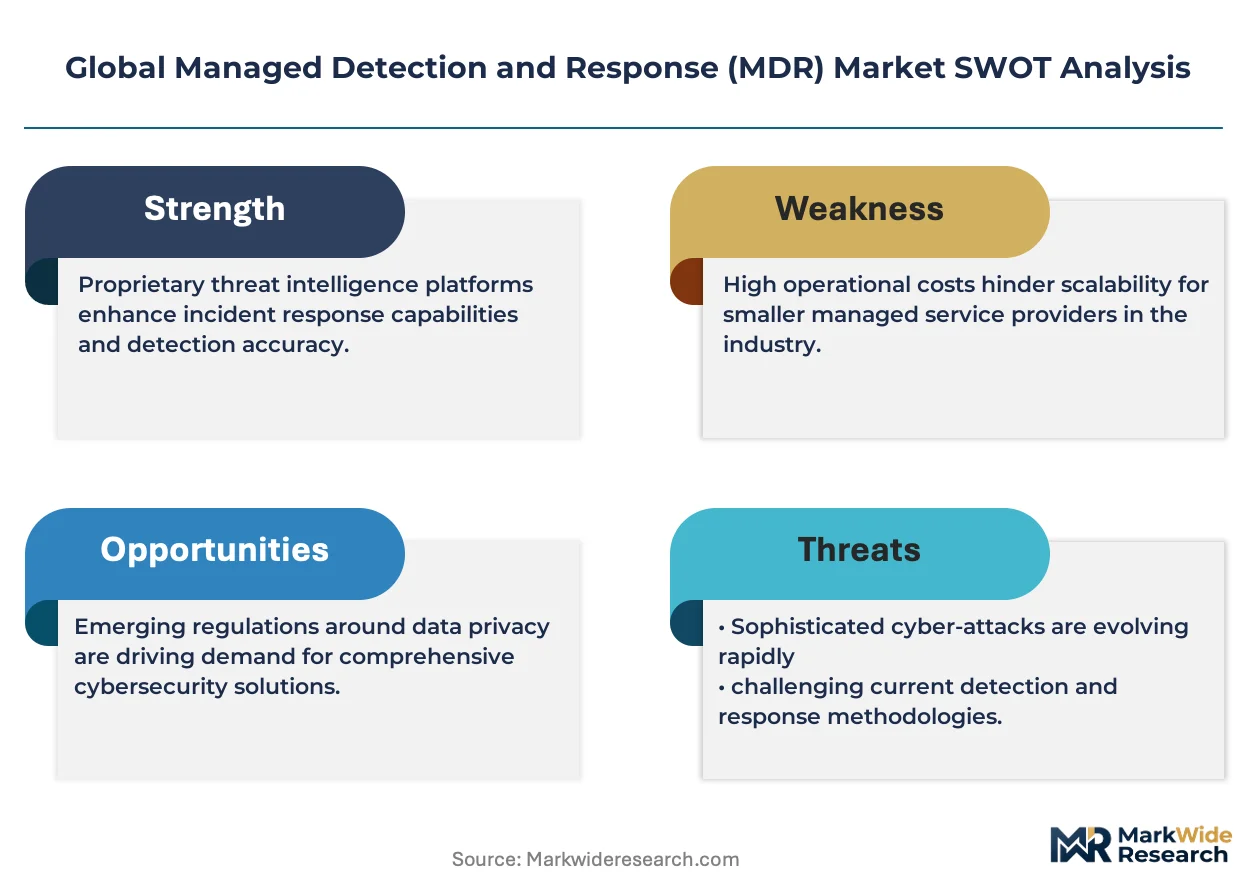
- High Service Costs:The premium cost associated with 24/7 access to specialized security analysts presents a significant adoption barrier, particularly for small and medium-sized enterprises with limited budgets.
- Integration Complexity:Integrating MDR platforms with a client's diverse array of legacy security tools can be technically complex and time-consuming, delaying service deployment and increasing initial setup costs.
- Data Access Concerns:A persistent restraint is the organizational reluctance to grant third-party providers the deep, privileged access to sensitive internal systems and data required for effective monitoring.
Strategic Opportunities
- Emerging Markets:Underpenetrated regions like Southeast Asia and Latin America offer significant growth potential as rapid digitalization outpaces local cybersecurity maturity, creating demand for outsourced expertise.
- Vertical Specialization:Developing tailored MDR offerings for specific verticals, such as securing Internet of Medical Things (IoMT) devices in healthcare or protecting municipal smart city infrastructure, opens new market segments.
- AI and Automation:Integrating AI-driven automation and security orchestration (SOAR) capabilities can scale operations, reduce response times, and create more efficient, cost-effective service tiers for providers.
Industry Challenges
- Cybersecurity Talent Shortage:A critical challenge is the persistent global shortage of qualified security analysts with the advanced skills required for effective threat hunting, digital forensics, and incident response.
- Alert Volume and Fatigue:MDR providers face the operational challenge of managing an overwhelming volume of security alerts from various tools, risking analyst burnout and potentially overlooking critical threat indicators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Managed Detection and Response (MDR) Market |
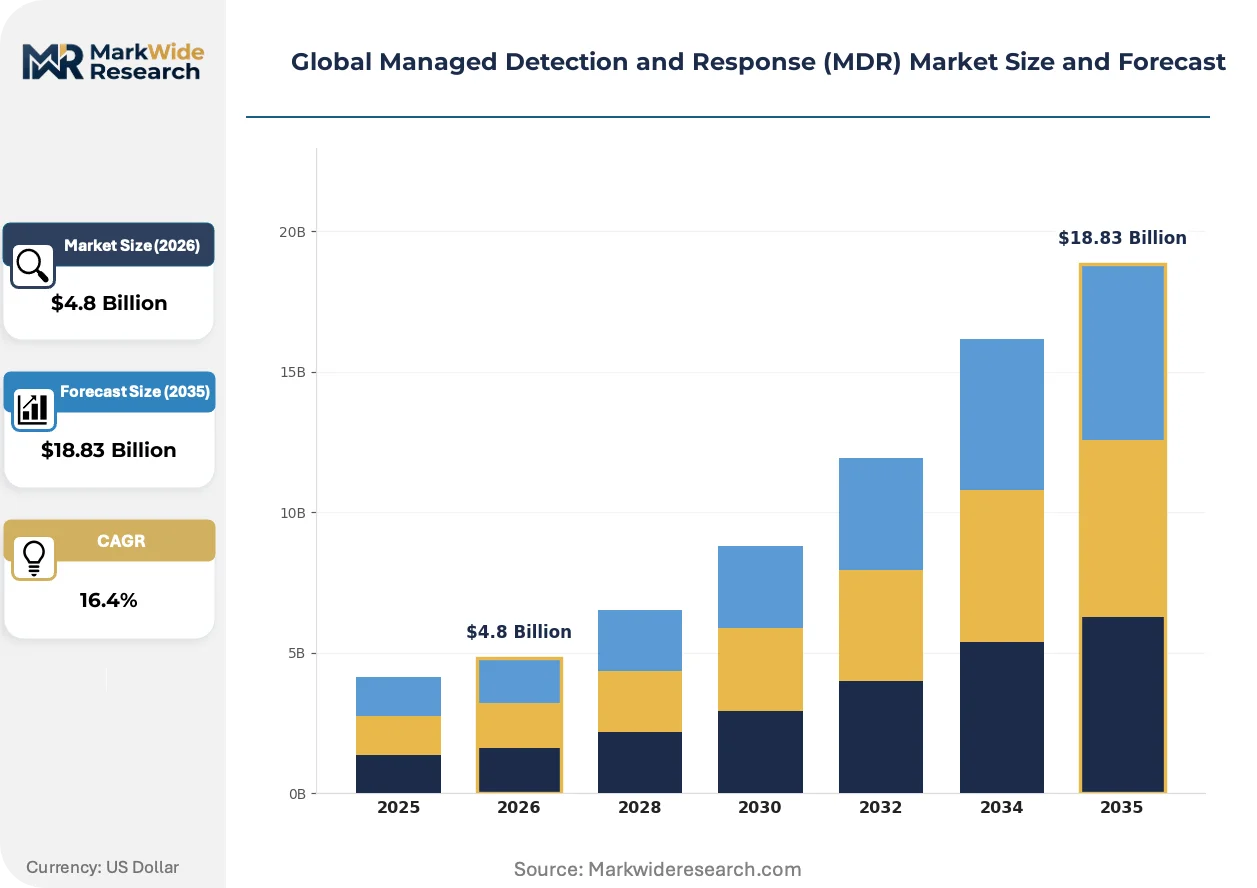
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $18.83 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Threat Intelligence, Incident Response, Vulnerability Management, Security Monitoring, Compliance Management Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Onsite End User: Telecommunications, Manufacturing, Energy & Utilities, Government, Education Solution Offering: Network Security, Endpoint Protection, Behavioral Analytics, Security Orchestration, Data Loss Prevention |
| Companies Covered | CrowdStrike, Rapid7, Arctic Wolf, SentinelOne, Red Canary, Palo Alto Networks, Sophos, Secureworks, Kudelski Security, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Managed Detection and Response (MDR) Market Strategic Shifts & Innovations
The industrialization of security operations is actively reshaping the market, moving it beyond simple alert monitoring. This evolution emphasizes the tight integration of AI-driven platforms with elite human expertise to deliver measurable risk reduction outcomes for clients.
Extended Detection and Response
Extended Detection and Response (XDR) platforms provide unified visibility by aggregating telemetry from endpoints, cloud workloads, and network sources. Large enterprises are adopting XDR to overcome security tool sprawl and data silos. The adoption of XDR is hybridizing MDR offerings, blending the platform's automated capabilities with the provider's human-led threat hunting to cover a broader attack surface.
Prescriptive National Directives
National cybersecurity directives, like those issued by India's CERT-In, are imposing more prescriptive security requirements on businesses. These regulations mandate specific incident reporting timelines and data logging practices for a wide range of organizations. Consequently, sectors like financial services and technology are procuring MDR services specifically to ensure auditable compliance with these localized government mandates.
Channel Consolidation via MSPs
A pivotal demand-side shift sees enterprises increasingly sourcing MDR services through their primary Managed Service Provider (MSP) instead of contracting directly with a security vendor. This channel consolidation simplifies procurement and billing, especially for mid-market companies seeking a single partner for IT and security. This pattern is most pronounced in North America and Europe, where the mature MSP ecosystem is now a dominant route-to-market.
Global Managed Detection and Response (MDR) Market Segmentation
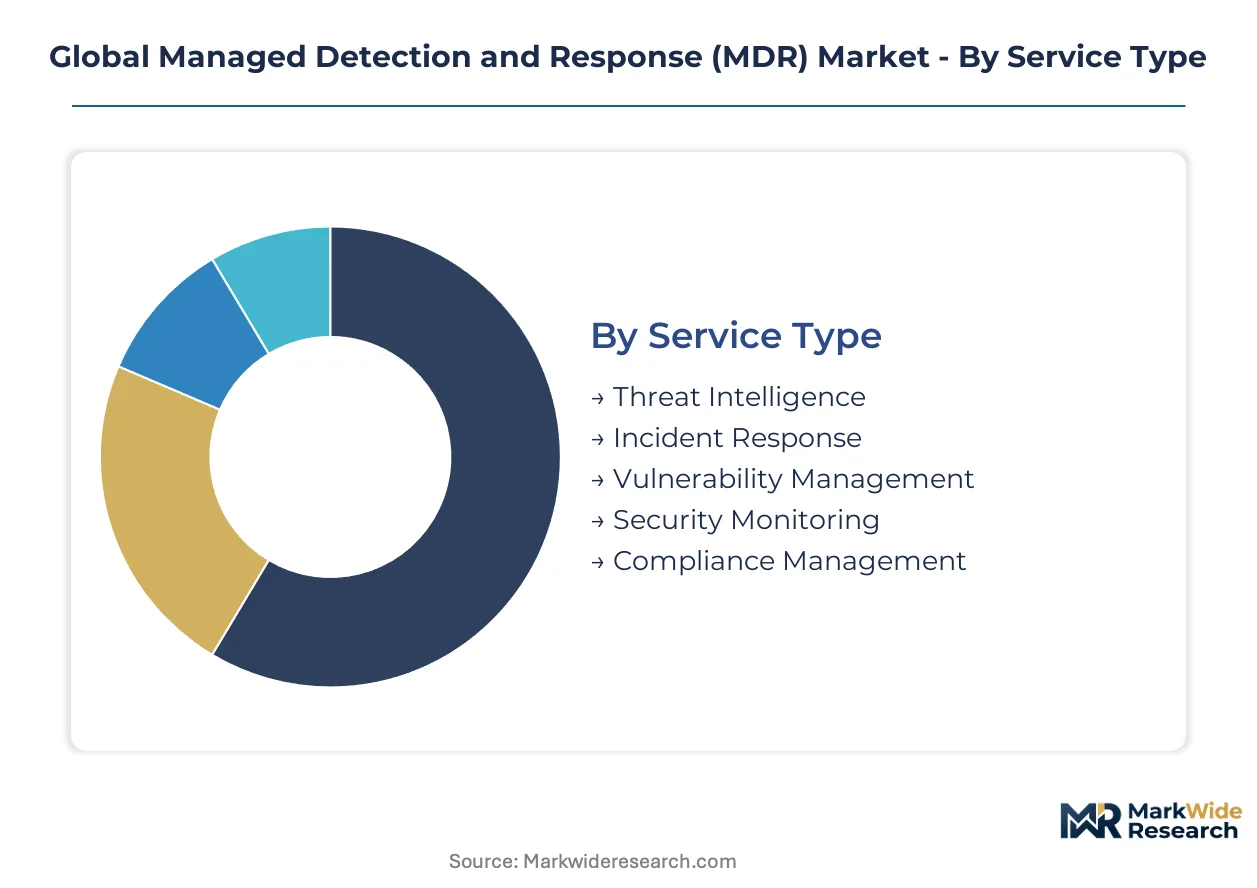
The Managed Detection and Response (MDR) market segments across various dimensions, reflecting the diverse needs and operational models of client organizations. Understanding these segmentations helps providers tailor solutions and clients identify the most suitable security partnerships for their specific risk profiles.
Service Type:
The intensity of after-sales service and ongoing client engagement significantly differentiates MDR offerings across various service types. Each service demands distinct levels of human expertise and technological integration to deliver effective security outcomes.
- Threat Intelligence:Provides proactive insights into emerging cyber threats and attacker methodologies. Organizations leverage this to anticipate attacks and harden defenses, particularly in sectors facing advanced persistent threats.
- Incident Response:Focuses on containing, eradicating, and recovering from active cyberattacks. This service is critical for minimizing breach impact and ensuring business continuity, especially for financial services and critical infrastructure.
- Vulnerability Management:Identifies and prioritizes security weaknesses within an organization's IT infrastructure, enabling proactive patching and remediation efforts.
- Security Monitoring:Offers continuous surveillance of IT environments for suspicious activities and anomalies, forming the foundation of real-time threat detection.
- Compliance Management:Assists organizations in meeting specific regulatory requirements for data protection and incident reporting, crucial for sectors like healthcare and government.
Incident Response holds the largest share of immediate client investment; momentum sits with Threat Intelligence for proactive defense strategies.
Deployment Model:
Deployment models reflect varying client infrastructure preferences and operational flexibility requirements for MDR services.
- Cloud-Based:Delivers MDR services entirely through a cloud infrastructure, offering scalability, rapid deployment, and reduced overhead for clients. This model is gaining traction among enterprises seeking agile security solutions without significant on-premises investments.
- Hybrid:Combines elements of both cloud-based and on-premises deployments, allowing organizations to retain control over sensitive data while leveraging cloud scalability. This approach caters to large organizations with complex, distributed IT environments.
- On-Premises:Involves deploying MDR tools and personnel directly within the client's own data centers, often preferred by highly regulated industries for data sovereignty.
- Managed Onsite:Places dedicated MDR security analysts directly within the client's physical premises, providing deeply integrated security operations and immediate response capabilities.
Cloud-Based deployments are expanding most quickly, while Hybrid models offer a balanced approach for diverse client needs.
End User:
Each end-user segment presents unique attack surfaces and regulatory compliance needs, driving specialized MDR service requirements.
- Manufacturing:Requires protection for industrial control systems (ICS) and operational technology (OT) against sophisticated nation-state attacks. The sector prioritizes uptime and supply chain integrity, making MDR crucial for production continuity.
- Telecommunications:Faces high volumes of cyber threats targeting critical network infrastructure and vast customer data. MDR services are essential for maintaining service availability and protecting sensitive communication records.
- Energy & Utilities:Secures vital infrastructure from attacks that could disrupt power grids or resource distribution, emphasizing resilience and rapid incident response.
- Government:Demands robust security for classified information and critical national infrastructure, often requiring specific compliance frameworks and data residency rules.
- Education:Protects academic research, student data, and campus networks from various cyber threats, including ransomware and phishing campaigns.
Manufacturing and Telecommunications sectors are driving significant demand, with Energy & Utilities climbing the fastest due to escalating critical infrastructure threats.
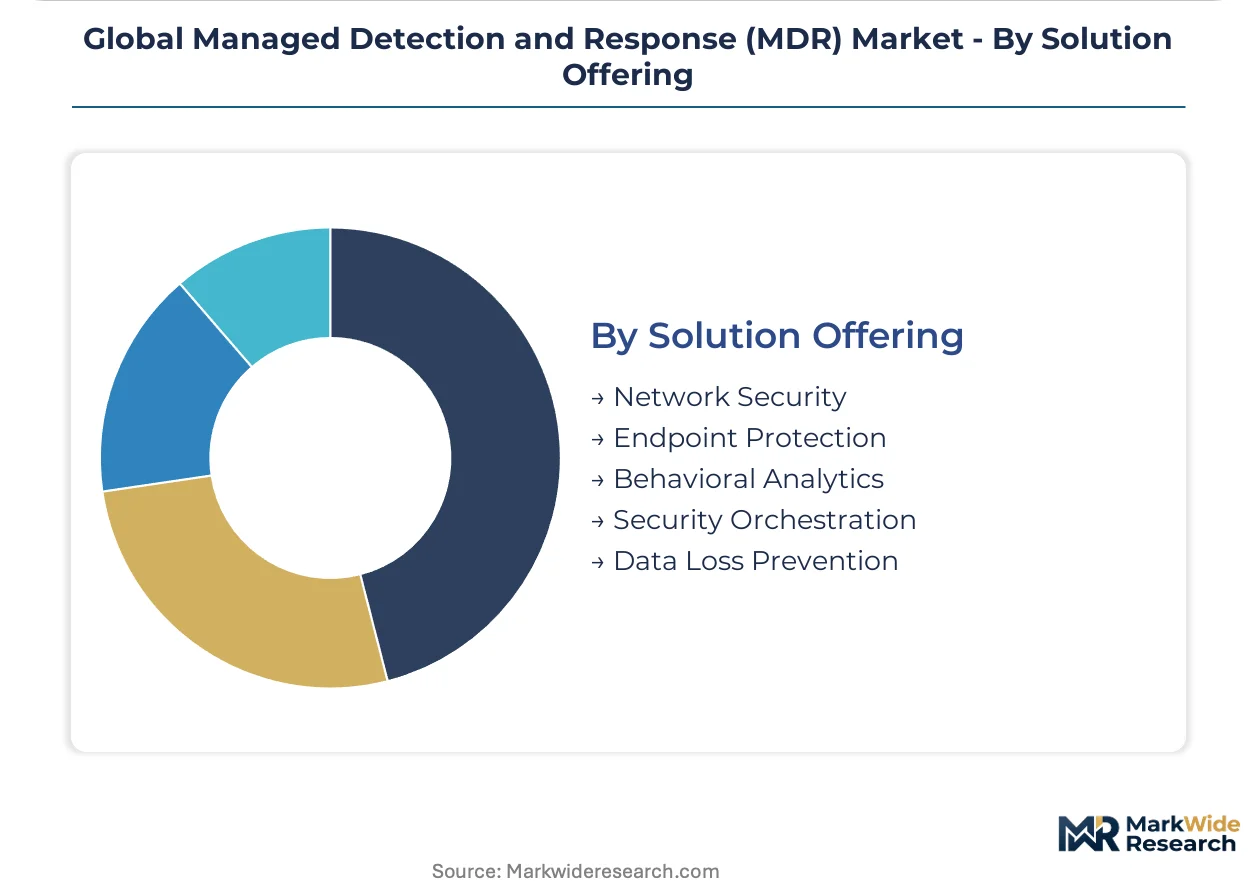
Solution Offering:
Solution offerings delineate the core value proposition and technological focus of MDR providers, addressing specific security domains.
- Endpoint Protection:Focuses on securing individual devices like laptops, servers, and mobile phones from malware and unauthorized access. This forms a foundational layer of defense for nearly all organizations, given the distributed nature of modern workforces.
- Behavioral Analytics:Utilizes machine learning to detect anomalous user and system activities that may indicate a breach, often bypassing signature-based detection. This capability is vital for identifying insider threats and zero-day attacks that traditional tools miss.
- Network Security:Monitors and defends network infrastructure from intrusions, unauthorized access, and data exfiltration, providing visibility into traffic patterns.
- Security Orchestration:Automates and streamlines security operations workflows, integrating various tools to accelerate threat response and improve efficiency.
- Data Loss Prevention:Prevents sensitive information from leaving an organization's controlled environment, crucial for compliance and intellectual property protection.
Endpoint Protection remains a fundamental offering, while Behavioral Analytics shows the steepest expansion due to its efficacy against sophisticated threats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' stringent HIPAA regulations drive significant demand for continuous monitoring and data protection services in the Managed Detection and Response market. Businesses across North America prioritize robust cybersecurity solutions to mitigate escalating cyber threats. This focus on regulatory compliance and threat mitigation shapes regional investment in advanced security capabilities.
United States
The United States' large enterprise base and high rate of cyber threats necessitate advanced MDR solutions. HIPAA and other federal mandates compel healthcare and financial institutions to adopt continuous monitoring and rapid incident response. Silicon Valley and major tech hubs like Austin concentrate demand for sophisticated behavioral analytics and endpoint protection services.
Germany
Germany's robust industrial sector requires specialized MDR services to protect critical operational technology and industrial control systems. The GDPR and national data protection laws mandate stringent cybersecurity measures for businesses operating across the European Union. Munich and Stuttgart, major industrial centers, focus on securing manufacturing facilities and supply chains.
India
India's rapid digitalization and expanding digital economy fuel demand for outsourced cybersecurity expertise. CERT-In directives establish localized cybersecurity standards, requiring specific incident reporting and data logging practices for businesses. Bengaluru's tech industry and Mumbai's financial sector seek MDR services for compliance and threat intelligence.
Japan
Japan's focus on technological innovation and critical infrastructure protection drives investment in advanced MDR capabilities. METI guidelines encourage robust cybersecurity practices, particularly for organizations managing sensitive data and essential services. Tokyo's financial district and manufacturing hubs prioritize network security and incident response services.
United Kingdom
The United Kingdom's diverse financial services and technology sectors demand comprehensive MDR services. The GDPR, post-Brexit data protection laws, and NCSC guidance influence cybersecurity investments across the nation. London's financial institutions and technology firms are significant consumers of threat intelligence and security monitoring.
Global Managed Detection and Response (MDR) Market Key Industry Players
Specialized security vendors and diversified IT service providers split the Managed Detection and Response market, reflecting varied client preferences. Large security platform companies often offer MDR as an extension of their existing product suites, integrating deeply with their proprietary technologies. This structure fosters competition among pure-play MDR specialists and broader cybersecurity solution providers aiming for comprehensive coverage. Companies pursue strategic partnerships and portfolio diversification to enhance their market reach and solution breadth.
Specialists in 24/7 threat monitoring and response include Arctic Wolf, which focuses on a concierge model tailored for small and medium-sized enterprises. Large platform providers like Palo Alto Networks exemplify the trend toward comprehensive security operations platforms, integrating MDR with a wider suite of security services for an end-to-end approach. CrowdStrike occupies a position as a leader in the endpoint security space, leveraging its cloud-native Falcon platform to deliver advanced detection and response capabilities. These entities demonstrate the market's segmentation by client focus and technological integration.
| Leading Market Players |
|---|
| CrowdStrike |
| Rapid7 |
| Arctic Wolf |
| SentinelOne |
| Red Canary |
| Palo Alto Networks |
| Sophos |
| Secureworks |
| Kudelski Security |
| Others |
Cost & Logistics Intelligence
Specialized security analyst talent pools in key regions like the United States and India directly influence the pricing power and margin pools for Managed Detection and Response (MDR) providers downstream.
Pricing Analysis
Pricing for Managed Detection and Response services exhibits significant regional variations, influenced by local labor costs and diverse regulatory compliance demands. The dominant pricing model is subscription-based, often tiered by the scope of monitoring, included features, and the level of human-led response. Price differentiation stems from the customization level of the service, the depth of human expertise, and the integration capabilities with existing client infrastructure. Pricing pressure intensifies for entry-level MDR services due to increased competition, while premium offerings command higher prices because of the scarcity of advanced cybersecurity talent. Small and medium-sized enterprises typically show the highest price sensitivity, whereas large enterprises prioritize comprehensive coverage over cost.
Supply Chain Analysis
Specialized security operations centers (SOCs) in regions like the United States, India, and the United Kingdom form the core supply infrastructure for MDR services. The supply chain relies on advanced threat intelligence feeds from global security vendors and robust cloud infrastructure providers for scalable operations. A significant supply chain risk is the persistent global cybersecurity talent shortage, which can constrain service delivery capacity and elevate operational costs. Distribution runs through a hybrid model, combining direct sales channels from large platform providers with an increasing reliance on Managed Service Providers (MSPs) for client acquisition and localized support, particularly in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Managed Detection and Response market represents a high-growth disruption, driven by the escalating sophistication of cyber threats and stringent data protection mandates like the EU's GDPR.
For Market Incumbents: Entrench market leadership by expanding XDR platform integration to counter the threat of fragmented security solutions. Consolidate smaller pure-play MDR providers to acquire specialized talent and regional market share. Invest heavily in AI-driven automation within their platforms to reduce analyst burnout and improve response efficiency, a critical lever against the global talent shortage.
For New Entrants and Emerging Players: Establish a beachhead in underpenetrated emerging markets like Southeast Asia by offering localized, compliance-focused MDR solutions. Target specific vertical niches, such as securing Internet of Medical Things (IoMT) in healthcare, where specialized expertise can differentiate offerings. A go-to-market angle focusing on rapid deployment and demonstrable ROI for SMBs through MSP partnerships can accelerate adoption.
For Investors and Strategic Acquirers: Capital is best deployed toward platform providers with strong AI-driven automation capabilities and a proven track record in specific vertical specializations. Long-term viability over a five-to-ten-year window favors companies that can consistently attract and retain top cybersecurity talent while scaling operations through technology. The signal to watch is the increasing integration of security orchestration, automation, and response (SOAR) platforms into core MDR offerings.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen AI-driven Automation | Reduces alert fatigue for analysts and accelerates threat response times. |
| Expand MSP Channel Partnerships | Accesses mid-market clients and simplifies procurement for diverse enterprises. |
| Develop Vertical-Specific MDR Offerings | Addresses unique compliance and threat profiles in sectors like healthcare or manufacturing. |
| Integrate XDR Capabilities | Provides unified visibility across endpoints, cloud, and networks, reducing data silos. |
| Invest in Cybersecurity Talent Development | Mitigates the global shortage of skilled security analysts for 24/7 operations. |
Research Approach
The analysis maps Managed Detection and Response service types, deployment models, and end-user segments, each validated through primary interviews with cybersecurity executives, IT directors, and compliance officers. This qualitative input was triangulated with secondary data from industry reports, regulatory filings from bodies like CERT-In, and vendor whitepapers. Both bottom-up and top-down approaches were employed to ensure robust market sizing and segment validation.
Assumptions regarding cybersecurity spending, regulatory enforcement, and technological advancements were held fixed over the projection horizon. The analytical framework modeled segmentation dimensions including service type, deployment model, end-user industry, solution offering, and regional adoption patterns. Compound annual growth rates were derived from historical trends and projected market drivers, with cyberattack volume and regulatory compliance costs serving as key forecast inputs.
Sensitivities concentrate around geopolitical tensions impacting cyber warfare, the pace of AI integration into security tools, and the evolution of data privacy regulations. Forecasts reflect these assumptions and acknowledge specific risk factors such as new zero-day exploits or economic downturns affecting IT budgets. Quarterly review of threat intelligence reports and regulatory updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Enterprise Network Firewall Market
Cybersecurity
Poland Cybersecurity Market
Cybersecurity
Romania Cybersecurity Market
Cybersecurity
Taiwan Cybersecurity Market
Cybersecurity
Spear Phishing Solution Market
Cybersecurity
Global Bug Bounty Platforms Market
Cybersecurity
AI in Cybersecurity Market
Cybersecurity
United Kingdom Ransomware Protection Market
Cybersecurity
M2M Network Security Market
Cybersecurity
LAMEA Deception Technology Market
Cybersecurity
Cyber Security Consulting Market
Cybersecurity
Cognitive Security Market
Cybersecurity
Global Virtualization Security Market
Cybersecurity
Italy Cybersecurity Market
Cybersecurity
Global Internet Security Market
Cybersecurity
Cloud DLP Market