
 Global Digital Vehicle Forensics Market | 2026-2036
Global Digital Vehicle Forensics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Vehicle Forensics Market Analysis
ISO 17025 accreditation for digital forensics laboratories is reorganizing competitive access across the Global Digital Vehicle Forensics Market, filtering out uncertified service providers from high-stakes criminal and civil proceedings. Oxygen Forensics leverages deep parsing capabilities for infotainment and telematics control units across European and Asian vehicle platforms. MSAB sustains technology leadership through dedicated R&D into proprietary OEM encryption bypass methods for Swedish and German automotive architectures. Grayshift dominates law enforcement channel access in North America with hardware-software bundles designed for roadside extraction workflows.
Digital vehicle forensics encompasses the systematic extraction, preservation, and analysis of electronically stored information from automotive control modules, infotainment systems, telematics gateways, and advanced driver-assistance sensors using write-blocking hardware and validated software tools to establish evidentiary integrity for legal proceedings. Data acquisition technology commands the largest installed base due to mandatory preservation requirements, while forensic software represents the fastest-expanding margin pool as OEM data formats proliferate and decryption complexity intensifies. Accident investigation applications generate the steadiest revenue flow from government contracts, whereas insurance fraud detection is emerging as a high-growth segment as carriers deploy automated anomaly detection across connected vehicle telemetry streams.
The U.S. National Highway Traffic Safety Administration mandates event data recorder preservation standards that directly shape tool validation requirements for vendors serving American litigation markets, while the European Union's General Data Protection Regulation imposes strict data minimization and subject consent protocols on cross-border forensic transfers involving EU-registered vehicles. China's Ministry of Industry and Information Technology enforces GB-standard cybersecurity review for any foreign forensic software processing domestic vehicle data, creating localized compliance barriers for international platform providers. Stakeholders must monitor the divergence between regional data sovereignty frameworks and OEM proprietary encryption strategies when allocating R&D and certification investments across jurisdictional footprints.
Market Dynamics
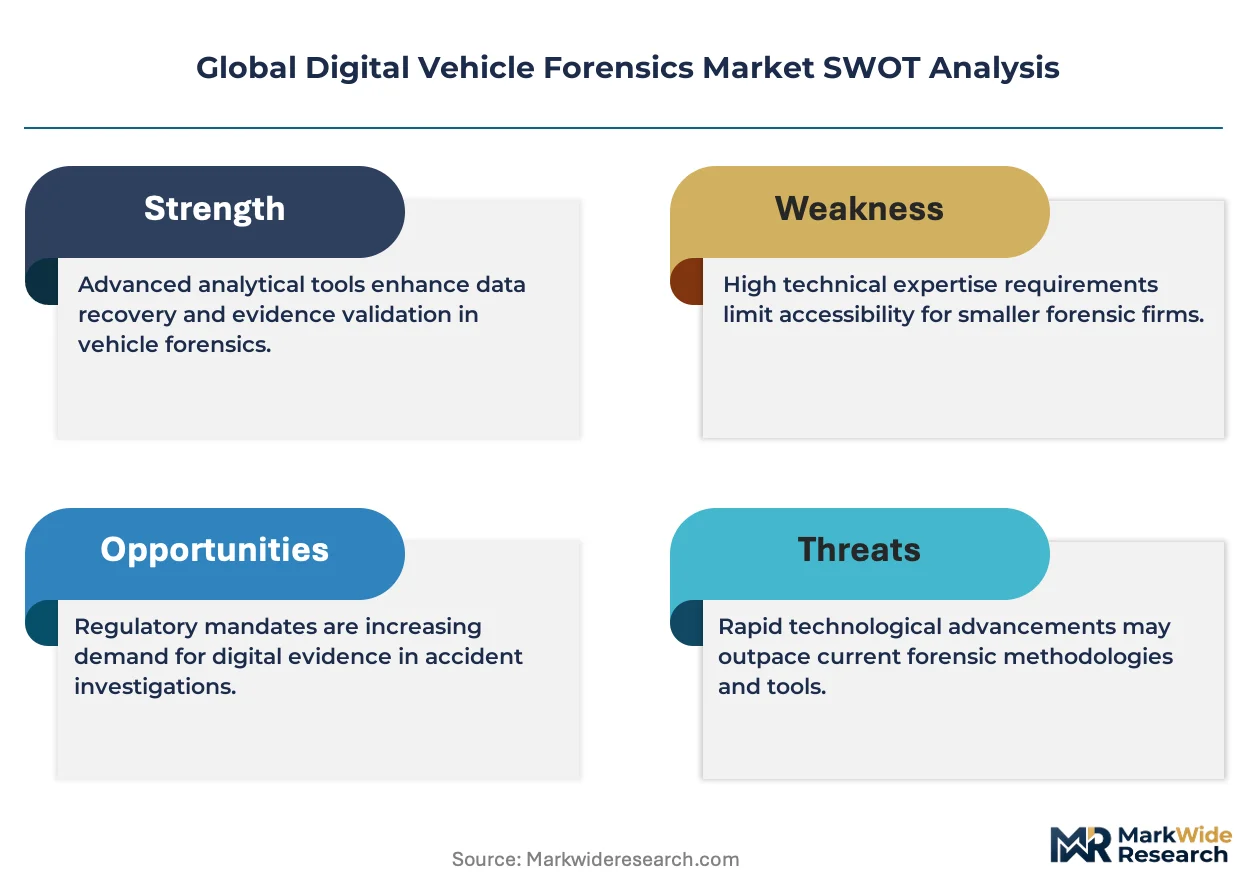
OEM proprietary encryption architectures are fragmenting forensic tool interoperability as each manufacturer deploys distinct cryptographic protocols for telematics and infotainment systems, forcing vendors to develop vehicle-specific parsing modules rather than universal extraction platforms.
Growth Catalysts
- NHTSA Event Data Recorder Mandates:United States federal preservation standards compel law enforcement agencies to procure validated forensic platforms, creating recurring procurement cycles for extraction hardware and chain-of-custody software.
- Connected Vehicle Telemetry Expansion:Advanced driver-assistance systems and infotainment architectures generate terabyte-scale data streams, expanding the addressable evidence surface for post-collision reconstruction and insurance litigation.
- EU AI Act Chain-of-Custody Protocols:European evidence handling requirements for algorithmic decision-making systems are mandating ISO 17025 laboratory accreditation for automotive digital forensics, filtering demand toward certified service providers.
Market Restraints
- Proprietary OEM Encryption Barriers:Volkswagen Group, Toyota Motor, and Stellantis deploy distinct cryptographic key management systems that resist standardized bypass methods, fragmenting tool development economics across incompatible vehicle architectures.
- Specialized Semiconductor Supply Concentration:Write-blocking hardware controllers depend on Taiwanese foundry capacity, exposing forensic equipment manufacturers to single-source geographic risk for critical acquisition components.
- GDPR Cross-Border Transfer Friction:European data minimization and subject consent requirements impose procedural delays on multinational insurance investigations involving EU-registered vehicles, compressing case velocity and service margins.
Strategic Opportunities
- Brazilian Federal Highway Police Digital Expansion:Latin America's largest automotive market lacks indigenous forensic platform capacity, creating first-mover advantage for ISO 17025-accredited laboratories establishing Portuguese-language service operations.
- Insurance Carrier Telemetry Anomaly Detection:Automated fraud identification systems processing connected vehicle data streams represent an emerging application segment distinct from traditional post-incident forensic reconstruction.
- Edge Computing and 5G Vehicle-to-Infrastructure Convergence:Real-time data streaming from roadside units and cellular vehicle-to-everything networks enables prospective evidence capture before physical vehicle seizure, redefining acquisition workflows.
Industry Challenges
- Automotive Cybersecurity Engineering Talent Scarcity:Forensic laboratories compete with OEMs and Tier-1 suppliers for personnel capable of reverse-engineering embedded control unit firmware without triggering anti-tamper lockdown protocols.
- ISO 17025 Accreditation Timeline Compression:Digital forensics laboratories face 18-24 month validation cycles for automotive-specific scope extensions, delaying market entry while demand accelerates.
- Legacy Controller Area Network Integration Complexity:Pre-2020 vehicle architectures with isolated CAN bus topologies require distinct extraction methodologies from modern Ethernet-based domain controllers, fragmenting training and equipment requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Vehicle Forensics Market |
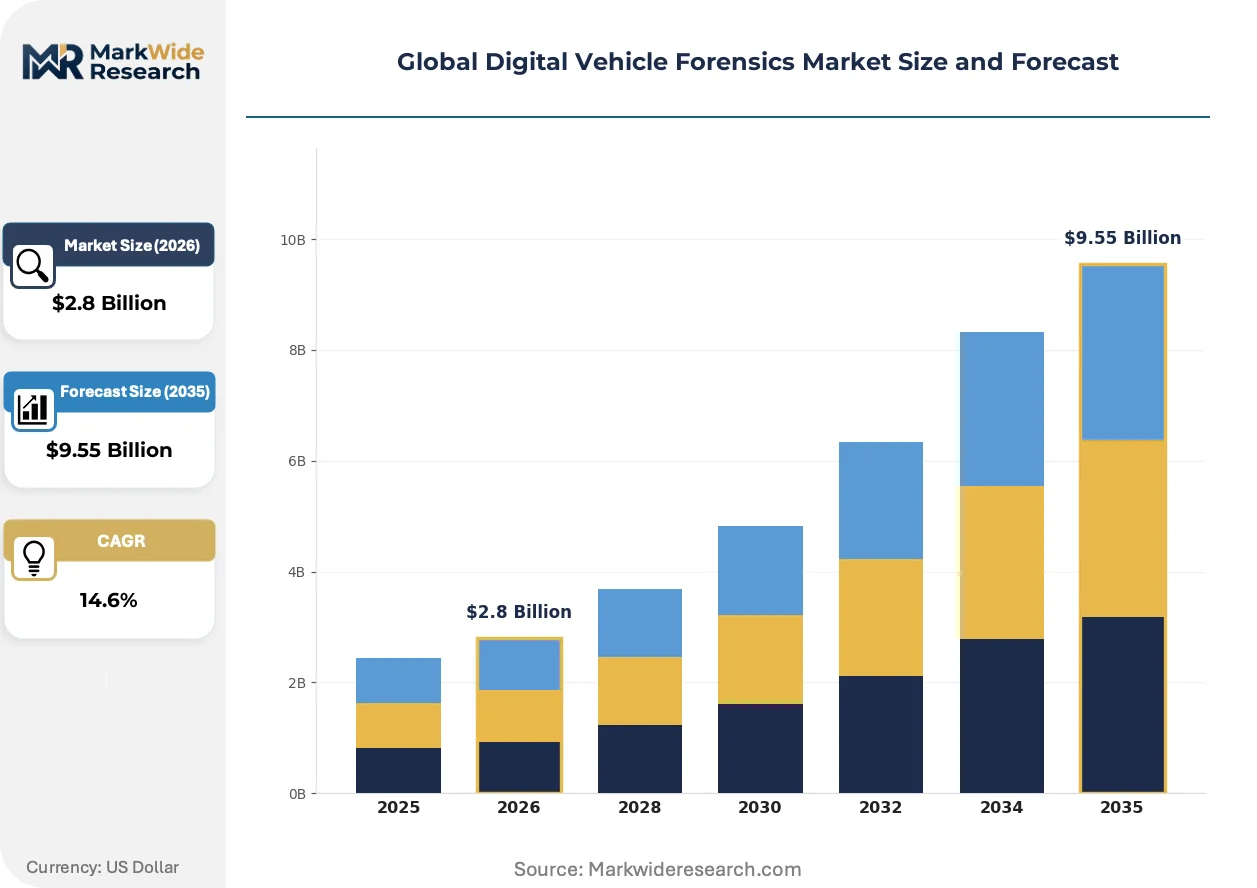
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Data Acquisition, Data Analysis, Reporting Tools, Forensic Software Application: Accident Investigation, Crime Scene Analysis, Insurance Fraud Detection, Regulatory Compliance End User: Law Enforcement, Forensic Labs, Insurance Companies, Private Investigators Service Type: Consulting, Training, Software Support, Incident Response |
| Companies Covered | Oxygen Forensics, Proven Data, Envista Forensics, Belkasoft, TechFusion, Group IB, MSAB, SUMURI, Grayshift, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Vehicle Forensics Market Emerging Trajectories
Cloud-native forensic architectures are displacing on-premise laboratory workflows as vehicle data volumes exceed local storage and processing capacities, redistributing competitive advantage toward platform vendors with elastic compute infrastructure.
Automotive-specific large language models trained on OEM diagnostic protocols and proprietary data format structures are displacing manual parsing workflows for infotainment and telematics control units. Insurance carriers in Germany and the United States are deploying these systems to accelerate preliminary evidence assessment. The technology is compressing analyst throughput requirements and reshaping staffing models for high-volume forensic service providers.
The EU AI Act's evidentiary standards for algorithmic decision-making are mandating technical documentation and audit trail preservation for advanced driver-assistance system forensics. European collision reconstruction firms must now demonstrate interpretability of neural network outputs in legal proceedings. This regulatory pressure is most acute in Germany and France, where civil liability frameworks for automated driving functions are advancing fastest, and vendors are responding with specialized ADAS logging modules.
Law enforcement procurement in the United States is consolidating around multi-agency shared service agreements for forensic platform access, displacing individual department capital expenditure models. State police organizations in California, Texas, and Florida are negotiating enterprise licenses with volume-tiered pricing structures. This behavioral shift concentrates buyer power and favors vendors with dedicated government contracting divisions and FedRAMP-authorized cloud infrastructure.
Global Digital Vehicle Forensics Market Segmentation
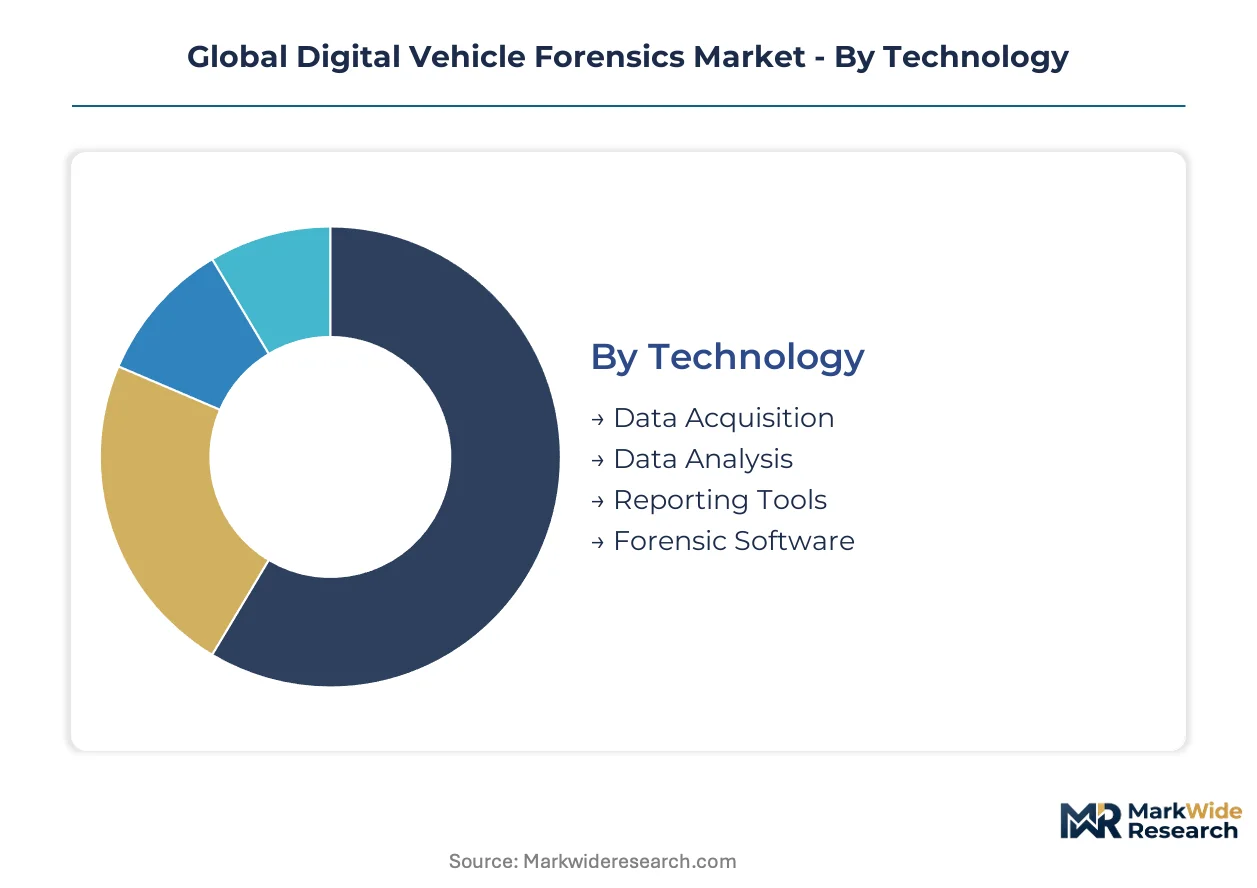
Segmentation in the Global Digital Vehicle Forensics Market reveals divergent margin structures across technology layers and service delivery models. Vendors must calibrate portfolio investments against distinct procurement cycles, certification requirements, and customer sophistication levels that vary sharply by segment.
Technology:
Margin pools concentrate most heavily in proprietary parsing engines that decode OEM-specific encryption, while hardware acquisition tools face commoditization pressure from Taiwanese component suppliers.
- Data Acquisition:Write-blocking hardware and physical extraction interfaces preserve evidentiary integrity during raw bitstream capture from control modules. Law enforcement agencies in the United States and Germany drive procurement through NHTSA-mandated preservation standards and KBA crash investigation protocols.
- Forensic Software:Advanced parsing platforms reverse-engineer proprietary OEM data formats for infotainment and telematics systems. Insurance carriers in Germany and the United States deploy these tools for automated anomaly detection across connected vehicle telemetry streams.
- Data Analysis:Pattern recognition engines reconstruct collision sequences from sensor fusion logs.
- Reporting Tools:Chain-of-custody documentation systems generate court-admissible evidence packages.
The dominant share belongs to Data Acquisition, while Forensic Software is closing the gap fastest.
Application:
Revenue stability varies sharply by application, with government-contracted accident reconstruction offering predictable cash flows versus insurance fraud detection's emerging volatility.
- Accident Investigation:Collision reconstruction from event data recorders and ADAS sensor logs supports criminal and civil proceedings. NHTSA-mandated preservation standards in the United States and EU AI Act chain-of-custody requirements in Germany sustain steady procurement cycles.
- Insurance Fraud Detection:Automated telemetry analysis identifies staged accidents and odometer manipulation through connected vehicle data streams. German and U.S. carriers are deploying machine learning models to flag anomalies before claim payout.
- Crime Scene Analysis:Infotainment system extraction recovers location history and communication metadata.
- Regulatory Compliance:GB-standard cybersecurity reviews in China and GDPR documentation mandates in Europe drive audit trail preservation.
Accident Investigation commands the largest revenue base, though Insurance Fraud Detection is expanding most quickly as carriers automate claims verification.
End User:
Procurement sophistication diverges dramatically, with forensic laboratories demanding ISO 17025-validated platforms while private investigators prioritize cost-minimizing entry-level tools.
- Law Enforcement:Police digital evidence units require roadside-capable extraction hardware with validated chain-of-custody workflows. Multi-agency shared service agreements in California, Texas, and Florida are consolidating buyer power around enterprise licensing structures.
- Forensic Labs:ISO 17025-accredited facilities perform deep technical analysis for criminal proceedings. Accreditation timelines of 18-24 months for automotive scope extensions create capacity constraints amid surging demand.
- Insurance Companies:Carrier forensic units process high-volume claim investigations with automated triage systems.
- Private Investigators:Individual practitioners serve civil litigation with limited-budget tool configurations.
Law Enforcement retains the dominant procurement volume, yet Forensic Labs are gaining share fastest through accreditation-driven quality differentiation.
Service Type:
Recurring revenue intensity distinguishes service models, with software support subscriptions offering superior predictability versus incident response's episodic revenue spikes.
- Software Support:Continuous update services for OEM format parsers and encryption bypass methods. Vendors like MSAB monetize through annual maintenance contracts tied to new vehicle model releases from Volkswagen Group and Toyota Motor.
- Training:Certification programs for forensic analysts on proprietary extraction methodologies. Brazilian Federal Highway Police expansion is creating demand for Portuguese-language instructional capacity.
- Consulting:Advisory services for laboratory accreditation and workflow design.
- Incident Response:Emergency deployment for time-critical evidence preservation.
Software Support generates the steadiest recurring revenue, while Training is climbing fastest on accreditation backlog and geographic expansion requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Law enforcement digital evidence units and insurance litigation departments concentrate procurement across five national markets where connected vehicle architectures and regulatory mandates intersect most acutely.
United States
NHTSA crash investigations and multi-agency shared service agreements in California, Texas, and Florida drive enterprise licensing demand for roadside-capable extraction platforms. Federal preservation standards for event data recorders compel recurring procurement cycles. Forensic laboratories in the Washington-Baltimore corridor specialize in ADAS sensor fusion reconstruction for civil litigation.
Germany
KBA crash investigation protocols and EU AI Act chain-of-custody requirements sustain ISO 17025 accreditation demand among automotive forensic providers. The country's automotive cybersecurity engineering talent scarcity intensifies competition between forensic laboratories and OEMs for embedded control unit specialists. Bavarian digital evidence units lead European adoption of cloud-native forensic architectures.
Japan
METI-connected vehicle initiatives and proprietary OEM encryption architectures from Toyota Motor and Honda Motor create localized parsing module development requirements. Japanese insurance carriers deploy automated telemetry anomaly detection for claims verification. Tokyo-based forensic service providers concentrate on infotainment system extraction for criminal proceedings.
Brazil
Federal Highway Police digital expansion and absence of indigenous forensic platform capacity create first-mover opportunity for ISO 17025-accredited laboratories establishing Portuguese-language operations. ANVISA-equivalent automotive data governance remains under development, reducing compliance friction for international platform entry. São Paulo state police organizations pilot roadside extraction workflows for commercial vehicle accidents.
China
MIIT enforces GB-standard cybersecurity review for foreign forensic software processing domestic vehicle data, creating localized compliance barriers. Domestic OEMs BYD and NIO deploy distinct cryptographic protocols resistant to standardized bypass methods. Shanghai-based forensic technology clusters focus on regulatory compliance documentation for connected vehicle data exports.
Global Digital Vehicle Forensics Market Vendor Landscape
Player mix skews toward specialized forensic technology developers with deep OEM parsing capabilities rather than diversified IT conglomerates. Market structure concentrates around three tiers: hardware-software bundle providers serving law enforcement, ISO 17025-accredited laboratory service operators, and cloud-native platform vendors processing telemetry at scale. Strategic differentiation runs through proprietary encryption bypass methods, accreditation-driven quality positioning, and multi-agency government contracting relationships.
Within the specialized forensic technology tier, Oxygen Forensics, MSAB, and Grayshift exemplify distinct geographic and channel positioning strategies. Oxygen Forensics represents European-Asian platform specialization with emphasis on infotainment and telematics control unit parsing. MSAB occupies a position anchored in Nordic automotive architecture expertise with dedicated R&D into proprietary OEM encryption methodologies. Grayshift anchors North American law enforcement channel access through hardware-software bundles optimized for roadside extraction workflows.
| Leading Market Players |
|---|
| Oxygen Forensics |
| Proven Data |
| Envista Forensics |
| Belkasoft |
| TechFusion |
| Group IB |
| MSAB |
| SUMURI |
| Grayshift |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month lead times for ISO 17025 automotive scope extensions concentrate pricing power among accredited laboratories while compressing margins for uncertified competitors scrambling to meet NHTSA preservation standards and EU AI Act chain-of-custody mandates.
Pricing Analysis
Cost-plus contracts with semiconductor foundry indexation dominate write-blocking hardware procurement, tethering forensic equipment manufacturers to Taiwanese wafer pricing volatility. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-accredited deep parsing services from roadside extraction bundles and entry-level investigator tools. Cost compression in hardware acquisition tiers is intensifying because Taiwanese component suppliers expand capacity. Private investigators exhibit highest price sensitivity, while forensic laboratories prioritize certification grade over unit cost.
Supply Chain Analysis
Taiwan Strait transit exposure concentrates single-source vulnerability for write-blocking controller semiconductors, forcing forensic hardware vendors to absorb geopolitical risk premiums. Manufacturing draws from Taiwan, South Korea, and Germany for specialized acquisition components, with proprietary OEM parsing modules developed in Sweden and the United States. Supply chain risk centers on regulatory restriction as China's MIIT enforces GB-standard cybersecurity review for foreign software processing domestic vehicle data. Distribution runs through law enforcement procurement channels and multi-agency shared service agreements in California, Texas, and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern as NHTSA-mandated preservation standards and EU AI Act compliance deadlines synchronize replacement procurement waves across government digital evidence units.
For Market Incumbents: Fortify ISO 17025 accreditation moats by accelerating automotive scope extensions before 18-24 month validation backlogs worsen. Deepen proprietary OEM encryption bypass R&D to resist cloud-native platform entrants attacking the forensic software margin pool. Channel control through FedRAMP-authorized infrastructure and dedicated government contracting divisions anchors enterprise licensing dominance.
For New Entrants and Emerging Players: Differentiate on Portuguese-language service delivery for Brazilian Federal Highway Police digital expansion, where indigenous forensic platform capacity remains absent. Target insurance carrier telemetry anomaly detection as the most penetrable segment, with automated fraud identification systems processing connected vehicle data streams distinct from saturated accident reconstruction markets. Pursue ISO 17025 laboratory partnerships as the fastest go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance play because NHTSA, EU AI Act, and GDPR mandates institutionalize recurring procurement regardless of vehicle sales cycles. Acquisition target archetype: ISO 17025-accredited laboratories with proven OEM parsing capabilities and established law enforcement channel relationships. Watch cloud-native forensic platform adoption rates as the inflection signal indicating workflow displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| OEM Encryption Bypass R&D Investment | Proprietary parsing capabilities defend margins against cloud-native entrants attacking forensic software tiers. |
| ISO 17025 Automotive Scope Extension | Accreditation backlog creates 18-24 month capacity constraints that concentrate pricing power among certified providers. |
| FedRAMP Cloud Infrastructure Authorization | Multi-agency shared service agreements in California, Texas, and Florida require government-grade security compliance. |
| Brazilian Portuguese-Language Service Launch | Federal Highway Police expansion lacks indigenous forensic platform capacity, offering first-mover positioning. |
| Insurance Carrier Telemetry Partnership | Automated anomaly detection for fraud identification represents emerging application segment beyond accident reconstruction. |
Methodological Framework
Initial hypotheses were tested against primary input from digital evidence unit commanders, forensic laboratory directors, insurance carrier claims executives, and OEM cybersecurity engineers and refined through secondary validation against NHTSA EDR preservation standards, EU AI Act technical documentation requirements, and vehicle production databases from IHS Markit. Bottom-up triangulation across law enforcement procurement records and top-down reconciliation against connected vehicle telemetry expansion estimates anchored market sizing.
Variance decomposition across technology, application, end user, and service type dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated OEM proprietary encryption proliferation rates and ISO 17025 accreditation pipeline constraints specific to automotive digital forensics.
Material uncertainties — OEM encryption protocol fragmentation, Taiwanese semiconductor supply disruption, and GDPR cross-border transfer friction — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and cloud-native platform displacement velocity. Revision becomes warranted when multi-agency shared service agreement penetration crosses thresholds indicating consolidated buyer power sufficient to restructure vendor pricing terms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Sound Masking Systems Market
Security Software
Global Email Verification Tools Market
Security Software
Identity and Access Management (IAM) Market
Security Software
Online Background Check Market
Security Software
Data Privacy Software Market
Security Software
Website Monitoring Software Market
Security Software
Robocall Mitigation Market
Security Software
Identity-As-A-Service (Idaas) Market
Security Software
Stalkerware Market
Security Software
Global Data Protection As a Service (Dpaas) Market
Security Software
ATM Security Market
Security Software
Global Consumer IAM Market
Security Software
Embedded Security Market
Security Software
Endpoint Detection and Response Market
Security Software
Security Software for Consumers Market
Security Software
Global Hardware Security Modules (HSM) Market