
 Activated Alumina Market | 2026-2036
Activated Alumina Market Size, Share, and Industry Trends Forecast 2026-2036
Activated Alumina Market Analysis
Maintenance contracts for adsorbent bed replacement and regeneration services is hardening as a recurring revenue stream for suppliers. BASF SE leverages its integrated alumina supply chain to control feedstock costs across European and North American operations. Honeywell International Inc. anchors its position through proprietary activation kiln technology that yields consistent pore volume distribution. Sumitomo Chemical Co., Ltd. competes on high-purity grades tailored to electronics-grade air drying systems.
Activated alumina is a porous, granular form of aluminum oxide manufactured by controlled thermal dehydration of aluminum hydroxide, typically achieving surface areas between 200 and 400 square meters per gram and pore diameters optimized for selective adsorption. The material functions primarily as a desiccant, catalyst support, and adsorptive medium for fluoride removal and hydrocarbon purification in industrial process streams. Desiccant-grade material occupies the largest volume position due to saturated demand from compressed air systems and natural gas dehydration infrastructure. Catalyst support applications represent the fastest-expanding margin pool as refiners upgrade hydroprocessing units to handle heavier crude slates. Water purification demand is concentrating in municipal treatment retrofits where legacy media replacements favor higher-capacity alumina formulations over conventional alternatives.
EPA regulations under the Safe Drinking Water Act set maximum contaminant levels for fluoride and arsenic that directly specify activated alumina as a best available technology for small community systems. NSF/ANSI Standard 61 certification governs product contact safety for municipal water applications, creating a compliance barrier for unqualified suppliers. REACH registration requirements in Europe impose full substance toxicity dossiers on alumina importers, raising documentation costs for non-European manufacturers. Stakeholders must monitor regulatory divergence between EPA and ECHA hazard classifications that could fragment product formulations across Atlantic markets.
Market Dynamics
EPA drinking water standards and tightening NSF/ANSI certification requirements are compressing supplier margins while simultaneously erecting barriers to unqualified competitors, creating a bifurcation between certified and non-certified supply tiers.
Growth Catalysts
- Safe Drinking Water Act compliance:EPA maximum contaminant levels for fluoride and arsenic designate activated alumina as best available technology for small community water systems, mandating media replacement cycles.
- Electronics manufacturing expansion:Semiconductor fabs and battery dry rooms require ultra-low dew point air drying, driving specification upgrades to high-purity desiccant grades.
- Natural gas infrastructure buildout:LNG export terminals and shale gas processing facilities in the United States and China require dehydration capacity for pipeline specification compliance.
Market Restraints
- Feedstock cost volatility:Aluminum hydroxide prices track bauxite mining output and alumina smelter capacity utilization, compressing activation kiln operators during energy price spikes.
- Substitution by molecular sieves:Zeolite 3A and 4A materials capture share in compressed air drying where regeneration energy costs dominate lifecycle economics.
- REACH registration burden:ECHA substance toxicity dossier requirements impose documentation costs on non-European manufacturers seeking EU market access.
Strategic Opportunities
- India municipal water retrofits:BIS drinking water standards adoption and Smart Cities Mission funding create replacement demand for legacy filtration media in tier-2 urban centers.
- Biogas upgrading systems:Siloxane and hydrogen sulfide removal from landfill gas and anaerobic digesters represents an emerging adsorption application with limited incumbent suppliers.
- Regenerable service models:Spent alumina take-back and thermal reactivation programs convert capital equipment sales into recurring revenue streams with embedded customer lock-in.
Industry Challenges
- Activation kiln operator scarcity:Precise temperature profiling and pore volume control require specialized thermal process engineers, constraining capacity expansion at mid-tier producers.
- NSF/ANSI Standard 61 certification timelines:Municipal water product contact safety approvals extend 12-18 months, delaying market entry for reformulated or new-source materials.
- Legacy system integration friction:Existing pressure vessel designs and flow distribution hardware limit adoption of higher-capacity alumina formulations without capital-intensive vessel replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Activated Alumina Market |
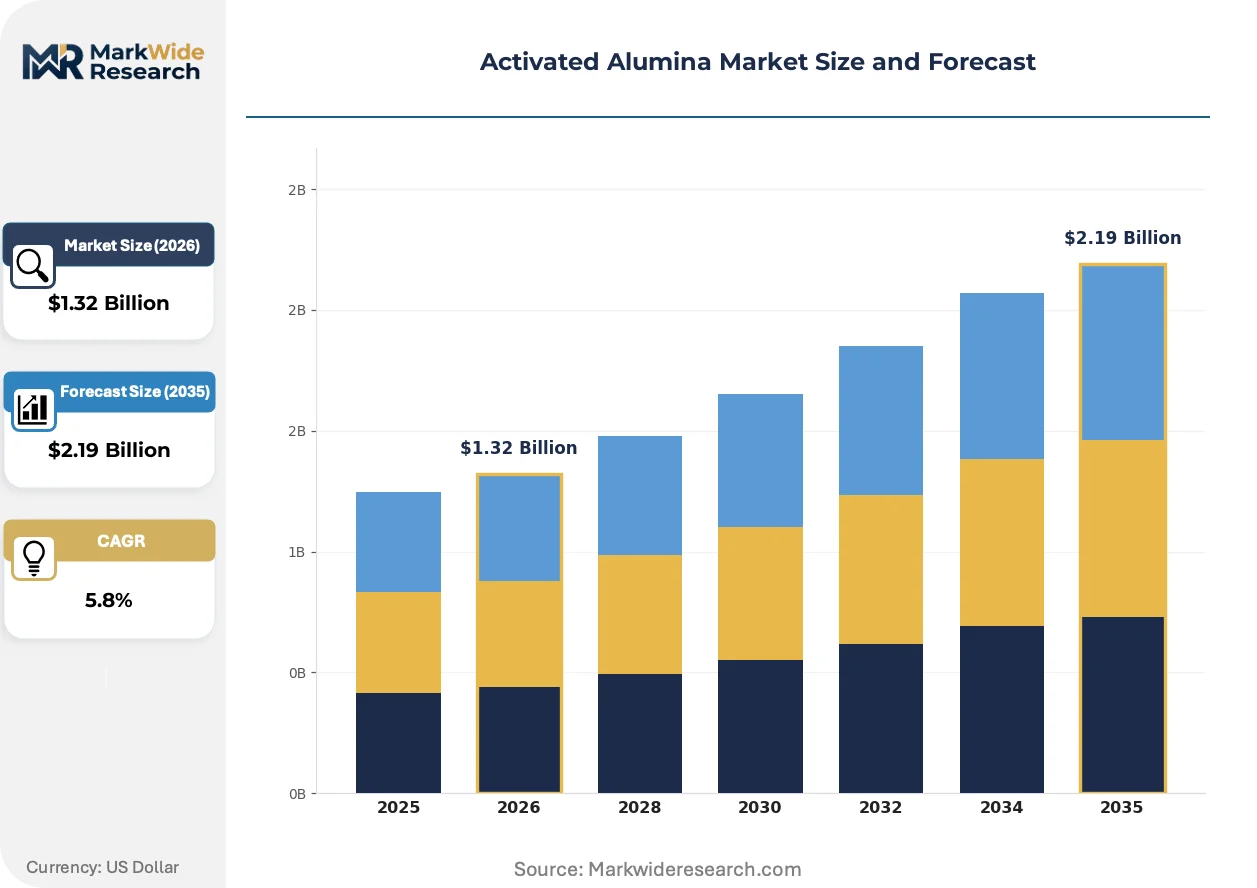
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.19 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desiccants, Catalyst Supports, Water Purification, Fluoride Adsorption Application: Air Drying, Oil & Gas Processing, Chemical Manufacturing, Wastewater Treatment End User: Pharmaceuticals, Food & Beverages, Petrochemicals, Electronics Form: Granular, Powder, Pellets, Tablets |
| Companies Covered | BASF SE, Honeywell International Inc., Sumitomo Chemical Co., Ltd., Huber Engineered Materials, Axens, Evonik Industries AG, Porocel Industries LLC, AGC Chemicals Pvt. Ltd., Sorbead India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Activated Alumina Market Emerging Trajectories
Process intensification in activation kilns and digital moisture monitoring are compressing operating margins for conventional suppliers while rewarding technology-differentiated competitors with premium positioning.
Advanced activation protocols using precisely controlled steam injection during thermal dehydration are rewriting pore architecture specifications for catalyst support grades. Refiners upgrading hydroprocessing units to handle heavier crude slates specify these materials for improved metals tolerance and longer cycle lengths. The structural consequence is a margin compression for commodity desiccant producers unable to meet electronics and refining purity thresholds.
REACH registration requirements in Europe impose full substance toxicity dossiers on alumina importers, raising documentation costs for non-European manufacturers. ECHA hazard classification divergence from EPA frameworks fragments product formulations across Atlantic markets. Catalyst support suppliers serving both jurisdictions face dual compliance testing burdens that smaller competitors cannot absorb.
Service contracting for adsorbent bed replacement and regeneration is displacing spot procurement of virgin material in municipal water and industrial gas applications. Utilities and compressed air operators in Germany and the United States favor performance-guaranteed supply agreements with embedded technical service. The shift concentrates procurement authority with integrated suppliers capable of field logistics and waste handling compliance.
Activated Alumina Market Segmentation
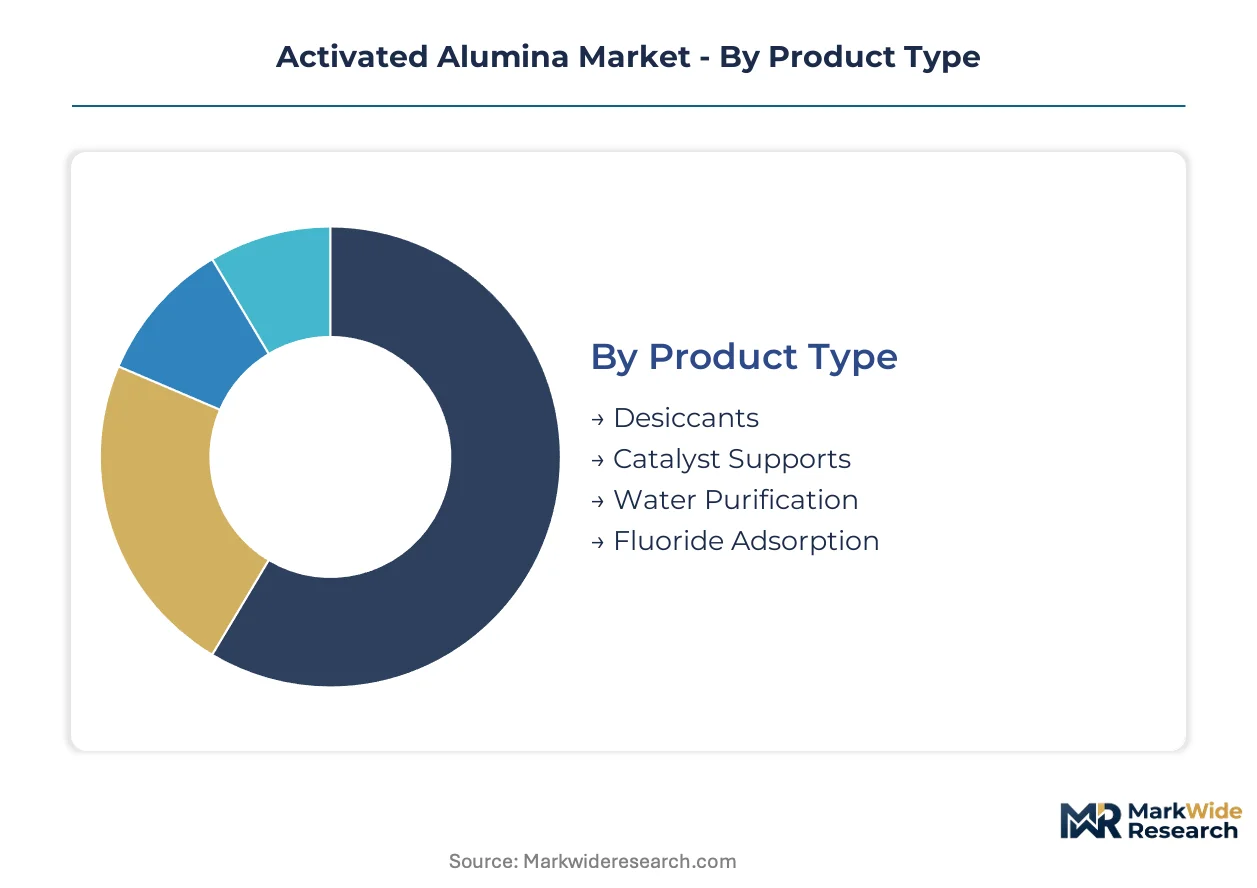
Activated alumina suppliers configure production lines around pore volume specifications and thermal activation profiles that lock in performance characteristics for target applications. Segmentation discipline separates commodity desiccant producers from specialists commanding premium positioning in catalyst support and high-purity grades.
Product Type:
Standardization dominates commodity desiccant production while catalyst support and water purification grades demand customized pore architecture and contaminant loading specifications.
- Desiccants:Thermal dehydration of aluminum hydroxide yields surface areas between 200 and 400 square meters per gram optimized for moisture adsorption in compressed air systems and natural gas dehydration infrastructure. Demand concentrates in United States shale gas processing facilities and China LNG terminals where pipeline moisture specifications mandate consistent dew point performance.
- Catalyst Supports:Controlled steam injection during activation creates pore structures engineered for metals tolerance and hydroprocessing cycle lengths in refinery upgrading units. Refiners in Germany and the United States specify these materials for heavier crude slate handling, driving specification upgrades that commodity producers cannot match.
- Water Purification:EPA-designated best available technology for fluoride and arsenic removal in small community systems under Safe Drinking Water Act compliance.
- Fluoride Adsorption:Municipal treatment retrofits in India and United States tier-2 cities favor higher-capacity alumina formulations over conventional alternatives.
Leading the category by volume: Desiccants. Expanding most quickly: Catalyst Supports.
Application:
Volume concentration in industrial gas processing contrasts with margin concentration in precision manufacturing environments requiring ultra-low moisture specifications.
- Air Drying:Semiconductor fabs and battery dry rooms require ultra-low dew point specifications that drive demand for high-purity desiccant grades with consistent pore volume distribution. Electronics manufacturing clusters in China and Germany anchor specification upgrades as legacy compressed air systems face replacement cycles.
- Oil & Gas Processing:Natural gas dehydration for pipeline specification compliance and LNG export terminal operations represents the largest volume application with established supplier relationships and long-term service contracting models.
- Chemical Manufacturing:Hydrocarbon purification and process stream drying in petrochemical complexes require regeneration-compatible alumina formulations.
- Wastewater Treatment:Municipal fluoride and arsenic removal systems drive replacement demand as EPA maximum contaminant levels tighten compliance thresholds.
Air Drying commands premium pricing. Oil & Gas Processing moves the most tonnage.
End User:
Regulatory intensity and contamination risk tolerance create three distinct procurement tiers across end-use verticals.
- Pharmaceuticals:FDA-regulated manufacturing environments require validated desiccant grades with documented batch consistency and extractables testing for product contact applications.
- Food & Beverages:NSF/ANSI certification requirements for product contact safety create compliance barriers that filter supplier qualification.
- Petrochemicals:Refinery hydroprocessing units and ethylene production facilities represent the largest integrated demand base with multi-year catalyst support supply agreements.
- Electronics:Semiconductor and battery manufacturing specifications for ultra-low moisture drive the most stringent purity requirements and highest margin positioning.
Petrochemicals dominate volume procurement. Electronics sets the purity benchmark.
Form:
Physical configuration determines pressure drop characteristics and regeneration efficiency in fixed-bed adsorption systems.
- Granular:Irregular particle geometry optimized for high surface area exposure in liquid-phase applications including water purification and wastewater treatment where pressure drop tolerance permits loose-packed bed configurations.
- Powder:Fine particle size distribution for specialized catalyst support applications requiring intimate contact with active metal phases.
- Pellets:Uniform cylindrical geometry engineered for low pressure drop and consistent flow distribution in compressed air and natural gas dehydration vessels.
- Tablets:High-density compression for applications requiring mechanical strength and minimal attrition during thermal cycling.
Pellets lead in gas-phase industrial applications. Granular formulations anchor liquid-phase treatment systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the most concentrated activated alumina demand cluster globally, hosting the largest concentration of natural gas processing infrastructure and refinery hydroprocessing units in North America.
United States
EPA Safe Drinking Water Act compliance drives municipal water system retrofits in tier-2 cities across Texas and Ohio. The agency's maximum contaminant levels for fluoride and arsenic mandate activated alumina as best available technology for small community systems. The Permian Basin and Gulf Coast petrochemical corridor generate sustained desiccant demand from shale gas dehydration and LNG export terminal operations.
China
LNG terminal buildouts along the Yangtze River Delta and Pearl River Delta require massive dehydration capacity for pipeline specification compliance. MEE environmental standards tighten emissions controls on industrial gas processing facilities. Semiconductor fabrication clusters in Shanghai and Shenzhen drive specification upgrades to high-purity desiccant grades for ultra-low dew point air drying systems.
Germany
REACH registration requirements impose full substance toxicity dossiers on alumina importers, raising documentation costs for non-European manufacturers. ECHA hazard classification frameworks diverge from EPA standards, fragmenting product formulations. The Rhine-Ruhr industrial belt and Bavarian chemical parks anchor catalyst support demand from refinery hydroprocessing upgrades handling heavier crude slates.
India
BIS drinking water standards adoption and Smart Cities Mission funding create replacement demand for legacy filtration media. The central government's Jal Jeevan Mission accelerates municipal treatment infrastructure deployment. Industrial corridors in Gujarat and Maharashtra concentrate petrochemical and pharmaceutical manufacturing that requires validated desiccant grades for process stream drying.
Activated Alumina Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the activated alumina value chain. Integrated alumina smelters and activation kiln operators control feedstock access and thermal process capabilities, while specialized fabricators focus on formulation chemistry and application engineering. Three archetypes dominate: diversified chemical conglomerates with captive bauxite supply, mid-tier activation specialists serving regional industrial gas markets, and application-focused purveyors of certified water treatment grades. Consolidation pressure operates through backward integration into bauxite mining and forward integration into regeneration service contracting.
Within the diversified chemical tier, BASF SE and Evonik Industries AG exemplify integrated supply chain control spanning European and North American operations. Honeywell International Inc. occupies a position emphasizing proprietary thermal processing capabilities, while Sumitomo Chemical Co., Ltd. anchors the high-purity specialty segment serving electronics-grade specifications. Mid-tier activation specialists including Porocel Industries LLC and Sorbead India sit within regional service networks, and Huber Engineered Materials represents the engineered materials archetype with cross-sector mineral processing expertise.
| Leading Market Players |
|---|
| BASF SE |
| Honeywell International Inc. |
| Sumitomo Chemical Co., Ltd. |
| Huber Engineered Materials |
| Axens |
| Evonik Industries AG |
| Porocel Industries LLC |
| AGC Chemicals Pvt. Ltd. |
| Sorbead India |
| Others |
Supply Flow & Price Mechanics
Municipal water utilities in the United States and Germany are consolidating procurement around NSF/ANSI-certified suppliers, forcing mid-tier activation kiln operators to absorb certification costs or exit the certified tier entirely. This buyer consolidation concentrates pricing power with integrated producers capable of spanning formulation chemistry, thermal processing, and field service logistics.
Pricing Analysis
Margin tightening in commodity desiccant grades reflects bauxite cost volatility and energy price spikes at European smelters. Three-tier pricing structure across premium catalyst support, standard desiccant, and economy water treatment grades separates certified from non-certified supply. Electronics-grade specifications command the least price sensitivity due to ultra-low dew point requirements. Municipal procurement in India and tier-2 U.S. cities shows highest price elasticity, favoring spot purchasing over service contracting.
Supply Chain Analysis
Domestic-content mandates in China's MEE environmental standards and India's Smart Cities Mission are reshaping sourcing toward local activation kiln capacity. Feedstock supply concentrates in Australia, Guinea, and Brazil for bauxite mining, with aluminum hydroxide processing anchored in China and the United States. Activation kiln operations draw from natural gas and electricity inputs, exposing margin structures to energy price volatility. Distribution runs through regional industrial gas distributors and direct municipal utility contracts. Single-source vulnerability sits with specialized thermal process engineers capable of precise pore volume control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: activation kiln operator scarcity limits capacity expansion and props pricing for qualified producers. The bottleneck concentrates returns with incumbents possessing captive thermal processing expertise.
For Market Incumbents: Anticipate molecular sieve substitution in compressed air drying by embedding regeneration service contracts that lock in multi-year offtake. BASF and Honeywell should deepen backward integration into bauxite supply to buffer feedstock volatility. Certification investment in India BIS standards captures Jal Jeevan Mission deployment before mid-tier competitors qualify. For New Entrants and Emerging Players: EPA Safe Drinking Water Act compliance in the United States opens a window for regional activation specialists to capture tier-2 municipal retrofits bypassed by national distributors. Biogas upgrading systems for siloxane removal represent the most penetrable white-space application with limited incumbent presence. A go-to-market angle anchored in spent alumina take-back and thermal reactivation converts capital sales into recurring revenue with embedded customer lock-in. For Investors and Strategic Acquirers: The window for entry favors mid-tier activation specialists with proven kiln technology and regional service networks over commodity chemical conglomerates. Long-term viability hinges on regeneration service model adoption and electronics-grade purity capabilities. Watch for EPA-ECHA hazard classification divergence as the inflection signal that fragments formulation requirements and rewards dual-jurisdiction testing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Supply | Captive feedstock access insulates BASF and Evonik from alumina smelter capacity volatility. |
| Regeneration Service Contracting | Spent alumina take-back programs convert Honeywell's kiln technology into recurring municipal utility revenue. |
| Electronics-Grade Purity Investment | Sumitomo's high-purity positioning captures semiconductor fab specification upgrades in Shanghai and Shenzhen. |
| India BIS Certification | Early qualification under Jal Jeevan Mission locks in tier-2 city replacement cycles before competitors enter. |
| Biogas Upgrading Application Development | Limited incumbent presence in siloxane removal creates first-mover advantage for specialized activation protocols. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with activation kiln operators, municipal procurement officers, and refinery catalyst buyers combined with EPA enforcement databases, ECHA registration dossiers, and BIS standard notifications. SEC 10-K disclosures from diversified chemical conglomerates and ACC sector reports provided capacity and margin data. Bottom-up segment modeling triangulated against top-down macroeconomic drivers across the analysis window.
Granularity-level modeling operated at product type, application, and end-user dimensions with regional production hub disaggregation. Catalyst support, desiccant, and water purification grades were projected separately. Electronics-grade purity thresholds and municipal certification requirements served as demand-side segmentation anchors. CAGRs derived from regression analysis against industrial gas processing capacity additions and semiconductor fabrication buildouts.
Caveats apply where EPA-ECHA regulatory divergence or aluminum hydroxide price spikes could materially shift the outlook. Forecasts reflect assumptions about activation kiln capacity expansion and municipal procurement consolidation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramics Market
Ceramics
Malaysia Ceramic Tiles Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
Cerium Carbonate Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Construction Ceramics Market
Ceramics
Cordierite Market
Ceramics
Advanced Structural Ceramics Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
Philippines Ceramic Tiles Market
Ceramics
Low Density Ceramic Proppant Market
Ceramics
White Fused Alumina Market
Ceramics
Ceramic Tiles Market
Ceramics
Ceramic Setter Plate Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
South Korea Ceramic Sanitaryware Market