
 Spain Avocado Market | 2026-2036
Spain Avocado Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Avocado Market Insights
Subscription-based ripening-as-a-service is consolidating how Spanish retailers manage avocado shelf life and waste. Trops leverages integrated cold-chain logistics from Malaga to northern European ports. Frutas Montosa anchors its position through varietal specialization in Hass and organic lines. Grupo Cuevas differentiates via controlled-atmosphere storage investments that extend selling windows.
An avocado is a climacteric berry with oil content ranging from fifteen to thirty percent at maturity, harvested firm and ripened post-harvest for fresh consumption or oil extraction. Hass dominates Spanish plantings due to its thick peel, extended shelf stability, and year-round production potential across coastal microclimates. Fuerte retains significance in organic channels where its thinner skin suits minimal-processing retail packs, while Bacon and Zutano occupy processing segments for oil and frozen pulp. Supermarkets command the largest volume channel, though online retail records the fastest expansion as quick-commerce platforms add fresh produce categories.
Spain's Ministry of Agriculture enforces EU Plant Health Regulation compliance for imported propagation material, while BSI-equivalent national standards govern pesticide residue thresholds under EU MRL harmonization. The EU Green Deal Farm-to-Fork strategy tightens input restrictions, pushing growers toward integrated pest management and water-efficient irrigation. Stakeholders must monitor drought contingency planning under the Guadalquivir River basin authority, as water allocation disputes between agriculture and urban users intensify.
Market Dynamics
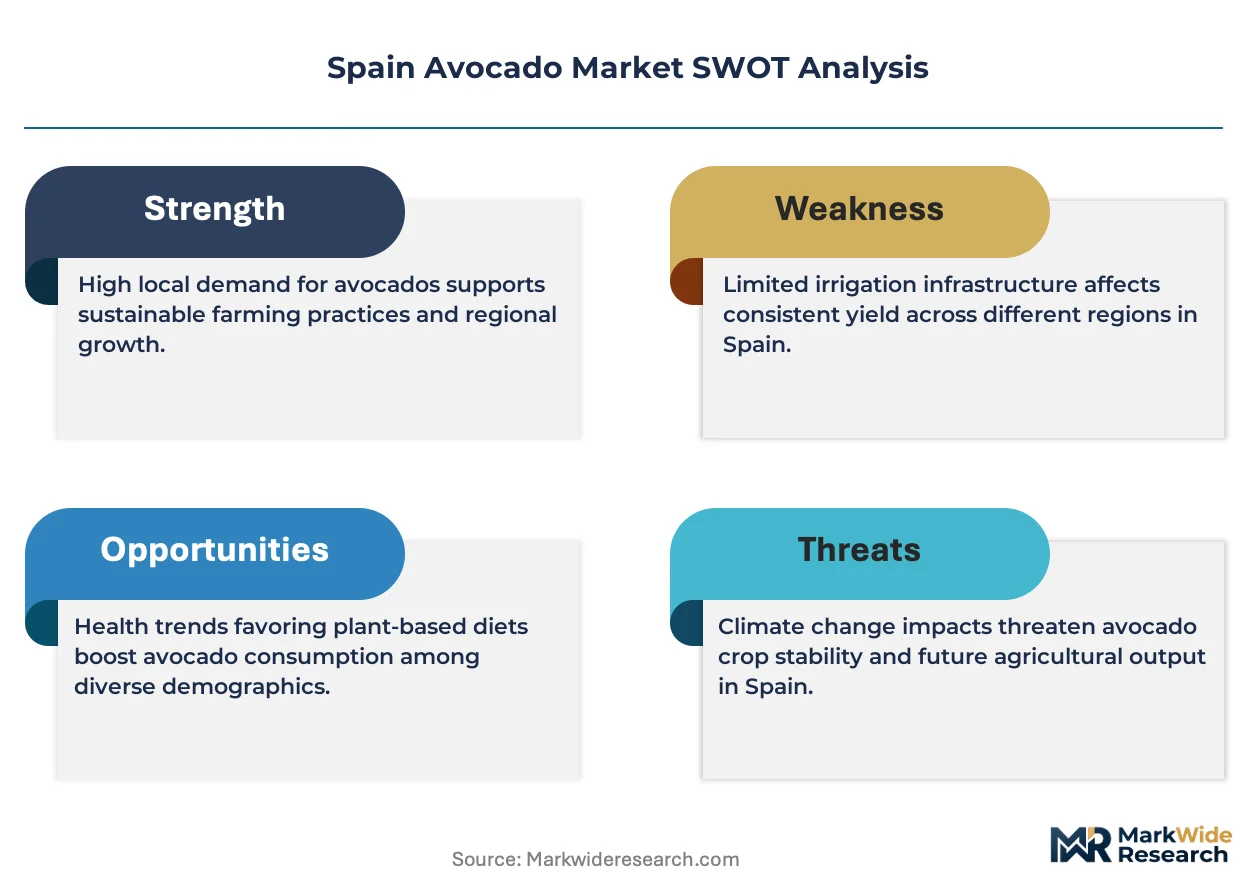
Spain's avocado sector faces acute water stress under the Guadalquivir River basin authority's allocation caps, forcing growers to recalibrate irrigation intensity and varietal selection while competing with urban demand centers for scarce resources.
Growth Catalysts
- EU Green Deal Farm-to-Fork strategy:Input restriction mandates accelerate integrated pest management adoption and certified organic hectare expansion across Andalusian growing zones.
- Quick-commerce platforms:Glovo and similar services add fresh produce categories, compressing delivery windows and expanding addressable demand for ripe-ready avocados.
- Ripening-as-a-service infrastructure:Subscription cold-chain models reduce retailer shrinkage and extend selling windows through controlled ethylene management.
Market Restraints
- Guadalquivir basin water allocation disputes:Agricultural quotas face downward pressure from Seville and Malaga municipal demand, constraining expansion of irrigated hectare capacity.
- Propagation material import barriers:EU Plant Health Regulation compliance requirements for rootstock and scion material create multi-year varietal conversion timelines.
- Olive oil price volatility:Competing Mediterranean oil crops capture processing margin when avocado oil extraction economics weaken.
Strategic Opportunities
- Basque Country and Catalonia foodservice corridors:Underpenetrated northern Spanish markets show accelerating per-capita consumption in premium restaurant and café channels.
- EU organic certification premium:National organic framework alignment creates price differentiation for certified growers supplying German and Dutch retail.
- Controlled-atmosphere storage convergence:Integration of modified atmosphere technology with ripening services enables year-round supply consistency for export markets.
Industry Challenges
- Phytosanitary technician scarcity:Specialized expertise in Xylella fastidiosa monitoring and integrated pest management remains concentrated in coastal Andalusia.
- BSI-equivalent residue testing compliance:Batch certification timelines create cash-flow friction for smallholder cooperatives seeking supermarket supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Avocado Market |
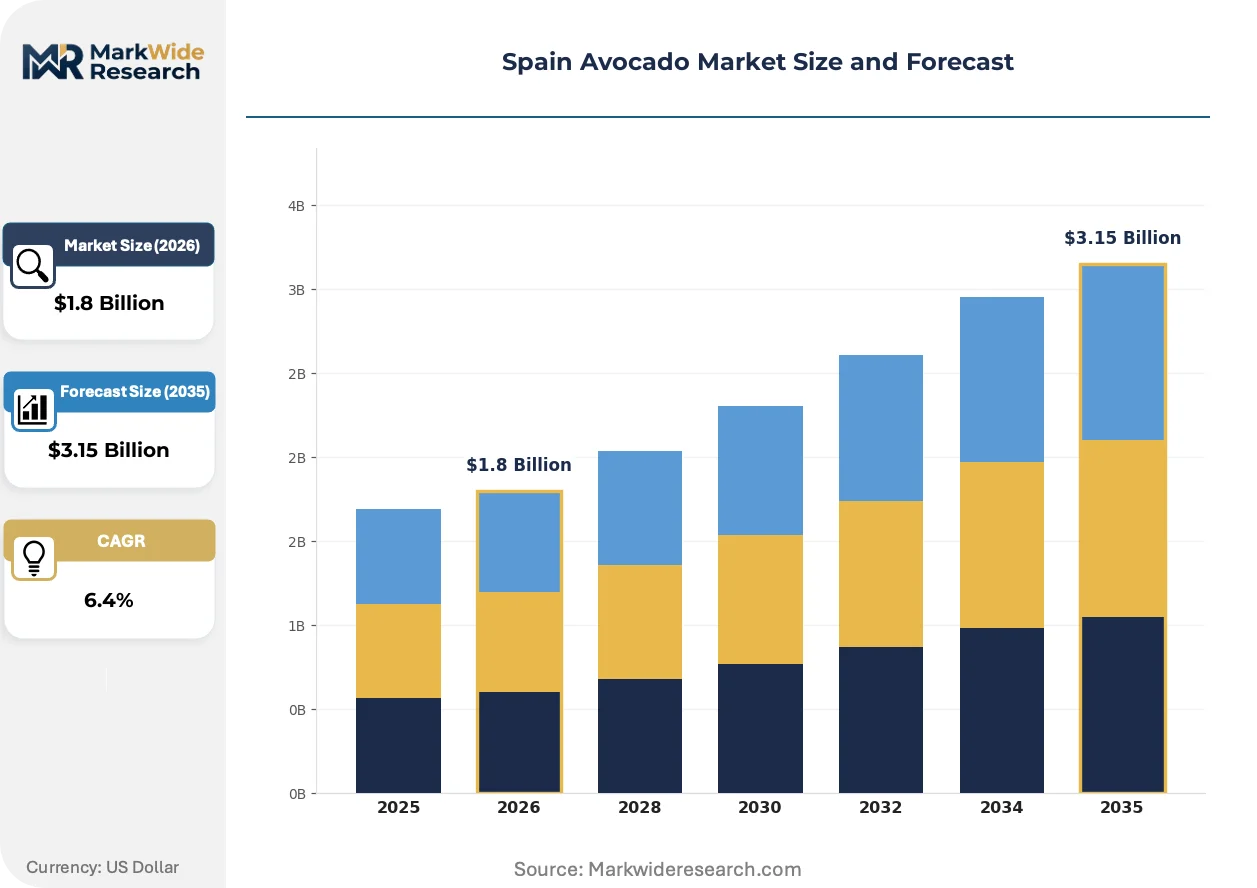
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hass, Fuerte, Bacon, Zutano Distribution Channel: Supermarkets, Online Retail, Wholesale, Farmers' Markets End User: Households, Restaurants, Food Service, Smoothie Bars Packaging Type: Bulk, Retail Packs, Tray Packs, Eco-Friendly Packaging |
| Companies Covered | BROKAW ESPAÑA S.L., Frutas Montosa, Natural Tropic, Sigfrido Molina, Trops, Reyes Gutiérrez, Valle del Guadiana, Alezan, Grupo Cuevas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Avocado Market Trends and Innovations
Spanish avocado supply chains are rewiring around precision ripening and water-stress agronomy, with technology investments clustering in Malaga packing infrastructure and regulatory compliance shaping varietal turnover rates.
Spectral sorting systems integrated at packing stations detect dry matter and oil content non-destructively, enabling batch segregation by ripening potential. Major retail chains deploy these units to reduce consumer-facing quality failures. This precision grading is rewriting procurement specifications, compressing tolerance bands for B-grade fruit and redirecting substandard volumes toward oil extraction channels.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants force cold-chain operators to retrofit controlled-atmosphere storage with CO2-based alternatives. The transition extends equipment replacement cycles and raises capital intensity for ripening service providers. Andalusian packing cooperatives face the steepest compliance burden given their concentration of legacy ammonia and HFC infrastructure.
Spanish households increasingly purchase avocados through quick-commerce platforms offering 15-minute delivery windows, displacing traditional weekly supermarket stock-ups for impulse-driven fresh produce. This channel shift concentrates demand in urban centers with dense dark-store networks. Barcelona and Madrid exhibit the highest penetration, with average basket sizes smaller but purchase frequency doubling year-over-year.
Spain Avocado Market Segmentation
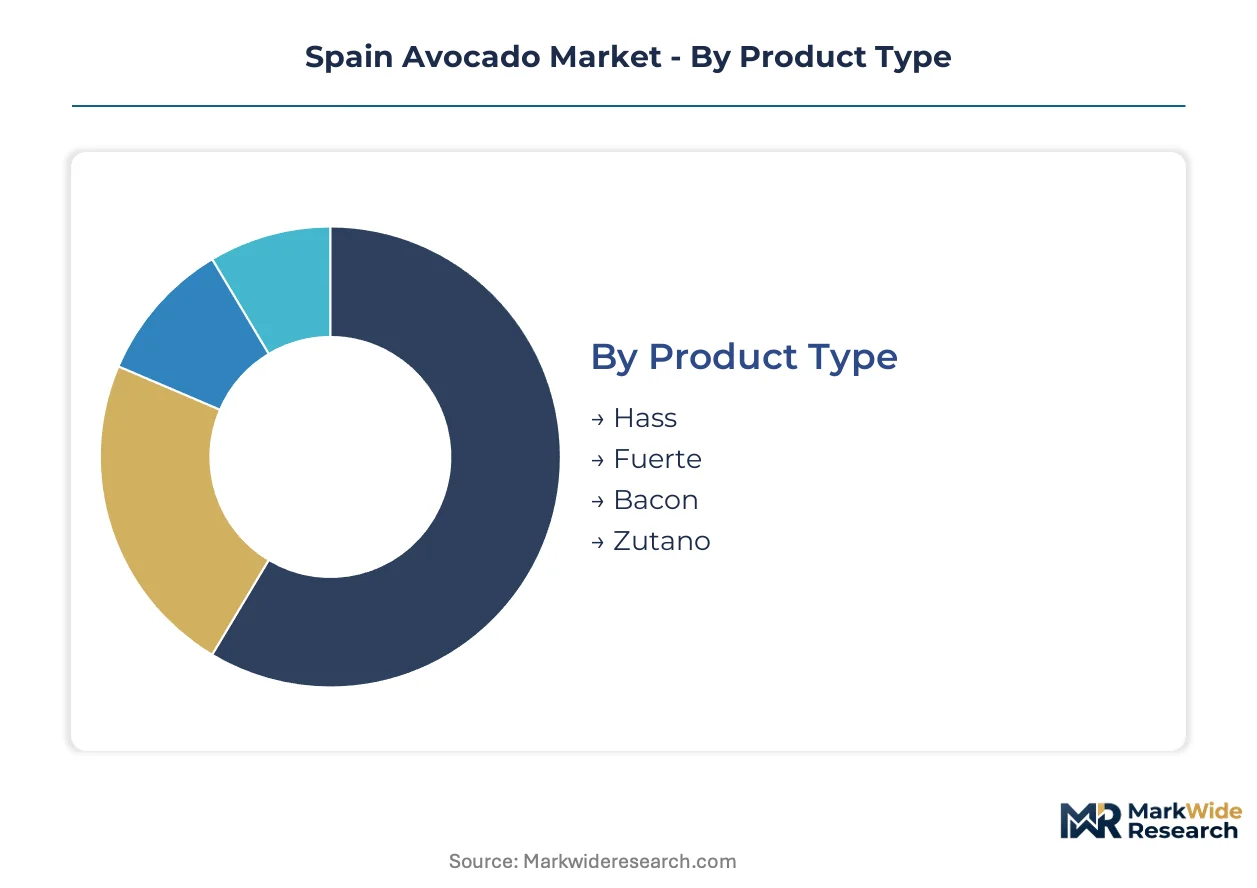
Segmentation in the Spain avocado market reveals how water stress, ripening infrastructure, and channel evolution concentrate value across distinct product tiers and customer interfaces. Understanding these splits exposes where margin pools form and which segments face structural pressure from regulation or competition.
Product Type:
Hass commands volume dominance while Fuerte captures organic premiums, creating a volume-versus-margin architecture that shapes grower planting decisions across Andalusian provinces.
- Hass:Thick peel and extended shelf stability enable year-round production across Malaga and Granada coastal microclimates. Spanish supermarkets and northern European export channels concentrate procurement here, driven by post-harvest ripening compatibility and consistent oil accumulation profiles.
- Fuerte:Thinner skin suits minimal-processing retail packs where organic certification commands price premiums in German and Dutch markets. Demand concentrates in specialized organic channels, constrained by lower drought tolerance and narrower harvest windows.
- Bacon:Cold-hardy rootstock properties support marginal growing zones, though oil content limitations restrict fresh consumption appeal.
- Zutano:Processing-oriented profile serves oil extraction and frozen pulp manufacturing segments with lower per-kilogram input costs.
Today's leader: Hass. Tomorrow's challenger: Fuerte.
Distribution Channel:
Channel fragmentation reflects diverging logistics requirements between impulse-driven urban demand and consolidated procurement for foodservice scale.
- Supermarkets:Volume anchor commanding the largest throughput, with spectral sorting systems now standard at major chain distribution centers to reduce quality failures and shrinkage.
- Online Retail:Quick-commerce platforms in Barcelona and Madrid compress delivery windows to fifteen minutes, doubling purchase frequency though compressing basket economics.
- Wholesale:Consolidated procurement for restaurant groups and catering operations, with ripening-as-a-service subscriptions reducing downstream handling complexity.
- Farmers' Markets:Direct producer-to-consumer interface concentrated in Basque Country and Catalonia urban corridors, capturing premium positioning through proximity narratives.
Supermarkets retain volume leadership. Online retail climbs fastest on quick-commerce penetration.
End User:
User segmentation tracks the prepared-food revolution and beverage-category expansion reshaping Spanish consumption patterns.
- Households:Core demand driver with purchasing shifting from weekly stock-ups toward frequent quick-commerce orders in dense urban zones.
- Restaurants:Premium positioning in Basque Country and Catalonia foodservice corridors shows accelerating per-capita consumption as operators expand avocado-forward menu development.
- Food Service:Institutional and contract catering procurement consolidating through ripening service providers to manage consistency at volume.
- Smoothie Bars:Beverage-channel specialization demanding specific ripening-stage specifications, with Barcelona and Madrid dark-store networks enabling just-in-time supply.
Households anchor current volume. Restaurants represent the steepest expansion trajectory on northern market penetration.
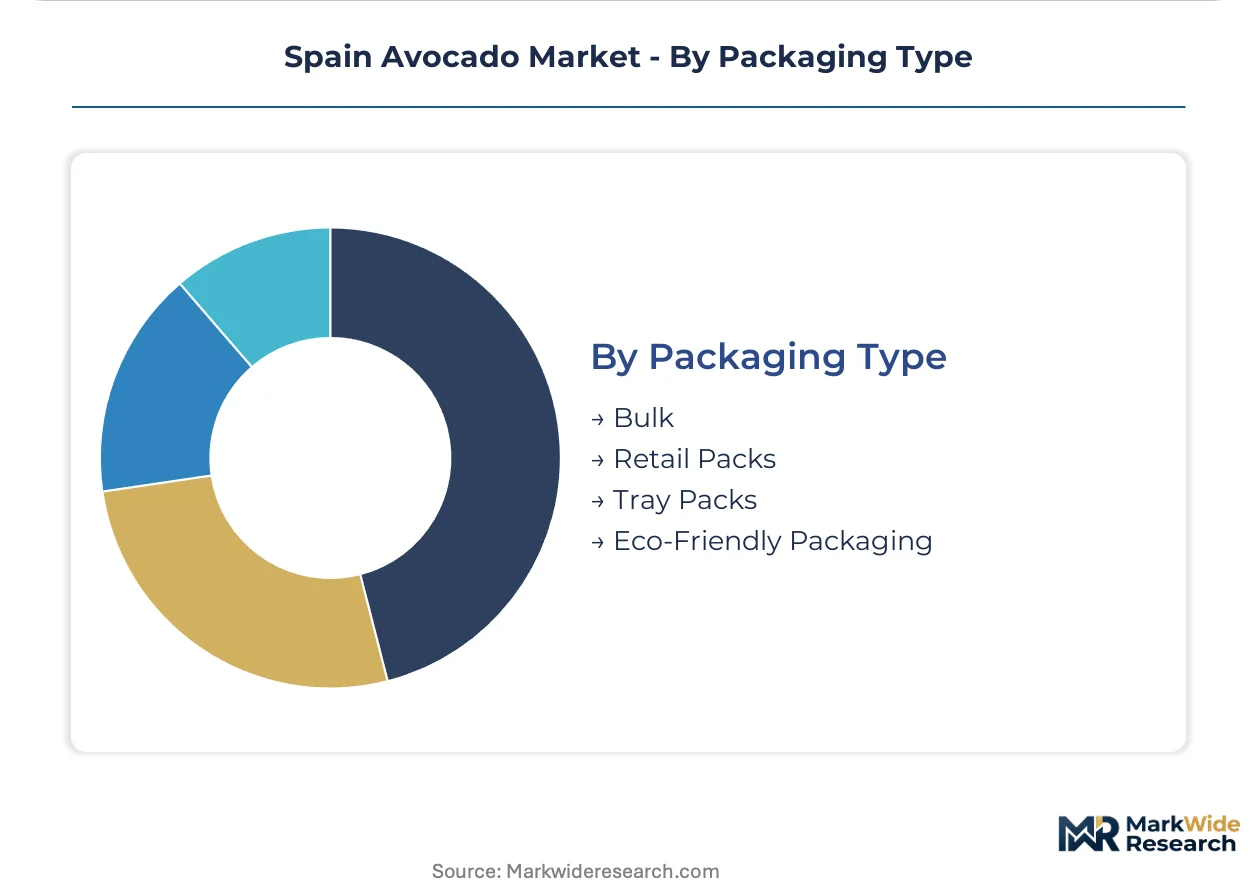
Packaging Type:
Packaging differentiation aligns with channel requirements and EU regulatory pressure on single-use materials.
- Bulk:Foodservice and processing inputs where downstream handling occurs within controlled facilities, minimizing retail presentation requirements.
- Retail Packs:Standard consumer-facing format with modified atmosphere films extending shelf life in supermarket produce sections.
- Tray Packs:Premium presentation tier for impulse and gift segments, absorbing higher per-unit packaging cost through price positioning.
- Eco-Friendly Packaging:Compostable and fiber-based alternatives gaining share under EU Green Deal Farm-to-Fork input restrictions and retailer sustainability procurement criteria.
Retail packs dominate current throughput. Eco-friendly packaging gains fastest on regulatory compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany imports more Spanish avocados than France, yet Dutch buyers pay steeper organic premiums for certified Andalusian fruit. This north-south demand gradient shapes where Spanish exporters direct ripening investments and cold-chain capacity.
Germany
Discounters Aldi and Lidl drive consolidated procurement of ripened-ready Hass avocados for their produce sections. The EU F-Gas Regulation forces German cold-chain operators to retrofit CO2-based refrigeration systems by 2030. Hamburg and Rotterdam port clusters now host dedicated ripening facilities serving German retail distribution centers.
France
Parisian quick-commerce demand concentrates in fifteen-minute delivery zones operated by Flink and Getir dark-store networks. ANSM phytosanitary protocols for imported propagation material create compliance friction for French nurseries sourcing Spanish rootstock. Marseille and Lyon foodservice corridors absorb premium Fuerte volumes for restaurant avocado-forward menu development.
Netherlands
Rotterdam's port-centric logistics hub handles the largest transshipment volumes of Spanish avocados bound for northern European markets. REACH chemical registration requirements govern pesticide residue testing protocols for Dutch supermarket supply contracts. Venlo distribution cluster hosts controlled-atmosphere storage investments by ripening-as-a-service providers serving Benelux retail chains.
United Kingdom
Post-Brexit border phytosanitary checks at Dover and Felixstowe extend transit times for Spanish avocado shipments. The UK's retained EU MRL framework maintains pesticide residue thresholds equivalent to continental standards. London's quick-commerce penetration exceeds any continental European city, with Getir and Zapp dark stores driving impulse-driven avocado purchases.
Italy
Milan and Rome foodservice operators expand avocado procurement for prepared dishes despite domestic olive oil competition. EFSA guidance on Xylella fastidiosa monitoring shapes Italian import protocols for Spanish propagation material. Northern Italian packing cooperatives invest in spectral sorting technology to compete with Andalusian exporters on quality consistency.
Spain Avocado Market Competitive Landscape
Top-tier vendors anchor integrated ripening and export logistics, while mid-tier cooperatives compete on organic certification and varietal specialization. The vendor base clusters around three strategic archetypes: port-proximate logistics integrators, organic-certified grower cooperatives, and controlled-atmosphere technology specialists. Consolidation pressure intensifies as water allocation caps under the Guadalquivir River basin authority favor capital-intensive operators with storage investments. M&A activity targets ripening-as-a-service capabilities, while strategic partnerships lock in northern European retail shelf space.
Among Andalusian-based operators, Trops exemplifies the integrated logistics archetype through its Malaga-to-northern-Europe cold-chain infrastructure. Frutas Montosa occupies a position within the varietal specialization tier, with its company name signaling focus on fruit categories. Grupo Cuevas represents the controlled-atmosphere investment archetype, its name indicating family-group ownership structure typical of Spanish agricultural enterprises. These three patterns illustrate how Spanish avocado competition stratifies across operational capabilities rather than pure scale.
| Leading Market Players |
|---|
| BROKAW ESPAÑA S.L. |
| Frutas Montosa |
| Natural Tropic |
| Sigfrido Molina |
| Trops |
| Reyes Gutiérrez |
| Valle del Guadiana |
| Alezan |
| Grupo Cuevas |
| Others |
Pricing and Supply Chain Analysis
German discounter procurement concentration anchors Spain's avocado pricing model around ripened-ready contract structures, with Aldi and Lidl volume commitments compressing spot-market tolerance bands and redirecting substandard fruit toward oil extraction channels.
Pricing Analysis
Capacity additions in Andalusia's controlled-atmosphere storage infrastructure are reshaping price floors by extending selling windows and reducing seasonal glut discounts. Three-tier pricing structure across premium organic, standard Hass, and economy processing grades differentiates by EU organic certification status and spectral sorting batch quality. Pricing pressure stems from Guadalquivir basin water allocation caps raising per-hectare irrigation costs. Quick-commerce platforms in Barcelona and Madrid exhibit highest price sensitivity due to compressed basket economics, while Dutch organic retailers show least sensitivity.
Supply Chain Analysis
Direct-to-retail ripening service subscriptions handle northern European supermarket demand consolidation, with Hamburg and Rotterdam port clusters hosting dedicated facilities serving German distribution centers. Geographic supply concentrates in Spain's Malaga and Granada coastal microclimates, with secondary sourcing from Portuguese Algarve growers during Andalusian harvest gaps. Raw material dependencies include propagation material under EU Plant Health Regulation compliance, ethylene gas for ripening protocols, and compostable packaging films meeting EU Green Deal Farm-to-Fork criteria. Supply chain risk centers on single-source vulnerability from Guadalquivir basin water allocation disputes between agricultural and urban users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's avocado market functions as a geographic-arbitrage play between water-stressed Andalusian production zones and premium-paying northern European organic retail channels, with the EU F-Gas Regulation phase-down creating compliance cost differentials favoring early CO2 refrigeration adopters.
For Market Incumbents: Cement cold-chain infrastructure advantages through controlled-atmosphere storage investments that extend selling windows past competitors' seasonal constraints. Defend against quick-commerce platform disintermediation by locking ripening-as-a-service subscriptions with urban dark-store networks. Prioritize backward integration into propagation material nurseries to bypass EU Plant Health Regulation compliance bottlenecks.
For New Entrants and Emerging Players: The premium-to-economy price gap in organic certification tiers offers entry space for specialized Fuerte growers targeting Dutch and German retail premiums. Basque Country and Catalonia foodservice corridors remain underpenetrated by Andalusian exporters, with per-capita consumption acceleration outpacing supply localization. Go-to-market through direct chef-procurement relationships bypasses incumbent supermarket slotting fee barriers.
For Investors and Strategic Acquirers: Controlled-atmosphere technology specialists are the most active acquirer target category in this space, with ripening service capabilities commanding strategic premiums. Long-term viability rests on water-rights security under intensifying Guadalquivir basin allocation disputes. Watch drought contingency declarations by the river basin authority as inflection signal for irrigated hectare valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Storage Investment | CO2 refrigeration retrofits under EU F-Gas Regulation extend selling windows for Malaga packing cooperatives. |
| Ripening-as-a-Service Expansion | Subscription cold-chain models reduce retailer shrinkage through precision ethylene management in Barcelona and Madrid. |
| Organic Certification Scale-Up | National organic framework alignment captures German and Dutch retail price premiums for certified Andalusian growers. |
| Water-Efficient Irrigation Deployment | Drip and deficit irrigation adoption mitigates Guadalquivir basin allocation risk for Granada coastal operations. |
| Quick-Commerce Channel Partnership | Fifteen-minute delivery platform integration captures impulse-driven urban demand in dense dark-store networks. |
Research Methodology
Direct dialogue with Andalusian packing cooperative managers, German supermarket category buyers, Dutch organic retail procurement leads, and Guadalquivir River basin authority water planners grounded qualitative insights. Secondary validation drew from EU F-Gas Regulation implementation timelines, ANAFAE avocado sector association trade statistics, EFSA phytosanitary guidance documents, and Spanish Ministry of Agriculture irrigation allocation records. Bottom-up hectare and yield estimates triangulated against top-down export volume customs data.
Segment-level value outputs across the projection horizon reflect modeled interactions between varietal planting decisions, ripening infrastructure capacity, and channel penetration rates. Segmentation dimensions included product type, distribution channel, end user, and packaging format, with organic certification status as a cross-cutting price-tier variable. CAGRs derived from trend extrapolation of per-capita consumption patterns and export volume growth, stress-tested against water allocation constraint scenarios.
Caveats apply where drought contingency declarations, EU Plant Health Regulation enforcement shifts, or quick-commerce platform consolidation could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Global Mushroom Market
Vegetables
Qatar Greenhouse Market
Vegetables
Italy Greenhouse Horticulture Market
Vegetables
Asparagus Market
Vegetables
IQF Vegetables Market
Vegetables
North America Christmas Tree Market
Vegetables
Vegetable Chutney Market
Vegetables
Fresh Mushroom Market
Vegetables
Yams Market
Vegetables
Roselle Market
Vegetables
Canada Microgreens Market
Vegetables
Yam Products Market
Vegetables
North America Sweet Potatoes Market
Vegetables
Peas Market
Vegetables
Asia-Pacific Peas Market
Vegetables
Tanzania Fruit and Vegetables Market