
 Japan Commercial Vehicles Market | 2026-2036
Japan Commercial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Commercial Vehicles Market Foresight
A capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is rotating competitive advantage toward firms with captive powertrain production. Isuzu Motors Limited leverages its diesel engine expertise to sustain dominance in medium-duty logistics applications. Toyota Motor Corporation anchors its position through hybrid system integration across commercial van platforms. Mitsubishi Fuso Truck and Bus Corporation differentiates via dedicated bus chassis architecture serving municipal transit operators.
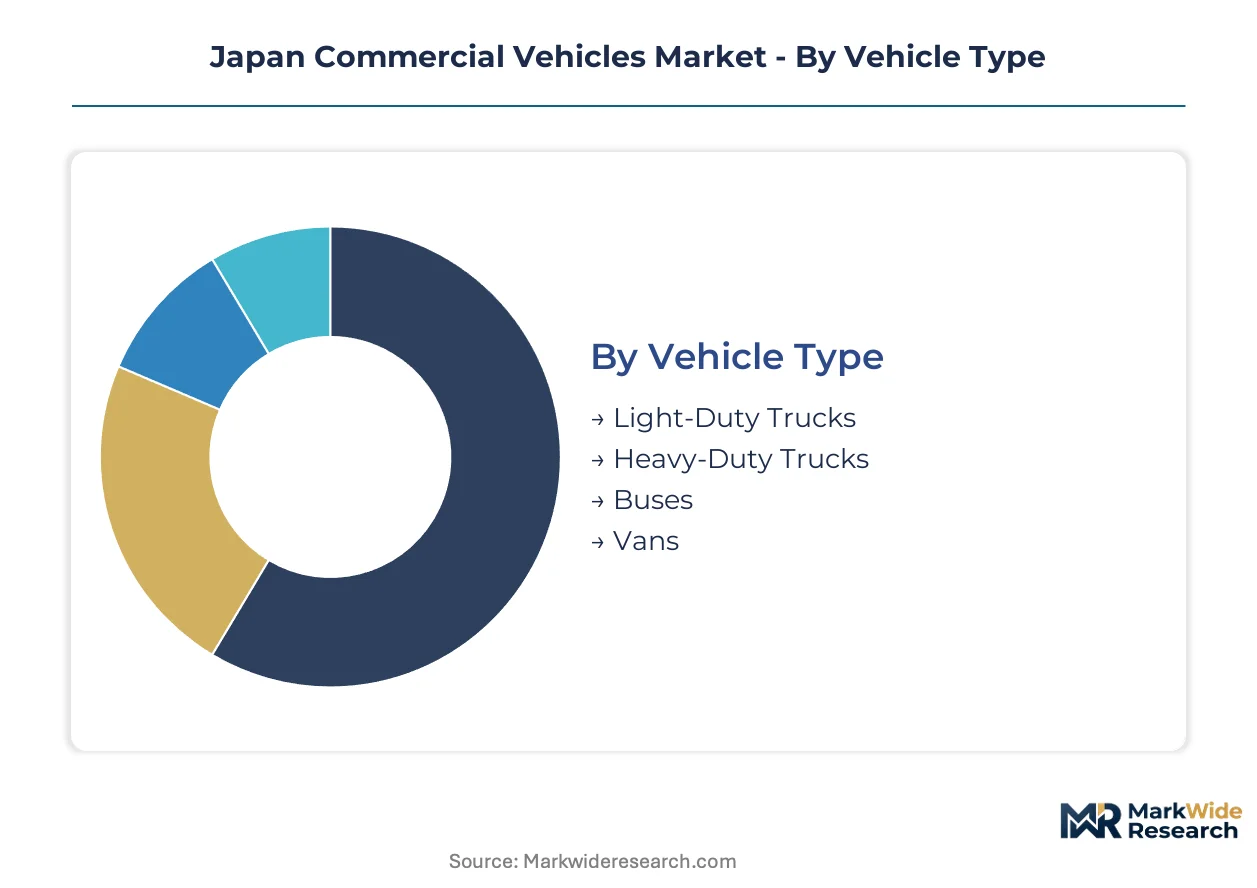
Japan commercial vehicles encompass motorized transport equipment designed for goods carriage and passenger movement, typically featuring reinforced frame rails, gross vehicle weight ratings exceeding 3.5 tonnes for heavy configurations, and powertrains optimized for stop-start urban duty cycles or sustained highway torque delivery. Light-duty trucks occupy the largest volume share as kei-class regulations preserve compact delivery formats for narrow urban streets. Electric fuel type segments are expanding fastest among refrigerated freight applications where government subsidies offset battery cost premiums. Hybrid configurations retain margin concentration in intercity bus routes where charging infrastructure remains sparse.
METI fuel efficiency standards and JIS certification requirements shape powertrain development timelines, while the Ministry of Land, Infrastructure, Transport and Tourism vehicle type designation system controls market access for imported chassis. PMDA-aligned occupational safety frameworks influence driver cabin ergonomics specifications for long-haul fleet procurement. Stakeholders must monitor subsidy phase-out schedules against battery cost curves to time electrification capital commitments.
Market Dynamics
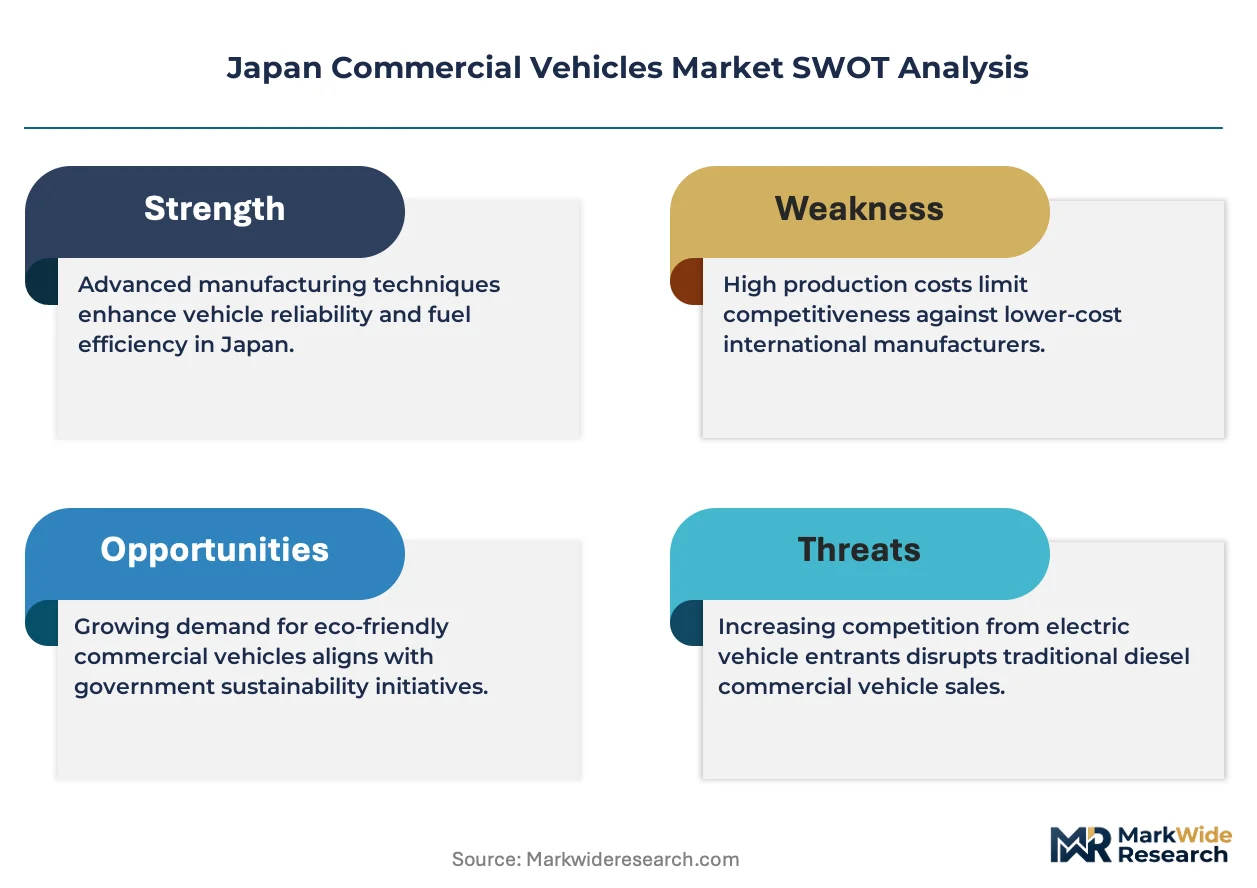
Japan's commercial vehicle sector faces a structural pivot as METI's carbon neutrality roadmap forces powertrain architecture decisions ahead of battery cost parity, compressing fleet operator replacement cycles and redrawing competitive boundaries between captive manufacturers and assembly-dependent rivals.
Growth Catalysts
- Last-mile delivery densification:E-commerce fulfillment networks serving Tokyo-Osaka freight corridors are expanding kei-class van procurement to serve narrow urban delivery routes.
- METI electrification subsidies:Government incentives for refrigerated freight applications offset battery cost premiums, accelerating electric powertrain adoption in cold-chain logistics.
- Hybrid system integration:Intercity bus operators facing sparse charging infrastructure are prioritizing hybrid configurations for sustained highway torque delivery.
Market Restraints
- Battery mineral supply concentration:Lithium and cobalt processing capacity clustering in Southeast Asia creates input cost volatility for domestic electric powertrain assembly.
- JIS certification timelines:Extended vehicle type approval processes through the Ministry of Land, Infrastructure, Transport and Tourism slow platform updates for imported chassis.
- Diesel engine substitution ceiling:Medium-duty logistics applications in Hokkaido and Tohoku regions face range limitations that compressed natural gas cannot resolve.
Strategic Opportunities
- Kyushu manufacturing cluster:Underdeveloped commercial vehicle assembly presence in southern Japan offers greenfield capacity for dedicated electric bus platforms.
- Vehicle-to-grid convergence:Bidirectional charging integration with stationary battery systems creates new revenue streams for fleet operators participating in demand response programs.
- PMDA-aligned cabin ergonomics:Occupational safety frameworks for long-haul drivers open premium positioning for ergonomic cabin specifications in intercity routes.
Industry Challenges
- Powertrain software integration:Fleet management systems require reconfiguration to coordinate hybrid-electric duty cycles with driver scheduling platforms.
- Subidy phase-out timing:Operators must align capital commitments with uncertain METI incentive schedules against declining battery cost curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Commercial Vehicles Market |
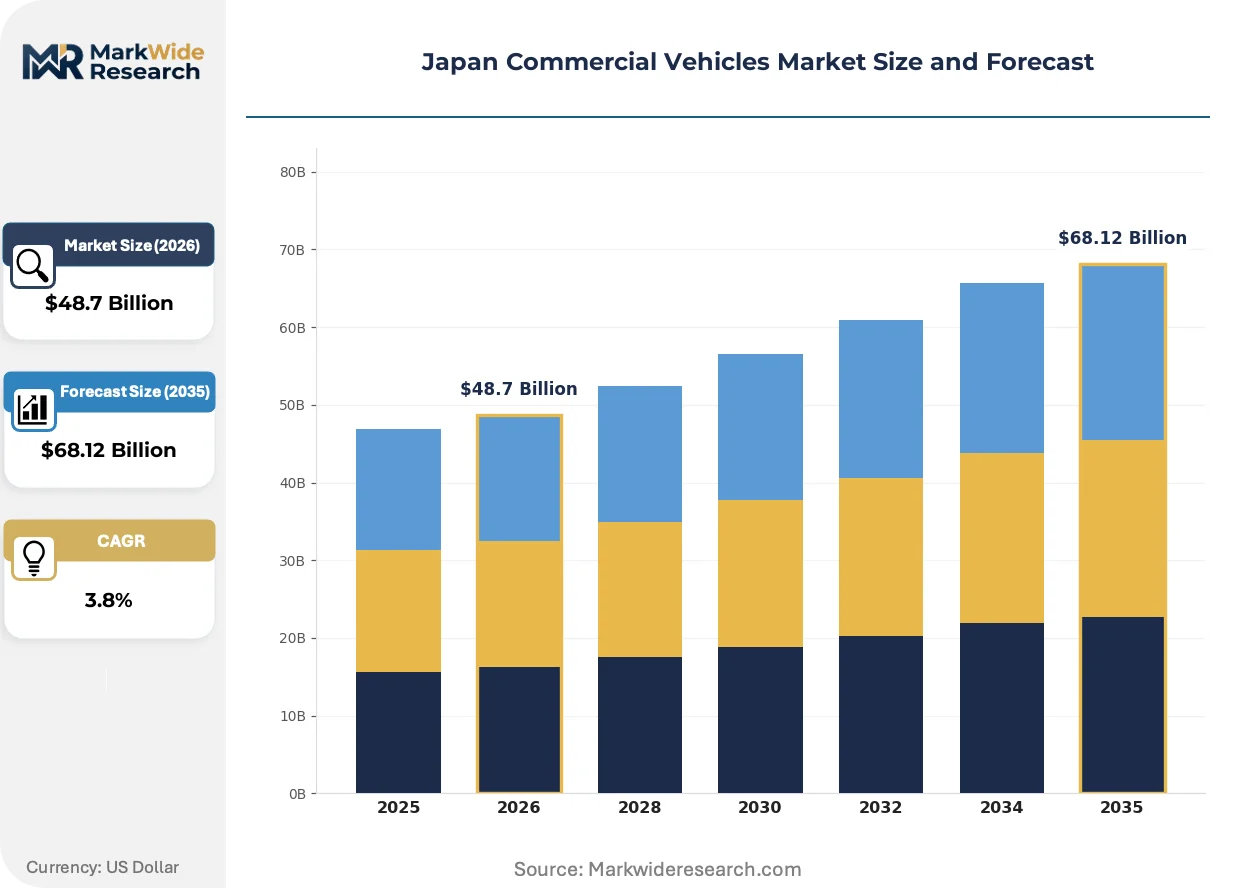
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $68.12 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light-Duty Trucks, Heavy-Duty Trucks, Buses, Vans Fuel Type: Diesel, Petrol, Electric, Hybrid End User: Logistics Companies, Construction Firms, Government Agencies, Retail Businesses Application: Freight Transport, Passenger Transport, Delivery Services, Emergency Services |
| Companies Covered | Mitsubishi Fuso Truck and Bus Corporation, Honda Motor Co Ltd, Toyota Motor Corporation, Mazda Motor Corporation, Suzuki Motor Corporation, Isuzu Motors Limited, Nissan Motor Co Ltd, Subaru Corporation, Hino Motors, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Commercial Vehicles Market Shifts & Advancements
Powertrain electrification is fragmenting procurement patterns across duty-cycle segments, with technology choices diverging between urban stop-start applications and sustained highway operations. This divergence is reshaping supplier relationships and fleet operator capital allocation priorities.
Solid-state battery chemistry is bifurcating development roadmaps for commercial vehicle platforms. Toyota's solid-state research targets energy density thresholds for intercity bus routes exceeding 300 kilometers. Fleet operators in the Kanto region are piloting prototype cells for refrigerated delivery vans where thermal stability reduces cargo loss risk. The technology is bifurcating competitive positioning between manufacturers with captive cell development and those dependent on external suppliers.
METI's fuel efficiency standards are compressing powertrain development timelines for medium-duty platforms. The regulatory framework mandates specific CO2 reduction trajectories through 2030, forcing diesel-dependent manufacturers to accelerate hybrid integration. Municipal transit operators in Osaka and Nagoya are responding by consolidating procurement around platforms with certified compliance pathways.
Service contract unbundling is disrupting traditional fleet procurement relationships. Logistics companies operating Tokyo-Osaka corridors are separating vehicle acquisition from maintenance and energy provision, creating multi-vendor ecosystems. This pattern concentrates in refrigerated freight segments where uptime guarantees outweigh brand loyalty in supplier selection criteria.
Japan Commercial Vehicles Market Segmentation
Segmentation in Japan's commercial vehicle market reveals how regulatory pressure and duty-cycle specialization are fragmenting procurement patterns. Fleet operators now select platforms based on corridor-specific requirements rather than brand loyalty.
Vehicle Type:
Margin pools concentrate in configurations serving narrow urban streets where kei-class regulations preserve compact formats against import competition.
- Light-Duty Trucks:Reinforced frame rails with gross vehicle weight ratings between 3.5 and 7.5 tonnes dominate last-mile delivery networks. Tokyo-Osaka freight corridor operators favor these platforms for dense urban routing where maneuverability constraints exclude heavier configurations.
- Heavy-Duty Trucks:Sustained highway torque delivery systems with sleeper cab provisions serve Hokkaido and Tohoku long-haul routes. Range limitations from battery weight penalties protect diesel-hybrid architectures in this segment against full electrification pressure.
- Buses:Municipal transit operators in Osaka and Nagoya procure dedicated chassis architecture with low-floor accessibility.
- Vans:Kei-class regulations preserve compact delivery formats for narrow urban streets in Kyoto and Kanazawa historic districts.
The dominant share belongs to Light-Duty Trucks, while Electric configurations within Vans are climbing the fastest as subsidy programs offset battery premiums.
Fuel Type:
Application requirements across duty cycles determine technology choices more than upfront acquisition cost.
- Diesel:Compression-ignition engines optimized for thermal efficiency under sustained load dominate medium-duty logistics. Hokkaido operators retain diesel for routes exceeding 500 kilometers where charging infrastructure remains sparse.
- Hybrid:Dual-powertrain systems combining internal combustion with electric assist capture intercity bus procurement. Nagoya municipal operators prioritize these configurations for routes with variable topography and stop-start frequency.
- Electric:Battery-electric powertrains with thermal management for refrigerated cargo are expanding in Kanto region cold-chain logistics.
- Petrol:Spark-ignition engines retain share in compact van segments where total cost of ownership calculations favor lower capital outlay.
Diesel retains volume leadership, though Hybrid systems are gaining share fastest among fleet operators facing METI compliance deadlines.
End User:
Procurement sophistication varies sharply between asset-heavy operators and contract-dependent service providers.
- Logistics Companies:Asset-heavy fleet operators with dedicated maintenance facilities dominate heavy-duty procurement. Yamato Transport and Sagawa Express anchor demand for standardized platforms enabling driver pool flexibility across depots.
- Government Agencies:Municipal procurement offices in Osaka and Fukuoka consolidate demand for accessible bus specifications. JIS certification requirements and PMDA-aligned safety frameworks shape tender specifications.
- Construction Firms:Project-based operators favor rental and lease arrangements over direct acquisition for specialized dump and mixer configurations.
- Retail Businesses:Convenience store chains and supermarket operators procure light-duty vans through dealer fleet programs with bundled maintenance.
Logistics Companies command the dominant procurement volume, while Government Agencies are expanding fastest as municipal transit electrification accelerates.
Application:
Service-level requirements determine platform specification more than vehicle category labels.
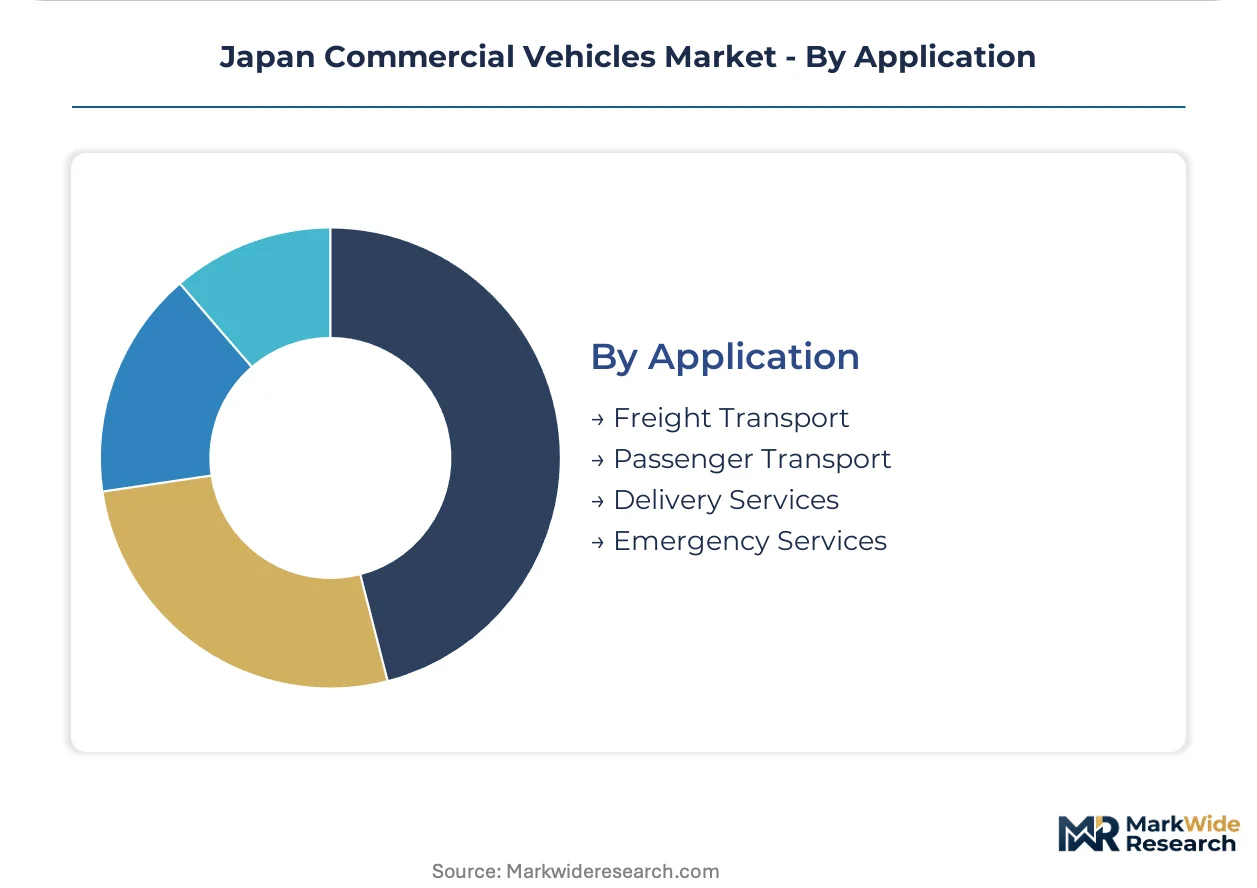
- Freight Transport:Temperature-controlled cargo systems with real-time monitoring dominate refrigerated corridor demand. Tokyo-Osaka pharmaceutical and fresh food logistics require uptime guarantees that favor established service networks.
- Delivery Services:High-frequency stop-start duty cycles with parcel tracking integration define e-commerce fulfillment requirements. Kanto region densification is expanding kei-class van deployment for same-day service commitments.
- Passenger Transport:Accessibility compliance and route flexibility specifications shape municipal bus procurement.
- Emergency Services:Specialized ambulance and fire apparatus configurations with dedicated electrical systems serve prefectural emergency response networks.
Freight Transport holds the dominant application share, while Delivery Services are expanding most quickly as e-commerce fulfillment networks densify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in Hokkaido exhibit the highest price elasticity due to sparse charging infrastructure and extended route requirements, while Tokyo-based logistics companies absorb premium pricing for zero-emission compliance. This demand-elasticity contrast shapes regional procurement patterns across Japan's commercial vehicle landscape.
Kanto/Tokyo
E-commerce fulfillment densification and last-mile delivery expansion drive kei-class van procurement throughout the Tokyo-Osaka freight corridor. METI electrification subsidies for refrigerated freight applications accelerate battery-electric adoption among cold-chain operators. The Greater Tokyo Area concentrates manufacturing partnerships between domestic OEMs and logistics platforms serving same-day delivery commitments.
Kansai/Osaka
Municipal transit electrification programs and intercity bus route modernization anchor hybrid system demand across Osaka and Nagoya metropolitan zones. JIS certification requirements shape tender specifications for accessible low-floor chassis architecture. The Osaka Bay industrial zone hosts fleet renewal initiatives consolidating procurement around METI-compliant powertrain platforms.
Chubu/Nagoya
Automotive supplier networks and precision manufacturing logistics sustain medium-duty truck replacement cycles throughout Aichi Prefecture. PMDA-aligned occupational safety frameworks influence driver cabin specifications for long-haul routes connecting Nagoya to Pacific coastal ports. The region's manufacturing corridor maintains diesel-hybrid dominance where charging infrastructure remains underdeveloped.
Kyushu
Underdeveloped commercial vehicle assembly presence and southern Japan freight corridor expansion create greenfield opportunities for dedicated electric bus platforms. Regional port logistics and agricultural distribution networks drive refrigerated transport demand across Fukuoka and Kumamoto prefectures. The Kyushu manufacturing cluster attracts investment targeting municipal transit electrification and inter-island shipping connections.
Hokkaido and Tohoku
Extended highway routes and severe winter operating conditions preserve diesel engine preference among long-haul operators serving Sapporo and Sendai distribution hubs. Range limitations from battery weight penalties and sparse fast-charging networks constrain full electrification timelines. Regional logistics companies prioritize thermal efficiency and all-wheel-drive configurations for snow-load corridors.
Japan Commercial Vehicles Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive powertrain manufacturers commanding structural advantages over assembly-dependent competitors. The market structure concentrates around firms with in-house diesel, hybrid, and electric drivetrain development capabilities. Three archetypes dominate: integrated powertrain specialists, hybrid system integrators, and municipal transit chassis architects. Competitive dynamics revolve around strategic partnerships for charging infrastructure deployment and portfolio diversification into electrified van platforms.
Among integrated Japanese manufacturers, Mitsubishi Fuso Truck and Bus Corporation, Isuzu Motors Limited, and Toyota Motor Corporation exemplify distinct competitive positioning. Mitsubishi Fuso occupies the municipal transit chassis tier serving Osaka and Nagoya operators with dedicated low-floor architecture. Isuzu Motors represents the diesel powertrain specialist archetype leveraging medium-duty logistics expertise across Hokkaido and Tohoku routes. Toyota Motor anchors the hybrid integration tier through commercial van platforms targeting Tokyo-Osaka corridor electrification requirements.
| Leading Market Players |
|---|
| Mitsubishi Fuso Truck and Bus Corporation |
| Honda Motor Co Ltd |
| Toyota Motor Corporation |
| Mazda Motor Corporation |
| Suzuki Motor Corporation |
| Isuzu Motors Limited |
| Nissan Motor Co Ltd |
| Subaru Corporation |
| Hino Motors |
| Others |
Supply & Pricing Matrix
Long-term fleet service contracts lock in both battery supply access and price visibility for Japanese commercial vehicle operators navigating METI subsidy phase-outs. These multi-year agreements with captive powertrain manufacturers insulate procurement teams from lithium cost volatility while committing capital ahead of technology transitions.
Pricing Analysis
After-sales service contracts drive lifetime value more than upfront vehicle acquisition in Japan's commercial vehicle sector. Three-tier pricing structure across premium, standard, and economy levels segments procurement by fleet scale and maintenance bundling. Price differentiation hinges on JIS certification tier and geographic delivery cost to Hokkaido versus Kanto depots. Cost compression in electric powertrain tiers is intensifying because battery mineral supply concentration in Southeast Asia feeds input volatility. Asset-heavy logistics companies like Yamato Transport exhibit lowest price sensitivity, while regional construction firms relying on rental arrangements show highest elasticity.
Supply Chain Analysis
Inventory lead times for solid-state battery cells extend platform development cycles beyond traditional diesel engine procurement schedules. Component sourcing draws from Japan, South Korea, and China for lithium-ion cells, rare earth magnets, and power electronics substrates. Raw material dependencies center on cobalt cathodes, lithium carbonate, and silicon carbide semiconductors. Single-source vulnerability concentrates in Southeast Asian mineral processing nodes. Distribution runs through OEM-captive dealer networks serving municipal transit authorities and national logistics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's commercial vehicle market demands substitution defense against Chinese electric truck platforms penetrating ASEAN corridors and threatening export-oriented Japanese OEM positioning.
For Market Incumbents: Consolidate hybrid system integration capabilities ahead of full electrification timelines, securing captive battery supply through joint ventures with South Korean cell manufacturers. Deepen backward integration into power electronics assembly to offset margin pressure from imported semiconductor content. METI compliance deadlines create urgency for certification investments in solid-state thermal management systems. For New Entrants and Emerging Players: Lead with dedicated electric bus platforms targeting Kyushu's underdeveloped assembly presence and municipal transit electrification programs. The most penetrable white space sits in refrigerated last-mile vans for Kanto cold-chain operators seeking uptime guarantees beyond incumbent service networks. A direct fleet-leasing model with bundled energy provision bypasses established dealer relationships. For Investors and Strategic Acquirers: Capital is best deployed toward powertrain-integrated mid-tier manufacturers with captive diesel-to-electric transition roadmaps and established JIS certification pathways. Long-term viability over the coming decade rests on software-defined vehicle architecture investments coordinating fleet management with charging infrastructure. The signal to watch is METI subsidy renewal announcements against battery cost curve inflection points.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium cell access from South Korean partners for Kanto electric van production. |
| Platform Standardization | Reduces part complexity across kei-class and medium-duty configurations serving Tokyo-Osaka corridors. |
| Charging Infrastructure Partnership | Integrates fleet depots with grid operators for vehicle-to-grid revenue streams in Nagoya. |
| Software-Defined Vehicle Investment | Enables over-the-air updates coordinating hybrid duty cycles with driver scheduling platforms. |
| Geographic Manufacturing Footprint | Establishes greenfield electric bus assembly in Kyushu targeting southern Japan transit authorities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with fleet procurement managers at Yamato Transport and Sagawa Express, METI policy officers, municipal transit authority tender specialists, and Tier 1 supplier engineering directors. Secondary validation drew from MLIT vehicle registration databases, METI subsidy disbursement records, JIS certification filings, and customs trade data for powertrain component imports. Bottom-up fleet operator demand modeling triangulated against top-down OEM production forecasts.
Across the projection horizon, the analytical framework segmented volume and value outputs by vehicle class, propulsion architecture, and regional production cluster. CAGRs were derived from regression analysis against METI compliance trajectories and battery cost decline curves. Industry-specific forecast inputs incorporated charging infrastructure deployment schedules and municipal transit electrification tender pipelines.
The analysis sits within stated boundaries; outcomes outside sustained METI subsidy levels or accelerated solid-state battery commercialization would require recalibration. Forecasts reflect documented assumptions regarding mineral supply concentration and JIS certification timeline stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
United States Vans Market
Commercial Vehicles
Semi-Tractor Trailer Market
Commercial Vehicles
Europe Van Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Flatbed Semi-Trailer Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
North America Van Market
Commercial Vehicles
Electric LCV Market
Commercial Vehicles
Commercial Vehicle (CV) Active Power Steering Market
Commercial Vehicles
Commercial Vehicle Transmission Market
Commercial Vehicles
Tank Car Market
Commercial Vehicles
Automated Truck Market
Commercial Vehicles
Electric Truck Chassis Market
Commercial Vehicles
Service Truck Market
Commercial Vehicles
Global Fuel Cell Commercial Vehicle Market
Commercial Vehicles
Global Commercial Vehicles Market