
 Whiteness Meter Market | 2026-2036
Whiteness Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Whiteness Meter Market Intelligence
The proliferation of equipment leasing models is reconfiguring the competitive landscape by lowering the capital barrier for smaller quality control labs. This shift enables broader access to high-end spectrophotometry and colorimetry instruments. Konica Minolta Sensing Americas, Inc. leverages its extensive portfolio to serve diverse end-user industries. Meanwhile, HunterLab specializes in appearance measurement solutions for specific applications, and BYK-Gardner GmbH dominates the European paints and coatings segment with its specialized instrumentation.
A whiteness meter is an optical instrument that quantifies the degree of whiteness of a surface, often using standards like the CIE Whiteness Index under a D65 illuminant. Its primary purpose is to ensure color consistency and quality control in industrial manufacturing processes. Benchtop models continue to lead in precision-critical research institutes and quality control labs, while portable units represent the fastest-growing product type for on-site inspections. The paper & pulp and textiles applications remain the largest consumers, driven by aesthetic and quality standards.
Regulatory frameworks directly influence instrument specifications and market access. International standards like ISO 11475 for paper and board, alongside FDA regulations on colorants in food-contact plastics in the United States and the EU's REACH directive, create a complex compliance environment. For instrument manufacturers, the strategic imperative is to develop devices that balance precision, portability, and adherence to these diverse and evolving international quality mandates.
Market Dynamics
The central structural force shaping the market is the elevation of whiteness measurement from a subjective aesthetic preference to a non-negotiable compliance requirement. Tightening regulations in food contact materials and textiles transform these instruments into essential tools for market access.
Growth Catalysts
- Food Contact Regulations:Strict guidelines from bodies like the FDA in the United States and the EFSA in Europe on additives in food-grade plastics and paper necessitate precise whiteness measurement to verify purity and absence of contaminants.
- Paper & Pulp Quality Mandates:Germany's advanced paper industry relies on compliance with ISO 11475 to maintain its export leadership in high-value packaging, making whiteness meters indispensable for quality control.
- Textile Industry Aesthetics:The global textile sector requires objective whiteness data to ensure color consistency and prevent batch-to-batch variation in high-end apparel and home goods, driving instrument adoption.
Market Restraints
- High Capital Outlay:The substantial initial investment for high-precision benchtop spectrophotometers remains a significant barrier for smaller enterprises, particularly within the fragmented textiles and plastics converting industries.
- Calibration and Maintenance:Instruments require frequent and complex calibration against physical standards, which introduces operational downtime and necessitates specialized technicians, adding to the total cost of ownership.
- Threat from Multi-Function Devices:General-purpose colorimeters and spectrophotometers that include whiteness measurement as a feature compete with dedicated instruments, potentially cannibalizing the market for single-function meters.
Strategic Opportunities
- Pharmaceutical Sector Expansion:Measuring the whiteness of pharmaceutical powders and tablet coatings offers a high-value opportunity, as color consistency is a key indicator of product purity and uniformity.
- Recycled Material Verification:The circular economy trend creates a need for whiteness meters to quantify and standardize the appearance of products made from post-consumer recycled paper and plastics.
- Cloud-Based Data Services:Developing subscription-based software for remote diagnostics, data logging, and comparative analysis across multiple manufacturing sites presents a new recurring revenue stream for instrument vendors.
Industry Challenges
- Inter-Instrument Agreement:Achieving consistent and reproducible measurements between different instrument models, particularly between benchtop laboratory units and portable field devices, remains a persistent technical hurdle for manufacturers.
- Divergent Global Standards:Harmonizing instrument specifications to meet conflicting regional standards, such as CIE Whiteness versus Ganz-Griesser, complicates product design and creates friction in global supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whiteness Meter Market |
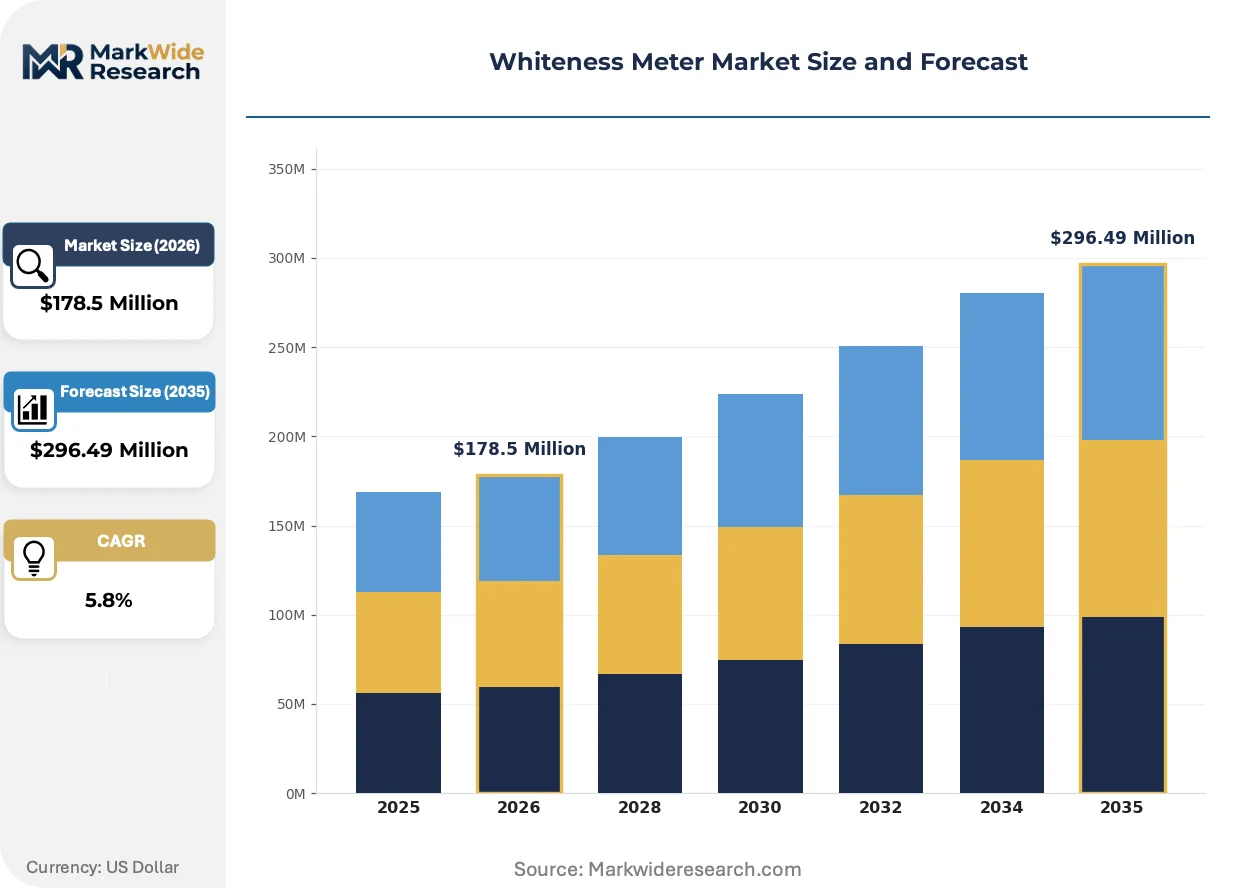
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $296.49 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Benchtop, Handheld, Online, Desktop Technology: Colorimetry, Spectrophotometry, Camera-Based, Reflectance, Fluorimetry Application: Paper & Pulp, Textiles, Plastics, Paints & Coatings, Food Quality End User Industry: Manufacturing Plants, Research Institutes, Quality Control Labs, Chemical Producers |
| Companies Covered | PCE Instruments, Konica Minolta Sensing Americas, Inc., BYK-Gardner GmbH, HunterLab, X-Rite, Incorporated, Optics Technology, Caltech Engineering Services, EIE Instruments, Mesu Lab Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whiteness Meter Market Strategic Shifts & Innovations
The market's evolution is defined by the integration of digital technologies that capture more than just a single whiteness value. This shift connects quality control data directly to manufacturing process optimization, moving beyond simple pass-fail metrics.
Digital appearance measurement combines high-resolution imaging with traditional spectrophotometry to create a more complete surface profile. Advanced R&D labs in the automotive coatings and consumer electronics sectors are the primary adopters. This technology is virtualizing physical reference standards, enabling digital simulations of product appearance under varied lighting and textures.
European Union chemical safety regulations, specifically REACH, impose strict controls on the use of optical brightening agents (OBAs) in paper and textiles. This is forcing manufacturers to either find OBA-free whitening solutions or precisely control their application levels. The paper and pulp sector is most affected, investing in advanced instruments that can differentiate fluorescent from non-fluorescent whiteness to ensure compliance.
Equipment leasing and subscription models are gaining traction as an alternative to outright capital purchase. This shift disrupts the traditional sales cycle for instrument manufacturers, especially when selling to contract research organizations and smaller quality control labs. The trend is most prominent in North America and Germany, where operational expenditure models align with the business needs of a flexible manufacturing base.
Whiteness Meter Market Segmentation
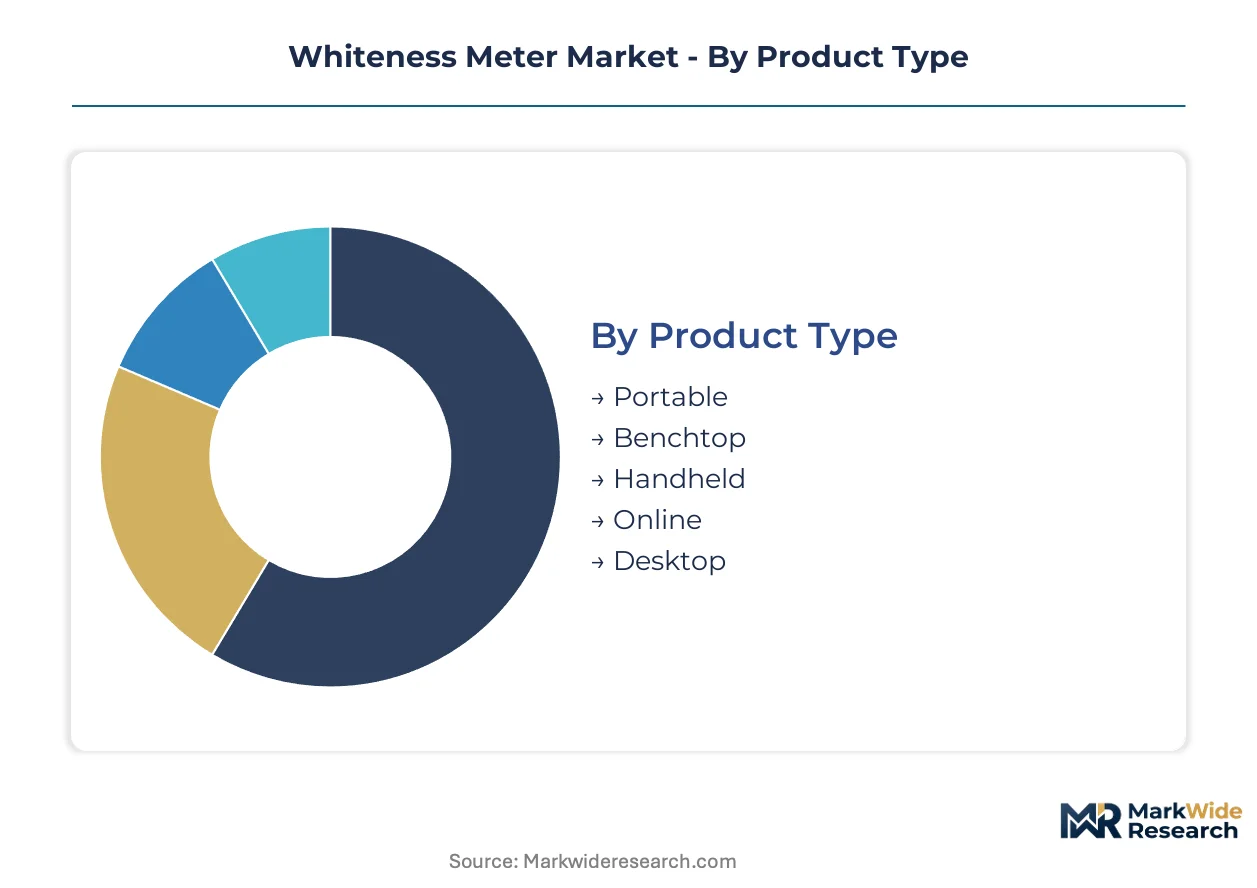
The whiteness meter market segments across diverse dimensions, reflecting varied industrial requirements for optical measurement and quality assurance. Understanding these distinctions helps stakeholders identify specific growth pockets and tailor product development to precise end-user needs. This segmentation highlights how different product types, technologies, applications, and end-user industries interact with regulatory mandates and operational demands.
Product Type:
The maturity spectrum of whiteness meter product types reflects diverse operational needs across industrial settings.
- Benchtop:These instruments provide the highest precision for critical laboratory analysis and research applications. Their stable platforms ensure repeatable measurements, crucial for pharmaceutical purity verification in Germany.
- Portable:Portable whiteness meters offer flexibility for on-site quality checks and field inspections across various manufacturing environments. Their ease of use supports rapid decision-making in textile production lines in India.
- Handheld:Compact handheld devices offer basic whiteness measurement for quick spot checks in less demanding industrial settings.
- Online:Integrated into production lines, online whiteness meters provide continuous, real-time monitoring for automated process control.
- Desktop:Desktop models offer a balance of precision and footprint, often used in smaller quality control labs or educational institutions.
Benchtop models handle the majority of precision-critical throughput; Portable units are the fastest mover on share.
Technology:
Technology segmentation in whiteness measurement directly influences instrument suitability for specific industrial applications.
- Spectrophotometry:Spectrophotometry-based instruments measure light reflectance across the visible spectrum, providing comprehensive color data for precise whiteness indices. This technology is vital for meeting ISO 11475 standards in the paper and pulp industry in Finland.
- Colorimetry:Colorimetry instruments quantify color based on tri-stimulus values, offering a cost-effective solution for general whiteness quality control. Their simpler operation makes them suitable for routine checks in plastics manufacturing in China.
- Camera-Based:This technology leverages high-resolution imaging to capture surface profiles, enabling digital appearance measurement and virtual reference standards.
- Reflectance:Reflectance-based meters measure the amount of light reflected from a surface, a fundamental principle for whiteness quantification.
- Fluorimetry:Fluorimetry specifically detects and quantifies fluorescent components, essential for industries using optical brightening agents in textiles and paper.
The adoption of Spectrophotometry provides foundational data, while Fluorimetry offers specialized insights for optical brightening agent detection.
Application:
Volume concentration within whiteness meter applications highlights sectors with stringent quality control requirements.
- Paper & Pulp:Whiteness meters in paper and pulp ensure aesthetic consistency and compliance with international standards for packaging materials. Germany's advanced paper industry relies heavily on these instruments to maintain export leadership.
- Textiles:The textile sector uses whiteness meters to achieve color uniformity and prevent batch-to-batch variation in high-end apparel and home goods. This application is critical for quality assurance in Vietnam's textile exports.
- Plastics:Whiteness measurement in plastics verifies material purity, color consistency, and compliance for food contact materials.
- Paints & Coatings:These instruments ensure color matching, opacity, and whiteness standards for architectural and industrial coatings.
- Food Quality:Whiteness meters assess the visual quality and freshness of food products, particularly in dairy and processed foods.
Compliance mandates drive demand in Paper & Pulp, while aesthetic demands shape adoption in Textiles.
End User Industry:
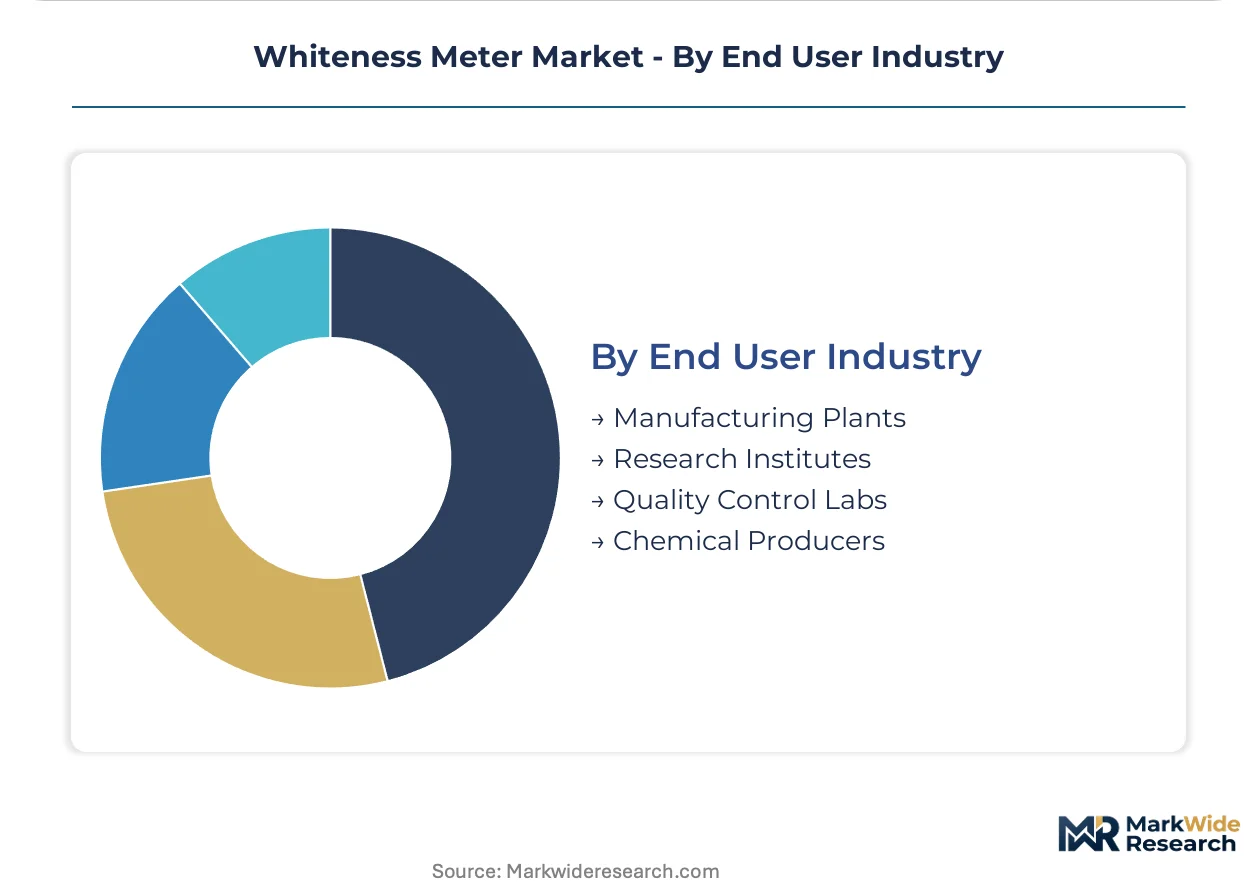
End user industry segmentation reveals distinct procurement patterns and operational scale among customers.
- Manufacturing Plants:Manufacturing plants integrate whiteness meters directly into production lines for real-time quality control and process optimization. This is crucial for large-scale plastics producers in the United States adhering to FDA regulations.
- Research Institutes:Research institutes utilize high-precision whiteness meters for material science studies, product development, and validation of new whitening agents. Academic and corporate R&D centers in Japan lead this segment.
- Quality Control Labs:Independent and in-house quality control labs use these meters for batch testing and certification against industry standards.
- Chemical Producers:Chemical producers employ whiteness meters to assess the purity and color of raw materials and finished products, including pigments and additives.
Large-scale production necessitates whiteness meters in Manufacturing Plants, whereas specialized testing drives demand in Research Institutes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A pronounced regional pricing-power asymmetry exists, with established markets like Germany driving premium demand while emerging economies such as India focus on cost-effective solutions. This divergence impacts instrument procurement and market access strategies across the globe. Manufacturers adjust offerings to cater to varied regulatory landscapes and industrial maturity levels.
Germany
Demand for whiteness meters in Germany stems from stringent quality control in paper & pulp and advanced manufacturing. ISO 11475 compliance is mandatory for high-value packaging exports, influencing instrument specifications. The Rhine-Main region, with its chemical and manufacturing clusters, actively integrates these instruments for purity verification.
United States
The United States experiences strong demand from plastics manufacturers and food contact material producers. FDA regulations for additives in food-grade plastics necessitate precise whiteness measurement. Major manufacturing hubs in the Midwest and Southeast adopt benchtop models for compliance and quality assurance.
China
China's expanding plastics manufacturing and textile industries drive significant whiteness meter adoption. GB standards for product quality and safety influence instrument specifications for local production. Industrial zones in the Yangtze River Delta integrate these devices for routine checks and export quality control.
India
India's textile sector relies on whiteness meters to ensure aesthetic consistency and prevent batch variations. BIS standards for textile products guide instrument selection for quality assurance. Production clusters in Gujarat and Tamil Nadu deploy portable units for on-site inspections and quality checks.
Japan
Japan's research institutes and high-tech manufacturing sectors require advanced whiteness measurement for material science. METI guidelines for industrial product quality influence instrument development and precision. Academic and corporate R&D centers in the Kanto region utilize high-precision benchtop models for innovation.
Whiteness Meter Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical optical modules. The market exhibits a tiered structure, with a few global leaders offering comprehensive solutions alongside numerous niche players. Strategic archetypes include full-spectrum providers, application-specific specialists, and regional distributors. Portfolio diversification and strategic partnerships represent dominant competitive moves among established players.
Within the specialized measurement segment, Konica Minolta Sensing Americas, Inc. exemplifies a global provider with a broad portfolio. Germany-based BYK-Gardner GmbH occupies a strong position in the European paints and coatings sector, reflecting its regional focus. HunterLab, an Inc.-structured entity, represents a specialist in appearance measurement solutions for specific industrial applications, anchoring its presence in niche markets.
| Leading Market Players |
|---|
| PCE Instruments |
| Konica Minolta Sensing Americas, Inc. |
| BYK-Gardner GmbH |
| HunterLab |
| X-Rite, Incorporated |
| Optics Technology |
| Caltech Engineering Services |
| EIE Instruments |
| Mesu Lab Instruments |
| Others |
Cost & Logistics Intelligence
Germany's advanced manufacturing capacity for high-precision optical instruments directly influences the premium pricing power for specialized whiteness meters across Europe. This concentration of expertise and production capability enables vendors to command higher margins for sophisticated benchtop and online models.
Pricing Analysis
Configured-to-order spectrophotometers command a premium due to their specialized calibration for unique industrial requirements. The pricing model primarily operates on a per-unit transactional basis for standard models, transitioning to a project-based approach for highly customized systems. Price differentiation stems from the customization level required for specific applications and the adherence to stringent certification levels like ISO 11475 for paper and pulp. Pricing softness emerges in the portable unit segment, driven by competition from multi-function devices offering basic whiteness measurement capabilities. Research institutes and pharmaceutical companies exhibit the least price sensitivity, prioritizing precision, while smaller textile and plastics converting enterprises are highly price-sensitive.
Supply Chain Analysis
Contract manufacturing of optical modules for whiteness meters concentrates in specialized facilities across Germany, Japan, and the United States. The supply chain relies heavily on high-purity optical sensors and specialized light sources as critical components. Single-source vulnerability for these high-precision optical components represents a significant structural risk, particularly for advanced spectrophotometers. Distribution primarily runs through direct sales channels for major industrial clients and research institutions, supplemented by regional distributors and value-added resellers serving smaller quality control labs and educational institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a high-growth disruption, driven by the emergence of digital appearance measurement technologies and increasingly stringent food contact regulations.
For Market Incumbents: Pre-empt competitive threats by investing heavily in cloud-based data services and developing multi-functional devices that integrate whiteness measurement. Focus R&D efforts on digital appearance measurement capabilities to virtualize physical reference standards, mitigating the threat from general-purpose colorimeters. Consolidate market position by acquiring niche specialists in fluorimetry to address the growing demand for OBA detection in paper and textiles.
For New Entrants and Emerging Players: Underpenetration in the pharmaceutical sector offers a significant white-space opportunity for specialized whiteness meters designed for powders and tablet coatings. Target recycled material verification in Europe and the United States, leveraging the circular economy trend. Penetrate the market through flexible equipment leasing models and subscription-based software services, appealing to smaller quality control labs and contract research organizations.
For Investors and Strategic Acquirers: Long-term, this sits as a precision instrument niche play because regulatory compliance and quality control remain non-negotiable across diverse industries. Identify acquisition targets specializing in camera-based systems or advanced fluorimetry to capture specialized segments. The growth in cloud-based data subscription uptake for remote diagnostics and comparative analysis across manufacturing sites is a crucial signal to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | Connects quality control data directly to manufacturing process optimization for real-time insights. |
| Specialized Sensor Development | Enhances accuracy for differentiating fluorescent from non-fluorescent whiteness in textiles. |
| Leasing Model Expansion | Lowers capital barriers for smaller quality control labs, broadening market access. |
| Regulatory Compliance Consulting | Provides value-added services, guiding clients through complex international standards. |
| Recycled Material Focus | Captures demand from circular economy initiatives requiring appearance standardization. |
Research Approach
Operator-level perspectives from quality control managers, R&D directors, procurement specialists, and regulatory experts anchored the qualitative base of this analysis. This primary research was triangulated with extensive secondary validation from sources such as ISO standards, FDA filings, trade association reports, and academic journals. The approach combined bottom-up data aggregation with top-down market sizing for comprehensive coverage.
The analytical framework employed scenario-bracketing to project market trajectories across the analysis window, accounting for various influencing factors. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional regulatory clusters. Compound annual growth rates (CAGRs) were derived from historical trends and projected forward based on anticipated market dynamics. Regulatory mandate evolution and material science advancements served as key industry-specific forecast inputs.
Practitioners should monitor new compliance directives, technological breakthroughs in optical sensing, and raw material supply disruptions for early signals of market shifts. Forecasts reflect assumptions regarding the stability of global trade policies and continued industrial investment in quality assurance. Quarterly review of regulatory updates and key technological advancements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Data Acquisition Equipment Market
Test and Measurement
Rohs Tester Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Coaxial Profile Projectors Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
Four-Quadrant Battery Simulator Market
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
Curve Tracer Market
Test and Measurement
Advanced Node Wafer Defect Inspection Systems Market
Test and Measurement
AI-Enabled Testing Tools Market
Test and Measurement
Tribometer Market
Test and Measurement
Density Tester Market
Test and Measurement
Noise Vibration Harshness (NVH) Testing Market
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
Optical Critical Dimension (OCD) Measurements System Market