
 Electrical Test Equipment Market | 2026-2036
Electrical Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Test Equipment Market Analysis
The gap between laboratory-grade precision instruments and field-portable commodity testers is repositioning how manufacturers allocate engineering resources. Keysight Technologies Inc. dominates high-frequency and semiconductor test segments through sustained R&D intensity. Fluke Corporation anchors the industrial maintenance channel with ruggedized handheld portfolios. Chroma ATE Inc. specializes in automated power electronics testing for electric vehicle battery validation.
Electrical test equipment encompasses instruments that measure voltage, current, resistance, frequency, and signal integrity across operating ranges from microvolts to kilovolts, using analog-to-digital conversion with sampling rates exceeding several gigasamples per second for high-bandwidth applications. These devices serve critical functions in product verification, safety certification, and operational troubleshooting across power generation, electronics manufacturing, and telecommunications infrastructure. Oscilloscopes and digital multimeters capture the largest revenue pools, while automated test systems represent the fastest-expanding category as automotive and aerospace end users integrate inline quality verification. Smart and connected instruments are displacing legacy analog units in utility and telecommunications deployments where remote diagnostics reduce field service costs.
FCC equipment authorization rules shape wireless-enabled test instrument market access in the United States, while EU CE marking and RoHS compliance constrain material composition and electromagnetic compatibility for products sold across Europe. Japan's METI energy efficiency standards influence power supply design within benchtop equipment sold domestically. Stakeholders must monitor evolving automotive functional safety standards and grid code harmonization as electrification expands test complexity beyond traditional parameter ranges.
Market Dynamics
Grid modernization mandates and semiconductor test complexity are pulling engineering resources toward automated validation systems, compressing development cycles for instruments that must span microvolt precision through kilovolt isolation.
Growth Catalysts
- EU Green Deal infrastructure mandates:German utilities are procuring smart grid diagnostic suites to meet renewable integration targets, requiring instruments with embedded communication protocols for distributed asset monitoring.
- Automotive electrification:Battery validation protocols for electric vehicle powertrains are expanding demand for automated power cycling test systems that simulate decade-long degradation in compressed test windows.
- Telecommunications 5G deployment:Millimeter-wave base station rollouts in South Korea and Japan are necessitating vector network analyzers with extended frequency ranges for signal integrity verification.
Market Restraints
- Precision component supply concentration:High-speed analog-to-digital converters and specialized ASICs for gigasample-per-second sampling rely on fabrication capacity concentrated in Taiwan and South Korea, creating input bottlenecks.
- Calibration infrastructure cost:Maintaining traceability to national metrology institutes requires capital-intensive reference standards and environmental controls that elevate total cost of ownership for end users.
- Regulatory fragmentation:Divergent electromagnetic compatibility certification requirements between FCC Part 15 rules in the United States and EU CE marking directives force redundant testing and regional product variants.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for domestic electronics manufacturing are creating demand for affordable test benches among contract manufacturers establishing assembly operations in Tamil Nadu and Karnataka.
- Cloud-native instrument architectures:Browser-based instrument control and centralized data lakes are enabling remote diagnostic services that reduce field deployment costs for utility asset management.
- Aerospace functional safety:DO-178C and DO-254 certification requirements for avionics systems are mandating traceable test coverage that favors integrated hardware-software validation platforms.
Industry Challenges
- RF engineering talent scarcity:Design of high-frequency test fixtures requires specialized electromagnetic simulation expertise that outpaces university pipeline output in North America and Western Europe.
- Legacy system integration friction:Brownfield manufacturing facilities in automotive and industrial sectors operate mixed-vintage equipment with incompatible data formats, complicating unified quality data architectures.
- Certification timeline compression:Accelerated product release schedules in consumer electronics are compressing the validation window for third-party safety agency approvals from UL and TÜV.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Test Equipment Market |
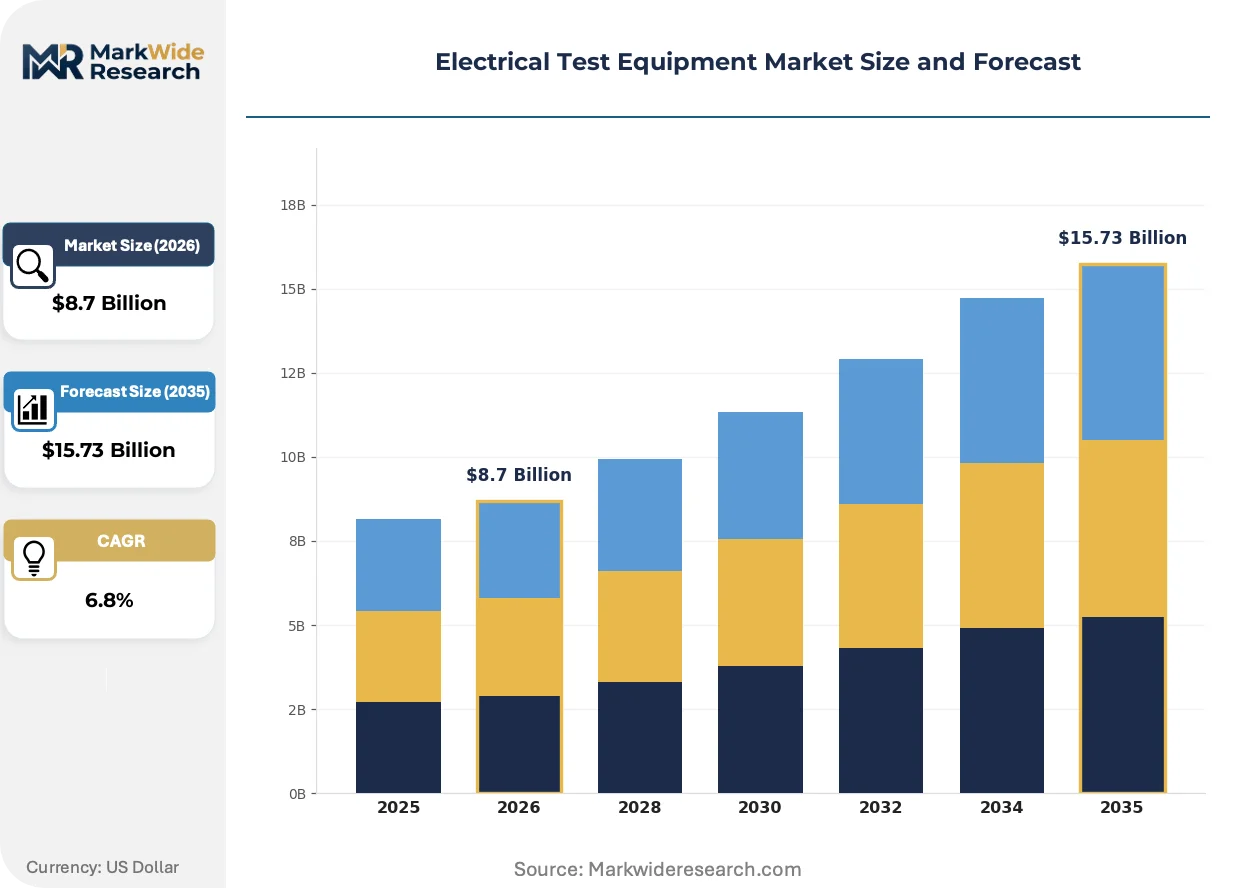
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multimeters, Oscilloscopes, Insulation Testers, Continuity Testers Application: Manufacturing, Maintenance, Research, Education Technology: Analog, Digital, Smart, Automated End User: Utilities, Telecommunications, Automotive, Aerospace |
| Companies Covered | Fluke Corporation, Anritsu Corporation, Keysight Technologies Inc., National Instruments Corporation, Chroma ATE Inc., Tektronix Inc., Yokogawa Electric Corporation, Hioki Corporation, Rohde & Schwarz GmbH & Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Test Equipment Market Emerging Trajectories
Software-defined instrumentation architectures are collapsing the traditional boundary between hardware measurement front-ends and cloud-based analytics, enabling subscription service models that alter capital deployment patterns for test assets.
Artificial intelligence-driven anomaly detection is automating pattern recognition in long-duration signal captures, allowing automotive battery manufacturers to reduce manual review of thermal runaway precursor signatures by an order of magnitude. The technology compresses test cycle duration while improving defect escape detection rates.
Japan's METI energy efficiency standards for industrial equipment are mandating standby power consumption limits below one watt for benchtop instruments sold domestically, forcing power supply redesigns that ripple through global product platforms. Manufacturers are responding with resonant converter topologies and adaptive sleep states that trade off warm-up time against quiescent draw.
Service unbundling is fragmenting the traditional capital sale model, with aerospace and defense primes negotiating instrument-as-a-service arrangements that transfer calibration liability and obsolescence risk to vendors. This shift concentrates in North American defense procurement, where federal acquisition regulations increasingly favor operational expenditure classification over capital asset ownership.
Electrical Test Equipment Market Segmentation
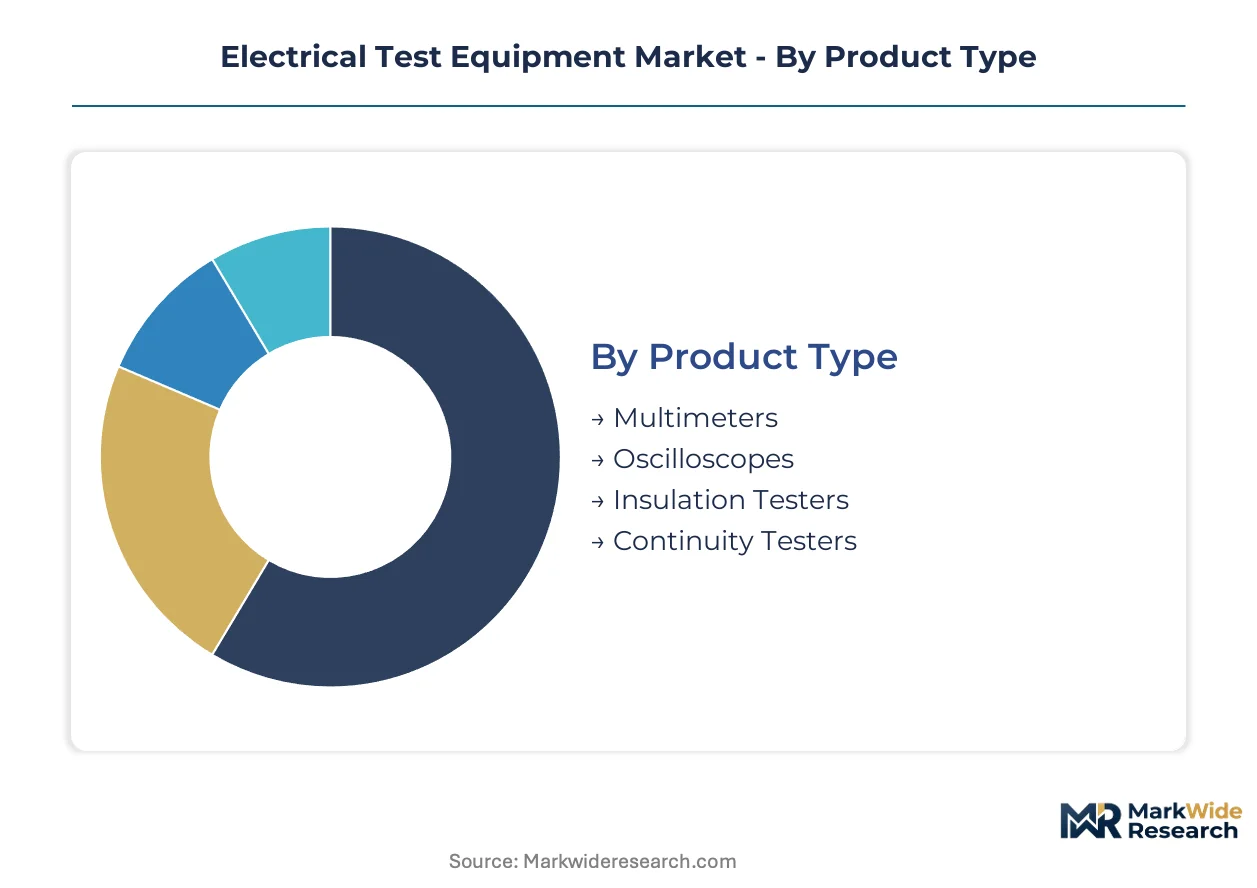
Segmentation in electrical test equipment reveals distinct engineering requirements across measurement precision tiers and deployment contexts. Standalone benchtop instruments serve calibration laboratories and R&D facilities, while embedded diagnostic modules integrate directly into manufacturing lines and field assets.
Product Type:
Integration depth varies sharply: multimeters and oscilloscopes function as discrete instruments in field troubleshooting, whereas insulation and continuity testers increasingly embed into automated production verification stations.
- Multimeters:Handheld and benchtop variants measure voltage, current, and resistance across ranges from microvolts to kilovolts. Demand concentrates in German automotive supplier networks where production line technicians require ruggedized units for daily electrical verification tasks.
- Oscilloscopes:Real-time and sampling architectures capture signal integrity with bandwidths spanning megahertz to gigahertz. South Korean 5G base station manufacturers procure high-bandwidth models for millimeter-wave circuit validation, driven by domestic deployment timelines.
- Insulation Testers:Megohm measurement instruments verify dielectric integrity in high-voltage cabling and motor windings.
- Continuity Testers:Low-resistance verification tools ensure ground bond integrity in electrical assemblies and protective conductor systems.
Multimeters lead volumes today; oscilloscopes are gaining share fastest.
Application:
Cost tier stratification separates capital-intensive automated test systems from portable field instruments, with maintenance budgets favoring replaceable units over repairable precision equipment.
- Manufacturing:Inline automated test equipment performs parametric verification at production cycle speeds. Japanese automotive battery plants in Nagoya deploy power cycling test systems that compress decade-long degradation simulation into compressed validation windows.
- Maintenance:Field-portable instruments support troubleshooting across distributed electrical infrastructure. German utilities procurement of smart grid diagnostic suites under EU Green Deal mandates drives ruggedized handheld demand.
- Research:Laboratory-grade precision instruments with traceable calibration chains serve metrology institutes and corporate R&D centers.
- Education:Cost-optimized training equipment introduces fundamental measurement concepts in technical vocational programs.
Manufacturing commands the largest capital allocation; maintenance volumes expand most quickly.
Technology:
Customer type differentiation separates regulated industries requiring traceable calibration from commercial sectors prioritizing speed and connectivity.
- Analog:Electromechanical meter movements persist in specific safety-critical applications requiring visual indication independence from power supply.
- Digital:Analog-to-digital conversion architectures dominate with sampling rates and resolution specifications determining price positioning.
- Smart:Network-connected instruments with embedded communication protocols enable remote diagnostics and distributed asset monitoring in utility deployments.
- Automated:Programmable test sequences with hardware-software integration support high-throughput validation in automotive and aerospace manufacturing.
Digital technology anchors installed base; automated systems show steepest expansion trajectory.
End User:
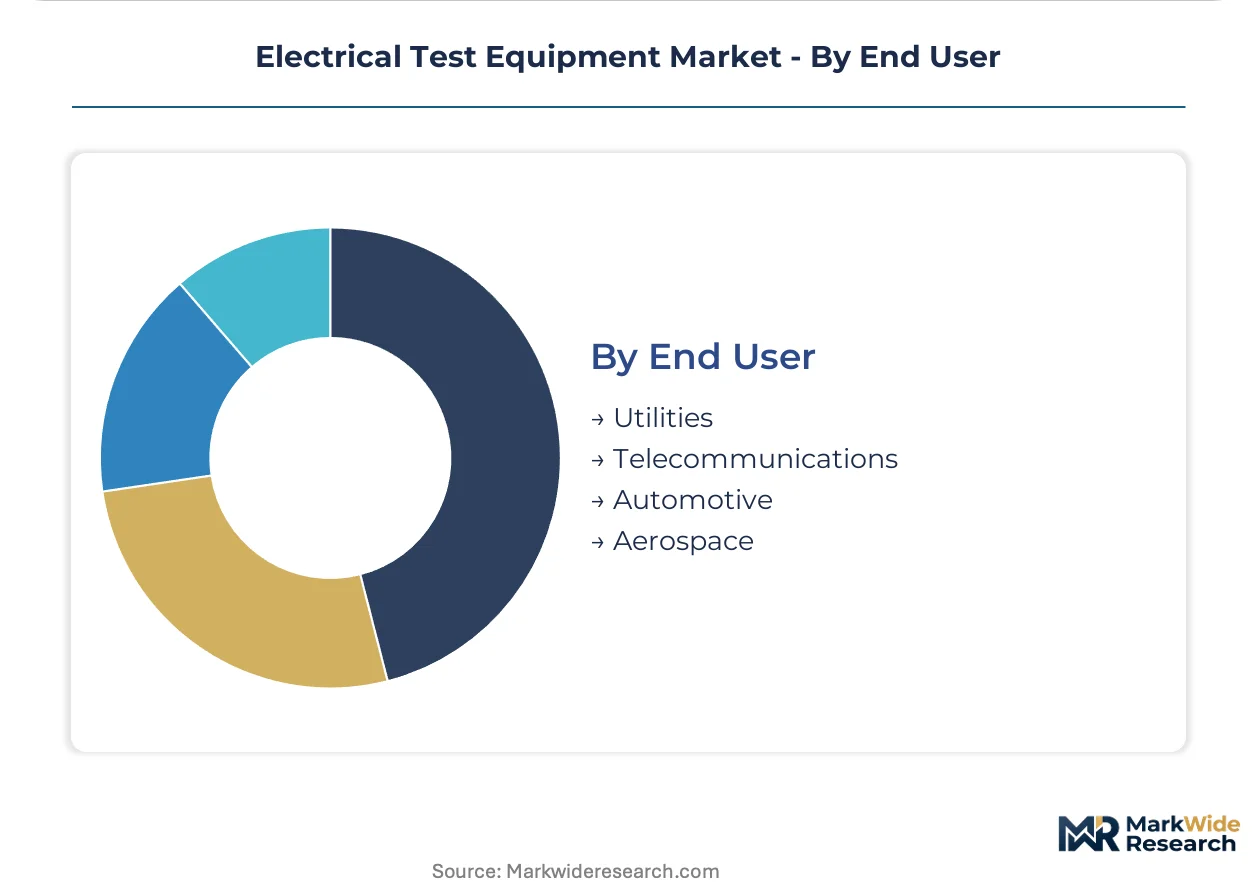
Geography shapes specification requirements, with regulatory environments and industrial structure driving distinct procurement patterns across national markets.
- Utilities:Grid modernization programs require diagnostic instruments with embedded communication protocols for distributed asset monitoring. North American investor-owned utilities deploy smart instrument networks to reduce field service dispatch costs.
- Telecommunications:5G infrastructure rollouts necessitate vector network analyzers and spectrum analyzers with extended frequency coverage. South Korean millimeter-wave base station deployment drives signal integrity verification equipment demand.
- Automotive:Electric vehicle powertrain validation requires automated power electronics test systems for battery cycling and inverter characterization.
- Aerospace:DO-178C and DO-254 functional safety mandates favor integrated hardware-software validation platforms with traceable test coverage documentation.
Automotive end-use leads absolute spending; telecommunications procurement climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF engineering talent pools concentrate in Germany, Japan, and the United States, anchoring high-frequency instrument design capabilities that migrate slowly despite cost pressures elsewhere.
United States
North American utilities deploy smart instrument networks for grid modernization, reducing field service dispatch costs through remote diagnostics. FCC equipment authorization rules govern wireless-enabled test instrument market access. Investor-owned utilities in Texas and California procure diagnostic suites with embedded communication protocols for distributed asset monitoring.
Germany
Industrial automation and automotive electrification drive precision testing requirements across supplier networks. EU Green Deal infrastructure mandates accelerate utility investment in smart grid diagnostic equipment. Automotive suppliers in Baden-Württemberg deploy ruggedized multimeters for daily electrical verification on production lines.
Japan
5G millimeter-wave base station rollouts necessitate vector network analyzers with extended frequency ranges for signal integrity verification. METI energy efficiency standards mandate standby power consumption limits below one watt for benchtop instruments. Battery plants in Nagoya deploy power cycling test systems that compress decade-long degradation simulation into compressed validation windows.
South Korea
Domestic 5G deployment timelines drive demand for high-bandwidth oscilloscopes in millimeter-wave circuit validation. National semiconductor fabrication strategy supports specialized ASIC supply for gigasample-per-second sampling architectures. Electronics manufacturers in Suwon and Seoul procure signal integrity verification equipment for base station component testing.
India
PLI scheme incentives for domestic electronics manufacturing create demand for affordable test benches among contract manufacturers. Central Electricity Authority regulations shape grid infrastructure testing requirements for emerging utility networks. Assembly operations in Tamil Nadu and Karnataka establish calibration-capable verification stations for export-bound electronics.
Electrical Test Equipment Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent engineering-resource allocation models. The market structure consolidates around high-frequency specialists with sustained R&D intensity, industrial maintenance channels anchored by ruggedized handheld portfolios, and automated power electronics testers for electric vehicle validation. Three archetypes dominate: precision laboratory instrument developers, field-portable commodity manufacturers, and integrated automated test system builders. Competitive moves concentrate on strategic partnerships for calibration infrastructure and geographic expansion into industrial automation growth markets.
Within the precision laboratory tier, Keysight Technologies Inc. and Rohde & Schwarz GmbH & Co KG exemplify sustained R&D intensity in high-frequency and semiconductor test segments. Among Asia-Pacific-based specialists, Anritsu Corporation and Yokogawa Electric Corporation occupy positions in telecommunications and industrial measurement applications. Chroma ATE Inc. represents the automated power electronics validation archetype, serving electric vehicle battery manufacturing requirements.
| Leading Market Players |
|---|
| Fluke Corporation |
| Anritsu Corporation |
| Keysight Technologies Inc. |
| National Instruments Corporation |
| Chroma ATE Inc. |
| Tektronix Inc. |
| Yokogawa Electric Corporation |
| Hioki Corporation |
| Rohde & Schwarz GmbH & Co KG |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Taiwan and Japan anchor precision component fabrication, concentrating supply-side discipline while forcing tier-one OEMs into long-term offtake commitments that lock in pricing corridors across oscilloscope and automated test system portfolios.
Pricing Analysis
The bundled-vs-unbundled service split separates capital-sale instruments from instrument-as-a-service arrangements where calibration liability transfers to vendors. Pricing stratifies across premium laboratory-grade, standard industrial, and economy field-portable tiers, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in economy handheld units is intensifying because contract manufacturers in India prioritize upfront acquisition cost over total cost of ownership. Maintenance departments in German automotive plants show least price sensitivity due to downtime cost exposure, while education procurement in emerging markets exhibits highest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements mandated by aerospace primes and automotive OEMs force qualification of redundant suppliers for high-speed analog-to-digital converters and specialized ASICs. Fabrication capacity concentrates in Taiwan, South Korea, and Japan, with raw material dependencies spanning silicon wafers, rare-earth magnetic components for probe assemblies, and high-purity copper for precision conductors. Single-source vulnerability in Taiwan-based foundry capacity represents the dominant structural risk. Distribution runs through authorized distributor networks with calibration-certified service capabilities rather than commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where automotive electrification and aerospace functional safety are pulling procurement toward premium specifications with traceable calibration chains.
For Market Incumbents: Extend calibration infrastructure ownership into emerging markets before local metrology institutes achieve international equivalence, defending against low-cost entrants from China targeting India's PLI-driven electronics manufacturing expansion. Prioritize R&D investment in software-defined architectures that enable subscription revenue streams. For New Entrants and Emerging Players: Direct-to-enterprise digital channels bypass distributor markups in segments where buyers self-specify, particularly among contract manufacturers establishing test capabilities in Tamil Nadu and Karnataka. White-space targets include affordable automated test benches for India's domestic electronics assembly and cloud-native instrument control platforms for utility asset management in North America. For Investors and Strategic Acquirers: Valuations sit cheapest among automated power electronics validation specialists serving electric vehicle battery manufacturing, where demand visibility extends through the projection horizon. Acquisition targets should exhibit captive calibration capabilities and embedded software content above fifty percent of instrument value. Watch for inflection in South Korean semiconductor capital expenditure as a demand signal for high-bandwidth test equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Partnership | Locks in recurring revenue streams with German automotive suppliers requiring traceable chains. |
| Software-Defined Architecture Development | Enables browser-based control that reduces field deployment costs for utility asset management. |
| Geographic Expansion into India | Captures PLI scheme-driven demand from contract manufacturers in Tamil Nadu and Karnataka. |
| Acquisition of RF Engineering Specialist | Addresses talent scarcity in millimeter-wave fixture design for 5G base station validation. |
| Automotive Functional Safety Certification | Qualifies platforms for DO-178C and DO-254 mandates in aerospace and electric vehicle programs. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with test equipment R&D directors, calibration laboratory managers, OEM procurement teams, and aftermarket service heads with secondary validation against SEC filings, customs trade data, and national metrology institute accreditation records. Bottom-up and top-down triangulation reconciles instrument shipment data with end-user capital expenditure disclosures.
Granularity-level framing models revenue at the intersection of product type, application context, technology tier, and end-user industry, with additional dimensioning by regional regulatory cluster and certification requirement. CAGRs derive from segment-level growth rate reconciliation against macroeconomic drivers and technology substitution curves across the projection horizon. Forecast inputs incorporate automotive battery plant buildout schedules and telecommunications infrastructure deployment timelines.
Semiconductor fabrication capacity constraints, automotive platform launch delays, and grid code harmonization failures are the dominant revision risks to the outlook. Deviation in Taiwan foundry utilization rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Europe Nondestructive Testing Equipment Market
Test and Measurement
DSL Tester Market
Test and Measurement
Duct Integrity Tester (DIT) Market
Test and Measurement
High Voltage Testing Market
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market
Test and Measurement
Global Arbitrary Waveform Generator Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Clamp Meters Market
Test and Measurement
State Transition Testing Market
Test and Measurement
Asia-Pacific Nondestructive Testing Equipment Market
Test and Measurement
Fogging Tester Market
Test and Measurement
Non-Destructive Testing Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Global Laser Tracker Market
Test and Measurement
Manufacturing Test Systems Market