
 Battery Capacity Testers Market | 2026-2036
Battery Capacity Testers Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Capacity Testers Market Outlook
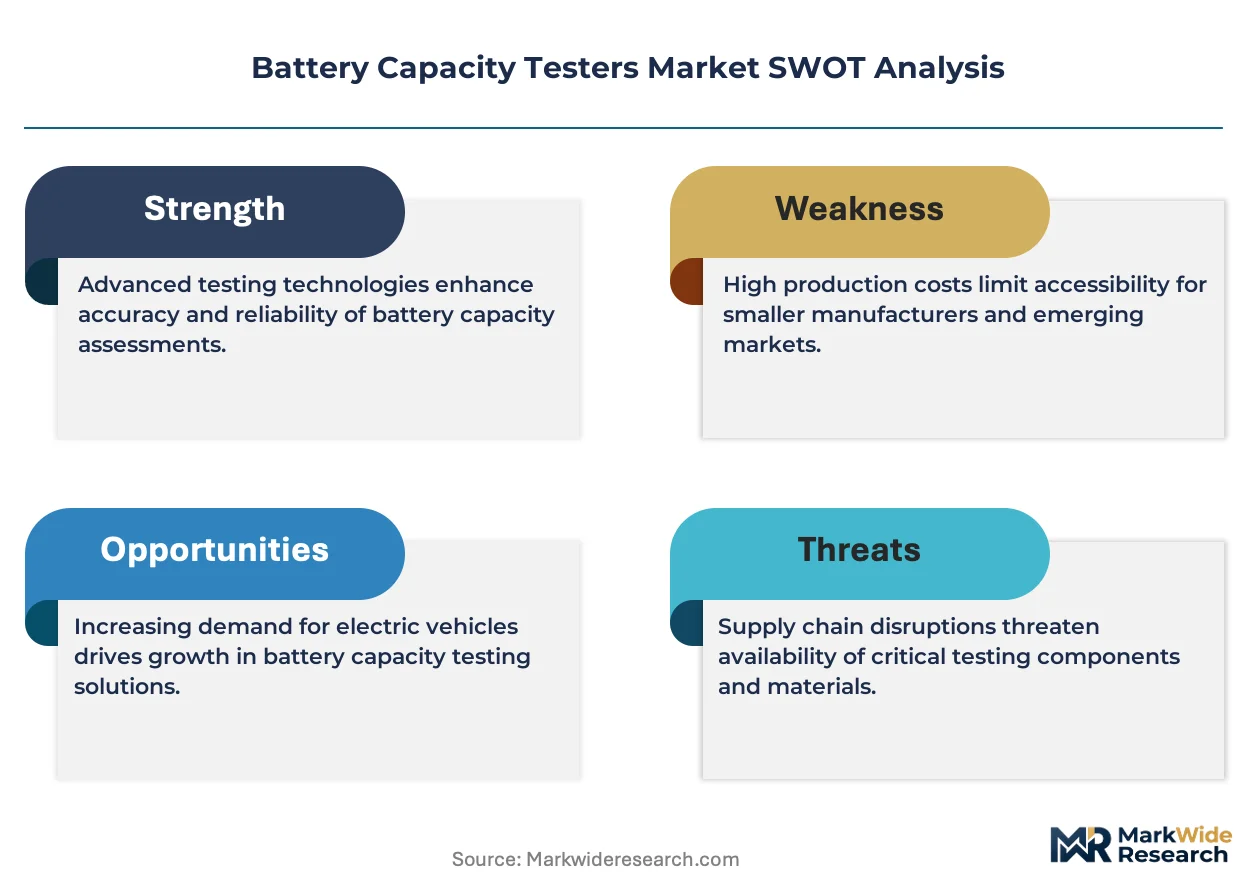
Asset-light leasing models for high-precision test equipment is rewriting competitive entry barriers for mid-sized battery laboratories. Arbin Instruments leverages its vertical integration into cell cycling hardware to sustain pricing power in North American EV R&D centers. Chroma ATE Inc. anchors its position through manufacturing scale in power electronics validation, while Keysight Technologies differentiates via software-defined measurement architectures that extend instrument utility across multiple chemistries.
A battery capacity tester is an electrochemical diagnostic instrument that applies controlled load profiles, impedance spectroscopy, or conductance measurements to quantify remaining charge capacity, internal resistance, and state-of-health against manufacturer-rated specifications. These instruments typically operate across voltage ranges from millivolt-level coin cells to 1,000 V+ battery pack systems, with current sourcing capabilities spanning microamps to kiloamps depending on application scale. Digital testers lead product type revenue due to their integration with laboratory information management systems, while automatic testers represent the fastest-growing configuration as EV production lines demand throughput without operator intervention. Conductance technology dominates portable field-service applications, whereas impedance analysis commands premium positioning in research-grade bench units where resolution below one milliohm determines cell grading accuracy.
The EU Battery Regulation and CE marking requirements under the MDR framework are mandating traceable state-of-health documentation for second-life battery deployments, directly expanding demand for calibrated capacity verification equipment. The EPA and NHTSA in the United States are tightening end-of-life battery handling protocols, pushing recyclers and automotive dismantlers toward standardized capacity assessment tools. Stakeholders must monitor how evolving UN 38.3 transport testing harmonization affects the specification baseline for portable versus rack-mounted tester portfolios.
Market Dynamics
EV manufacturers are internalizing battery validation programs, compressing third-party testing demand while elevating specifications for in-house equipment. This vertical consolidation is redrawing procurement patterns and technical requirements across the supply base.
Growth Catalysts
- EU Battery Regulation:Mandated state-of-health declarations for industrial and automotive batteries are expanding demand for calibrated capacity verification equipment across European testing facilities.
- Second-life battery deployments:Traceable documentation requirements under CE marking and MDR frameworks are driving recycler investment in standardized assessment tools.
- Impedance spectroscopy:Research-grade bench units with sub-milliohm resolution are commanding premium positioning as cell grading accuracy becomes a competitive differentiator.
Market Restraints
- Precision sensor supply concentration:High-accuracy current shunts and voltage references concentrate among Japanese and German component suppliers, creating input bottlenecks.
- Capital intensity for multi-chemistry compatibility:Software-defined architectures require substantial R&D investment to support lithium-ion, solid-state, and sodium-ion protocols simultaneously.
- Calibration infrastructure scarcity:NIST-traceable reference standards for kiloamp-range testers remain limited to a handful of national metrology institutes.
Strategic Opportunities
- India battery manufacturing:PLI scheme incentives for cell production are creating demand for validation equipment as domestic gigafactories scale operations.
- Leasing models for mid-sized laboratories:Asset-light access to high-precision test equipment is lowering entry barriers for independent validation services.
- UN 38.3 transport testing harmonization:Evolving lithium battery shipping protocols are expanding specification requirements for portable versus rack-mounted tester portfolios.
Industry Challenges
- Electrochemical engineering talent scarcity:Cross-functional expertise spanning battery chemistry, power electronics, and software integration remains concentrated among a limited pool of specialists.
- ISO 17025 accreditation timelines:Third-party laboratories face extended certification cycles for high-voltage battery pack testing capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Capacity Testers Market |
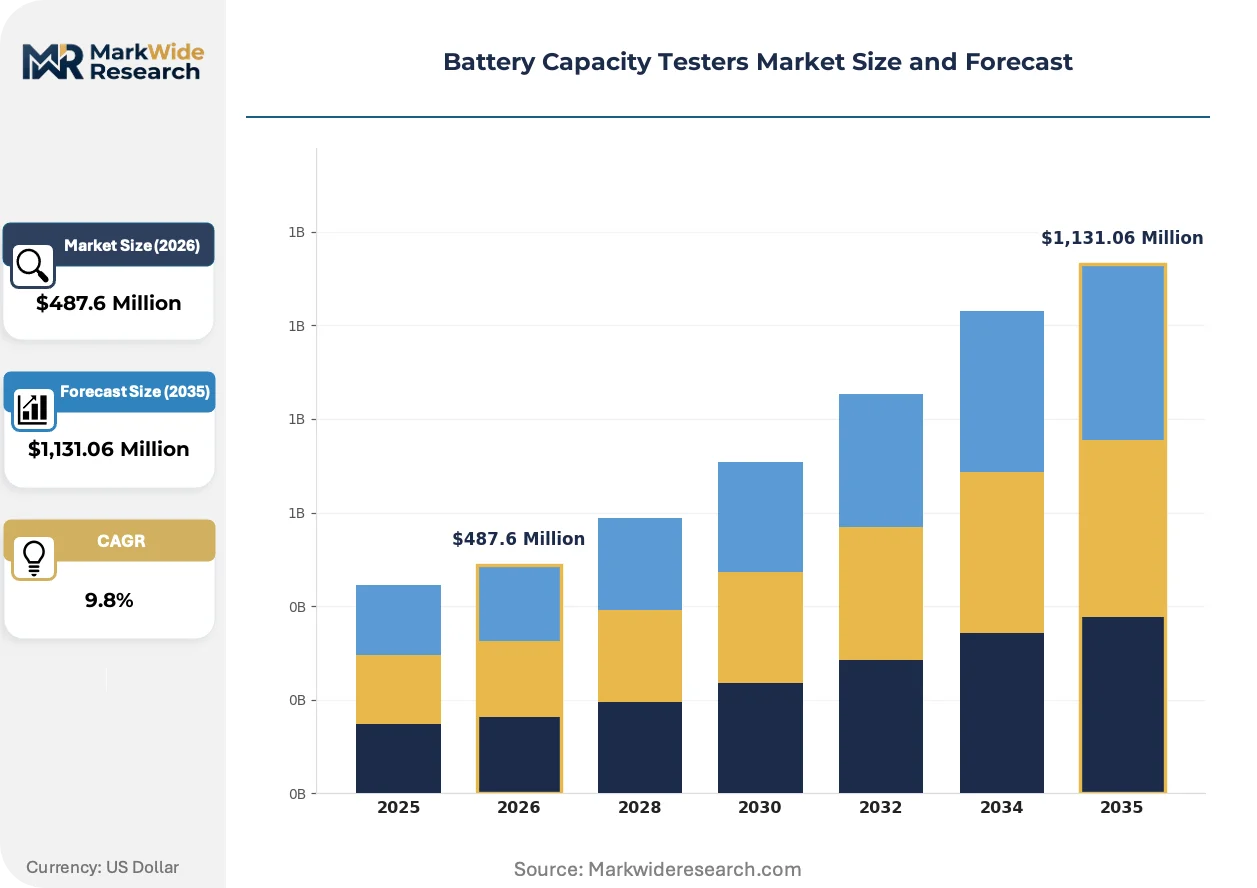
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,131.06 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Testers, Analog Testers, Automatic Testers, Manual Testers Technology: Conductance, Impedance, Load Testing, Voltage Measurement End User: Automotive, Electronics, Renewable Energy, Industrial Equipment Size: Portable Units, Bench Units, Rack-Mounted Units, Bulk Deliveries |
| Companies Covered | Arbin Instruments, Hioki E.E. Corporation, Neware Battery Testers, Chroma ATE Inc., Keysight Technologies, BioLogic, AMETEK Inc., Megger Group Limited, DIGATRON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Capacity Testers Market Strategic Shifts
Test equipment architectures are converging around software-defined measurement platforms that decouple hardware from protocol-specific functionality. This shift is compressing product development cycles and extending instrument utility across evolving battery chemistries.
Impedance spectroscopy is hybridizing with traditional DC load testing to enable simultaneous capacity and internal resistance characterization in single test sequences. Automotive OEMs in Germany and South Korea are adopting these hybrid architectures for production-line incoming inspection. The convergence is compressing test cycle times while elevating data granularity for predictive state-of-health algorithms.
REACH substance restrictions and RoHS amendments are tightening material composition requirements for test equipment electronics, particularly affecting high-current contactors and thermal management components. Manufacturers are reformulating solder alloys and connector plating to maintain conductivity under stricter substance limits. European test equipment vendors face accelerated redesign cycles to maintain CE marking compliance.
Buying organizations are consolidating supplier relationships around full-stack validation partners capable of integrating cell cycling, environmental simulation, and safety testing. Tier-1 battery producers in China and Japan are reducing vendor counts from five-plus to two or three strategic partners. This concentration is elevating contract values while compressing margins for standalone equipment specialists.
Battery Capacity Testers Market Segmentation
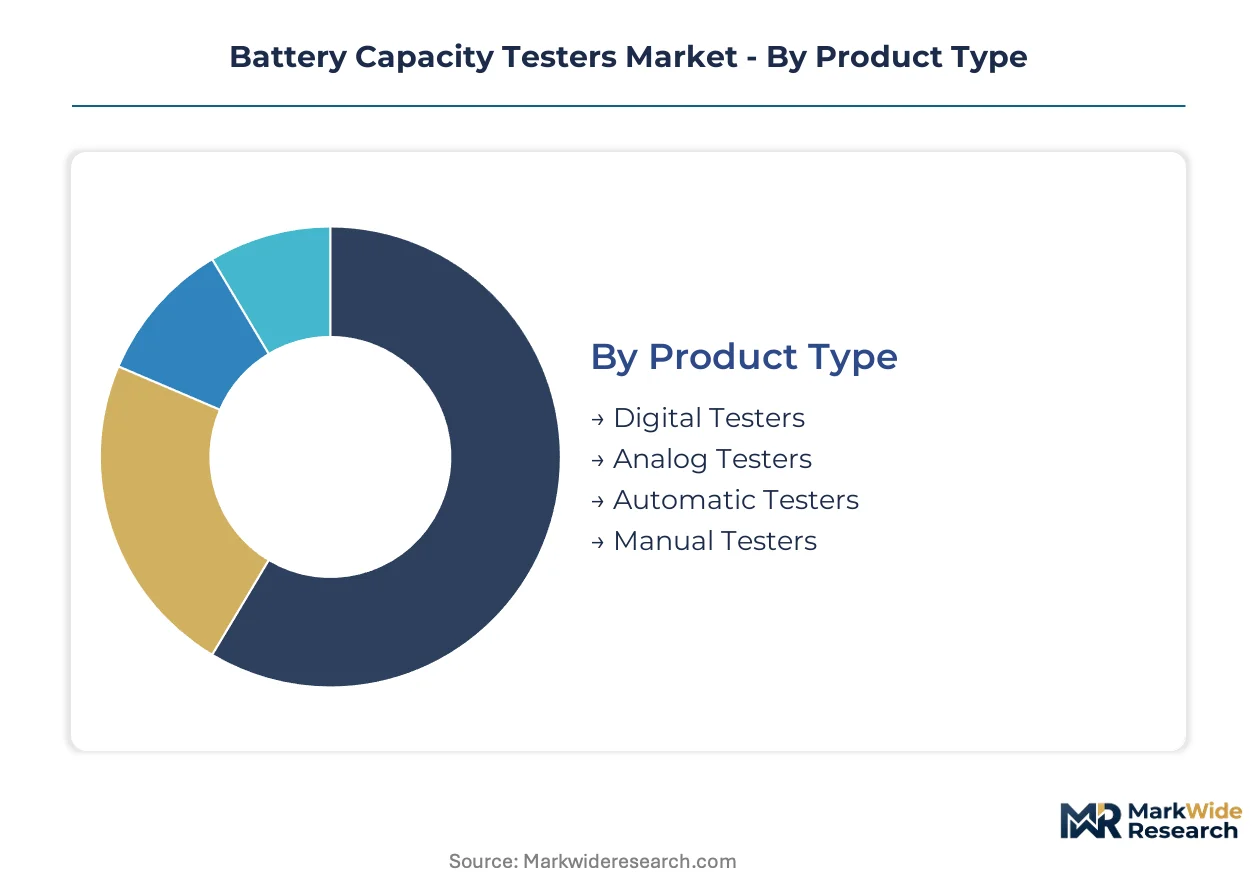
Segmentation in battery capacity testers reflects divergent service intensity requirements across validation workflows. Equipment specifications, calibration protocols, and replacement part availability vary sharply between laboratory installations and field-service deployments.
Product Type:
After-sales service intensity escalates with automation complexity, driving divergent margin structures across tester configurations.
- Digital Testers:These instruments integrate analog-to-digital conversion with embedded firmware for data logging and LIMS connectivity. Laboratories in Germany prioritize digital testers for their traceability features under EU Battery Regulation documentation requirements. By volume, digital testers lead. By growth pace, automatic testers are ahead.
- Automatic Testers:Programmable load sequencing eliminates operator intervention for high-throughput EV production lines. South Korean automotive OEMs deploy these for incoming cell inspection at gigafactory scale. Calibration contracts and software maintenance generate recurring revenue streams that exceed hardware margins.
- Analog Testers:Simpler electromechanical designs persist in cost-sensitive educational and basic maintenance applications.
- Manual Testers:Handheld units serve field technicians requiring immediate capacity verification without external power.
Service revenue attachment rates favor automatic configurations, though digital platforms retain broader installed base coverage.
Technology:
Cost tier stratification separates research-grade precision from operational screening tools.
- Impedance:Spectroscopic methods resolve internal resistance below one milliohm for cell grading accuracy. Research institutions in Japan and Germany specify impedance analyzers for solid-state battery development programs.
- Conductance:Alternating current injection enables rapid state-of-health assessment without full discharge cycles. Field service operations across North American utility fleets favor conductance for its speed and portability.
- Load Testing:Controlled DC discharge remains the reference method for capacity verification against manufacturer ratings.
- Voltage Measurement:Basic open-circuit voltage readings provide preliminary screening in low-stakes applications.
Impedance commands premium pricing tiers; conductance dominates unit shipment volumes.
End User:
Application-specific certification requirements fragment procurement specifications across verticals.
- Automotive:EV manufacturers internalize validation programs with multi-chemistry protocol support. OEM facilities in Germany operate kiloamp-range rack systems for pack-level verification.
- Renewable Energy:Utility-scale battery installations demand periodic capacity auditing for warranty compliance and insurance coverage.
- Electronics:Consumer device manufacturers require compact bench units for coin cell and pouch format validation.
- Industrial Equipment:Forklift and stationary power applications prioritize ruggedized portable testers for maintenance workflows.
Automotive absorbs the highest equipment value per installation; renewable energy shows steepest expansion trajectory.
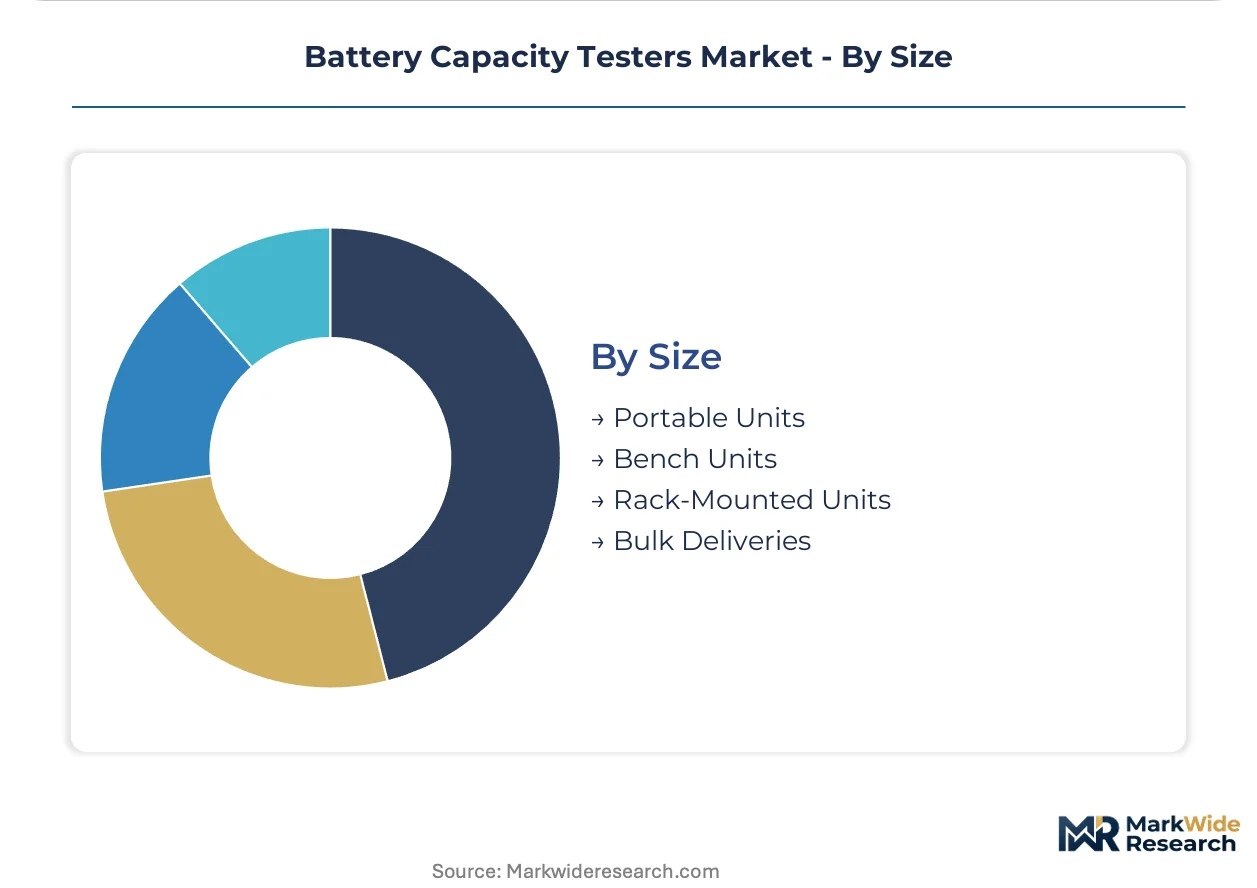
Size:
Supply chain configuration determines lead time differentiation across form factors.
- Rack-Mounted Units:Modular chassis accommodate multi-channel configurations for production-line integration. Chinese cell producers specify these for high-volume cycling operations.
- Bench Units:Self-contained instruments balance precision with laboratory footprint constraints.
- Portable Units:Battery-powered designs enable field verification without facility infrastructure.
- Bulk Deliveries:Containerized test stations serve gigafactory commissioning and large-scale recycling operations.
Rack-mounted systems generate largest individual contract values; portable units ship in highest quantities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives and EU Battery Regulation mandates are redirecting capacity tester procurement toward domestic validation infrastructure across major manufacturing economies.
Germany
Automotive OEMs operate kiloamp-range rack systems for pack-level verification at facilities in Stuttgart and Munich. The EU Battery Regulation mandates state-of-health declarations that expand demand for calibrated equipment. Testing clusters in Baden-Württemberg concentrate incoming cell inspection capacity for gigafactory supply chains.
China
Cell producers specify modular multi-channel configurations for high-volume cycling operations in Shenzhen and Ningde. GB standards and MIIT guidelines shape equipment specifications for domestic battery validation. Yangtze River Delta manufacturing hubs integrate capacity testing into production line commissioning workflows.
United States
EPA and NHTSA protocols push recyclers and automotive dismantlers toward standardized assessment tools in Michigan and California. The IRA manufacturing incentives accelerate domestic gigafactory buildouts requiring validation equipment. Detroit-area R&D centers deploy software-defined architectures for multi-chemistry protocol support.
South Korea
Automotive OEMs adopt hybrid impedance-load architectures for production-line incoming inspection in Ulsan and Pyeongtaek. MFDS-equivalent industrial standards and KTL certification requirements govern equipment procurement. Seoul Capital Area battery producers consolidate supplier relationships around full-stack validation partners.
India
PLI scheme incentives for cell production create demand for validation equipment as domestic gigafactories scale in Gujarat and Tamil Nadu. BIS standards and CEA technical regulations establish baseline specifications for testing infrastructure. Manufacturing clusters in Maharashtra deploy bench and rack-mounted units for commissioning operations.
Battery Capacity Testers Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers differentiated by measurement precision, software integration depth, and service attachment models. Precision instrument specialists with captive calibration infrastructure occupy the premium tier. Power electronics fabricators with manufacturing scale anchor the mid-market. Portable field-service specialists compete on unit economics and distribution reach. Competitive moves center on backward integration into sensor manufacturing and strategic partnerships with gigafactory operators.
Within the precision instrument tier, Arbin Instruments and Hioki E.E. Corporation exemplify archetypes built around vertical control over measurement hardware and Japanese component sourcing respectively. Chroma ATE Inc. occupies a position among Taiwan-based power electronics validators where manufacturing scale in semiconductor test equipment transfers to battery cycling applications. Keysight Technologies represents the software-defined measurement vector, leveraging instrumentation heritage to decouple hardware from protocol-specific functionality across chemistry generations.
| Leading Market Players |
|---|
| Arbin Instruments |
| Hioki E.E. Corporation |
| Neware Battery Testers |
| Chroma ATE Inc. |
| Keysight Technologies |
| BioLogic |
| AMETEK Inc. |
| Megger Group Limited |
| DIGATRON |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese cell cycling equipment is compressing margins for mid-tier testers while elevating pricing power for NIST-traceable calibration services. This utilization divergence forces suppliers toward either premium metrology positioning or volume manufacturing scale.
Pricing Analysis
Certification level creates the primary spread between entry-level and research-grade equipment. Three-tier pricing structure across premium, standard, and economy levels dominates, with CE-marked units commanding 40-60% premiums over uncertified alternatives in European procurement. Price differentiation hinges on calibration traceability and software protocol breadth. Pricing pressure stems from Chinese manufacturers flooding the mid-market with GB-standard equipment. Renewable energy utilities show highest price sensitivity; automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Japanese export controls on high-precision current shunts and voltage references are constraining flows to non-allied manufacturing bases. Component sourcing draws from Japan, Germany, and South Korea for critical measurement hardware. Raw material dependencies include copper busbars, precision resistors, and ceramic substrates for high-current contactors. Single-source vulnerability concentrates in NIST-traceable reference standards. Distribution runs through direct OEM relationships for rack systems and regional distributors for portable field units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined measurement platforms are reconfiguring this market toward interoperability ecosystems, with protocol-agnostic architectures displacing chemistry-specific hardware. This platform shift rewards vendors who decouple firmware from physical instrumentation.
For Market Incumbents: Build captive calibration infrastructure as the primary moat. Invest in NIST-traceable reference laboratories to lock in automotive OEM procurement. Deepen backward integration into precision sensor manufacturing to offset Japanese component bottlenecks. Threat: Chinese equipment makers undercutting on GB-standard specifications.
For New Entrants and Emerging Players: India's PLI-subsidized gigafactory buildout represents the most penetrable geography for validation equipment. Target leasing models for mid-sized independent laboratories lacking capital for rack-system purchases. Go-to-market angle: asset-light subscription pricing bundled with ISO 17025 accreditation support.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automatic tester manufacturers with embedded software maintenance contracts. Long-term viability favors vendors with multi-chemistry protocol support spanning solid-state and sodium-ion architectures. Acquisition target: precision instrument specialists with captive metrology infrastructure. Signal to watch: UN 38.3 harmonization timelines affecting portable versus rack-mounted specification requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive supply of high-accuracy current shunts reduces exposure to Japanese export restrictions. |
| Software-Defined Measurement Platform Launch | Protocol-agnostic architectures extend instrument utility across lithium-ion, solid-state, and sodium-ion chemistries. |
| Calibration Infrastructure Expansion | NIST-traceable laboratories secure automotive OEM procurement under EU Battery Regulation mandates. |
| Leasing Model Introduction | Asset-light access lowers entry barriers for mid-sized battery laboratories in India and Southeast Asia. |
| Multi-Chemistry Protocol Certification | CE marking and GB standard compliance unlock procurement channels across European and Chinese gigafactories. |
Study Parameters
Desk research of customs trade databases, SEC filings from precision instrument manufacturers, and EU regulatory bulletins preceded structured interviews with battery testing laboratory directors, automotive OEM validation engineers, and metrology equipment procurement managers. Primary fieldwork across Germany, China, and the United States captured equipment specification requirements and purchasing decision criteria. Secondary validation drew from MIIT technical guidelines, EPA handling protocols, and BIS standards documentation. Bottom-up equipment shipment data triangulated against top-down gigafactory investment announcements.
Assumptions held fixed include continuation of EU Battery Regulation documentation requirements and PLI scheme incentive structures across the analysis window. Segmentation modeling incorporated product type, technology method, end-use vertical, and geographic production cluster dimensions. CAGRs derived from equipment procurement patterns tied to announced cell manufacturing capacity buildouts. Industry-specific inputs included impedance spectroscopy adoption curves and automatic tester penetration rates in EV production lines.
Practitioners should monitor export control expansions on precision measurement components and UN 38.3 protocol harmonization timelines for early signals of specification shifts. Forecasts reflect assumptions regarding sustained automotive OEM internalization of validation programs and continued scarcity of NIST-traceable calibration infrastructure. Material shifts in Japanese semiconductor equipment export restrictions or EU Battery Regulation enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Semiconductor Chip Test Probes Market
Test and Measurement
Metrology Software Market
Test and Measurement
Optical Critical Dimension (OCD) Measurements System Market
Test and Measurement
Radiography Test Equipment Market
Test and Measurement
Durometer Calibration Service Market
Test and Measurement
Continuous Level Measurement Market
Test and Measurement
In-Circuit Test Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market
Test and Measurement
Analog Multimeters Market
Test and Measurement
Test and Measurement Equipment Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
RF Test Equipment Market
Test and Measurement
Industrial X-Ray Inspection System Market
Test and Measurement
Sound Level Meter Market
Test and Measurement
Digital Moisture Meters Market