
 Fuel Capacitance Test Equipment Market | 2026-2036
Fuel Capacitance Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Capacitance Test Equipment Market Foresight
Buyer concentration among aircraft servicing firms is consolidating as regional MRO providers merge to secure long-term contracts with tier-one airlines. Barfield Inc. leverages its FAA-approved repair station network to dominate North American aftermarket service. Teledyne Technologies sustains its position through proprietary capacitive sensing architectures deployed across military and commercial aviation platforms. Keysight competes by extending RF analysis capabilities into automated fuel system diagnostics for next-generation narrow-body aircraft.
Fuel capacitance test equipment comprises precision instrumentation that measures dielectric properties of aviation and refined petroleum fuels to verify fuel quantity indication system accuracy, typically operating across frequency ranges of 1 kHz to 10 MHz with temperature compensation protocols. These systems serve the essential commercial purpose of ensuring airworthiness compliance and preventing fuel starvation incidents during flight operations. Portable testers lead volume demand among field maintenance crews, while automated systems capture expanding margin pools in refinery process control. Capacitive sensing anchors technology selection for aerospace applications, whereas impedance spectroscopy gains traction in biofuel production where variable ethanol blends complicate dielectric calibration.
FAA airworthiness directives mandate recurrent calibration intervals for fuel quantity test sets, compelling MRO providers to maintain certified equipment inventories. EASA's CS-25 certification standards for large aeroplanes impose equivalent test rig requirements across European maintenance networks. Stakeholders must monitor evolving SAF blending specifications and corresponding dielectric property shifts that will necessitate equipment recalibration protocols.
Market Dynamics
Fleet modernization mandates from the FAA and EASA are compressing calibration cycles for fuel quantity indication systems, forcing MRO networks to expand certified test equipment inventories faster than organic demand growth alone would justify.
Growth Catalysts
- SAF Blending Mandates:European Union Green Deal targets for sustainable aviation fuel integration are creating dielectric property recalibration requirements that extend equipment replacement cycles into new fuel certification protocols.
- CS-25 Certification Standards:EASA's airworthiness requirements for large aeroplanes mandate specific test rig configurations, compelling European maintenance networks to standardize on compliant capacitance measurement systems.
- Narrow-Body Fleet Expansion:Airlines in China and India are adding single-aisle aircraft at rates that outstrip existing MRO capacity, driving greenfield test equipment procurement for new maintenance stations.
Market Restraints
- Precision Component Concentration:High-stability reference capacitors and temperature-compensated oscillators rely on Japanese and German specialty component suppliers, creating single-source vulnerability for test equipment manufacturers.
- Platinum Group Metal Volatility:Electrode materials in precision capacitive sensors contain palladium and platinum, exposing production costs to commodity price swings that compress margin predictability.
- Impedance Spectroscopy Substitution:Biofuel refineries are adopting broadband dielectric analysis systems that bypass traditional capacitance testing entirely, threatening equipment category relevance in emerging fuel segments.
Strategic Opportunities
- India MRO Infrastructure:The country's civil aviation regulator is licensing new maintenance facilities at regional airports, creating first-mover advantage for test equipment vendors establishing calibration service partnerships.
- Automated Refinery Integration:Inline capacitance monitoring for continuous process control represents an unserved application where aerospace-grade precision could transfer to hydrocarbon processing quality assurance.
- Dual-Use Military Specification Convergence:NATO standardization initiatives are aligning military and commercial aviation test protocols, opening equipment platforms to cross-certified procurement pools.
Industry Challenges
- Metrology Talent Scarcity:Field calibration of capacitance test sets requires traceable standards expertise that aviation-focused technical programs are not producing at replacement rates.
- Legacy System Integration Friction:New digital test equipment must interface with analog fuel quantity gauges installed on aging regional aircraft fleets, complicating certification documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Capacitance Test Equipment Market |
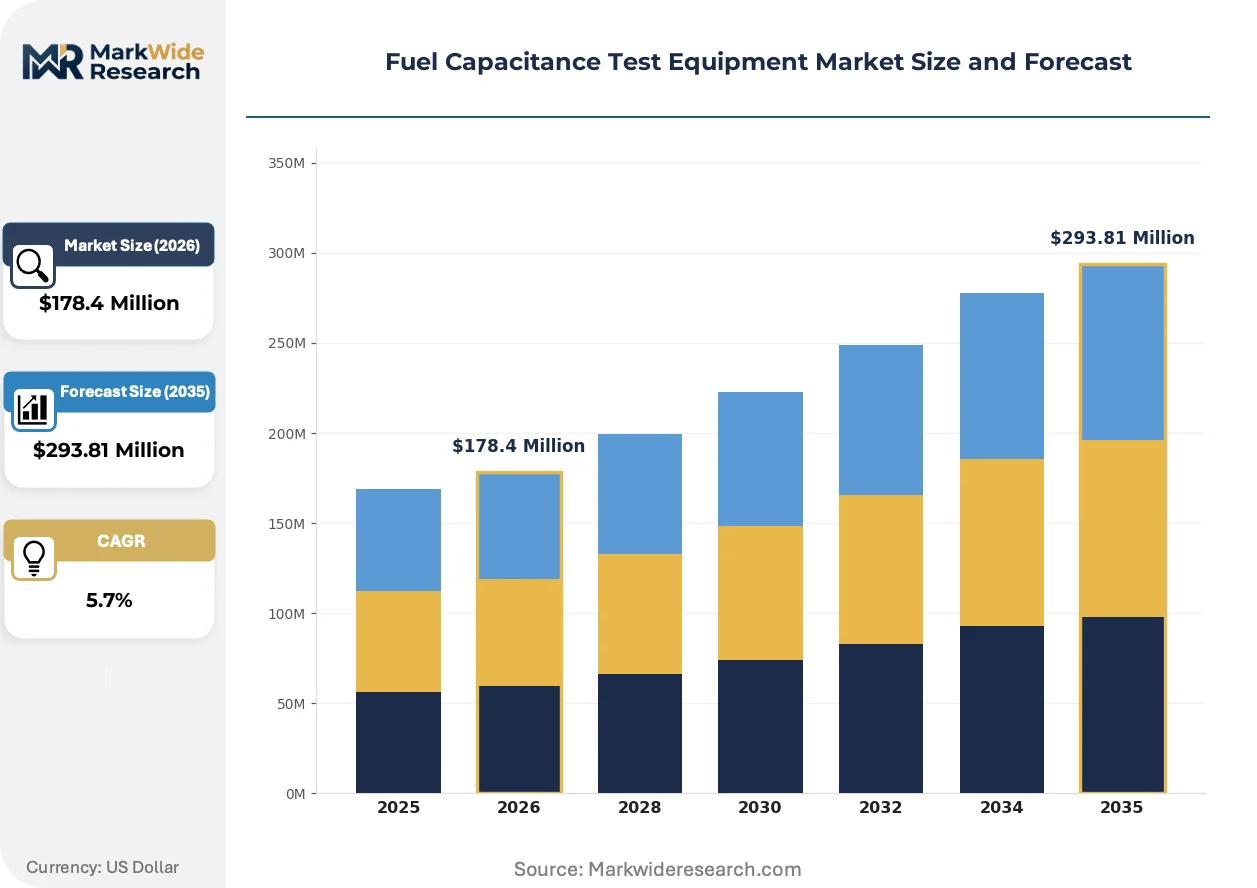
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $293.81 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Testers, Benchtop Units, Online Monitors, Battery Operated Devices, Automated Systems Technology: Capacitive Sensing, Ultrasonic Measurement, Laser-Based Detection, Impedance Spectroscopy, RF Analysis Application: Petroleum Processing, Biofuel Production, Aerospace Fuel Systems, Marine Fuel Monitoring, Refinery Maintenance End User: Refining Companies, Fuel Additive Manufacturers, Aircraft Servicing Firms, Shipbuilding Units, Petrochemical Plants |
| Companies Covered | MERATRONIK S.A., Barfield Inc., Ultra, Gull Airborne Instruments, Edmodo, Shenzhen Times HongYuan Technology Co., Ltd, Keysight, Fluke, Teledyne Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Capacitance Test Equipment Market Shifts & Advancements
Digital signal processing architectures are displacing analog measurement circuits across portable and rack-mounted test equipment, enabling software-defined calibration curves that adapt to emerging fuel formulations without hardware replacement.
Multi-frequency impedance analyzers are modularizing test system architectures by separating signal generation, sensing, and processing into swappable sub-assemblies. MRO providers in Germany and the United States are adopting these configurations to reduce field service inventory burdens. This modularity is compressing equipment lifecycle costs while accelerating compliance updates for new dielectric specifications.
EASA's expanding airworthiness directive scope for fuel system accuracy verification is mandating documented traceability chains for all calibration equipment used in European-registered aircraft maintenance. The directive forces MRO networks to retire uncertified legacy test sets and adopt ISO 17025-accredited systems. Narrow-body operators with European routes are consolidating supplier relationships to simplify audit compliance across multiple station locations.
Airline engineering departments are unbundling test equipment procurement from long-term service contracts, separating capital expenditure decisions from ongoing calibration support. This disintermediation pressures traditional bundled vendors and creates direct sales opportunities for specialized capacitance instrument manufacturers. The pattern is most pronounced among low-cost carriers in Southeast Asia seeking to minimize total cost of ownership through competitive tendering for each cost element.
Fuel Capacitance Test Equipment Market Segmentation
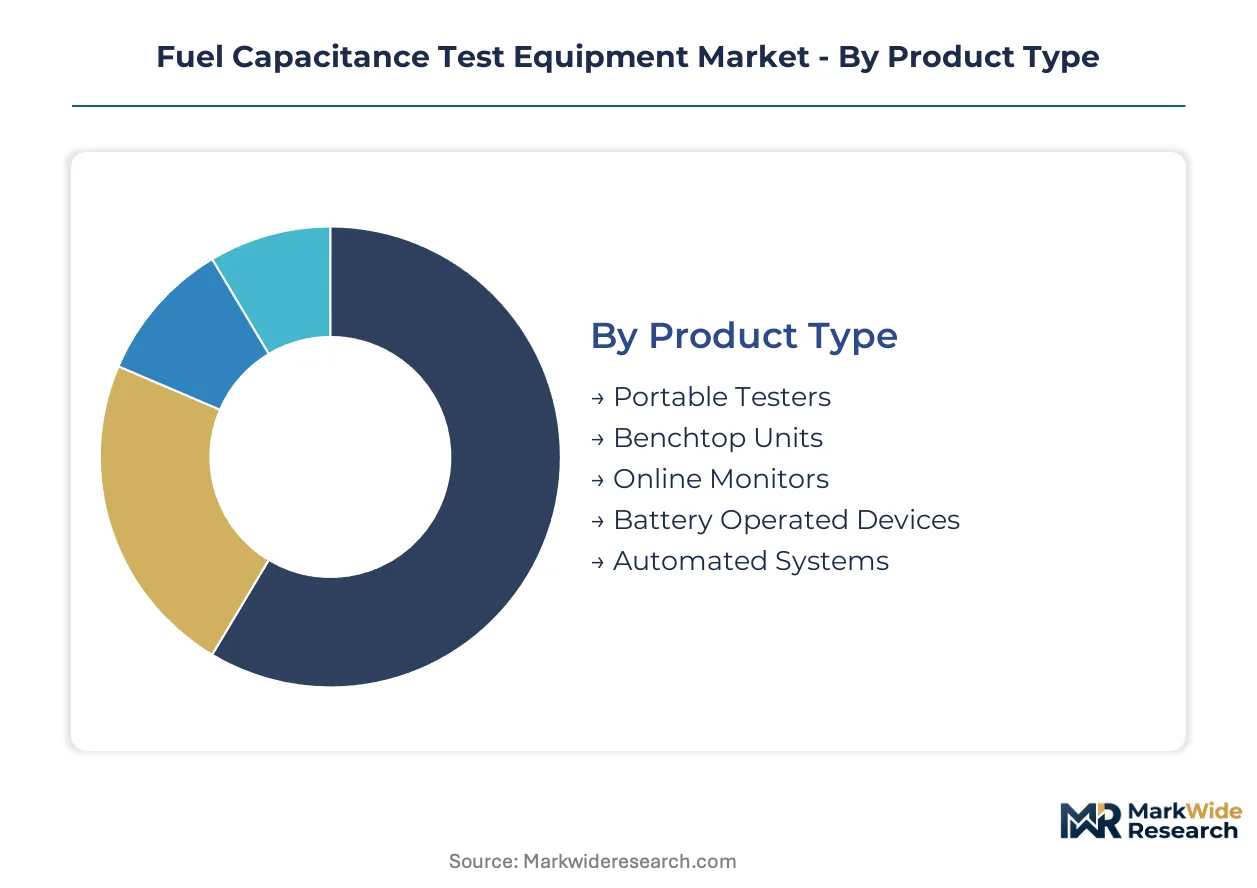
Segmentation in fuel capacitance test equipment reveals how hardware form factors, sensing technologies, and end-use requirements create distinct procurement patterns. Each dimension carries implications for calibration protocols, regulatory compliance pathways, and equipment lifecycle economics.
Product Type:
Integration depth varies sharply: portable and battery-operated units serve standalone field diagnostics, while automated systems embed permanently into process control architectures.
- Portable Testers:Handheld units with integrated reference capacitors and LCD readouts deliver dielectric measurements at 1 kHz to 10 MHz for line maintenance crews. Aircraft servicing firms in the United States and Germany deploy these for FAA-mandated recurrent calibration without removing fuel quantity indicators from aircraft.
- Automated Systems:Rack-mounted configurations with programmable logic controllers interface directly with refinery distributed control systems, enabling continuous dielectric monitoring of fuel blending operations. These systems capture expanding procurement budgets as European refineries integrate sustainable aviation fuel certification protocols.
- Benchtop Units:Laboratory-grade precision instruments with temperature-controlled chambers support metrology-grade calibration for MRO certification labs.
- Online Monitors:Permanently installed sensors with real-time data transmission serve pipeline custody transfer verification and storage terminal quality assurance.
- Battery Operated Devices:Compact, intrinsically safe designs enable hazardous area inspections in tank farms and marine bunkering operations where mains power is unavailable.
Portable testers lead volumes today; automated systems are gaining share fastest.
Technology:
Cost tier differentiation separates mature capacitive architectures from emerging spectroscopic methods requiring specialized signal processing hardware.
- Capacitive Sensing:Parallel-plate electrode configurations with temperature compensation circuits dominate aerospace applications due to established FAA and EASA certification pathways. The technology anchors procurement for aircraft fuel quantity indication system verification where regulatory precedent reduces certification risk.
- Impedance Spectroscopy:Broadband frequency sweep capabilities from 1 Hz to 10 MHz capture complex permittivity signatures across variable ethanol and fatty acid methyl ester blends. Biofuel producers in Germany and the Netherlands adopt these systems to characterize dielectric shifts in sustainable aviation fuel formulations.
- Ultrasonic Measurement:Time-of-flight acoustic sensors provide non-contact level verification in petroleum storage tanks, complementing capacitive methods in hybrid instrumentation packages.
- Laser-Based Detection:Optical interferometry techniques measure fuel refractive index as a proxy for dielectric properties in high-purity hydrocarbon certification.
- RF Analysis:Vector network analyzer architectures extend into fuel system diagnostics, with Teledyne Technologies and Keysight competing on automated narrow-body aircraft integration.
Capacitive sensing commands the largest installed base; impedance spectroscopy shows the steepest expansion trajectory.
Application:
Customer type concentration drives specification divergence: aerospace mandates precision traceability chains, while refinery applications prioritize throughput and chemical compatibility.
- Aerospace Fuel Systems:Fuel quantity indication system calibration for commercial and military aircraft demands documented uncertainty budgets and ISO 17025-accredited procedures. EASA CS-25 certification requirements for large aeroplanes compel European MRO networks to maintain standardized test rig inventories.
- Petroleum Processing:Crude distillation and catalytic cracking units require dielectric monitoring for water-in-oil detection and product cutpoint verification. Refining companies in the United States and China deploy inline capacitance sensors for continuous process control.
- Biofuel Production:Variable feedstock compositions in renewable diesel and sustainable aviation fuel manufacturing necessitate adaptive calibration curves for dielectric property measurement.
- Marine Fuel Monitoring:Bunker fuel quality verification for IMO 2020 sulfur compliance drives portable tester procurement among shipbuilding units and vessel operators.
- Refinery Maintenance:Turnaround inspection protocols for storage tanks and process vessels employ battery-operated devices for confined space entry safety.
Petroleum processing anchors current procurement volumes; biofuel production is climbing the fastest.
End User:
Geography concentration aligns end user type with regional industrial structure: aircraft servicing firms cluster near major airline hubs, while petrochemical plants locate near feedstock and port infrastructure.
- Aircraft Servicing Firms:MRO providers with FAA-approved repair station status and EASA Part-145 certification dominate test equipment procurement for fleet maintenance contracts. Consolidation among regional providers in the United States is compressing supplier relationships toward bundled calibration service agreements.
- Refining Companies:Integrated oil majors and independent refiners in the United States, Germany, and China drive demand for online monitors and automated systems as processing capacity expands.
- Fuel Additive Manufacturers:Specialty chemical producers require benchtop precision for quality control of conductivity improvers and biocide formulations.
- Shipbuilding Units:Korean and Chinese shipyards incorporate marine fuel monitoring systems into newbuild specifications for emission compliance verification.
- Petrochemical Plants:Olefins and aromatics producers employ capacitance testing for feedstock characterization and product specification adherence.
Aircraft servicing firms represent the largest addressable base; refining companies are expanding procurement most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement volumes exceed German demand, yet Chinese refinery capacity expansion is accelerating equipment orders faster than either mature market. Regulatory divergence between FAA and EASA calibration mandates is fragmenting supplier certification requirements across North Atlantic maintenance networks.
United States
Aircraft servicing firms in Dallas-Fort Worth and Atlanta are consolidating MRO contracts with tier-one airlines, forcing test equipment standardization across multi-station operations. FAA airworthiness directives mandate recurrent calibration intervals that compel inventory expansion beyond organic fleet growth. Oklahoma City's aviation maintenance cluster is absorbing displaced technicians from regional carrier bankruptcies, expanding certified labor pools for field calibration services.
Germany
EASA CS-25 certification standards for large aeroplanes are tightening test rig specifications across European maintenance networks, compelling equipment replacement cycles. The EU Green Deal's sustainable aviation fuel blending targets are creating dielectric property recalibration requirements that extend into new fuel certification protocols. Hamburg's aircraft servicing corridor is licensing additional Part-145 facilities to capture narrow-body fleet maintenance diverted from saturated Mediterranean MRO capacity.
China
State-owned refiners in Shandong and Guangdong are expanding catalytic cracking capacity with inline capacitance monitoring for continuous process control. The country's civil aviation regulator is licensing new maintenance facilities at regional airports in Chengdu and Xiamen, creating greenfield procurement for test equipment vendors. Yangtze River Delta petrochemical clusters are adopting automated dielectric analysis systems for custody transfer verification in expanded storage terminal networks.
India
The Directorate General of Civil Aviation is licensing new MRO facilities at Bangalore and Hyderabad regional airports, creating first-mover advantage for calibration service partnerships. Narrow-body fleet expansion by low-cost carriers is outstripping existing maintenance capacity, driving procurement for new test equipment inventories. Gujarat's specialty chemicals corridor is absorbing impedance spectroscopy systems for renewable diesel quality verification as domestic biofuel mandates tighten.
United Kingdom
London Heathrow and Gatwick maintenance bases are consolidating supplier relationships to simplify EASA audit compliance across European route networks. The CAA's alignment with post-Brexit airworthiness standards is preserving CS-25 equipment certification pathways for domestic MRO providers. Midlands aerospace manufacturing clusters are integrating test equipment production into existing precision instrumentation supply chains serving both commercial and defense aviation platforms.
Fuel Capacitance Test Equipment Market Competitive Landscape
United States producers anchor one tier; German and Japanese component specialists hold critical positions in precision reference subsystems. Market structure tilts toward consolidated procurement relationships at the aircraft servicing firm level, with fragmented equipment manufacturing below. Three archetypes dominate: FAA-approved repair station networks, proprietary sensing architecture developers, and RF analysis capability extenders. Competitive moves concentrate on bundled calibration service agreements and modular sub-assembly standardization.
Within the integrated service tier, Barfield Inc. and Teledyne Technologies exemplify divergent positioning strategies. Barfield occupies a position tied to North American aftermarket service density, while Teledyne anchors military-commercial cross-certification pathways. Keysight sits within the instrumentation extension archetype, translating RF domain expertise into automated diagnostics. MERATRONIK S.A. represents European specialist fabrication, with Shenzhen Times HongYuan Technology Co., Ltd. exemplifying Asia-Pacific manufacturing scale.
| Leading Market Players |
|---|
| MERATRONIK S.A. |
| Barfield Inc. |
| Ultra |
| Gull Airborne Instruments |
| Edmodo |
| Shenzhen Times HongYuan Technology Co., Ltd |
| Keysight |
| Fluke |
| Teledyne Technologies |
| Others |
Supply & Pricing Matrix
Metrology technician clusters in Oklahoma City and Hamburg anchor labor-cost differentials that widen pricing-tier spreads between ISO 17025-accredited systems and uncertified portable units. FAA and EASA calibration mandates compress this spread by forcing equipment upgrades regardless of labor arbitrage opportunities.
Pricing Analysis
Capacity additions in China are reshaping price floors for automated refinery systems as domestic manufacturers scale production of programmable logic controller interfaces. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade certification from refinery process control and field-portable diagnostics. Cost compression in the economy tier is intensifying because impedance spectroscopy substitution threatens traditional capacitance testing relevance. Low-cost carriers in Southeast Asia exhibit highest price sensitivity; military-commercial cross-certified platforms show least.
Supply Chain Analysis
Domestic-content mandates in India's civil aviation sector are reshaping sourcing patterns for MRO calibration partnerships. Precision component supply draws from Japan, Germany, and the United States for high-stability reference capacitors and temperature-compensated oscillators. Palladium and platinum electrode materials expose production to commodity price volatility. Distribution runs through FAA-approved repair station networks and EASA Part-145 certified facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
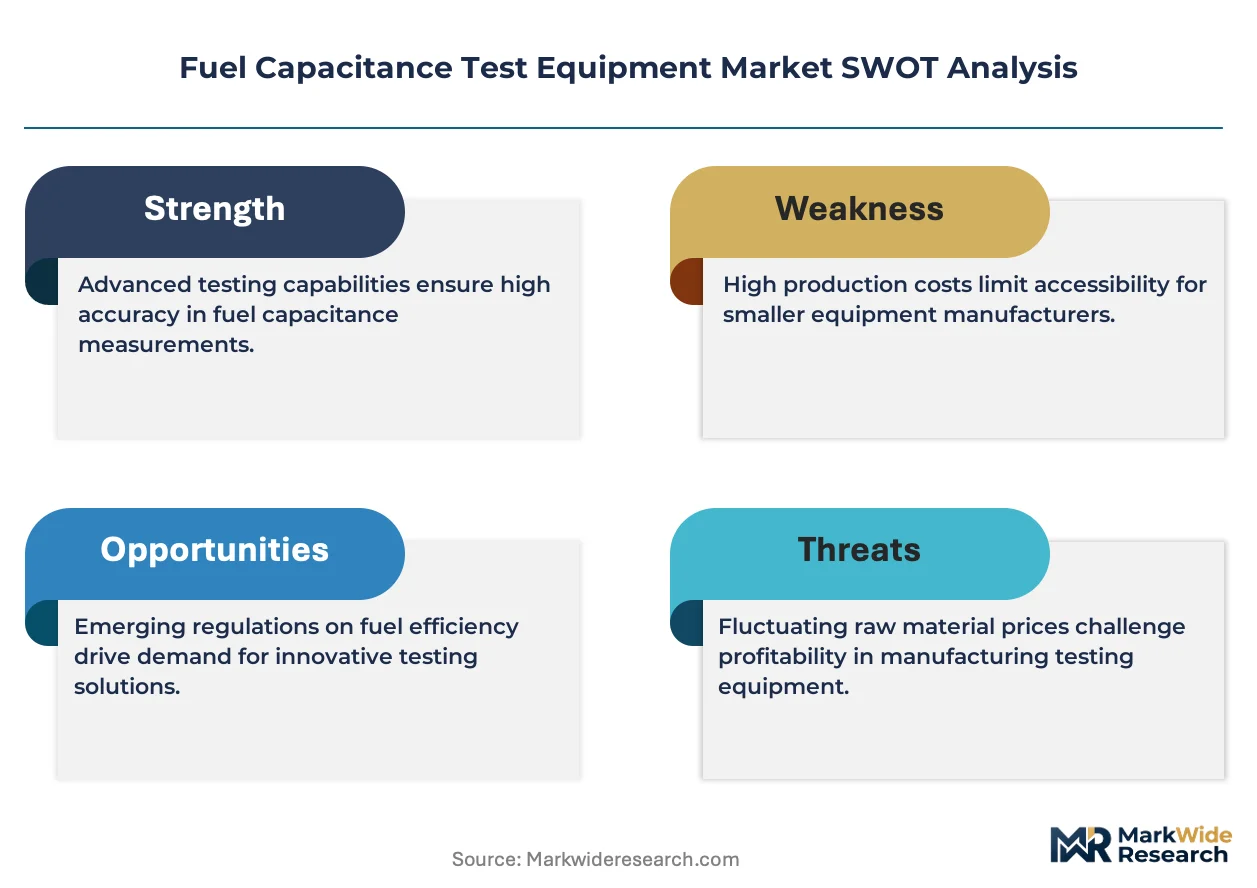
This market functions as a regulatory compounder where EASA's expanding airworthiness directive scope for fuel system accuracy verification creates recurrent equipment replacement demand.
For Market Incumbents: Deepen backward integration into Japanese and German specialty component supply to mitigate single-source vulnerability for high-stability reference capacitors. Expand calibration service partnerships in India's greenfield MRO facilities before domestic competitors establish relationships. Impedance spectroscopy substitution in biofuel segments demands R&D investment in multi-frequency modular architectures.
For New Entrants and Emerging Players: Begin with automated refinery integration for continuous process control where aerospace-grade precision transfers to hydrocarbon quality assurance. India's Directorate General of Civil Aviation licensing wave offers the most penetrable geography. Position through calibration-as-a-service rather than equipment-only sales to bypass incumbent bundled relationships.
For Investors and Strategic Acquirers: Aircraft servicing firms with FAA-EASA dual certification are the most active acquirer in this space, consolidating regional MRO providers to secure long-term airline contracts. Five-to-ten year viability hinges on sustainable aviation fuel dielectric property standardization. Watch for NATO standardization initiative alignment between military and commercial protocols as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Sub-Assembly Standardization | Reduces MRO field service inventory burdens across German and United States maintenance networks. |
| Dual Certification Investment | Opens procurement pools to NATO-aligned military-commercial aviation test protocols. |
| SAF Dielectric Protocol Development | Positions equipment for EU Green Deal sustainable aviation fuel blending mandates. |
| Calibration Service Partnership | Captures recurring revenue from FAA-mandated recurrent calibration intervals. |
| Impedance Spectroscopy Integration | Defends biofuel segment relevance against broadband dielectric analysis substitution. |
Research Methodology
Direct dialogue with MRO procurement directors, aviation maintenance technicians, refinery process control engineers, and FAA repair station managers grounded qualitative findings in operational realities. Secondary validation drew from EASA airworthiness directive filings, FAA certification databases, customs trade records for precision instrumentation, and SEC filings from listed test equipment manufacturers. Bottom-up equipment unit economics triangulated against top-down market sizing across product type, technology, and application segments.
Bottom-up modeling tracked portable tester, automated system, benchtop unit, and online monitor deployments by end-user category. Technology segmentation captured capacitive sensing, impedance spectroscopy, ultrasonic measurement, laser-based detection, and RF analysis adoption curves. Geographic clusters modeled United States, Germany, China, India, and United Kingdom procurement patterns against regulatory mandate timelines. CAGRs derived from equipment replacement cycle compression and fleet expansion rates.
Several conditions sit outside the modeled scope, including unannounced regulatory mandate delays, abrupt palladium supply disruptions, and impedance spectroscopy technology leapfrogging. Forecasts reflect documented assumptions about calibration interval enforcement and sustainable aviation fuel blend penetration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Impedance Tester Market
Test and Measurement
Chiplet-Based System Thermal Cycling and Interconnect Fatigue Test Systems Market
Test and Measurement
Circuit Breaker Test Devices Market
Test and Measurement
Photostability Chamber Market
Test and Measurement
Battery Testing Market
Test and Measurement
Ultrasonic Flaw Detector Market
Test and Measurement
Insulation Testing Instrument Market
Test and Measurement
Automated Optical Inspection (AOI) System Market
Test and Measurement
AI Inference Hardware Performance Benchmarking Test Systems Market
Test and Measurement
Signal Generator Market
Test and Measurement
Gauss Meter Market
Test and Measurement
Handheld Digital Multimeter Market
Test and Measurement
Over-The-Air (OTA) Testing Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
In-Circuit Test Market
Test and Measurement
EMC Shielding and Test Equipment Market