
 Leak Testing Market | 2026-2036
Leak Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Leak Testing Market Foresight
A widening capability gap between capital-heavy spectrometer specialists and modular pneumatic equipment vendors is unwinding traditional competitive boundaries in leak testing. INFICON sustains technology leadership through captive helium detection intellectual property and vacuum instrumentation integration. ATEQ Corporation leverages high-volume automotive assembly line deployments across European and North American manufacturing plants. Uson anchors its position in medical device validation with FDA-compliant trace gas systems for catheter and pacemaker seal verification.
Leak testing encompasses methods for detecting and quantifying unintended fluid or gas escape from sealed components, systems, or packaging, employing pressure differential measurement, tracer gas detection, or acoustic emission analysis to identify defects as small as nanometers in equivalent channel diameter. The primary industrial purpose centers on ensuring product safety, environmental compliance, and functional reliability across sealed systems in critical-use environments. Helium leak testing commands premium positioning due to sensitivity requirements in aerospace propulsion and semiconductor fabrication, while pressure decay methods dominate automotive coolant and fuel system validation where throughput economics favor simpler pneumatic architectures. Mass flow leak testing is gaining share in electronics enclosure verification as IP67-rated smartphone and wearable production scales.
FDA 21 CFR Part 820 quality system regulations mandate validated leak test protocols for Class II and III medical devices, directly shaping instrument qualification requirements and software documentation burdens for vendors serving pharmaceutical packaging. EPA Clean Air Act leak detection and repair standards for volatile organic compound emissions drive adoption of optical gas imaging and ultrasonic methods in chemical processing and refining operations. REACH restrictions on helium supply chain concentration are prompting industrial users to evaluate hydrogen tracer alternatives and closed-loop gas recovery systems. Stakeholders must weigh capital commitment to multi-tracer-capable platforms against single-method equipment obsolescence risk as regulatory thresholds tighten across jurisdictions.
Market Dynamics
Helium supply chain concentration under REACH restrictions is forcing industrial users toward alternative tracer gases and closed-loop recovery architectures, fundamentally restructuring equipment procurement criteria across automotive and medical device validation workflows.
Growth Catalysts
- FDA 21 CFR Part 820 validation mandates:Class II and III medical device manufacturers must implement documented leak test protocols, driving helium mass spectrometry system upgrades for catheter and implantable device seal verification.
- Automotive electrification:Battery pack thermal management systems and fuel cell hydrogen circuits require sub-micron leak detection sensitivity, expanding addressable equipment demand beyond traditional combustion engine applications.
- IP67-rated electronics production scaling:Smartphone and wearable manufacturers in South Korea and China are integrating mass flow leak testing into final assembly lines to meet ingress protection certification requirements.
Market Restraints
- Helium price volatility:REACH concentration limits on natural gas-derived helium supply have compressed margins for spectrometer-dependent operations, particularly affecting aerospace propulsion testing facilities.
- Capital intensity of multi-tracer platforms:Equipment capable of switching between helium, hydrogen, and refrigerant tracer gases requires 40-60% higher upfront investment than single-method pneumatic systems, limiting mid-tier manufacturer participation.
- Technical sensitivity limitations:Pressure decay methods cannot reliably detect defects below 10⁻³ mbar·l/s, excluding their use in semiconductor fabrication and pharmaceutical sterile barrier applications.
Strategic Opportunities
- India pharmaceutical packaging expansion:CDSCO alignment with FDA quality standards is creating demand for validated leak detection systems in injectable drug primary container manufacturing.
- Hydrogen tracer gas convergence:Forming gas (5% hydrogen, 95% nitrogen) detection technology is achieving sensitivity parity with helium at 15-20% lower operating cost, opening retrofit markets in automotive assembly plants.
- Outcome-based equipment leasing:German automotive OEMs are piloting performance-contracted leak testing service models that shift capital burden to equipment vendors while guaranteeing throughput rates.
Industry Challenges
- Vacuum instrumentation technician scarcity:Mass spectrometry maintenance and calibration requires specialized expertise in electron multiplier operation and ion source conditioning, with training pipelines failing to match equipment deployment rates.
- FDA software documentation burdens:21 CFR Part 820 instrument qualification protocols demand extensive validation documentation for test algorithm modifications, extending equipment commissioning timelines by 8-14 weeks.
- Legacy pneumatic system integration:Automotive Tier-1 suppliers face friction retrofitting helium recovery systems into existing coolant circuit test stations originally designed for open-loop nitrogen purge architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leak Testing Market |
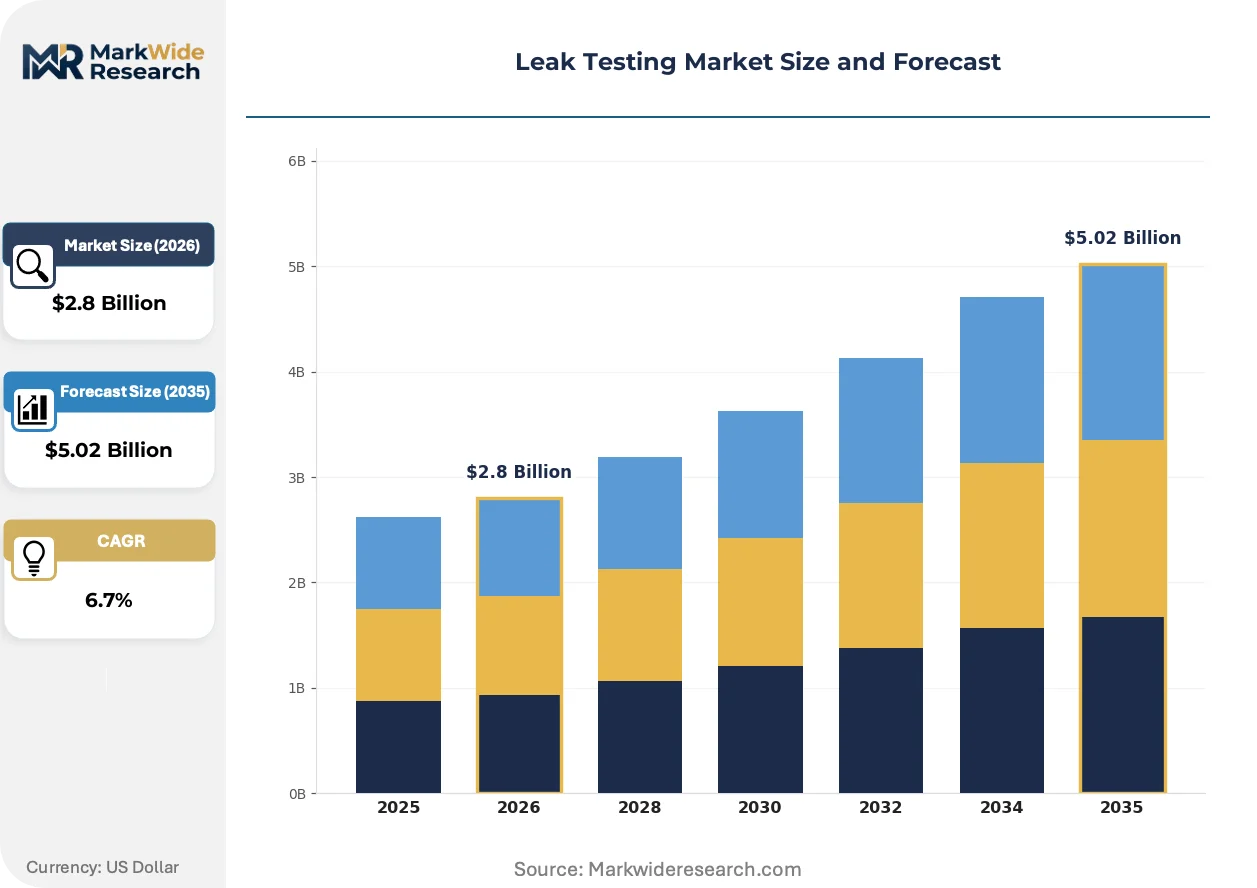
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bubble Testing, Pressure Decay Testing, Helium Leak Testing, Mass Flow Leak Testing End User: Aerospace, Automotive, Electronics, Medical Devices Technology: Ultrasonic, Optical, Vacuum, Pneumatic Application: Gas Leak Detection, Liquid Leak Detection, Quality Control, Research & Development |
| Companies Covered | ATEQ Corporation, INFICON, Vacuum Instruments Corporation, CETA TESTSYSTEME, Uson, Pfeiffer Vacuum, TASI Group, LACO Technologies, Drägerwerk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leak Testing Market Shifts & Advancements
Tracer gas technology diversification and regulatory protocol harmonization are compressing traditional equipment category boundaries while elevating software and service components in vendor value capture.
Optical gas imaging is decomposing conventional sniffer probe methods in chemical processing leak detection. Refinery operators under EPA Clean Air Act LDAR standards are deploying handheld thermal cameras for volatile organic compound visualization, achieving 10x faster survey rates than traditional soap bubble or electronic sniffing approaches. This compression is enabling third-party environmental compliance contractors to displace in-house maintenance teams for fugitive emission monitoring contracts.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant tracer gas substitution in HVAC component testing. Equipment manufacturers must validate heat exchanger and compressor seal integrity using hydrofluorocarbon alternatives or natural refrigerants with modified detection thresholds, forcing recalibration of existing mass spectrometer sensitivity specifications. German KBA automotive type-approval requirements are tightening concurrently, creating dual compliance pressure for climate control system suppliers.
After-sales service unbundling is fragmenting traditional equipment vendor relationships. Japanese automotive manufacturers are separating hardware procurement from calibration and maintenance contracts, awarding multi-year service agreements to specialized metrology firms rather than original equipment suppliers. This disintermediation is most visible in Toyota and Honda assembly plant networks, where third-party ISO/IEC 17025 accredited laboratories now manage trace gas system verification cycles.
Leak Testing Market Segmentation
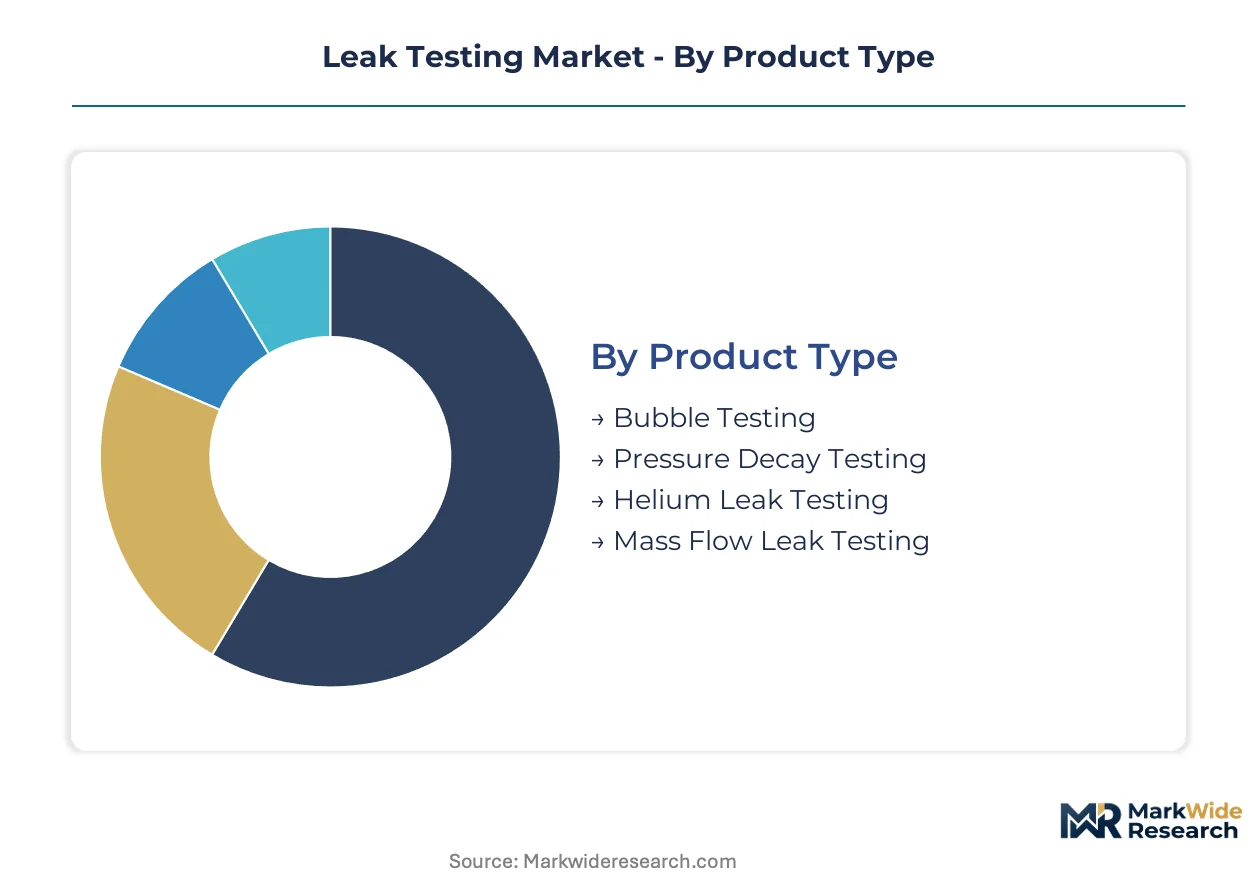
Leak testing equipment procurement channels diverge sharply by sensitivity requirement and validation burden. High-complexity spectrometer systems flow through specialized distributors with metrology certification capabilities, while pneumatic instruments reach volume buyers through industrial automation integrators.
Product Type:
Bubble testing and pressure decay systems reach mid-tier manufacturers through regional equipment distributors, whereas helium mass spectrometry and mass flow platforms require direct vendor engagement for installation qualification.
- Bubble Testing:Submersion-based visual detection for coarse leaks above 10⁻³ mbar·l/s in plumbing fixtures and consumer appliance manufacturing. Demand concentrates in Southeast Asian contract manufacturers serving North American retail brands, constrained by manual inspection throughput limitations.
- Pressure Decay Testing:Differential pressure measurement across sealed cavities for automotive coolant circuits and HVAC compressor validation. German automotive OEMs in Stuttgart and Wolfsburg drive procurement through Tier-1 supplier mandates, though sensitivity floors exclude semiconductor applications.
- Helium Leak Testing:Mass spectrometry detection achieving 10⁻⁹ mbar·l/s sensitivity for aerospace propulsion and pharmaceutical sterile barrier verification.
- Mass Flow Leak Testing:Direct flow measurement for IP67-rated electronics enclosures in South Korean smartphone foundries.
By volume, pressure decay testing leads. By growth pace, mass flow leak testing is expanding most quickly.
End User:
Cost tiers stratify sharply across end-use verticals, with medical device and aerospace buyers absorbing 3-5x equipment premiums versus automotive procurement.
- Aerospace:Propulsion system and fuel tank validation requiring 10⁻⁹ mbar·l/s detection thresholds for FAA-certified airworthiness. NASA contractors and SpaceX suppliers in California and Texas anchor demand, with helium recovery systems mandatory for cost containment.
- Automotive:Battery thermal management and fuel cell hydrogen circuit testing for electrification transitions. German KBA type-approval requirements and NHTSA safety mandates in the US drive parallel compliance investments.
- Electronics:Smartphone and wearable ingress protection verification at IP67 and IP68 ratings.
- Medical Devices:Catheter, pacemaker, and drug delivery system seal validation under FDA 21 CFR Part 820.
Automotive generates the highest unit volumes. Medical devices command the steepest pricing premiums.
Technology:
Technology maturity curves separate established pneumatic methods from emerging optical and ultrasonic alternatives still seeking standardization.
- Ultrasonic:Acoustic emission detection for pressurized gas leaks in chemical processing and refinery operations. EPA Clean Air Act LDAR compliance in Texas and Louisiana petrochemical corridors sustains demand, though ambient noise interference limits indoor deployment.
- Optical:Thermal camera visualization of volatile organic compound plumes for fugitive emission monitoring. European refineries under EU Green Deal methane reduction targets pilot handheld systems, achieving 10x faster survey rates than sniffer probes.
- Vacuum:Mass spectrometry and residual gas analysis for semiconductor fabrication and aerospace.
- Pneumatic:Pressure differential and mass flow methods for high-throughput automotive and electronics assembly.
Pneumatic technologies dominate installed base. Optical methods are climbing the fastest on environmental compliance drivers.
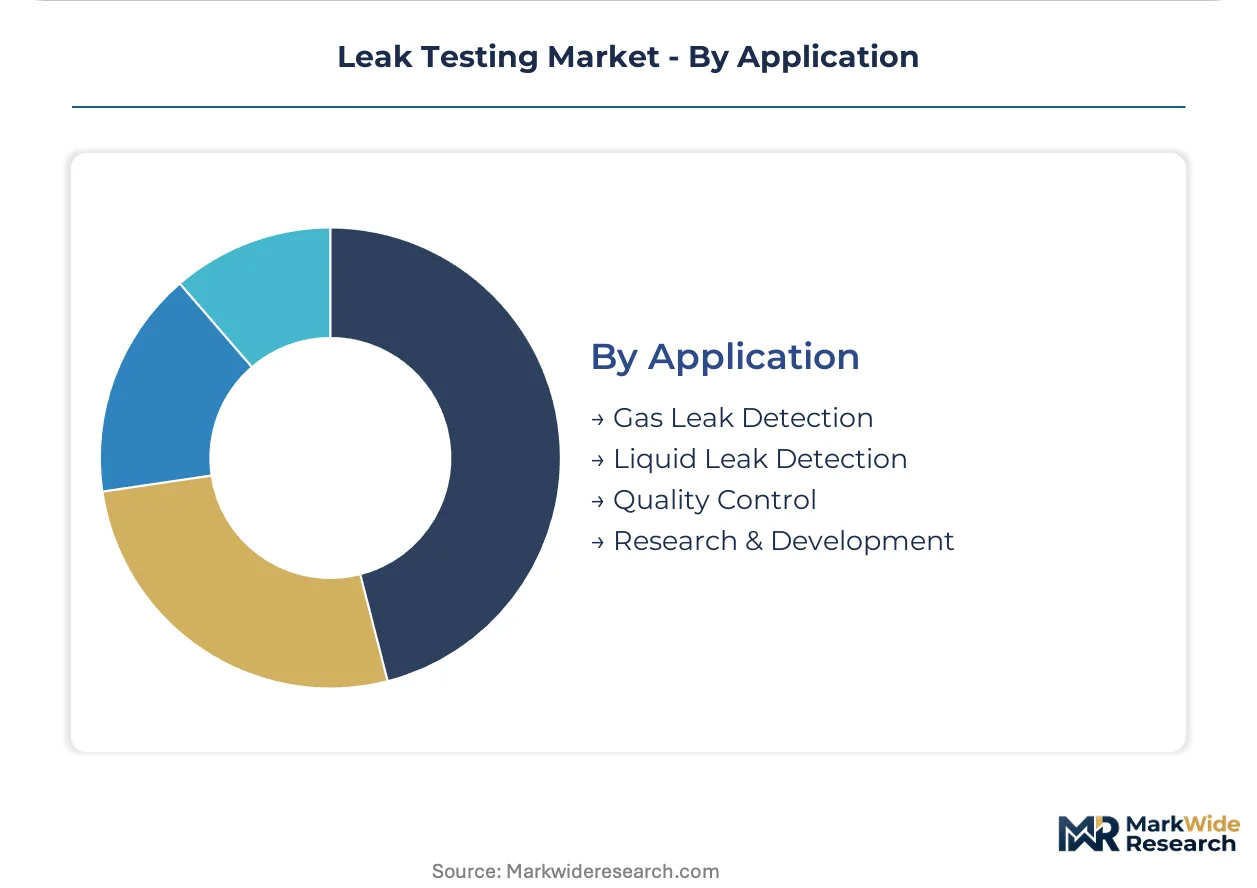
Application:
Application workflows separate production-line validation from laboratory R&D, with quality control commanding 70% of equipment spend.
- Gas Leak Detection:Tracer gas and pressure-based methods for refrigerant, fuel, and process gas containment. EU F-Gas Regulation phase-down schedules in Germany and France force hydrofluorocarbon alternative validation, complicating detection threshold calibration.
- Liquid Leak Detection:Pressure decay and bubble testing for hydraulic systems and pharmaceutical liquid packaging. Indian pharmaceutical exporters aligning with CDSCO-FDA harmonization drive system upgrades in Mumbai and Hyderabad manufacturing clusters.
- Quality Control:In-line production testing for 100% lot verification in automotive and electronics.
- Research & Development:Method development and failure analysis for new product qualification.
Quality control absorbs the largest equipment budgets. Research and development shows the steepest expansion trajectory on materials science innovation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany absorb 40% equipment premiums for helium spectrometry without volume hesitation, while Indian pharmaceutical exporters negotiate aggressively on pneumatic system pricing despite regulatory upgrade mandates. This elasticity divergence shapes vendor go-to-market strategies across geographies.
United States
FDA 21 CFR Part 820 enforcement tightens validation documentation for Class III implantable devices, pushing catheter and pacemaker manufacturers toward mass spectrometry upgrades. NASA contractors in Texas and SpaceX suppliers in California anchor aerospace propulsion testing demand with mandatory helium recovery systems for cost containment.
Germany
KBA automotive type-approval requirements and concurrent EU F-Gas Regulation phase-down schedules create dual compliance pressure for climate control system suppliers. Stuttgart and Wolfsburg precision engineering clusters drive procurement of advanced pneumatic and vacuum testing systems through Tier-1 supplier mandates.
China
MIIT battery safety standards for electric vehicle thermal management systems mandate sub-micron leak detection sensitivity beyond traditional combustion engine specifications. Yangtze River Delta smartphone foundries integrate mass flow testing for IP67-rated wearable production at scale.
India
CDSCO alignment with FDA quality standards creates demand for validated leak detection in injectable drug primary container manufacturing. Mumbai and Hyderabad pharmaceutical exporters upgrade bubble and pressure decay systems to meet export certification requirements despite capital constraints.
South Korea
MFDS medical device registration harmonization with FDA standards elevates validation protocol requirements for domestic manufacturers. Seoul Capital Area electronics assembly plants deploy mass flow leak testing for IP67-rated smartphone final certification at production line speeds.
Leak Testing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with spectrometer specialists commanding 3-5x pricing premiums over pneumatic equipment vendors. The vendor base separates into three strategic tiers: captive helium detection IP holders, high-volume automotive assembly line deployers, and FDA-compliant medical validation specialists. Dominant competitive moves include strategic partnerships for tracer gas recovery system integration and geographic expansion into pharmaceutical packaging growth markets.
Among European precision instrumentation developers, INFICON and Pfeiffer Vacuum exemplify technology leadership through vacuum instrumentation integration and captive detection intellectual property. ATEQ Corporation occupies a position as a scale-driven deployer across automotive assembly networks, while Uson anchors the medical device validation tier with trace gas system specialization.
| Leading Market Players |
|---|
| ATEQ Corporation |
| INFICON |
| Vacuum Instruments Corporation |
| CETA TESTSYSTEME |
| Uson |
| Pfeiffer Vacuum |
| TASI Group |
| LACO Technologies |
| Drägerwerk |
| Others |
Supply & Pricing Matrix
Capacity utilization at German precision engineering clusters shapes both supply concentration and price floors for helium spectrometry systems, compressing margins for mid-tier pneumatic vendors while sustaining premiums for captive-IP holders. REACH restrictions on natural gas-derived helium feedstock have forced equipment buyers toward closed-loop recovery architectures, embedding service contracts deeper into lifetime value calculations and elevating after-sales revenue as a pricing anchor.
Pricing Analysis
After-sales service contracts and calibration agreements now generate 40-60% of lifetime equipment value, shifting vendor economics from transactional hardware sales toward recurring revenue models. Three-tier pricing structure across premium helium spectrometry, standard pneumatic systems, and economy bubble testing levels separates FDA-validated medical device platforms from automotive assembly line equipment. Pricing pressure stems from REACH-driven helium scarcity forcing buyers to evaluate hydrogen tracer alternatives, eroding spectrometer pricing power in automotive applications. Automotive Tier-1 suppliers exhibit highest price sensitivity due to capital constraints on multi-tracer platform upgrades, while medical device manufacturers absorb premiums for FDA 21 CFR Part 820 compliance.
Supply Chain Analysis
Strategic stockpiling of helium reserves characterizes aerospace and semiconductor fabrication buyers, contrasting with just-in-time component sourcing for pneumatic instrumentation. Manufacturing concentration centers on Germany, Switzerland, and Japan for vacuum instrumentation and mass spectrometry subsystems, with South Korea and China dominating mass flow sensor fabrication. Critical component dependencies include electron multipliers, ion sources, and high-purity helium gas supplies. Single-source vulnerability in helium feedstock from natural gas processing facilities creates supply chain risk. Distribution runs through specialized metrology distributors for spectrometer systems and industrial automation integrators for pneumatic equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German automotive OEMs and US medical device manufacturers, forcing equipment vendors toward performance-contracted service models and outcome-based leasing structures that shift capital burden upstream.
For Market Incumbents: Secure captive helium detection intellectual property through patent portfolio expansion and vacuum instrumentation integration, while building backward integration into tracer gas recovery system manufacturing to defend against hydrogen tracer substitution. Lock in multi-year calibration and maintenance contracts with Japanese automotive manufacturers before third-party ISO/IEC 17025 laboratories capture service revenue disintermediation. Capacity addition in Indian pharmaceutical packaging clusters offers geographic hedge against European REACH compliance cost compression. For New Entrants and Emerging Players: After-sales service unbundling by incumbent vendors creates white-space opportunity for specialized metrology firms to capture multi-year verification contracts in Toyota and Honda assembly networks. Target Indian pharmaceutical exporters in Mumbai and Hyderabad upgrading from bubble testing to pressure decay systems for CDSCO-FDA harmonization, where capital constraints favor rental or leasing models over spectrometer purchases. Partner with regional equipment distributors lacking metrology certification capabilities to embed calibration services into hardware procurement workflows. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among FDA-compliant medical validation specialists with installed base lock-in from 21 CFR Part 820 documentation burdens. Long-term viability across the analysis window favors vendors with multi-tracer platform architectures capable of helium, hydrogen, and refrigerant gas switching. Acquisition targets should demonstrate captive IP in vacuum instrumentation or established service relationships with aerospace propulsion contractors. Watch for hydrogen tracer sensitivity parity announcements as inflection indicator for spectrometer pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Tracer Gas Recovery System Integration | REACH helium restrictions force closed-loop architectures into automotive validation workflows at German OEMs. |
| Outcome-Based Equipment Leasing | Performance-contracted models shift capital burden to vendors while guaranteeing throughput at Stuttgart assembly plants. |
| Multi-Tracer Platform Development | Helium-hydrogen-refrigerant switching capability insulates against single-gas regulatory obsolescence under EU F-Gas phase-downs. |
| Third-Party Metrology Accreditation | ISO/IEC 17025 certification enables service revenue capture from disintermediated Japanese automotive manufacturer contracts. |
| Pharmaceutical Packaging Geographic Expansion | CDSCO-FDA harmonization in Indian injectable drug manufacturing creates validated system demand in Mumbai clusters. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with vacuum instrumentation technicians, biomedical engineers at medical device manufacturers, automotive Tier-1 procurement leads, and pharmaceutical packaging quality directors; and secondary validation against FDA 21 CFR Part 820 guidance documents, EPA Clean Air Act LDAR enforcement data, EU F-Gas Regulation phase-down schedules, and SEC filings from precision instrumentation vendors. Bottom-up equipment deployment estimates triangulated against top-down end-use industry capital expenditure patterns across automotive, aerospace, medical device, and electronics verticals.
Across the projection horizon, the analytical framework modeled demand segmentation by product type, end-use industry, detection technology, and application workflow, with cross-dimensional analysis of sensitivity requirements versus throughput economics. CAGRs were derived from equipment replacement cycles, regulatory mandate implementation timelines, and electrification-driven validation protocol expansion in battery thermal management and fuel cell hydrogen circuits. Industry-specific forecast inputs included helium price volatility trajectories under REACH restrictions and FDA software documentation burden impacts on commissioning timelines.
Underlying assumptions cover sustained REACH enforcement on helium supply concentration, FDA validation mandate continuity for Class II and III devices, and automotive electrification scaling for battery and fuel cell leak detection protocols, with deviation risk concentrated in hydrogen tracer sensitivity achievement timelines and technician training pipeline expansion rates. Revision becomes warranted when hydrogen detection sensitivity crosses parity thresholds with helium mass spectrometry or when automotive OEMs accelerate outcome-based leasing adoption beyond pilot phases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Stress Test Chamber Market
Test and Measurement
Data Acquisition Equipment Market
Test and Measurement
Electronic Measuring Device Market
Test and Measurement
Noise Dosimeter Market
Test and Measurement
Semiconductor Bond Testing Market
Test and Measurement
Psophometer Market
Test and Measurement
Optical Wafer Inspection Systems Market
Test and Measurement
Compression Testing Machines Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Brightness Meter Market
Test and Measurement
In-Process Composite Layup Monitoring Sensors and Test Equipment Market
Test and Measurement
Fiber Optic Test Equipment (FOTE) Market
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
Shock Testing System Market
Test and Measurement
Global Source Measure Unit Market
Test and Measurement
Ultrasonic Thickness Gauge Market