
 Programmable Logic Device (PLD) Market | 2026-2036
Programmable Logic Device (PLD) Market Size, Share, and Industry Trends Forecast 2026-2036
Programmable Logic Device (PLD) Market Analytics
Buyer concentration among hyperscale data center operators is realigning procurement leverage toward custom silicon alternatives. Intel Corporation leverages its foundry integration to bundle programmable logic with processor platforms. Lattice Semiconductor Corporation specializes in low-power FPGA architectures for edge deployments. Advanced Micro Devices Inc. competes across high-performance adaptive computing portfolios following its Xilinx integration.
Programmable Logic Devices are semiconductor integrated circuits with reconfigurable logic blocks and programmable interconnect matrices, typically fabricated on CMOS processes with SRAM or flash-based configuration cells, enabling post-manufacturing functional reprogramming for digital signal processing and hardware acceleration tasks. FPGA architectures occupy the dominant margin pool due to their density scalability in telecommunications infrastructure and data processing workloads. CPLD segments serve control systems applications where deterministic timing and instant-on operation outweigh logic capacity requirements. Mixed-signal technology integration is expanding addressable scope into RF front-end and sensor interface domains previously served by discrete analog components.
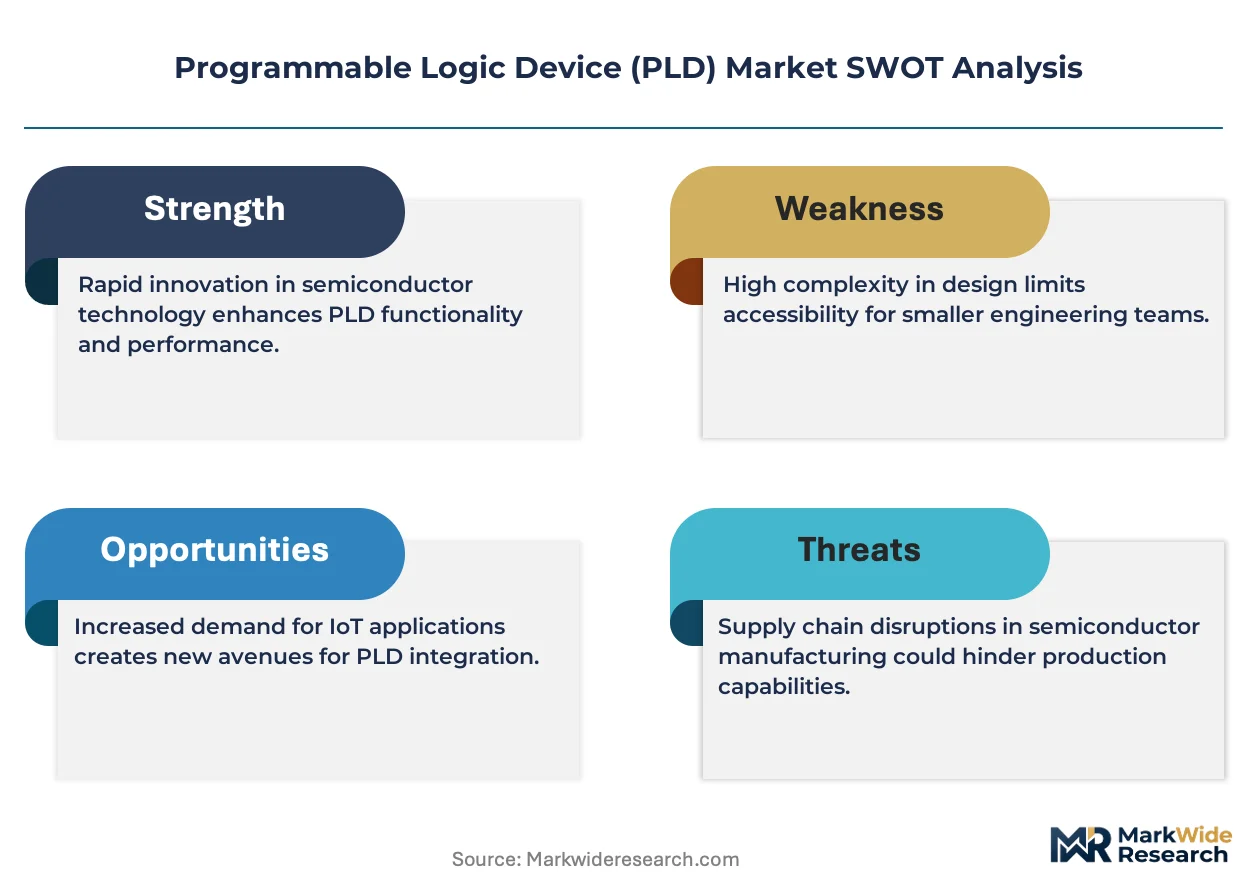
The US Department of Commerce Bureau of Industry and Security administers export classification controls on field-programmable gate arrays above specified logic cell thresholds, restricting shipment destinations and end-user categories. China's MIIT mandates GB standard compliance and domestic certification for programmable logic deployed in critical information infrastructure. The EU REACH regulation and RoHS directive constrain substrate materials and packaging substances across the supply chain. Stakeholders must monitor evolving dual-use technology classifications and foundry geographic diversification requirements to sustain market access and qualification status.
Market Dynamics
Export control classifications on advanced semiconductors are fragmenting programmable logic supply chains, forcing procurement diversification away from concentrated foundry clusters and toward multi-source qualification strategies.
Growth Catalysts
- Telecommunications infrastructure:5G base station deployments and Open RAN architectures consume high-density FPGA arrays for signal processing and hardware acceleration.
- EU AI Act:Compliance mandates for high-risk AI systems drive certified programmable logic adoption in safety-critical automation and medical devices.
- SRAM-based configuration:Reprogrammability without power cycling enables dynamic workload optimization in hyperscale data centers.
Market Restraints
- Wafer supply concentration:Leading-edge CMOS capacity at Taiwan-based foundries creates single-point vulnerability for high-density FPGA production.
- Flash memory cost volatility:CPLD configuration cell manufacturing faces input price pressure from competing NAND demand.
- ASIC substitution economics:Volume production thresholds above ten thousand units favor hardwired silicon over programmable alternatives.
Strategic Opportunities
- Edge AI inference:Low-power FPGA deployment in industrial sensors and autonomous systems creates white space below data center scale.
- India PLI scheme:Domestic electronics manufacturing incentives attract programmable logic packaging and testing investment.
- Photonic interconnect convergence:Co-packaged optics with programmable logic enables terabit-scale data movement in next-generation switches.
Industry Challenges
- Hardware description language expertise:RTL design and verification talent scarcity constrains customer implementation velocity.
- Dual-use export licensing:Bureau of Industry and Security classification reviews extend order fulfillment timelines by quarters.
- Legacy system integration:Existing CPLD sockets resist migration to advanced FPGA architectures due to board redesign costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Programmable Logic Device (PLD) Market |
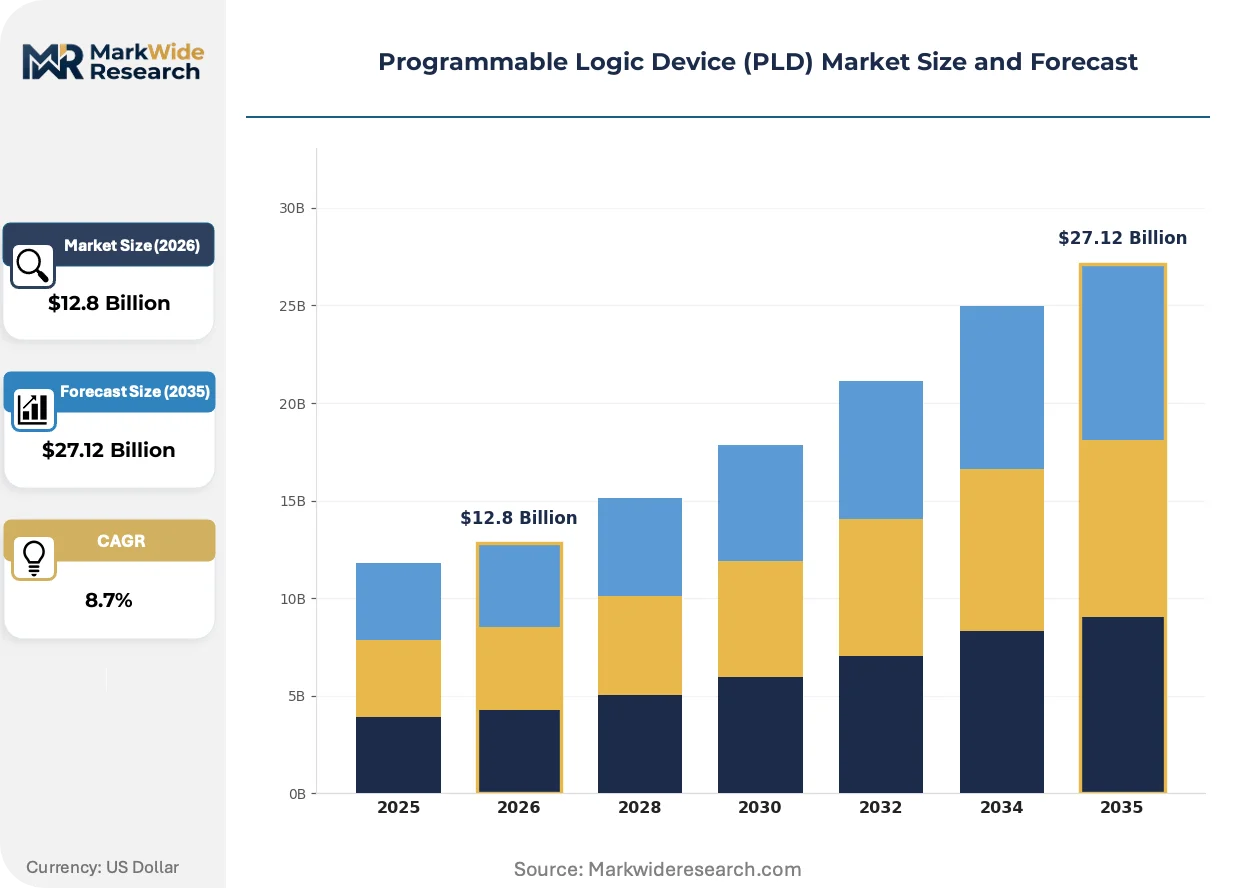
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
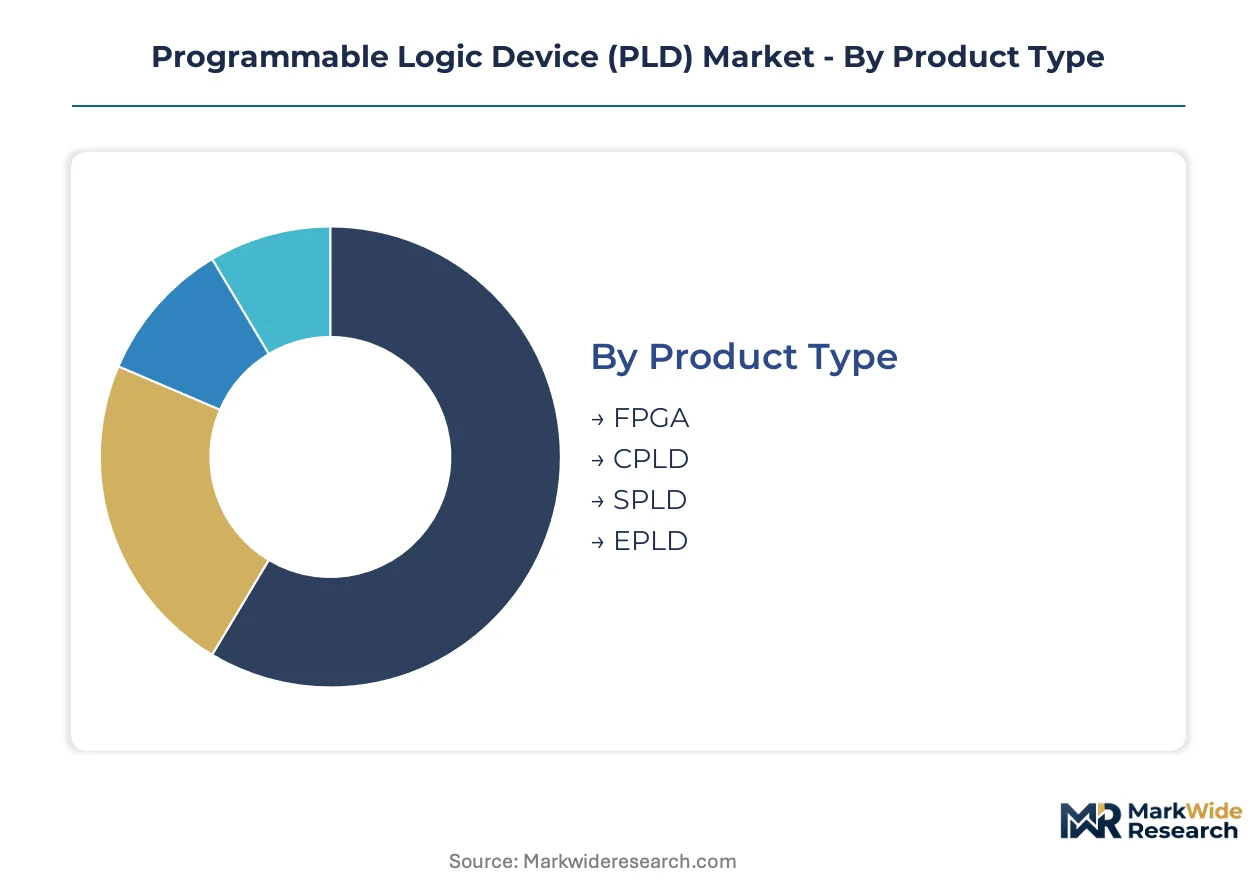
| Segmentation | Product Type: FPGA, CPLD, SPLD, EPLD End User: Aerospace, Consumer Electronics, Automotive, Industrial Automation Technology: Analog, Digital, Mixed-Signal, RF Application: Telecommunications, Data Processing, Control Systems, Others |
| Companies Covered | Intel Corporation, Advanced Micro Devices Inc., Lattice Semiconductor Corporation, Microchip Technology Inc., Xilinx, Inc., Achronix Semiconductor Corporation, QuickLogic Corporation, Efinix, Inc., Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Programmable Logic Device (PLD) Market Evolving Landscape
Adaptive computing architectures are absorbing functions from discrete processors and fixed-function accelerators, compressing system-level bill-of-materials while expanding programmable logic attach rates per socket.
Embedded AI engines within FPGA fabric are absorbing inferencing workloads previously executed on standalone neural processing units. Automotive Tier 1 suppliers are qualifying these devices for driver-assistance perception pipelines. The integration is absorbing margin from the discrete AI accelerator market.
REACH substance restrictions and RoHS substance bans are eliminating lead-based solder and specific flame retardants from substrate materials. European contract manufacturers are requalifying assembly processes. Medical device and industrial control segments face the steepest compliance cost absorption.
Hyperscale operators are consolidating programmable logic procurement through direct foundry relationships, bypassing traditional distribution. Cloud service providers negotiate volume commitments for custom FPGA configurations. This concentration is most visible in Washington State and Northern Virginia data center clusters.
Programmable Logic Device (PLD) Market Segmentation
PLD segmentation reveals divergent upgrade cycles across product architectures and end-use environments. Aerospace programs demand decade-long qualification stability while consumer electronics compress replacement intervals to annual cadences. Understanding these temporal patterns shapes inventory strategy and foundry allocation decisions.
Product Type:
Upgrade cycles stretch from instant-on CPLD sockets to multi-year FPGA reconfiguration roadmaps, creating tiered replacement revenue visibility.
- FPGA:SRAM-based field-programmable gate arrays integrate millions of configurable logic blocks with DSP slices and embedded memory. Telecommunications infrastructure in Taiwan's Hsinchu cluster consumes high-density arrays for 5G baseband processing, driven by Open RAN disaggregation mandates.
- CPLD:Complex programmable logic devices employ flash-based configuration cells for deterministic boot-up without external memory. Industrial control systems across German automotive plants favor CPLD instant-on reliability, constrained by flash memory cost volatility from competing NAND demand.
- SPLD:Simple programmable logic devices address glue logic consolidation in legacy board redesigns.
- EPLD:Erasable programmable logic devices serve niche UV-erase applications in aerospace maintenance depots.
Volume placements concentrate in FPGA; the faster expansion belongs to CPLD as edge AI inference drives low-power socket growth.
End User:
Customer concentration patterns split between long-qualification defense contractors and high-volume consumer electronics OEMs with opposing margin structures.
- Aerospace:Mission-critical avionics systems require DO-254 certified programmable logic with radiation-hardened configurations. Boeing and Lockheed Martin procurement cycles extend across multi-year platform developments, shaped by US Bureau of Industry and Security export licensing timelines.
- Automotive:ISO 26262 functional safety compliance drives FPGA adoption in ADAS perception pipelines. Tier 1 suppliers in Stuttgart and Nagoya qualify adaptive computing platforms, absorbing margin from discrete AI accelerators through embedded inference engines.
- Consumer Electronics:Smartphone and wearable OEMs in Shenzhen specify ultra-low-power programmable logic for sensor hubs.
- Industrial Automation:Factory floor controllers leverage deterministic CPLD timing for safety interlocks and motion control.
Procurement volume clusters in Automotive; the steepest expansion trajectory runs through Aerospace as defense modernization accelerates.
Technology:
Silicon integration depth determines addressable scope, with mixed-signal architectures expanding into RF front-end domains previously served by discrete analog.
- Mixed-Signal:Analog-to-digital converter integration with programmable fabric enables single-chip sensor interfaces. Medical device manufacturers in Switzerland and Minnesota adopt these platforms for portable diagnostic equipment, facing REACH substance restriction compliance costs in European contract manufacturing.
- Digital:Pure CMOS logic arrays dominate high-density signal processing workloads in hyperscale data centers.
- Analog:Programmable analog blocks serve precision measurement applications in test equipment.
- RF:Millimeter-wave configurable front-ends target 5G massive MIMO antenna arrays.
Shipment volumes concentrate in Digital; Mixed-Signal gains share fastest as sensor fusion requirements proliferate.
Application:
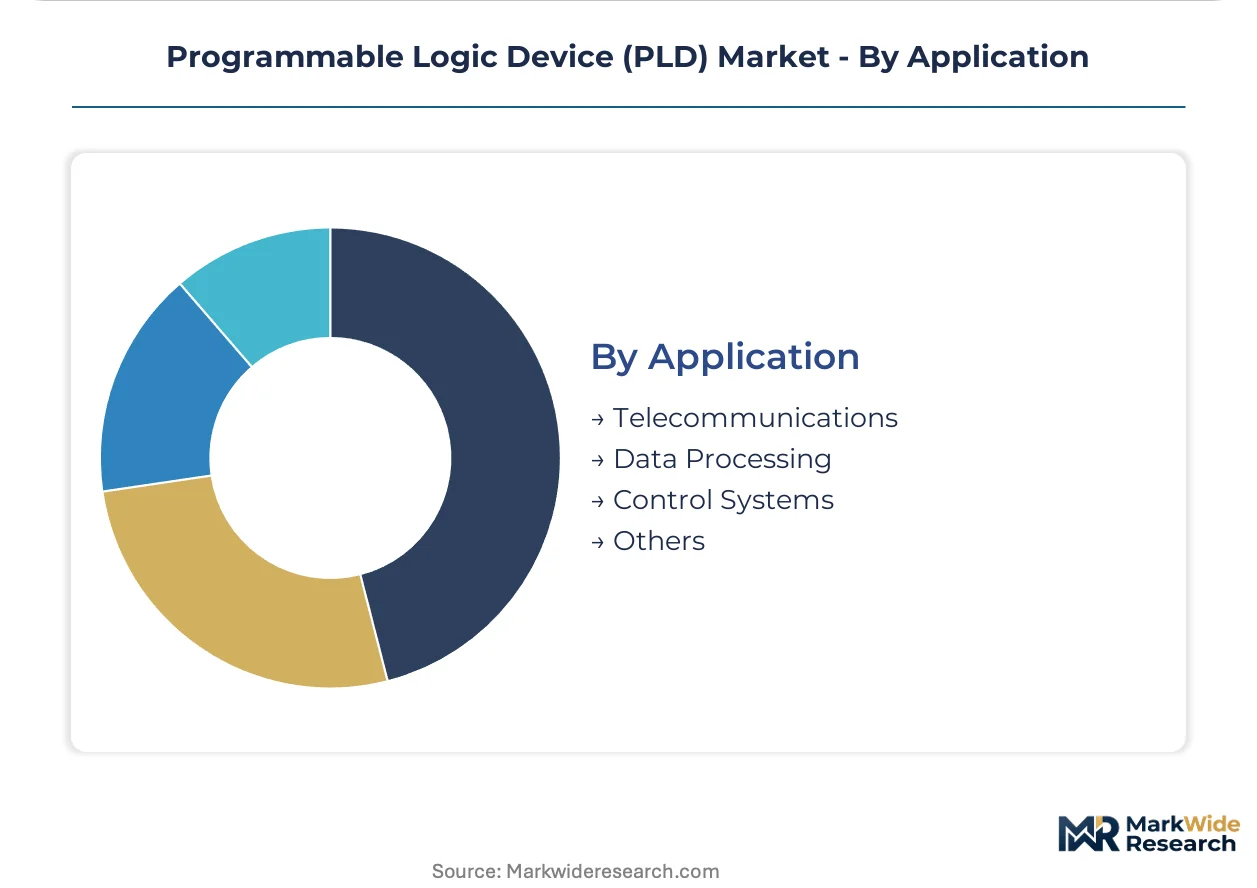
Workload characteristics dictate logic density requirements, with telecommunications infrastructure consuming the highest cell counts per device.
- Telecommunications:Base station digital front-ends and fronthaul switches absorb high-density FPGA arrays for massive MIMO precoding. Open RAN architectures in South Korean and US deployments disaggregate hardware layers, driving programmable logic attach rates per rack.
- Data Processing:Hyperscale operators in Washington State and Northern Virginia negotiate direct foundry relationships for custom FPGA configurations, bypassing traditional distribution channels.
- Control Systems:Deterministic PLCs and safety interlocks favor CPLD instant-on operation over reconfigurability.
- Others:Niche military and scientific computing applications specify radiation-tolerant configurations.
Volume concentrates in Telecommunications; Data Processing climbs fastest as cloud AI training infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center operators in the United States concentrate procurement leverage for high-density FPGA arrays, while Taiwan's foundry ecosystem feeds design houses serving telecommunications infrastructure across multiple continents.
United States
Defense modernization programs at Boeing and Lockheed Martin drive radiation-hardened FPGA demand for mission-critical avionics. The Bureau of Industry and Security administers export classification controls on field-programmable gate arrays above specified logic cell thresholds. Washington State and Northern Virginia data center clusters host cloud service providers negotiating direct foundry relationships for custom configurations.
China
Domestic 5G base station deployments consume high-density programmable logic for massive MIMO precoding and signal processing workloads. MIIT mandates GB standard compliance and domestic certification for programmable logic deployed in critical information infrastructure. Shenzhen smartphone and wearable OEMs specify ultra-low-power programmable logic for sensor hub integration.
Germany
Automotive Tier 1 suppliers in Stuttgart qualify adaptive computing platforms for ISO 26262-compliant ADAS perception pipelines. ECHA REACH regulation and RoHS directive constrain substrate materials and packaging substances across European contract manufacturing. Industrial control systems across German automotive plants favor CPLD instant-on reliability for safety interlocks.
South Korea
Open RAN disaggregation mandates in telecommunications infrastructure drive programmable logic attach rates per rack in 5G deployments. The country's national semiconductor regulator enforces dual-use technology classifications on advanced programmable logic shipments. Seoul Capital Area design houses coordinate with Taiwan foundries for high-density array production.
India
Domestic electronics manufacturing incentives under the PLI scheme attract programmable logic packaging and testing investment from multinational suppliers. BIS certification requirements govern programmable logic deployment in critical information infrastructure. Karnataka and Telangana technology corridors host emerging design services targeting industrial automation applications.
Programmable Logic Device (PLD) Market Competitive Landscape
United States producers anchor one tier; Taiwanese foundry-linked specialists hold manufacturing leverage. The vendor base structures around three tiers: integrated device manufacturers with captive foundry access, fabless design houses dependent on external fabrication, and programmable logic specialists focused on low-power edge architectures. Strategic consolidation through acquisition and direct hyperscale procurement relationships represent the dominant competitive vectors reshaping channel economics.
Within the integrated device manufacturer tier, Intel Corporation and Advanced Micro Devices Inc. exemplify archetypes combining processor platforms with programmable logic portfolios. Lattice Semiconductor Corporation occupies a position representing the low-power FPGA specialist archetype targeting edge deployment environments. These three anchors illustrate the geographic and structural segmentation governing competitive positioning across telecommunications infrastructure, data center acceleration, and industrial control applications.
| Leading Market Players |
|---|
| Intel Corporation |
| Advanced Micro Devices Inc. |
| Lattice Semiconductor Corporation |
| Microchip Technology Inc. |
| Xilinx, Inc. |
| Achronix Semiconductor Corporation |
| QuickLogic Corporation |
| Efinix, Inc. |
| Renesas Electronics Corporation |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between automotive ISO 26262-compliant devices and commodity CPLD sockets manifests in both unit economics and foundry allocation priorities, with safety-critical tiers commanding premium wafer commitments at Taiwan-based fabrication facilities while consumer-grade volumes compete for residual capacity.
Pricing Analysis
Volume-margin splits separate hyperscale data center procurement from industrial control sockets. Three-tier pricing structure across radiation-hardened aerospace, automotive functional safety, and consumer electronics tiers reflects certification burden and qualification timeline differentials. Price differentiation hinges on logic cell density thresholds and foundry node access, with leading-edge CMOS capacity scarcity intensifying cost compression in mid-density segments. Automotive Tier 1 suppliers exhibit lowest price sensitivity due to platform lock-in, while Shenzhen wearable OEMs drive aggressive commoditization in ultra-low-power categories.
Supply Chain Analysis
Workforce availability constraints in Taiwan, South Korea, and Arizona fabrication corridors limit expansion velocity for advanced CMOS processes. Raw material dependencies center on silicon wafers, specialty gases for EUV lithography, and bismaleimide-triazine substrate resins. Single-source vulnerability concentrates in Taiwan's Hsinchu Science Park cluster, where foundry-linked design houses control high-density FPGA output. Distribution runs through direct hyperscale procurement relationships and authorized distribution networks serving fragmented industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Leading-edge CMOS capacity scarcity at Taiwan-based foundries props pricing across high-density FPGA tiers, constraining volume expansion regardless of demand signals.
For Market Incumbents: Deepen backward integration into specialty substrate manufacturing to offset REACH substance restriction compliance costs and secure packaging material supply. Lock in multi-year wafer allocation agreements with foundry partners before capacity expansion lags widen. Defend against ASIC substitution by embedding AI inference engines that absorb discrete accelerator functions. For New Entrants and Emerging Players: Photonic interconnect co-packaging offers entry into data center switch architectures underserved by incumbent programmable logic portfolios. Target India's PLI scheme incentives for packaging and testing investment to bypass foundry capacity constraints. Pursue design services partnerships with Karnataka and Telangana industrial automation corridors as a beachhead before silicon development. For Investors and Strategic Acquirers: Re-rating potential sits with mixed-signal specialists given sensor fusion proliferation in medical and automotive end-uses. Long-term viability favors acquisition targets with radiation-hardened qualification heritage and defense contractor relationships. Watch Bureau of Industry and Security export classification expansion as an inflection signal for geographic demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | Long-term wafer commitments at Taiwan facilities secure high-density FPGA output for telecommunications infrastructure. |
| Photonic Interconnect Integration | Co-packaged optics with programmable logic enables terabit-scale data movement in next-generation switches. |
| Automotive Safety Certification | ISO 26262 qualification opens ADAS perception pipeline sockets previously served by discrete AI accelerators. |
| India PLI Scheme Localization | Domestic packaging and testing investment attracts multinational suppliers seeking geographic diversification. |
| Radiation-Hardened Product Line | DO-254 certified devices capture defense modernization procurement at Boeing and Lockheed Martin. |
Research Methodology
Independent corroboration across semiconductor foundry executives, aerospace procurement officers, and telecommunications infrastructure engineers underwrites the qualitative findings. Primary fieldwork engaged FPGA program managers at hyperscale operators, automotive Tier 1 supplier platform architects, and industrial control system integrators. Secondary validation drew from Bureau of Industry and Security export classification filings, MIIT GB standard compliance registries, and ECHA REACH substance restriction updates. Bottom-up shipment estimates triangulated against top-down foundry capacity allocation data.
Comparable-period anchoring tied projection windows to historical FPGA deployment cycles in telecommunications infrastructure and defense platform development timelines. Segmentation modeling spanned product architecture, end-use qualification tier, technology integration depth, and geographic regulatory cluster. CAGRs derived from logic cell density migration curves and foundry node transition rates. Forecast inputs incorporated Open RAN disaggregation mandates and EU AI Act compliance deadlines.
Several conditions sit outside the modeled scope, including unannounced foundry node transitions, export control classification threshold adjustments, and ASIC substitution acceleration above ten-thousand-unit production thresholds. Forecasts reflect assumptions regarding sustained Taiwan-based CMOS capacity availability and stable dual-use licensing timelines. A small set of named triggers warrants ongoing watch: Bureau of Industry and Security rulemaking expansion, India PLI scheme incentive modifications, and photonic interconnect standardization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Layer Pads Market
Semiconductor Devices
Global Current Sense Amplifier Market
Semiconductor Devices
Global Through Silicon via (TSV) Technology Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Gaming GPU Market
Semiconductor Devices
Global Transistor Market
Semiconductor Devices
Global Precision Parts Market
Semiconductor Devices
Global Small Signal Diode Market
Semiconductor Devices
Reachers Market
Semiconductor Devices
Bipolar Transistors Market
Semiconductor Devices
IGBT Market
Semiconductor Devices
Rad-Hard Mosfets Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Global Switched Capacitor Filter Market