
 Asia-Pacific Semiconductor Diode Market | 2026-2036
Asia-Pacific Semiconductor Diode Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Semiconductor Diode Market Insights
Silicon carbide is shifting into mainstream rectifier and Schottky diode designs as manufacturers pursue higher breakdown voltages and thermal performance. ROHM Co. Ltd leverages captive SiC substrate capacity to anchor its power device portfolio across Japanese automotive OEM supply chains. Toshiba Electronic Devices & Storage Corporation sustains dominance in discrete silicon rectifiers through its Kaga fab operations. Infineon Technologies AG competes on GaN-on-Si process maturity for telecommunications infrastructure applications.
A semiconductor diode is a two-terminal p-n junction device that permits unidirectional current flow with a specified forward voltage drop and reverse recovery time; foundries fabricate these structures through epitaxial growth, ion implantation, and metallization to achieve precise breakdown characteristics for power conversion and signal conditioning tasks. Schottky diodes lead the product type hierarchy in consumer electronics power supplies due to their sub-50 nanosecond switching speed, while silicon carbide technology captures the fastest expansion trajectory as electric vehicle onboard chargers demand kilovolt-class blocking capability. Industrial automation end users concentrate procurement in high-current rectifier modules, whereas telecommunications infrastructure prioritizes low-capacitance signal diodes for RF front-end protection.
Japan's METI coordinates domestic semiconductor supply chain resilience through facility subsidies and export control alignment with US Commerce Department frameworks. China's MIIT enforces GB standards for power semiconductor reliability testing, while South Korea's MFDS and KOSHA jointly govern occupational exposure limits in GaN epitaxy fabs. Stakeholders must monitor how divergent carbon-border adjustment mechanisms and subsidy localization requirements reshape cross-border wafer sourcing decisions.
Market Dynamics
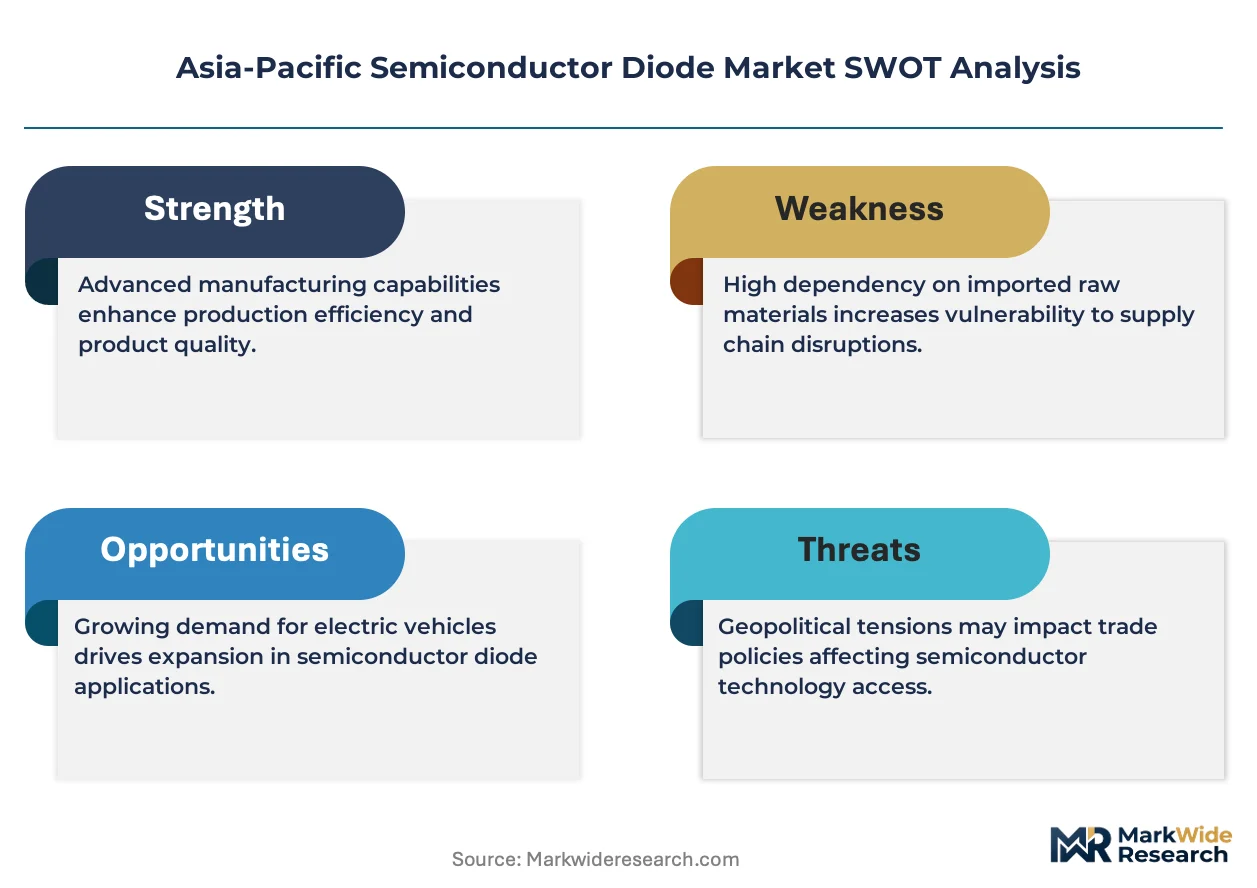
Wide-bandgap material substitution is redrawing competitive boundaries across the Asia-Pacific semiconductor diode landscape, as electric vehicle manufacturers demand thermal performance that legacy silicon architectures cannot deliver.
Growth Catalysts
- Powertrain electrification mandates:China's dual carbon goals and Japan's METI semiconductor subsidies are redirecting fabrication investment toward silicon carbide substrates for onboard charger applications.
- Telecommunications infrastructure buildout:GaN-on-Si process maturity is accelerating deployment in 5G base station RF front-end protection across South Korea's Pyeongtaek semiconductor complex.
- Regional cluster concentration:Foundry capacity expansion in China's Yangtze River Delta cluster is compressing lead times for high-current rectifier modules serving industrial automation end users.
Market Restraints
- Substrate supply concentration:Captive silicon carbide wafer production remains concentrated among Japanese and Chinese vertically integrated suppliers, constraining independent device house access.
- GaN epitaxy capital intensity:Metal-organic chemical vapor deposition equipment costs exceed $3 million per reactor, limiting fab capacity expansion among mid-tier manufacturers.
- REACH substance restrictions:European chemical registration requirements are complicating metallization paste formulations for lead-free diode packaging exported from Asia-Pacific facilities.
Strategic Opportunities
- India's PLI scheme for semiconductors:Production-linked incentive structures are attracting diode packaging and testing operations to Gujarat and Tamil Nadu industrial corridors.
- Renewable energy inverter demand:Photovoltaic string inverters and wind turbine converters are creating kilovolt-class blocking requirements that silicon carbide Schottky diodes uniquely satisfy.
- Direct OEM contracting:Automotive powertrain engineers are bypassing traditional distribution channels to specify custom diode modules directly with foundries.
Industry Challenges
- Wide-bandgap device modeling expertise:Power electronics design houses face acute shortages of engineers proficient in SiC and GaN thermal runaway characterization.
- Cross-border wafer logistics:Divergent carbon-border adjustment mechanisms between China, Japan, and South Korea are forcing inventory repositioning across multi-site supply networks.
- Reliability certification timelines:GB standards enforcement by China's MIIT for power semiconductor testing is extending qualification cycles for new diode product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Semiconductor Diode Market |
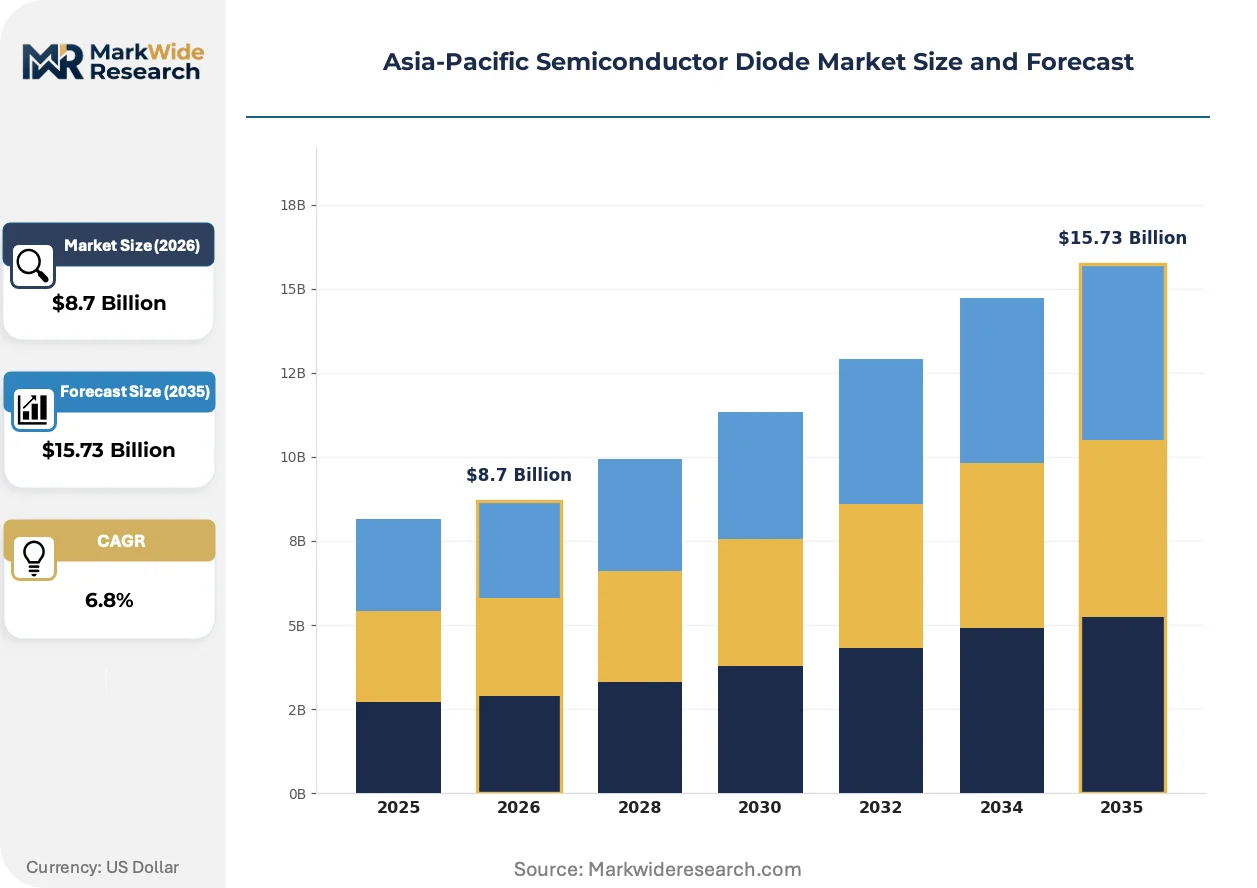
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rectifier Diodes, Zener Diodes, Schottky Diodes, Signal Diodes End User: Consumer Electronics, Automotive, Industrial Automation, Telecommunications Technology: Silicon, Gallium Nitride, Silicon Carbide, Organic Application: Power Supply, Voltage Regulation, Signal Processing, Lighting |
| Companies Covered | Hitachi Power Semiconductor Device Ltd, Littelfuse Inc., ROHM Co. Ltd, Semikron, Toshiba Electronic Devices & Storage Corporation, Infineon Technologies AG, NXP Semiconductors NV, Shindengen Electric Manufacturing Co. Ltd, Diodes Incorporated, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Semiconductor Diode Market Trends and Innovations
Material science breakthroughs and procurement model reinvention are converging to compress product lifecycles and redistribute value capture across the Asia-Pacific semiconductor diode value chain.
Silicon carbide trench MOSFET-integrated diodes are decentralizing power module design authority away from discrete component specialists toward integrated system architects. Automotive tier-one suppliers in Japan's Kumamoto prefecture are adopting these co-packaged solutions for 800-volt electric vehicle architectures. This integration trajectory is compressing the addressable market for standalone rectifier devices in high-voltage applications.
METI's facility subsidy framework is mandating export control alignment with US Commerce Department semiconductor restrictions as a condition for domestic resilience funding. Japanese diode manufacturers must now bifurcate product roadmaps between China-accessible and China-restricted process technologies. The policy friction is most acute in silicon carbide epitaxy equipment sourcing, where Tokyo Electron and Shin-Etsu Chemical face licensing complexity.
Automotive OEMs are consolidating diode procurement under single-source power module contracts that bundle active and passive components under unified reliability warranties. This contractual consolidation is displacing the multi-vendor discrete purchasing patterns that historically characterized Japanese and Korean supply chains. The behavioral shift is most visible in China's Yangtze River Delta, where NIO, BYD, and SAIC Motor have established captive power electronics engineering centers.
Asia-Pacific Semiconductor Diode Market Segmentation
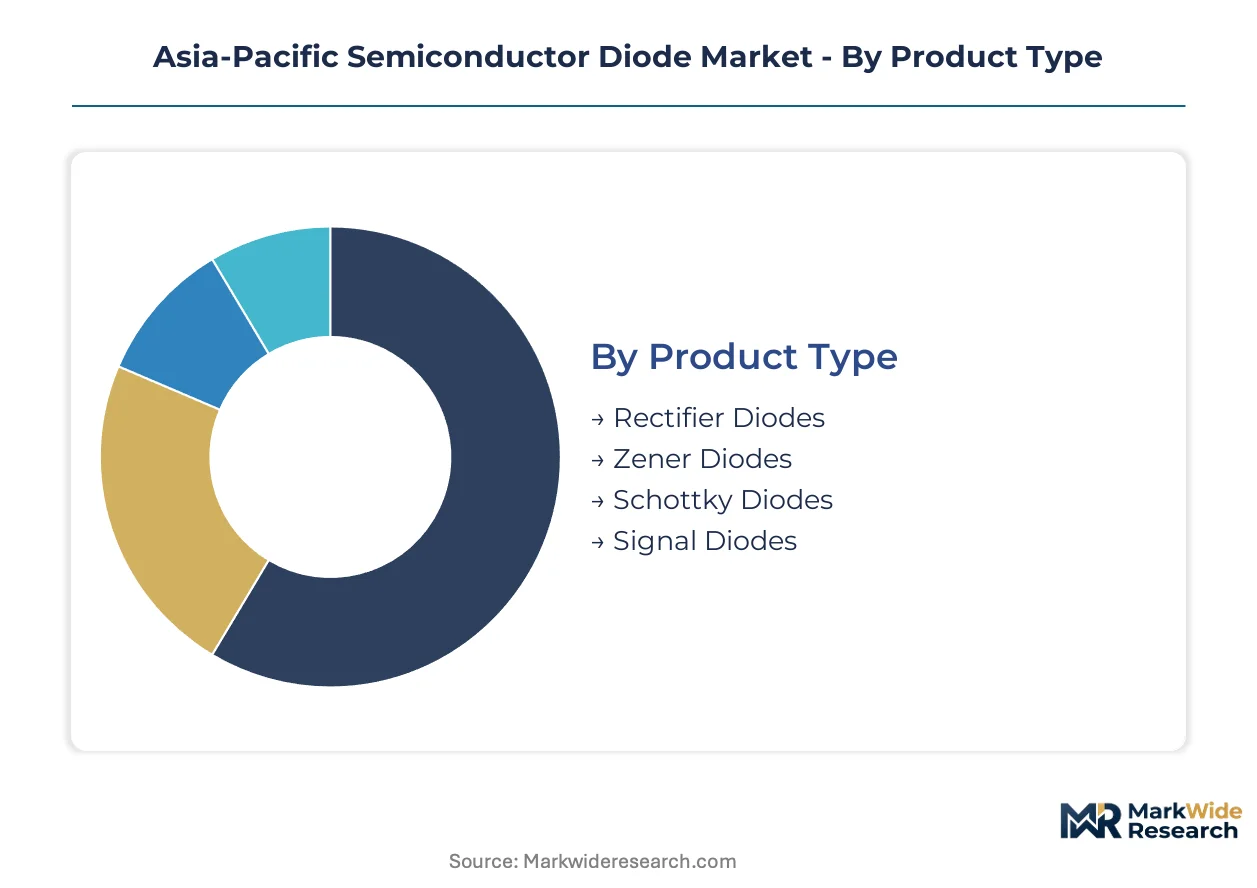
Diode procurement patterns diverge sharply across power electronics applications. Material selection and thermal specifications determine supplier qualification pathways in automotive and telecommunications verticals.
Product Type:
Buyers in this category differentiate by switching speed requirements and reverse recovery tolerance.
- Schottky Diodes:Metal-semiconductor junction architecture delivers sub-50 nanosecond switching with minimal forward voltage drop. Consumer electronics power supplies in China's Yangtze River Delta cluster specify these for adapter and charger applications where efficiency losses compound at scale.
- Rectifier Diodes:Standard p-n junction construction handles high-current conversion in industrial motor drives and welding equipment. Procurement concentrates in South Korea's Pyeongtaek semiconductor complex, where captive fab capacity serves Hyundai and Kia electrification programs.
- Zener Diodes:Heavily doped junctions exploit reverse breakdown for precise voltage clamping in protection circuits.
- Signal Diodes:Small-signal germanium or silicon structures manage RF front-end switching in 5G base station deployments.
Volume sits with Rectifier Diodes; growth tilts toward Schottky Diodes.
End User:
Application voltage tiers separate procurement specifications across customer verticals.
- Automotive:Onboard chargers and DC-DC converters demand kilovolt-class blocking capability with junction temperatures exceeding 175°C. Japan's Kumamoto prefecture hosts concentrated engineering activity for 800-volt electric vehicle architectures.
- Telecommunications:Low-capacitance signal diodes protect RF front-ends in 5G massive MIMO arrays. South Korean base station deployment schedules compress qualification timelines for GaN-compatible protection devices.
- Consumer Electronics:Cost-optimized silicon Schottky devices dominate adapter and fast-charger applications.
- Industrial Automation:High-current rectifier modules serve variable frequency drives and servo motor controllers.
Automotive commands premium pricing; telecommunications infrastructure drives volume scale.
Technology:
Substrate bandgap properties determine thermal runway margins and switching frequency ceilings.
- Silicon Carbide:Wide bandgap enables 10x higher breakdown field strength than silicon, with thermal conductivity approaching copper. China's MIIT GB standards for reliability testing are extending qualification cycles for new SiC diode introductions.
- Gallium Nitride:Heterostructure devices exploit two-dimensional electron gas for megahertz-class switching in telecommunications power amplifiers. MOCVD reactor capital costs exceed $3 million per unit, constraining mid-tier fab expansion.
- Silicon:Mature epitaxy and ion implantation processes sustain cost leadership in sub-600V applications.
- Organic:Solution-processed semiconductors enable flexible substrate integration for emerging display and wearable applications.
Silicon retains volume dominance; silicon carbide gains share fastest in electrification applications.
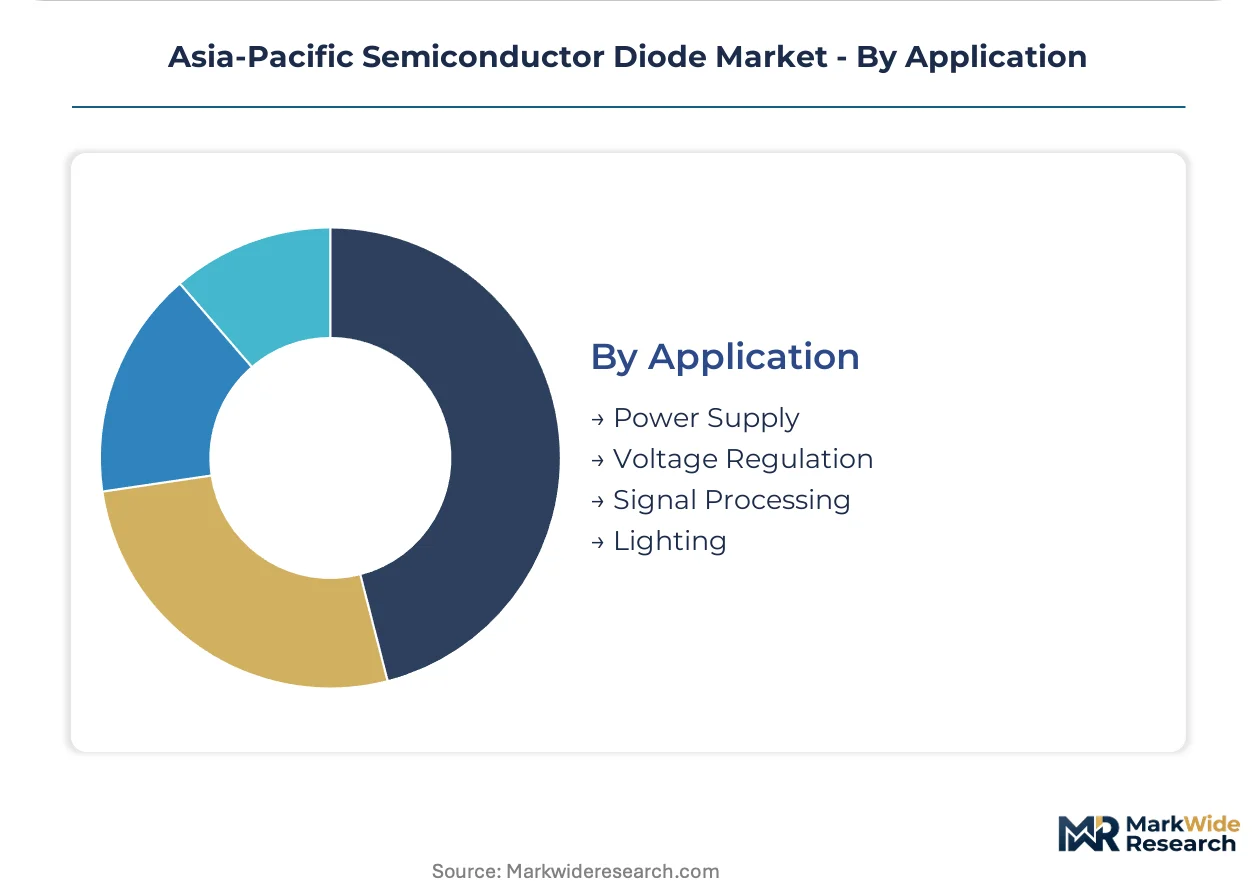
Application:
Power density requirements separate passive component selection across circuit functions.
- Power Supply:AC-DC and DC-DC conversion stages specify diodes by forward drop and reverse recovery charge. Photovoltaic string inverters in India and Australia create demand for 1200V-class silicon carbide rectifiers.
- Voltage Regulation:Shunt and series regulators depend on tight tolerance Zener and avalanche breakdown characteristics. Industrial automation end users in Japan's Kaga fab corridor prioritize long-term stability over cost minimization.
- Signal Processing:RF mixers and detectors require minimal junction capacitance at microwave frequencies.
- Lighting:LED driver circuits specify fast-recovery rectifiers for high-frequency switching topologies.
Power Supply anchors procurement volume; Voltage Regulation exhibits steepest expansion trajectory in renewable energy integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric vehicle powertrain electrification concentrates diode procurement in three distinct manufacturing corridors across the Asia-Pacific region. China's dual carbon goals and Japan's METI semiconductor subsidies are redirecting fabrication investment toward wide-bandgap materials. South Korea's telecommunications infrastructure buildout creates parallel demand for RF protection devices.
China
Onboard charger and DC-DC converter programs at BYD, NIO, and SAIC Motor are scaling silicon carbide diode procurement. MIIT enforces GB standards for power semiconductor reliability testing that extend qualification cycles. The Yangtze River Delta cluster hosts concentrated foundry capacity expansion for high-current rectifier modules.
Japan
Automotive OEMs including Toyota and Honda are specifying 800-volt architectures requiring kilovolt-class blocking capability. METI coordinates domestic supply chain resilience through facility subsidies contingent on export control alignment with US Commerce Department frameworks. Kumamoto prefecture anchors engineering activity for integrated power module development.
South Korea
5G massive MIMO base station deployment schedules compress qualification timelines for low-capacitance signal diodes. MFDS and KOSHA jointly govern occupational exposure limits in GaN epitaxy fabrication facilities. The Pyeongtaek semiconductor complex serves Hyundai and Kia electrification programs with captive rectifier capacity.
India
Production-linked incentive structures under the PLI scheme for semiconductors are attracting diode packaging and testing operations. The country's national electronics regulator coordinates with state industrial development authorities on fab approvals. Gujarat and Tamil Nadu industrial corridors host emerging backend assembly and test facilities.
Vietnam
Consumer electronics manufacturing migration from China is scaling demand for cost-optimized silicon Schottky devices in adapter and charger applications. The Ministry of Industry and Trade administers special economic zone incentives for semiconductor component operations. Northern industrial provinces including Bac Ninh and Thai Nguyen concentrate foreign-invested electronics assembly.
Asia-Pacific Semiconductor Diode Market Competitive Landscape
Capacity expansion dominates the current landscape as foundries race to secure silicon carbide substrate supply for automotive electrification programs. The vendor structure tiers between vertically integrated Japanese suppliers with captive wafer production and independent device houses dependent on merchant substrate sources. Three archetypes define competitive positioning: integrated materials-to-devices players, fabless design specialists with foundry partnerships, and discrete component module assemblers. M&A activity targets GaN epitaxy capabilities while strategic partnerships lock in multi-year substrate offtake agreements.
Among Japanese vertically integrated suppliers, ROHM Co. Ltd and Toshiba Electronic Devices & Storage Corporation exemplify the materials-captive archetype with in-house silicon carbide substrate operations. Infineon Technologies AG represents the European multinational position competing through GaN-on-Si process maturity. Hitachi Power Semiconductor Device Ltd, Littelfuse Inc., and Semikron occupy positions across the power module and protection device segments. These named entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Hitachi Power Semiconductor Device Ltd |
| Littelfuse Inc. |
| ROHM Co. Ltd |
| Semikron |
| Toshiba Electronic Devices & Storage Corporation |
| Infineon Technologies AG |
| NXP Semiconductors NV |
| Shindengen Electric Manufacturing Co. Ltd |
| Diodes Incorporated |
| Others |
Pricing and Supply Chain Analysis
Captive silicon carbide substrate production among Japanese and Chinese vertically integrated suppliers anchors both supply security and pricing power across the Asia-Pacific semiconductor diode landscape. ROHM Co. Ltd and Toshiba Electronic Devices & Storage Corporation leverage in-house wafer operations to command premium positioning for automotive electrification contracts, while independent device houses face margin compression from merchant substrate sourcing.
Pricing Analysis
Volume concentrates in silicon rectifiers where commoditization compresses margins, while silicon carbide Schottky diodes capture premium spreads through thermal performance differentiation. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels separates qualification-intensive EV powertrain modules from cost-optimized adapter components. Pricing pressure stems from GaN epitaxy equipment capital intensity exceeding $3 million per MOCVD reactor, forcing mid-tier foundries to absorb depreciation through aggressive quoting. Consumer electronics buyers exhibit highest price sensitivity in adapter applications, whereas automotive OEMs prioritize reliability warranties over unit cost minimization.
Supply Chain Analysis
Workforce availability constraints in Japan's Kumamoto prefecture and South Korea's Pyeongtaek complex are tightening labor markets for GaN epitaxy technicians and SiC device physicists. Raw material flows draw from Chinese rare earth processing for metallization pastes, Japanese high-purity SiC boules, and Korean GaN-on-Si epitaxial templates. Single-source vulnerability concentrates in Tokyo Electron and Shin-Etsu Chemical equipment licensing, where METI export control alignment restricts technology transfer. Distribution runs through direct OEM contracting for automotive power modules, bypassing traditional component distribution channels that historically served Japanese and Korean supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific semiconductor diode market represents a consolidation play as wide-bandgap capital requirements and METI subsidy conditionalities force capital-constrained independents toward strategic exit. Substrate supply concentration and export control bifurcation are accelerating competitive separation between integrated materials-to-devices players and merchant-dependent assemblers.
For Market Incumbents: Hedge against China-restricted technology roadmaps by qualifying parallel process flows for automotive OEMs with divergent market access requirements. Secure multi-year silicon carbide substrate offtake agreements before captive Japanese and Chinese capacity locks in competitor allocation. METI's export control alignment mandates bifurcated product development, increasing R&D overhead for non-integrated players without captive wafer supply. For New Entrants and Emerging Players: India's PLI scheme for semiconductors opens a window for packaging and testing operations targeting Gujarat and Tamil Nadu industrial corridors with lower capital intensity than front-end fabrication. Target renewable energy inverter demand in photovoltaic string applications where 1200V-class silicon carbide rectifier specifications are standardizing faster than automotive qualification cycles. Pursue direct contracting with Indian and Australian solar developers bypassing incumbent module supplier relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated Japanese suppliers seeking GaN epitaxy capabilities to complement captive SiC operations. Long-term viability favors positions with demonstrated wide-bandgap device modeling expertise and automotive reliability certification track records. Watch for inflection in carbon-border adjustment mechanism harmonization across China, Japan, and South Korea, which would signal inventory repositioning cost stabilization and multi-site supply network rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Captive SiC Substrate Expansion | ROHM and Toshiba anchor automotive supply chains through in-house wafer production control. |
| GaN Epitaxy Capability Acquisition | MOCVD reactor access determines telecommunications infrastructure RF protection device participation. |
| India PLI Scheme Localization | Gujarat and Tamil Nadu corridors attract backend assembly with production-linked incentive structures. |
| Direct OEM Power Module Contracting | BYD and NIO engineering centers bypass distribution channels for custom diode specifications. |
| Export Control Roadmap Bifurcation | METI subsidy conditionalities force dual process technology development for China-accessible and restricted markets. |
Research Methodology
Independent corroboration across primary interviews with power electronics design engineers, automotive tier-one procurement directors, GaN epitaxy fab operations managers, and MIIT regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from METI facility subsidy disclosures, MIIT GB standards documentation, SEC 10-K filings of listed semiconductor suppliers, and customs data tracking silicon carbide substrate trade flows. Bottom-up segment sizing triangulates against top-down market aggregation across the analysis window.
Rate-of-change decomposition separates volume growth from value expansion across product type, end-user vertical, substrate technology, and regional production cluster dimensions. CAGRs derive from modeled adoption curves for silicon carbide in electric vehicle onboard chargers and gallium nitride in 5G telecommunications infrastructure. Forecast inputs incorporate MIIT reliability testing timeline extensions, METI export control implementation schedules, and India's PLI scheme disbursement pacing without year-specific assumptions.
The model assumes a particular technology adoption path; alternative pathways for silicon carbide trench MOSFET-integrated diodes displacing standalone rectifier devices would alter the outlook for discrete component specialists. Forecasts reflect assumptions regarding sustained electrification program commitments by Chinese and Japanese automotive OEMs and stable rare earth processing access for metallization paste formulations. Material deviation in carbon-border adjustment mechanism convergence or GaN epitaxy equipment licensing restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Finfet Technology Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
Asia Pacific Motherboard Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
ATX Motherboards Market
Semiconductor Devices
IT & Telecom Discrete Semiconductor Market
Semiconductor Devices
Global Silicon Carbide Wafers Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Global Semiconductor Lead Frame Market
Semiconductor Devices
Super Junction Mosfet Market
Semiconductor Devices
Laneth-16 Market
Semiconductor Devices
IGBT Market
Semiconductor Devices
Varactor Diode Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market