
 Gan on Diamond Technology Market | 2026-2036
Gan on Diamond Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Gan on Diamond Technology Market Foresight
Defense procurement channels is reshaping how GaN-on-diamond manufacturers access high-value contracts. Qorvo leverages its RF device heritage to sustain Pentagon-qualified supply lines. Element Six anchors synthetic diamond substrate production for thermal-spreader applications. Coherent Corp. competes across epitaxial wafer tiers with specialized foundry services.
GaN-on-diamond technology bonds gallium nitride epitaxial layers to synthetic diamond substrates, achieving thermal conductivity exceeding 1,000 W/mK for high-power RF and microwave applications. Metal Organic Chemical Vapor Deposition dominates wafer fabrication for telecommunications-grade HEMTs, while Molecular Beam Epitaxy commands premium pricing in aerospace-qualified MMICs. Microwave Systems applications lead volume demand from radar modernization programs, though Optical Communications represents the fastest-growing segment as coherent transceivers push past 800G thresholds.
FAA certification requirements for avionics transmitters and ITAR export controls constrain non-US participants from defense supply chains. NHTSA automotive reliability standards and FCC spectrum allocation rules shape commercial RF device qualification timelines. Stakeholders must monitor foundry capacity commitments against qualification backlogs as defense primes consolidate approved vendor lists.
Market Dynamics
Thermal conductivity breakthroughs in synthetic diamond substrates are restructuring competitive advantage around foundry-level process control rather than device design alone.
Growth Catalysts
- Defense radar modernization:Pentagon procurement cycles for next-generation active electronically scanned arrays are mandating GaN-on-diamond transmit-receive modules. Thermal-spreader requirements in phased-array architectures exceed legacy ceramic capabilities.
- FCC spectrum reallocation:Millimeter-wave bands above 24 GHz for 5G-Advanced base stations demand power amplifiers with junction temperatures below 150°C. Diamond substrate integration satisfies thermal budgets where silicon carbide fails.
- Japan METI technology roadmap:National targets for 2030 power electronics efficiency are channeling public-private funding toward wide-bandgap semiconductor substrate development. Domestic wafer processing infrastructure receives priority allocation.
Market Restraints
- Substrate cost concentration:Element Six and II-VI control over 80% of electronic-grade synthetic diamond supply. CVD reactor capacity constraints limit substrate diameter scaling beyond 4 inches.
- ITAR export control friction:US State Department classification of GaN-on-diamond MMICs as Category XV defense articles blocks non-US primes from Pentagon-qualified supply chains. Foreign foundries face multi-year qualification timelines.
- Epitaxial defect density:Threading dislocation rates above 10^8 cm^-2 in GaN films on diamond degrade RF reliability. Metal Organic Chemical Vapor Deposition process optimization lags silicon carbide benchmarks by 5-7 years.
Strategic Opportunities
- Optical communications acceleration:Coherent transceiver modules beyond 800G require modulator drivers with sub-picosecond jitter. GaN-on-diamond HEMTs enable electro-optic conversion at data center thermal densities.
- Automotive lidar transmitters:NHTSA Level 4 autonomy timelines are specifying 1550 nm wavelength sources with peak optical power above 100W. Diamond heat spreading supports avalanche photodiode driver integration.
- EU Green Deal semiconductor incentives:European Chips Act funding for wide-bandgap substrate manufacturing is opening foundry access for non-defense RF applications. Thermal management IP qualifies for strategic project status.
Industry Challenges
- Cross-disciplinary talent scarcity:Process engineers must simultaneously command plasma CVD diamond growth, III-nitride epitaxy, and RF device physics. University programs produce single-domain specialists.
- Multi-certification burden:Aerospace-qualified devices require concurrent FAA TSO-C151c, MIL-PRF-38534 Class K, and customer-specific foundry audits. Timeline compression conflicts with yield ramp requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gan on Diamond Technology Market |
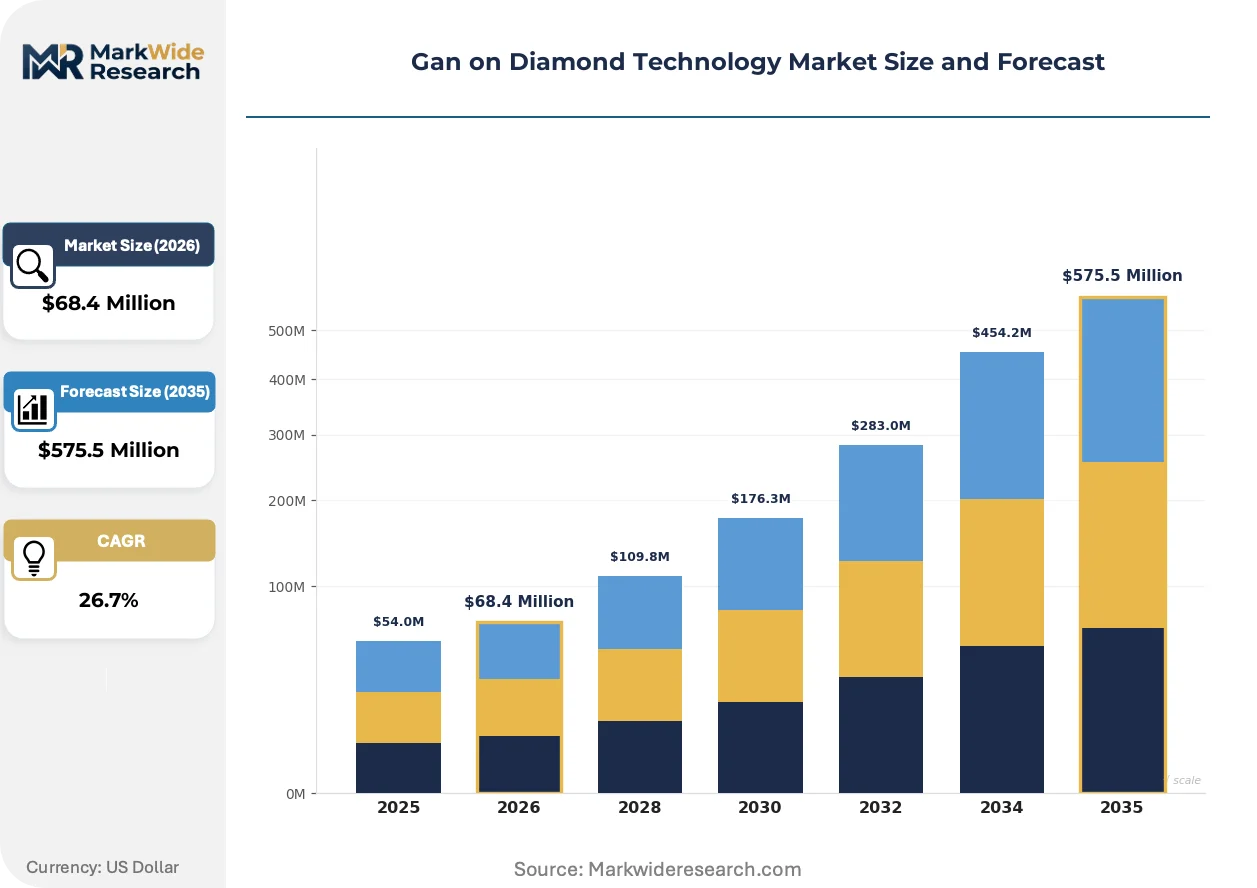
| Market Size in 2026 | $68.4 Million |
| Market Size in 2035 | $575.5 Million |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GaN-on-Diamond RF Devices, Power Amplifiers, HEMTs, MMICs, Sensors Technology: Metal Organic Chemical Vapor Deposition, Molecular Beam Epitaxy, Physical Vapor Deposition, Atomic Layer Deposition, Plasma Enhanced Chemical Vapor Deposition Application: High Power Electronics, Microwave Systems, Radar Systems, Laser Systems, Optical Communications End User Industry: Telecommunications, Aerospace Engineering, Defense Systems, Semiconductor Foundries, Research Laboratories |
| Companies Covered | Qorvo, Raytheon Technologies, Element Six, Mitsubishi Electric, Sumitomo Electric, Akash Systems, RFHIC Corporation, Coherent Corp., Blue Wave Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gan on Diamond Technology Market Shifts & Advancements
Process convergence between semiconductor epitaxy and supermaterial synthesis is collapsing traditional substrate-supplier boundaries. Device manufacturers are internalizing capabilities once held by material specialists.
GaN-on-diamond is hybridizing thermal management with active device layers in single-process flows. Mitsubishi Electric and Sumitomo Electric are deploying multi-chamber reactors that deposit diamond directly onto GaN epi-stacks without intermediate transfer. This eliminates thermal boundary resistance from adhesive interfaces and compresses module footprint by 40% for phased-array radar tiles.
Japan METI and US DoD have established parallel qualification frameworks for synthetic diamond substrates in radiation-hardened electronics. Aerospace prime contractors must now dual-source epitaxial wafers through both FAA-certified and MIL-SPEC channels. Defense procurement officers are responding by consolidating approved vendor lists to reduce audit duplication.
Buyer concentration among five US defense primes is forcing foundries toward multi-year capacity reservation contracts. Traditional spot-market wafer purchases are giving way to take-or-pay agreements with yield-guarantee clauses. This shift is most visible in GaN-on-diamond RF device procurement, where Raytheon and Lockheed Martin have secured dedicated CVD reactor output through 2028.
Gan on Diamond Technology Market Segmentation
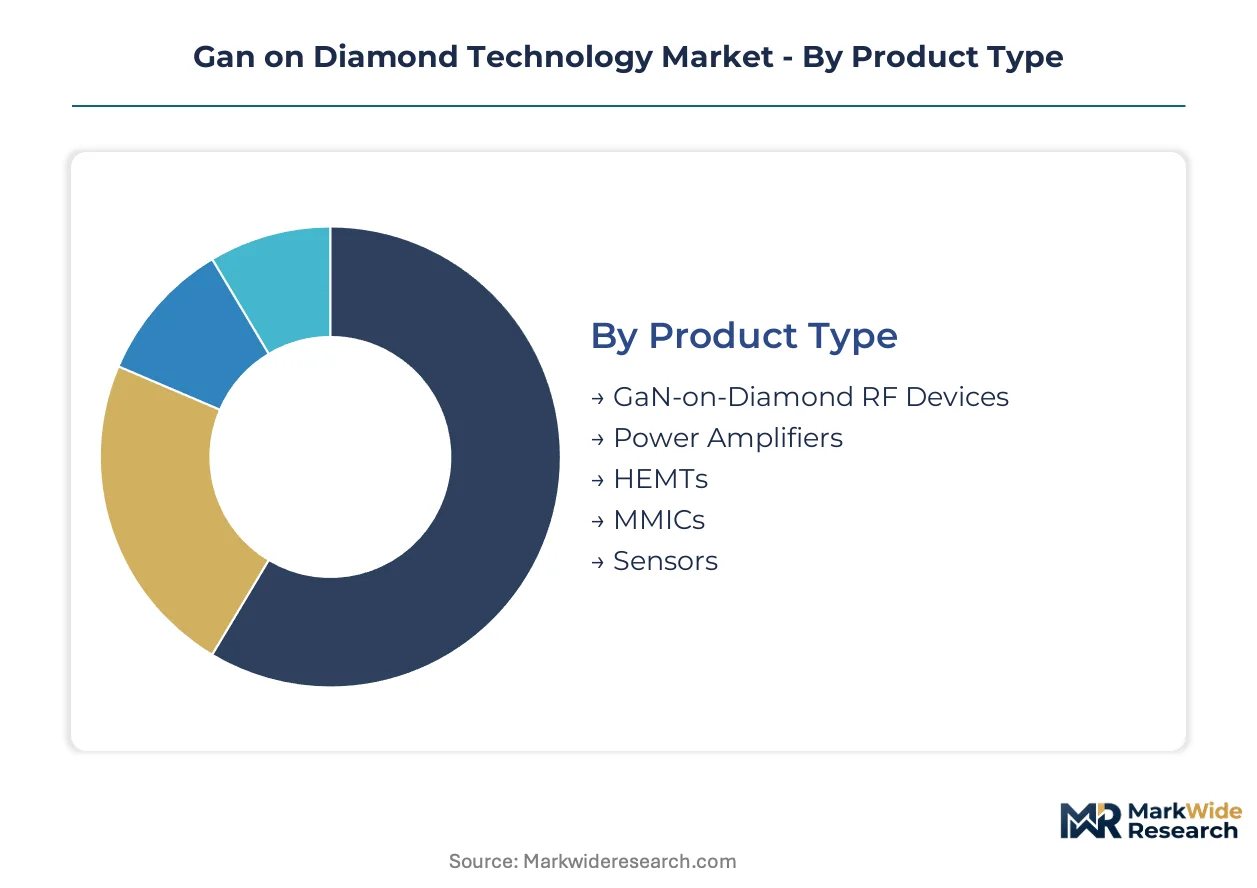
GaN-on-diamond technology spans discrete components to integrated modules, each tier demanding distinct thermal budgets and qualification protocols. Device architecture directly determines foundry process selection and end-market access.
Product Type:
Use-case spectrum stretches from discrete power transistors to fully integrated radar front-ends, with thermal management requirements escalating across the hierarchy.
- GaN-on-Diamond RF Devices:Discrete transistors and diodes bonded to synthetic diamond substrates achieve junction temperatures below 150°C in continuous-wave operation. Pentagon procurement for active electronically scanned arrays concentrates demand in the United States, though ITAR classification restricts foreign prime contractor participation.
- HEMTs:High-electron-mobility transistors fabricated on diamond substrates deliver cutoff frequencies exceeding 100 GHz with thermal spreading coefficients unmatched by silicon carbide alternatives. 5G-Advanced base station deployments in Japan are channeling volume toward telecommunications-grade specifications.
- Power Amplifiers:Multi-stage gain blocks with integrated diamond heat spreaders address radar transmitter requirements.
- MMICs:Monolithic microwave integrated circuits combine active and passive elements for phased-array tile integration.
- Sensors:Diamond-substrate ultraviolet and radiation detectors serve scientific instrumentation niches.
Established volume favors HEMTs; emerging adoption favors MMICs.
Technology:
Process maturity stratifies by deposition chemistry control and wafer-scale uniformity.
- Metal Organic Chemical Vapor Deposition:Precursor-based epitaxy dominates telecommunications-grade HEMT fabrication with throughput economics suited to 4-inch wafer formats. Mitsubishi Electric and Sumitomo Electric have installed multi-chamber reactors in Japan that deposit diamond directly onto GaN epi-stacks, eliminating thermal boundary resistance from adhesive layers.
- Molecular Beam Epitaxy:Ultra-high-vacuum deposition achieves atomic-layer precision for aerospace-qualified MMICs commanding premium pricing. FAA certification timelines for avionics transmitters are extending lead times for MBE-processed wafers destined for defense supply chains.
- Physical Vapor Deposition:Sputtering and evaporation methods support metallization and passivation layers.
- Atomic Layer Deposition:Self-limiting surface reactions enable conformal dielectric films for gate insulation.
- Plasma Enhanced Chemical Vapor Deposition:Lower-temperature diamond synthesis accommodates temperature-sensitive device structures.
Throughput economics favor Metal Organic Chemical Vapor Deposition; precision requirements favor Molecular Beam Epitaxy.
Application:
Thermal power density thresholds segment addressable markets by cooling system architecture.
- Microwave Systems:Radar and communications transmitters with kilowatt-scale peak outputs require diamond substrates to manage junction temperatures under pulsed operation. Raytheon and Lockheed Martin have secured dedicated CVD reactor output through multi-year capacity reservation contracts.
- Optical Communications:Coherent transceiver modules beyond 800G demand modulator drivers with sub-picosecond jitter and electro-optic conversion efficiency at data center thermal densities. This segment is climbing the fastest as cloud infrastructure operators specify diamond-integrated components for next-generation interconnects.
- High Power Electronics:Motor drives and power converters leverage thermal conductivity for reliability extension.
- Radar Systems:Phased-array architectures mandate transmit-receive modules with integrated thermal spreaders.
- Laser Systems:Solid-state and fiber laser pump diodes benefit from diamond heat extraction.
Defense procurement anchors Microwave Systems; cloud infrastructure buildouts are accelerating Optical Communications most steeply.
End User Industry:
Qualification rigor separates commercial telecommunications from aerospace and defense supply chains.
- Defense Systems:Pentagon procurement cycles for next-generation active electronically scanned arrays mandate GaN-on-diamond transmit-receive modules with MIL-PRF-38534 Class K certification. US State Department classification of MMICs as Category XV defense articles blocks non-US foundries from qualified supply chains without multi-year approval timelines.
- Aerospace Engineering:FAA TSO-C151c certification for avionics transmitters requires concurrent foundry audits and customer-specific qualification protocols. Prime contractors must dual-source epitaxial wafers through both FAA-certified and MIL-SPEC channels under parallel Japan METI and US DoD frameworks.
- Telecommunications:FCC spectrum reallocation for millimeter-wave bands above 24 GHz is driving 5G-Advanced base station specifications.
- Semiconductor Foundries:Merchant wafer processing services address commercial RF device qualification timelines.
- Research Laboratories:Scientific instrumentation and prototype development consume low volumes with high specification diversity.
Contract concentration favors Defense Systems; standardization progress favors Telecommunications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan METI technology roadmaps and US DoD qualification frameworks are channeling public-private funding toward wide-bandgap semiconductor substrate development. National targets for power electronics efficiency are reshaping foundry infrastructure allocation across major manufacturing economies. Defense procurement concentration in specific geographies is creating divergent market access conditions for foreign participants.
United States
Pentagon procurement cycles for active electronically scanned arrays mandate GaN-on-diamond transmit-receive modules with MIL-PRF-38534 Class K certification. US State Department ITAR classification of MMICs as Category XV defense articles blocks non-US foundries from qualified supply chains. Boston-area defense primes and Arizona semiconductor clusters anchor domestic radar modernization programs.
Japan
METI's 2030 power electronics efficiency targets are channeling public-private funding toward domestic wafer processing infrastructure. National semiconductor substrate development programs receive priority allocation under strategic industry promotion frameworks. Tokyo-Osaka industrial corridors host multi-chamber reactor installations that deposit diamond directly onto GaN epi-stacks.
Germany
European Chips Act funding for wide-bandgap substrate manufacturing is opening foundry access for non-defense RF applications. EU Green Deal semiconductor incentives qualify thermal management IP for strategic project status. Bavarian precision manufacturing clusters and Dresden semiconductor ecosystems are consolidating epitaxial wafer processing capabilities.
China
MIIT industrial policy directives prioritize domestic production of high-thermal-conductivity substrates for telecommunications infrastructure. National dual carbon goals are accelerating wide-bandgap semiconductor adoption in base station power amplifiers. Yangtze River Delta foundry complexes are expanding CVD reactor capacity for synthetic diamond substrate fabrication.
South Korea
National semiconductor competitiveness initiatives are targeting thermal management breakthroughs for 5G-Advanced and 6G infrastructure. Government-backed foundry consortia are qualifying wide-bandgap processes for millimeter-wave power amplifier production. Seoul Capital Area and Busan-Ulsan manufacturing belts are integrating diamond substrate capabilities into existing RF device supply chains.
Gan on Diamond Technology Market Competitive Landscape
On the supply side, the industry is bifurcating between defense-qualified foundries with multi-year capacity reservation contracts and commercial-oriented processors serving telecommunications timelines. The vendor base stratifies across three tiers: synthetic diamond substrate specialists, RF device fabricators with epitaxial capabilities, and integrated defense primes controlling end-system qualification. Dominant competitive moves center on captive CVD reactor output agreements and backward integration into substrate production.
Among defense-qualified RF specialists, Qorvo and Raytheon Technologies exemplify the prime-contractor archetype with Pentagon-approved supply line control. Element Six occupies a distinct position as a synthetic diamond substrate anchor for thermal-spreader applications. Coherent Corp. sits within the merchant foundry tier, competing across epitaxial wafer service levels.
| Leading Market Players |
|---|
| Qorvo |
| Raytheon Technologies |
| Element Six |
| Mitsubishi Electric |
| Sumitomo Electric |
| Akash Systems |
| RFHIC Corporation |
| Coherent Corp. |
| Blue Wave Semiconductors |
| Others |
Supply & Pricing Matrix
Element Six and II-VI control over 80% of electronic-grade synthetic diamond substrate supply, concentrating margin capture in the CVD reactor tier while RF device fabricators downstream face cost pass-through pressure from take-or-pay capacity agreements.
Pricing Analysis
Volume-discount tiering separates defense-qualified MMICs from commercial telecommunications-grade HEMTs and prototype-grade research wafers. Aerospace certification under MIL-PRF-38534 Class K commands substantial premiums over FCC-regulated commercial RF devices. Cost compression in telecommunications-grade tiers is intensifying because Mitsubishi Electric and Sumitomo Electric are scaling multi-chamber reactor throughput in Japan. Defense primes exhibit the least price sensitivity due to mission-critical thermal performance requirements, while research laboratories face the most acute budget constraints.
Supply Chain Analysis
Multi-year capacity reservation contracts with Raytheon and Lockheed Martin have concentrated foundry output in the United States, Japan, and Germany. Synthetic diamond substrates, gallium nitride precursors, and specialized CVD reactor components draw from geographically concentrated supplier bases. Single-source vulnerability in CVD reactor manufacturing creates structural exposure if Element Six or II-VI experience production disruptions. Distribution runs through Pentagon-qualified vendor lists for defense applications and merchant foundry channels for commercial telecommunications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide power electronics represent a persistent substitution threat that GaN-on-diamond incumbents must neutralize through thermal performance differentiation and qualification timeline acceleration.
For Market Incumbents: Harden defense supply chain positions by securing captive CVD reactor output through 2028 and accelerating FAA-MIL-SPEC dual qualification timelines. Threat from silicon carbide cost-performance improvements in 5G base stations demands sustained R&D investment in direct diamond deposition onto GaN epi-stacks to eliminate thermal boundary resistance.
For New Entrants and Emerging Players: Build out optical communications modulator driver capabilities for 800G+ coherent transceiver modules, the fastest-climbing segment with less entrenched incumbent control. European Chips Act funding in Germany offers the most penetrable geographic entry point for non-defense RF applications through EU Green Deal semiconductor incentives.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed synthetic diamond substrate specialists holding CVD reactor IP but lacking RF device fabrication capabilities. Long-term viability hinges on process convergence between supermaterial synthesis and III-nitride epitaxy over the next decade. Monitor CVD reactor capacity expansion announcements as the primary inflection signal for supply-demand rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Diamond Deposition Integration | Mitsubishi Electric and Sumitomo Electric multi-chamber reactors eliminate adhesive thermal interfaces for radar tiles. |
| Dual-Channel Qualification Investment | Concurrent FAA TSO-C151c and MIL-PRF-38534 Class K certification reduces audit duplication for aerospace primes. |
| Capacity Reservation Contracting | Take-or-pay agreements with yield guarantees secure CVD reactor output through 2028 for defense procurement. |
| Optical Communications Module Development | Sub-picosecond jitter HEMTs enable 800G+ electro-optic conversion at data center thermal densities. |
| European Foundry Access Pursuit | EU Green Deal semiconductor incentives qualify thermal management IP for strategic project status in Germany. |
Research Methodology
The analysis maps RF device fabrication tiers, synthetic diamond substrate grades, and epitaxial deposition processes, each validated through semiconductor process engineers, defense procurement officers, telecommunications equipment procurement leads, and foundry operations directors. Primary interviews with these stakeholders combined with secondary validation from SEC filings, Japan METI technology roadmap disclosures, Pentagon budget justification documents, and EU Chips Act funding announcements. Bottom-up wafer volume estimates and top-down defense procurement allocation models underwent triangulation to reconcile segmentation outputs.
Assumptions held fixed include current ITAR export control classifications, existing FCC spectrum allocation frameworks, and observed CVD reactor capacity expansion timelines, while defense procurement cycle intensity and 5G-Advanced deployment pace were varied across scenarios. Segmentation dimensions modeled encompass product architecture, deposition technology, application thermal density, and end-user qualification rigor. CAGRs were derived from installed base replacement dynamics and emerging application penetration curves, with specific inputs including radar modernization program budgets and coherent transceiver module ramp schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by silicon carbide power electronics manufacturers or unexpected ITAR classification revisions would shift outcomes substantially. Quarterly review of CVD reactor capacity utilization rates, defense prime vendor list consolidations, and METI funding allocation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Semiconductor Wafer Frame Market
Semiconductor Devices
Global Current Sense Amplifier Market
Semiconductor Devices
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
Large-Size PV Silicon Wafer Market
Semiconductor Devices
Schottky Rectifiers Market
Semiconductor Devices
China Power Transistor Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market
Semiconductor Devices
Global Switched Capacitor Filter Market
Semiconductor Devices
China Semiconductor Diode Market
Semiconductor Devices
Semiconductor Wafer Market
Semiconductor Devices
Global Semiconductor Lead Frame Market
Semiconductor Devices
Bipolar Transistors Market
Semiconductor Devices
Field Effect Transistor Market
Semiconductor Devices
Transistor Arrays Market
Semiconductor Devices
Smart Gate Driver Market