
 Stand-Alone Video Processors Market | 2026-2036
Stand-Alone Video Processors Market Size, Share, and Industry Trends Forecast 2026-2036
Stand-Alone Video Processors Market Analytics
The EU Green Deal is decoupling energy-intensive legacy designs from next-generation procurement across European broadcasting chains. Crestron Electronics leverages its vertical integration in control systems to sustain premium positioning in enterprise installations. Extron Electronics anchors North American supply through deep channel control in educational and government verticals. NXP Semiconductors competes at the component layer, supplying codec silicon that powers multiple downstream OEM brands.
A stand-alone video processor is a dedicated hardware or firmware subsystem that ingests raw video signals, applies deinterlacing, scaling, color space conversion, and compression algorithms, and outputs formatted streams at specified resolutions and frame rates for downstream display or transmission. Its primary commercial purpose is to offload compute-intensive video manipulation from general-purpose CPUs in professional environments where latency and throughput constraints are non-negotiable. The 4K processor segment leads absolute revenue due to replacement cycles in broadcast control rooms and cinema projection chains, while streaming-technology deployments are expanding fastest as over-the-top and cloud-gaming architectures displace traditional broadcast distribution. HD processors retain volume share in cost-sensitive digital signage and secondary education installations where infrastructure refresh budgets remain constrained.
The Federal Communications Commission in the United States mandates ATSC 3.0 transition timelines that compel broadcasters to upgrade head-end processing equipment, while the European Telecommunications Standards Institute frames interoperability requirements affecting codec and interface selection across member states. China's Ministry of Industry and Information Technology enforces GB standards for video compression that condition market access for imported and domestically produced units alike. Stakeholders must monitor regulatory divergence in spectrum allocation, compression standards, and energy labeling as these forces increasingly dictate product roadmaps and geographic deployment sequencing.
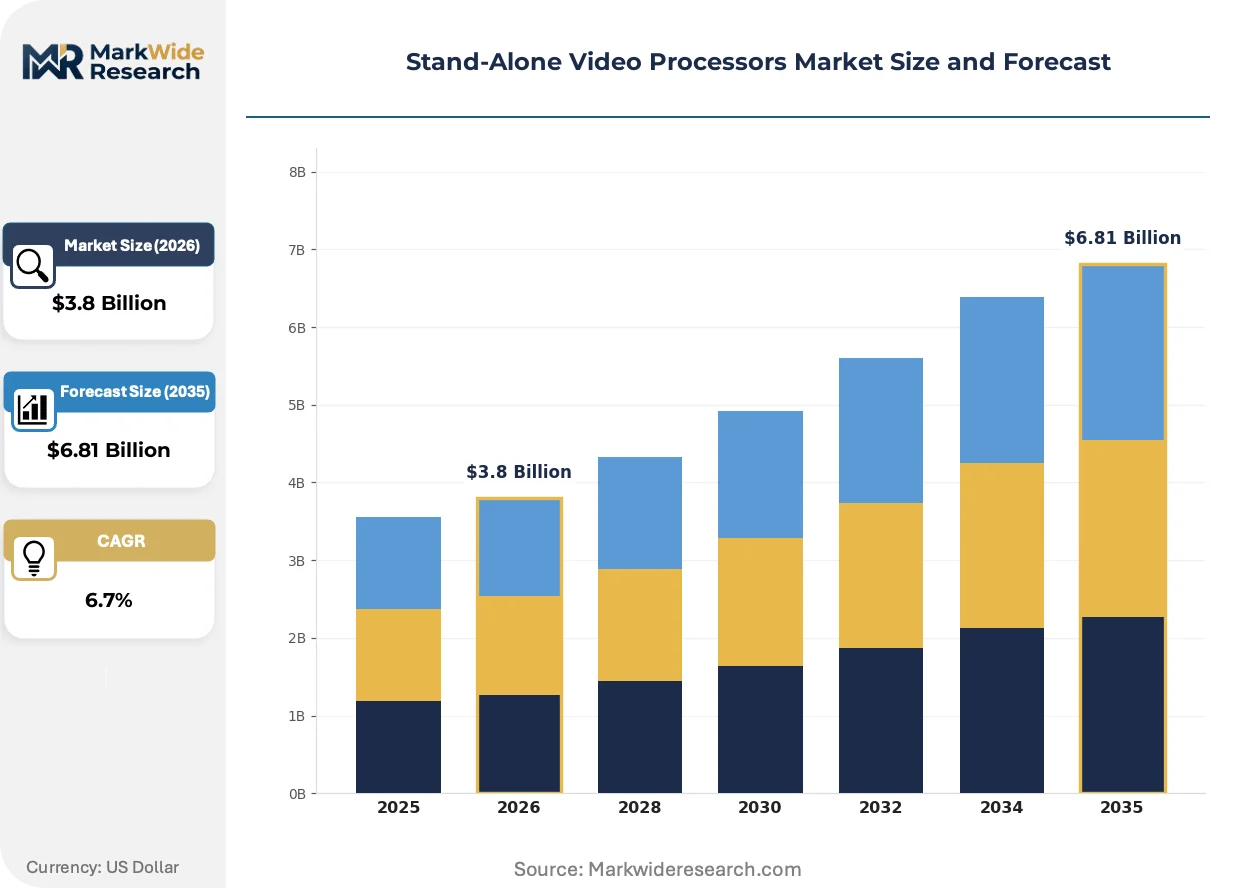
Market Dynamics
Broadcast infrastructure replacement cycles and streaming-technology diffusion are compressing refresh timelines across professional AV installations, forcing hardware procurement decisions toward codec-agnostic, energy-efficient architectures that satisfy divergent regional compliance regimes.
Growth Catalysts
- ATSC 3.0 mandates:The FCC's transition timeline compels US broadcasters to overhaul head-end processing equipment, creating immediate replacement demand for 4K-capable units with next-generation compression support.
- Cloud-gaming infrastructure:Low-latency video pipeline requirements from hyperscale data center operators are accelerating procurement of dedicated processing hardware that offloads encoding from general-purpose compute.
- EU Ecodesign requirements:Energy-efficiency thresholds under the EU Green Deal are redirecting European procurement budgets toward architectures that reduce thermal load and operational expenditure.
Market Restraints
- Codec licensing complexity:Patent pool fragmentation around HEVC, VVC, and AV1 increases unit cost unpredictability and extends vendor negotiation timelines.
- Silicon supply concentration:Advanced codec DSP and FPGA fabrication concentrates among a limited set of foundry operators, exposing OEMs to capacity allocation risk.
- Legacy infrastructure inertia:HD-SDI and 3G-SDI cabling investments in educational and government verticals delay 12G-SDI and IP-based upgrade commitments.
Strategic Opportunities
- India professional AV expansion:Bureau of Indian Standards certification alignment and rising cinema multiplex construction create entry pathways for streaming-optimized processor vendors.
- AI-assisted upscaling integration:Machine learning inference engines converging with traditional scalar pipelines enable real-time artifact reduction that differentiates premium product tiers.
- Subscription-based hardware access:Channel partners in Germany and the United States are piloting processor-as-a-service models that unbundle capital expenditure for live-event producers.
Industry Challenges
- Embedded firmware security certification:Common Criteria and FIPS 140-2 validation timelines for government and defense installations extend sales cycles by 12-18 months.
- Interoperability testing burden:SMPTE ST 2110, NMOS IS-04/IS-05, and SRT protocol compliance requirements multiply pre-deployment validation costs for systems integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stand-Alone Video Processors Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 4K Processors, HD Processors, Audio/Video Processors, Multimedia Processors Application: Broadcasting, Home Theater, Gaming, Digital Signage Technology: Analog, Digital, Hybrid, Streaming End User: Retailers, Cinemas, Educational Institutions, Enterprises |
| Companies Covered | Crestron Electronics, Inc., InFocus Corporation, Extron Electronics, NXP Semiconductors N.V., Morpho, Inc., Ateme, Vantrix Corporation, Synamedia, The MathWorks, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stand-Alone Video Processors Market Evolving Landscape
Edge-based processing architectures and software-defined video pipelines are redistributing computational workloads away from centralized broadcast facilities, compressing the boundary between production and distribution infrastructure.
IP-based signal transport using SMPTE ST 2110 and NDI protocols is decentralizing routing and processing functions that previously required dedicated hardware matrices. Regional broadcasters in the United States and Germany are adopting these standards fastest, collapsing the distinction between production switchers and distribution processors. This shift enables facility designers to repurpose physical space while reducing dedicated rack-unit counts.
The EU Green Deal's Ecodesign requirements are mandating standby power limits and operational efficiency disclosures that reshape product development roadmaps. Manufacturers serving European broadcast chains must now document carbon footprint metrics and design for circular material recovery. This regulatory pressure favors modular architectures that permit field-upgradable codec cards rather than full-unit replacement.
Live-event producers are consolidating vendor relationships and demanding unified control surfaces that span switching, processing, and distribution functions. Systems integrators in China and the United States are responding with single-source procurement contracts that bundle hardware, configuration, and remote monitoring. This buyer concentration rewards vendors with comprehensive control-system portfolios and penalizes specialized component suppliers lacking integration depth.
Stand-Alone Video Processors Market Segmentation
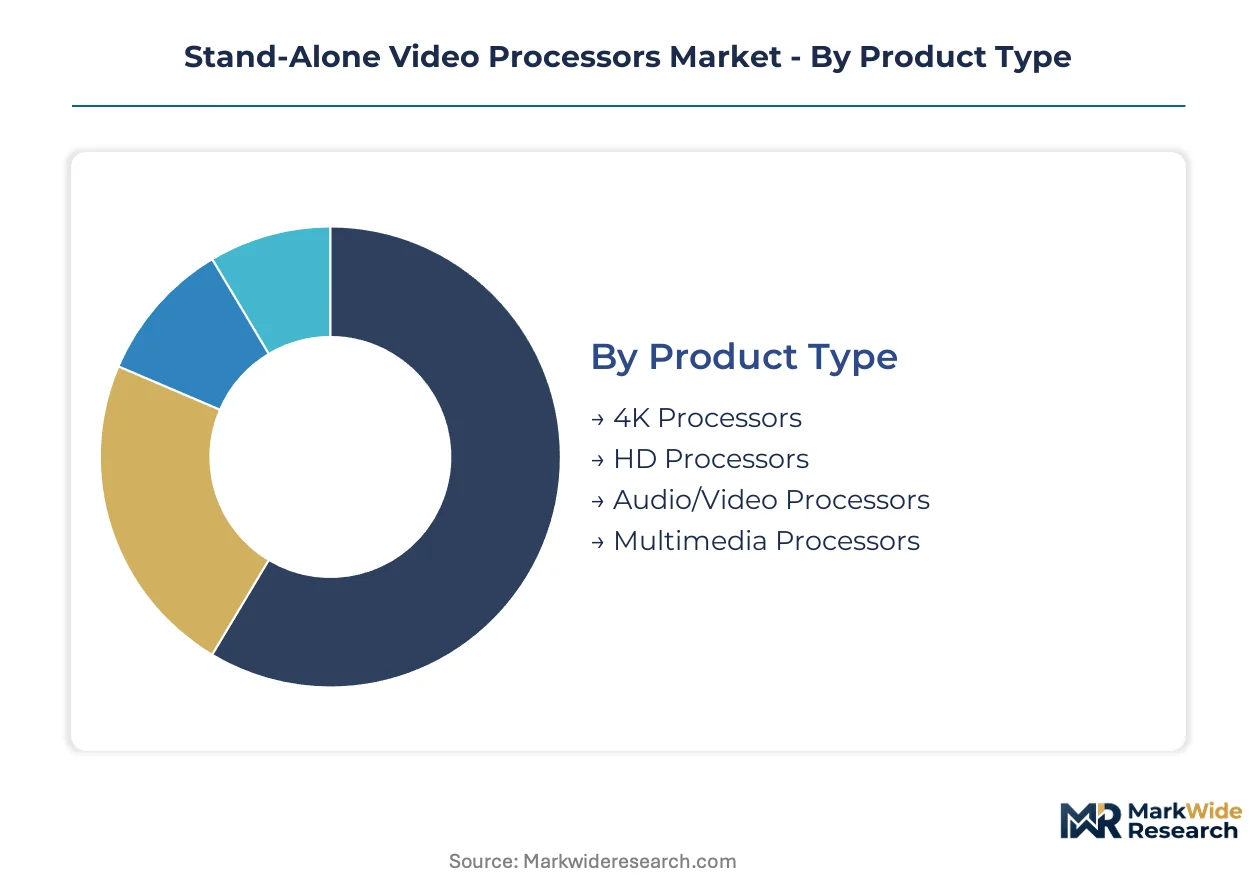
Procurement patterns across stand-alone video processors diverge sharply by resolution tier, signal environment, and institutional buyer type. Replacement cycles and codec transitions create asynchronous growth trajectories that vendors must map against specific infrastructure vintages.
Product Type:
Upgrade timelines stretch from broadcast control rooms refreshing 4K head-ends to schools extending HD equipment life cycles, creating a bifurcated demand landscape.
- 4K Processors:These units ingest 2160p signals with HDR metadata handling and HEVC encoding pipelines. Broadcasters in the United States and cinema chains in China dominate procurement as ATSC 3.0 mandates and multiplex construction force codec-agnostic hardware commitments.
- HD Processors:Legacy 1080p architectures with SDI-centric I/O remain entrenched in cost-sensitive verticals. Secondary education installations and municipal government AV rooms in Germany extend refresh timelines due to constrained capital budgets.
- Audio/Video Processors:Integrated DSP and video scalar functions for unified signal management in conference and worship environments.
- Multimedia Processors:Flexible input aggregation supporting multiple simultaneous sources for museum and experiential retail deployments.
Volume placements concentrate in HD Processors; the faster expansion belongs to 4K Processors.
Application:
Signal transport architecture—SDI, IP, or hybrid—determines processor specification across use cases with divergent latency tolerances.
- Broadcasting:SMPTE ST 2110 and NMOS-compliant units with PTP synchronization for frame-accurate studio environments. European public broadcasters under EU Green Deal procurement rules prioritize energy-efficient 4K-capable models with field-upgradeable codec slots.
- Home Theater:Consumer-facing scalers with HDMI 2.1 and Dolby Vision support for high-end residential installations. Demand clusters in Japan and South Korea where premium display penetration drives accessory processor sales.
- Gaming:Low-latency frame generation and variable refresh rate handling for esports venues and cloud-gaming edge nodes.
- Digital Signage:Networked players with content management system integration for retail and transit advertising networks.
Broadcasting commands the largest installed base; Gaming exhibits the steepest expansion trajectory.
Technology:
Silicon selection—discrete DSP, FPGA, or SoC—varies by required flexibility and unit economics across signal processing paradigms.
- Analog:Legacy composite and component video handling for archive digitization and legacy equipment interfacing. Museums and post-production houses in the United States maintain small-volume procurement for content preservation workflows.
- Digital:Precision digital signal processing with fixed-function pipelines for standardized broadcast formats. Volume production for digital signage and enterprise conferencing concentrates in Chinese manufacturing clusters.
- Hybrid:Analog-digital conversion with simultaneous output generation for transitional infrastructure.
- Streaming:HLS, DASH, and SRT protocol encoding for OTT and remote production workflows.
Digital architectures dominate unit shipments; Streaming technology is climbing the fastest.
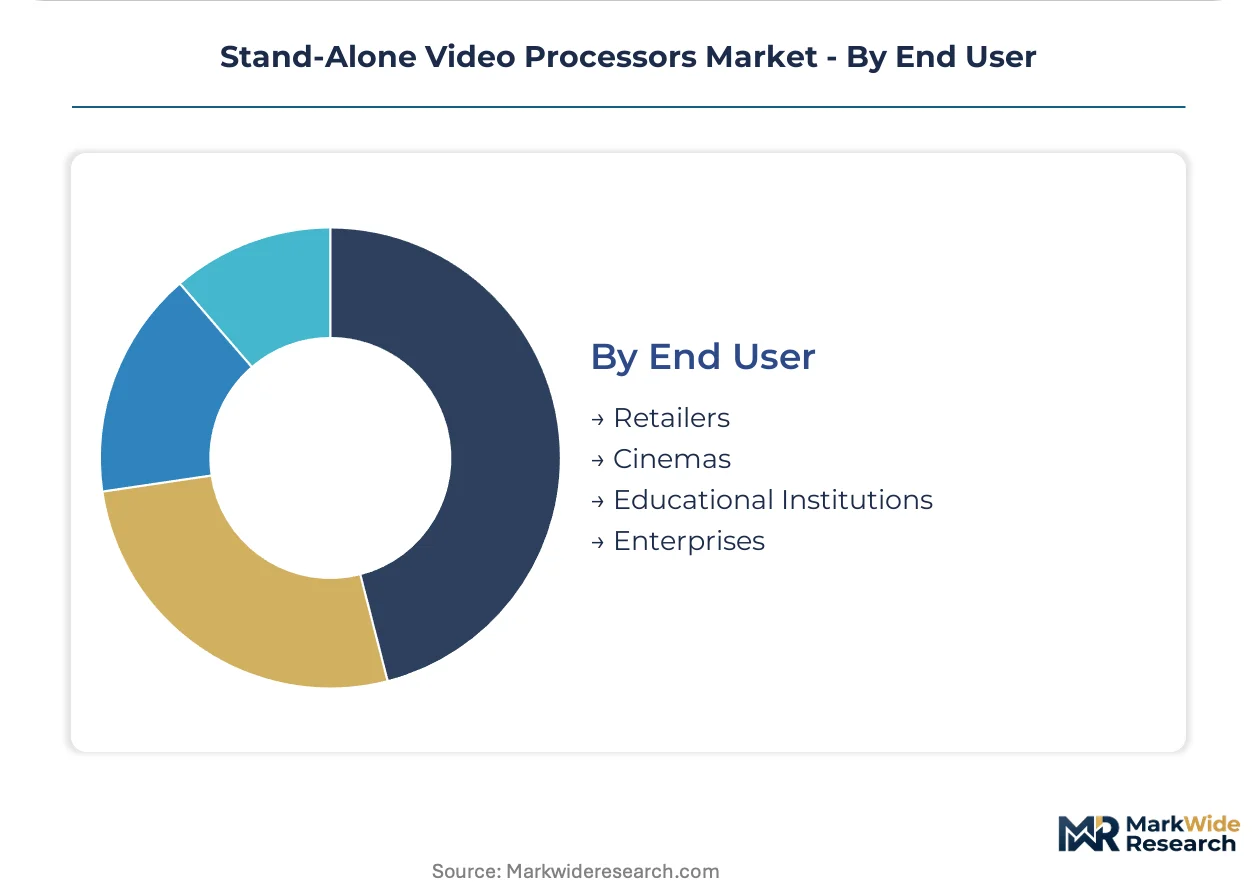
End User:
Institutional procurement cycles and compliance requirements segment buyer behavior across vertical markets with distinct specification priorities.
- Cinemas:DCI-compliant 4K projection processors with encrypted content handling and thermal management for 24/7 operation. Multiplex construction in India and refurbishment waves in Germany drive replacement demand.
- Enterprises:Unified communication-integrated processors with BYOD compatibility and room automation interfaces. Corporate headquarters in the United States and China standardize on IP-based architectures with centralized monitoring.
- Retailers:Networked players with remote content deployment and failure alerting for distributed store networks.
- Educational Institutions:Cost-optimized HD units with extended warranty terms for K-12 and university lecture capture systems.
Educational Institutions anchor volume placements; Cinemas show the sharpest growth acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the densest cluster of stand-alone video processor manufacturing, with contract assembly lines feeding broadcast and cinema supply chains across Asia-Pacific and North America.
United States
ATSC 3.0 transition mandates from the FCC are compelling broadcasters in New York and Los Angeles to replace head-end equipment with 4K-capable units. The FCC's compression and spectrum allocation rules condition codec selection for domestic deployments. Cloud-gaming edge nodes in Northern Virginia's data center corridor are accelerating procurement of low-latency processing hardware.
China
GB standards from the Ministry of Industry and Information Technology enforce domestic video compression requirements that shape both import and local production. Cinema multiplex construction in Shanghai and Beijing is driving demand for DCI-compliant 4K projection processors. The Yangtze River Delta hosts the primary manufacturing concentration for streaming-optimized silicon.
Germany
EU Green Deal Ecodesign requirements are redirecting procurement budgets toward energy-efficient architectures with modular codec cards. Public broadcasters in Berlin and Cologne prioritize field-upgradeable units that reduce full-replacement cycles. Bavaria's industrial automation clusters are piloting processor-as-a-service models for live-event production.
India
Bureau of Indian Standards certification alignment is creating entry pathways for streaming-optimized processor vendors targeting cinema and broadcast verticals. Multiplex construction in Mumbai and Delhi-NCR is accelerating replacement demand for 4K projection systems. The Telangana government's AV infrastructure incentives are attracting systems integrators to Hyderabad's technology corridor.
Japan
METI's digital broadcasting standards and energy efficiency guidelines condition product specifications for professional AV installations. Premium home theater processor demand concentrates in Tokyo and Osaka where high-end display penetration drives accessory sales. Kansai-based broadcast equipment specialists are integrating AI-assisted upscaling into traditional scalar pipelines.
Stand-Alone Video Processors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across control-system integration depth and codec-agnostic architecture flexibility. The vendor base stratifies between comprehensive platform providers and specialized component suppliers. Three archetypes dominate: vertically integrated control-system houses, silicon-layer codec specialists, and streaming-technology pure-plays. Capacity expansion and strategic partnerships represent the dominant competitive vectors as firms seek to bridge hardware and cloud-gaming infrastructure requirements.
Within the control-system tier, Crestron Electronics, Inc. and Extron Electronics occupy positions that exemplify premium-channel anchoring in enterprise and educational verticals. NXP Semiconductors N.V. represents the component-layer archetype, supplying codec silicon downstream to multiple OEM brands. These three entities illustrate how competitive positioning fragments across integration depth rather than concentrating around identical capability stacks.
| Leading Market Players |
|---|
| Crestron Electronics, Inc. |
| InFocus Corporation |
| Extron Electronics |
| NXP Semiconductors N.V. |
| Morpho, Inc. |
| Ateme |
| Vantrix Corporation |
| Synamedia |
| The MathWorks, Inc. |
| Others |
Value Network & Pricing Analysis
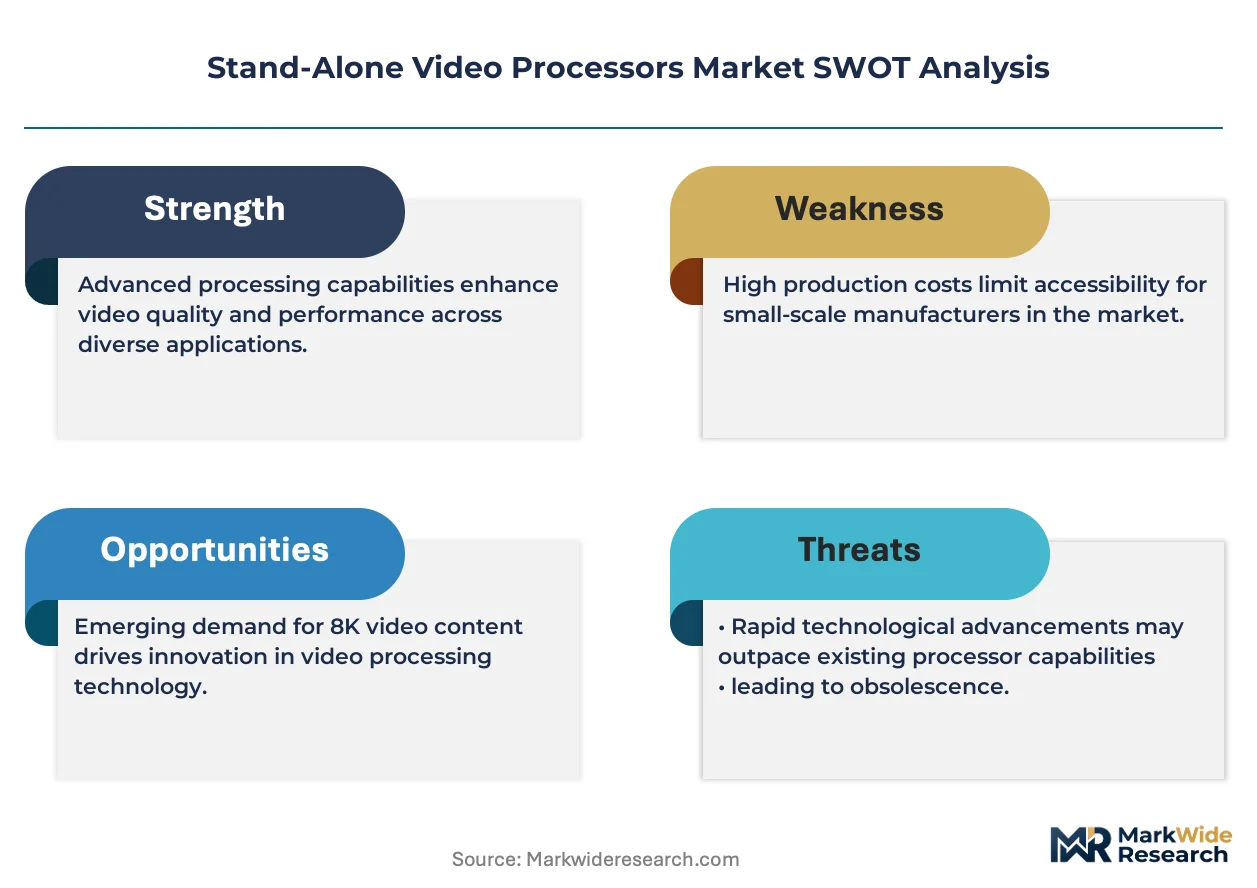
Codec-agnostic architecture certification bifurcates procurement tiers between broadcast-grade 4K units and cost-optimized HD installations, with premium pricing anchored to ATSC 3.0 compliance and EU Ecodesign thresholds while commodity supply chains concentrate in Shenzhen manufacturing clusters serving digital signage and education verticals.
Pricing Analysis
Throughput-based pricing anchors enterprise broadcast contracts, with 4K processor vendors charging per encoded stream capacity rather than per-unit hardware cost. Three-tier pricing structure across premium, standard, and economy levels separates DCI-compliant cinema processors from modular broadcast units and fixed-function HD scalers. Pricing pressure stems from HEVC patent pool fragmentation extending vendor negotiation timelines. Educational institutions exhibit highest price sensitivity, while cloud-gaming hyperscalers prioritize latency guarantees over unit cost.
Supply Chain Analysis
Common Criteria and FIPS 140-2 certification gating restricts government procurement to validated firmware vendors, elongating sales cycles by 12-18 months for defense-adjacent installations. Advanced codec DSP and FPGA fabrication concentrates in Taiwan, South Korea, and the United States, drawing from silicon wafer supply and rare earth substrate inputs. Single-source vulnerability at foundry allocation points threatens OEM delivery schedules. Distribution runs through Crestron and Extron channel partners in North America, direct systems integrator relationships in Germany, and contract manufacturers in the Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal Ecodesign mandates are compressing margins for legacy architecture vendors unable to field-upgrade codec cards, forcing consolidation toward modular platform providers with circular material recovery capabilities.
For Market Incumbents: Anticipate codec licensing complexity intensifying margin pressure by negotiating pooled patent access through MPEG-LA and Access Advance consortiums. Backward integration into FPGA firmware development reduces foundry allocation vulnerability. Energy-efficiency certification investment defends European public broadcaster relationships against emerging modular competitors. For New Entrants and Emerging Players: Begin with India's cinema multiplex construction wave, where Bureau of Indian Standards alignment creates lower certification barriers than FCC or ETSI jurisdictions. Streaming-optimized processor-as-a-service models for live-event producers in Bavaria offer white-space entry with unbundled capital expenditure positioning. For Investors and Strategic Acquirers: Re-rating potential sits with streaming-technology pure-plays given cloud-gaming infrastructure buildout acceleration across Northern Virginia and Shanghai data center corridors. Long-term viability favors vendors bridging SMPTE ST 2110 IP transport with AI-assisted upscaling inference engines. Monitor SRT protocol adoption rates in remote production workflows as inflection indicator for premium tier demand.| Strategic Initiative | Industry Significance |
|---|---|
| Codec-Agnostic Architecture Development | HEVC, VVC, and AV1 support future-proofs broadcast processor deployments against ATSC 3.0 transitions. |
| AI-Assisted Upscaling Integration | Machine learning inference engines differentiate premium tiers for Kansai-based broadcast equipment specialists. |
| Processor-as-a-Service Pilot Programs | Subscription models unbundle capital expenditure for live-event producers in Germany and the United States. |
| EU Ecodesign Compliance Investment | Modular codec cards and circular material recovery satisfy EU Green Deal procurement requirements. |
| India Market Entry Alignment | Bureau of Indian Standards certification opens cinema and broadcast verticals in Mumbai and Delhi-NCR. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with broadcast engineering directors, systems integrators, cinema technology procurement managers, and semiconductor foundry account executives. FCC rulemaking dockets, ETSI interoperability specifications, MIIT GB standard publications, and Shenzhen customs export declarations provided triangulation against bottom-up shipment estimates and top-down market sizing.
Shipment volume reconciliation against hyperscaler capex disclosures and cinema projection equipment import databases validated segment-level assumptions across the analysis window. Resolution tier, signal environment, and end-user vertical dimensions structured the forecast framework, with CAGRs derived from replacement cycle timing and codec transition velocity. Cloud-gaming edge node deployment schedules and ATSC 3.0 mandate compliance deadlines informed near-term demand inflection points.
Underlying measurement precision varies by segment; 4K broadcast processor shipments carry tighter precision than analog archive digitization niches. Forecasts reflect documented assumptions regarding silicon foundry capacity allocation and patent pool licensing terms. A model refresh is warranted upon material change in FCC spectrum allocation rules or EU Ecodesign standby power threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Resist Strip System Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
Embedded Controllers Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market
Electronic Systems and Devices
Electronic-Nose Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
Hi-Fi System Market
Electronic Systems and Devices
Global Bioelectronics Market
Electronic Systems and Devices
Radio Dot System (RDS) Market
Electronic Systems and Devices
Vacuum Pulse System Market
Electronic Systems and Devices
Global Automotive Electronic Brake System Market
Electronic Systems and Devices
Electronic Tongue Market
Electronic Systems and Devices
System on Module (Som) Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
AI Computing Hardware Market