
 Liquid Filter Bags Market | 2026-2036
Liquid Filter Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Filter Bags Market Foresight
Polymer engineering talent scarcity is bifurcating the competitive landscape into technology-heavy specialists and volume-driven commoditized suppliers. Pall Corporation leverages its membrane science heritage to dominate high-purity pharmaceutical applications. Donaldson Company, Inc. anchors its position through backward integration into nonwoven media production. Parker Hannifin Corporation competes across diversified industrial channels with standardized bag platforms.
Liquid filter bags are cylindrical filtration media constructed from woven or nonwoven synthetic fibers, typically rated from 1 to 200 microns, designed to remove particulate contaminants from process fluids in pressurized housing systems. Manufacturing employs needle-punch, melt-blown, or woven monofilament processes depending on chemical compatibility and temperature requirements. Polypropylene formulations lead volume due to broad chemical resistance and cost efficiency in water treatment and chemical processing applications. Pharmaceutical-grade polyester bags command premium positioning owing to extractables testing and FDA compliance documentation requirements. Nonwoven segments are gaining structural share in food and beverage applications where single-use protocols reduce cross-contamination risk.
EPA effluent limitation guidelines and EU REACH chemical compliance frameworks are elevating product certification requirements for bag suppliers seeking industrial market access. FDA food contact substance notifications and 3-A sanitary standards govern pharmaceutical and dairy filtration deployments respectively. ISO 9001 quality management certification has become a baseline procurement filter among multinational OEMs and distributors. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across North American and European jurisdictions, as these chemicals historically enhanced media durability in demanding process environments.
Market Dynamics
Stricter effluent standards under EPA and EU frameworks are forcing chemical processors to upgrade filtration infrastructure faster than replacement cycles would naturally allow, compressing demand timing and elevating certification requirements for bag suppliers.
Growth Catalysts
- REACH chemical compliance:EU manufacturers must install higher-efficiency filtration to meet discharge protocols, creating pull for polypropylene and polyester media with documented extractables profiles.
- China's industrial water corridors:Local MEE enforcement in Jiangsu and Shandong provinces is retrofitting municipal and chemical treatment plants with 1-10 micron rated bag systems.
- Single-use protocols:Food and beverage processors are abandoning cleanable cartridge systems for disposable nonwoven bags to eliminate cross-contamination risk in dairy and brewing applications.
Market Restraints
- Polypropylene resin volatility:Propylene feedstock price swings directly compress bag margins, especially for commoditized 25-100 micron water treatment specifications.
- Needle-punch media concentration:Three nonwoven producers in Germany and the United States control pharmaceutical-grade polyester supply, creating bottleneck risk for FDA-compliant bag converters.
- Membrane substitution:Hollow-fiber ultrafiltration modules are displacing 1-5 micron bags in high-purity pharmaceutical water systems where endotoxin removal is critical.
Strategic Opportunities
- India's pharmaceutical expansion:CDSCO is aligning with FDA inspection protocols, creating demand for documented polyester bags in active pharmaceutical ingredient manufacturing clusters around Hyderabad and Ahmedabad.
- PFAS-free media development:ECHA restrictions on per- and polyfluoroalkyl substances are opening white space for fluorine-free surface treatments in chemical processing applications.
- Direct OEM contracting:Filter housing manufacturers are bypassing distribution to specify captive bag supply, rewarding converters with in-house nonwoven production capabilities.
Industry Challenges
- Polymer engineering talent scarcity:Formulation chemists with melt-blown and nanofiber process expertise are concentrated at membrane specialists, forcing bag converters to compete for limited talent pools.
- FDA 510(k) documentation timelines:Pharmaceutical-grade bag introductions face 12-18 month validation cycles for extractables and compatibility testing, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Filter Bags Market |
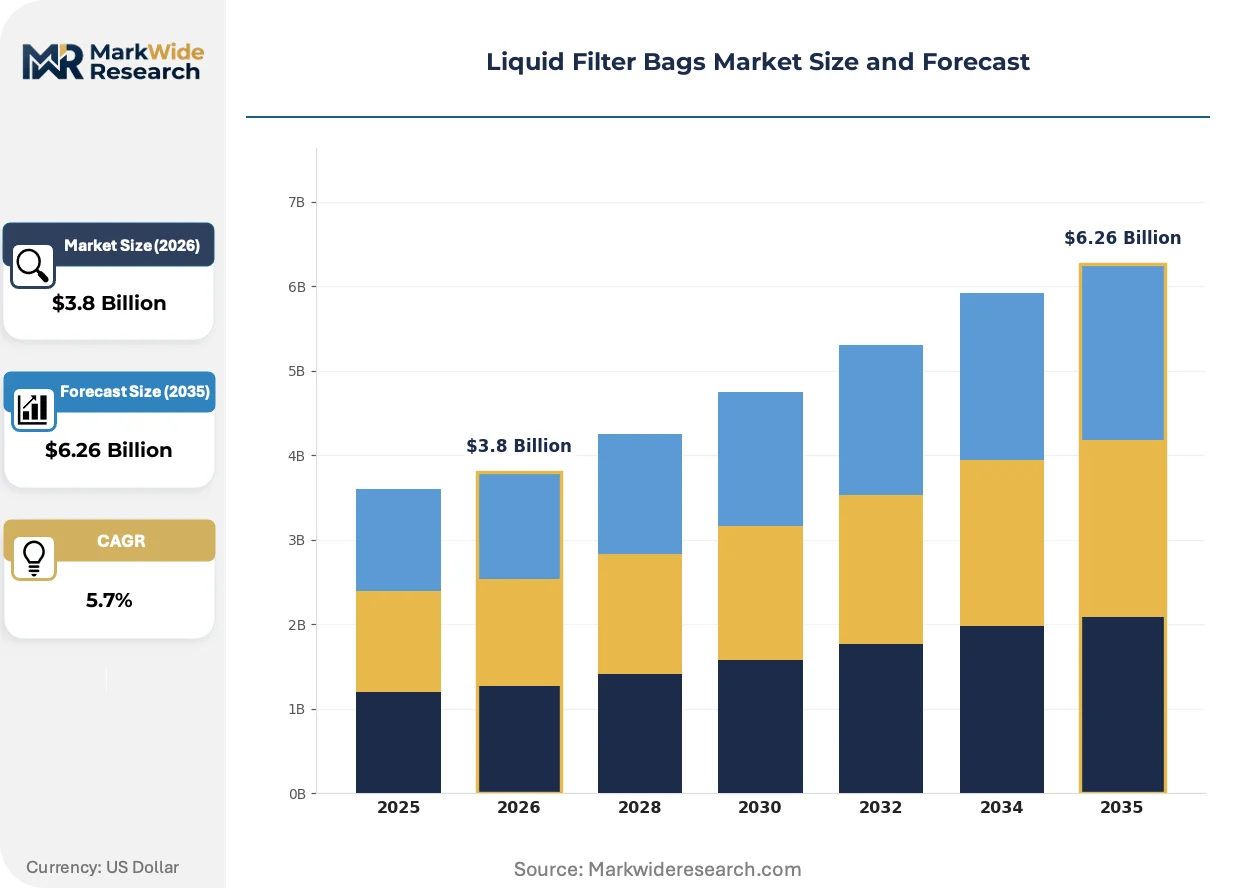
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polypropylene, Nylon, Nonwoven Application: Pharmaceutical, Water Treatment, Food & Beverage, Chemical Processing End User: Manufacturers, Distributors, OEMs, Retailers Dimension: Standard Size, Custom Size, Microfiltration, Nanofiltration |
| Companies Covered | 3M, Pentair, Donaldson Company, Inc., Amazon Filters, Filpro Corporation, Parker Hannifin Corporation, Pall Corporation, Sefar, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Filter Bags Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are converging to reshape competitive positioning around media formulation expertise rather than conversion capacity alone.
Multilayer melt-blown nanofiber media is fragmenting the traditional needle-punch dominance in fine-filtration applications. Pharmaceutical and electronics chemical processors in Germany and Japan are specifying gradient-density structures for 0.5-2 micron retention. This technology is fragmenting the supplier base into specialists with captive nanofiber lines versus commodity converters dependent on merchant supply.
EU REACH Annex XVII restrictions on perfluorinated compounds are forcing reformulation of surface treatments historically used for oleophobic bag performance. Chemical processors in Belgium and the Netherlands are qualifying plasma-treated polyester alternatives. Bag suppliers with in-house fluorine-free coating capabilities are capturing specification authority from housing OEMs.
Consolidated chemical processors are unbundling filter procurement from maintenance contracts, creating direct material sourcing relationships. Large water treatment operators in the United States are establishing approved vendor lists with technical qualification requirements. This pattern concentrates volume with converters offering batch traceability and ISO 9001 documentation rather than distribution intermediaries.
Liquid Filter Bags Market Segmentation
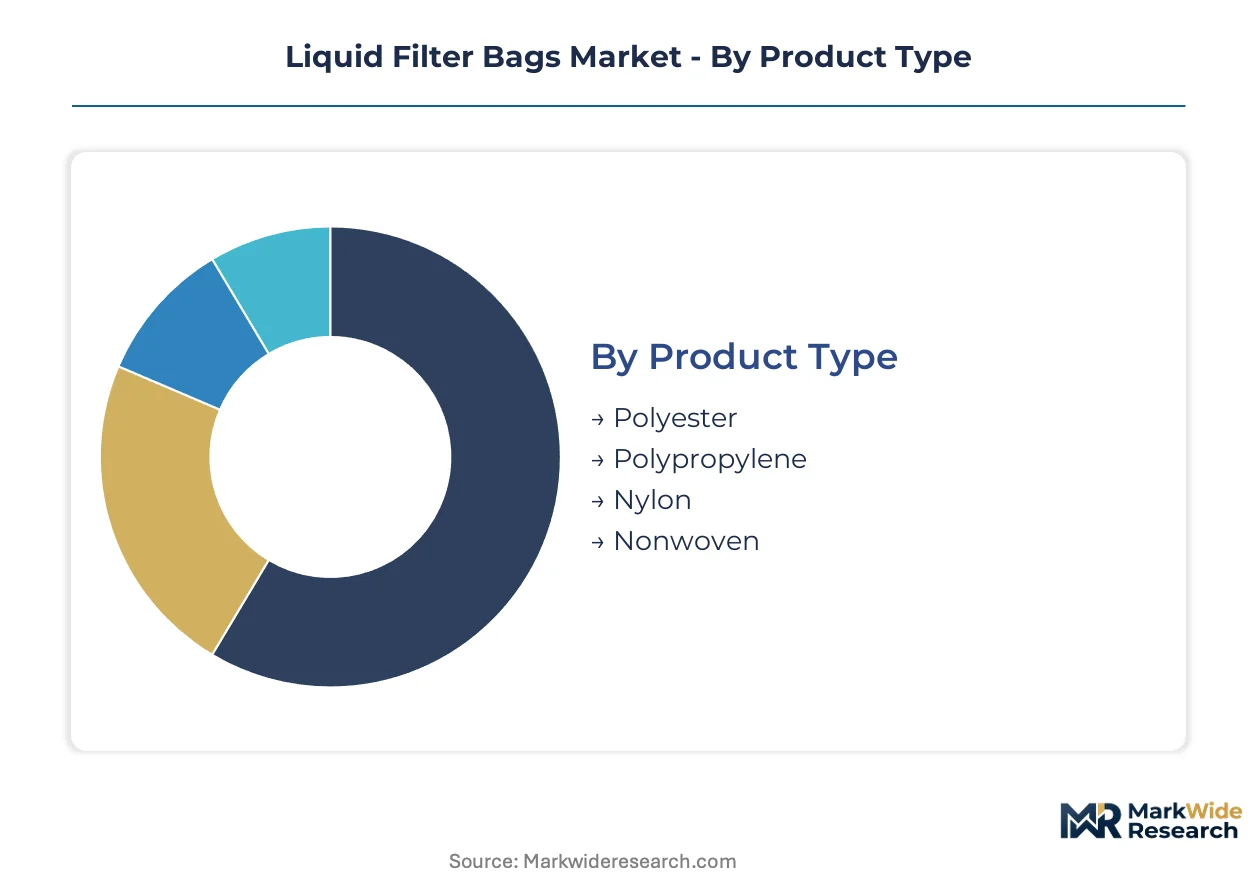
Filtration performance requirements diverge sharply across chemical compatibility, purity standards, and contamination risk protocols. Segment selection determines both procurement economics and regulatory compliance pathways for end-users.
Product Type:
Membrane substitution pressures concentrate most intensely on commodity polymer grades, while specialty formulations defend position through extractables documentation and FDA compliance certification.
- Polyester:Woven and felted polyethylene terephthalate media deliver thermal stability to 150°C and broad chemical resistance for pharmaceutical solvent filtration. Demand clusters in FDA-regulated active pharmaceutical ingredient manufacturing where extractables testing documentation is mandatory for 510(k) submissions.
- Polypropylene:Needle-punched and melt-blown polyolefin structures dominate volume through cost efficiency and compatibility with acids, alkalis, and aqueous systems. Water treatment corridors in China's Jiangsu province and chemical processing facilities in Germany's Rhine-Ruhr region are retrofitting with 1-50 micron rated polypropylene bags under stricter MEE and REACH discharge protocols.
- Nylon:Polyamide monofilament and multifilament constructions offer superior abrasion resistance for hydrocarbon filtration and aggressive solvent applications. Hydrocarbon processing in Texas and Louisiana specifies nylon for lubricant and fuel filtration where mechanical durability outweighs chemical resistance trade-offs.
- Nonwoven:Spunbond and melt-blown synthetic fiber matrices enable single-use protocols in food and beverage applications. Dairy processors in Wisconsin and brewing operations in Colorado are abandoning cleanable cartridge systems for disposable nonwoven bags to eliminate cross-contamination risk.
Polypropylene retains volume leadership; nonwoven holds the steepest expansion curve.
Application:
Purity thresholds and contamination consequences create tiered procurement economics across end-use sectors.
- Pharmaceutical:Polyester and polypropylene bags rated 0.5-10 micron with documented extractables profiles serve sterile filtration and active pharmaceutical ingredient processing. CDSCO alignment with FDA inspection protocols in India's Hyderabad and Ahmedabad clusters is accelerating demand for certified media.
- Water Treatment:Municipal and industrial facilities deploy 1-200 micron polypropylene bags for sediment removal and pre-filtration. China's MEE enforcement in Shandong province is retrofitting treatment plants with fine-rated bag systems.
- Food & Beverage:Nonwoven polypropylene bags with FDA food contact substance notifications filter dairy, brewing, and edible oil processes. Single-use protocols are displacing cleanable systems where allergen cross-contamination liability exceeds consumable costs.
- Chemical Processing:Chemical-resistant polypropylene and nylon media handle aggressive process streams in Germany's chemical parks and US Gulf Coast petrochemical complexes. REACH and EPA effluent guidelines are forcing faster filtration infrastructure upgrades than natural replacement cycles would allow.
Water treatment commands the largest installed base; pharmaceutical generates the highest margin per unit.
End User:
Procurement authority is shifting from maintenance contractors to direct material sourcing relationships with technical qualification requirements.
- Manufacturers:Chemical, pharmaceutical, and food processors specify bags directly based on process compatibility and regulatory documentation needs. Large operators are establishing approved vendor lists with ISO 9001 and batch traceability requirements.
- Distributors:Industrial supply intermediaries serve fragmented small and mid-size processors with standardized inventory. Margin compression from direct OEM contracting is forcing distributors to add technical services or consolidate.
- OEMs:Filter housing manufacturers increasingly specify captive bag supply through backward integration or exclusive converter partnerships. Housing OEMs in Germany and the United States are bypassing distribution to control specification authority.
- Retailers:Limited role in industrial liquid filtration; occasional presence in residential and light commercial water treatment accessories.
Manufacturers represent the dominant demand channel; OEMs are capturing specification authority fastest.
Dimension:
Filtration scale and housing compatibility create distinct procurement and performance categories.
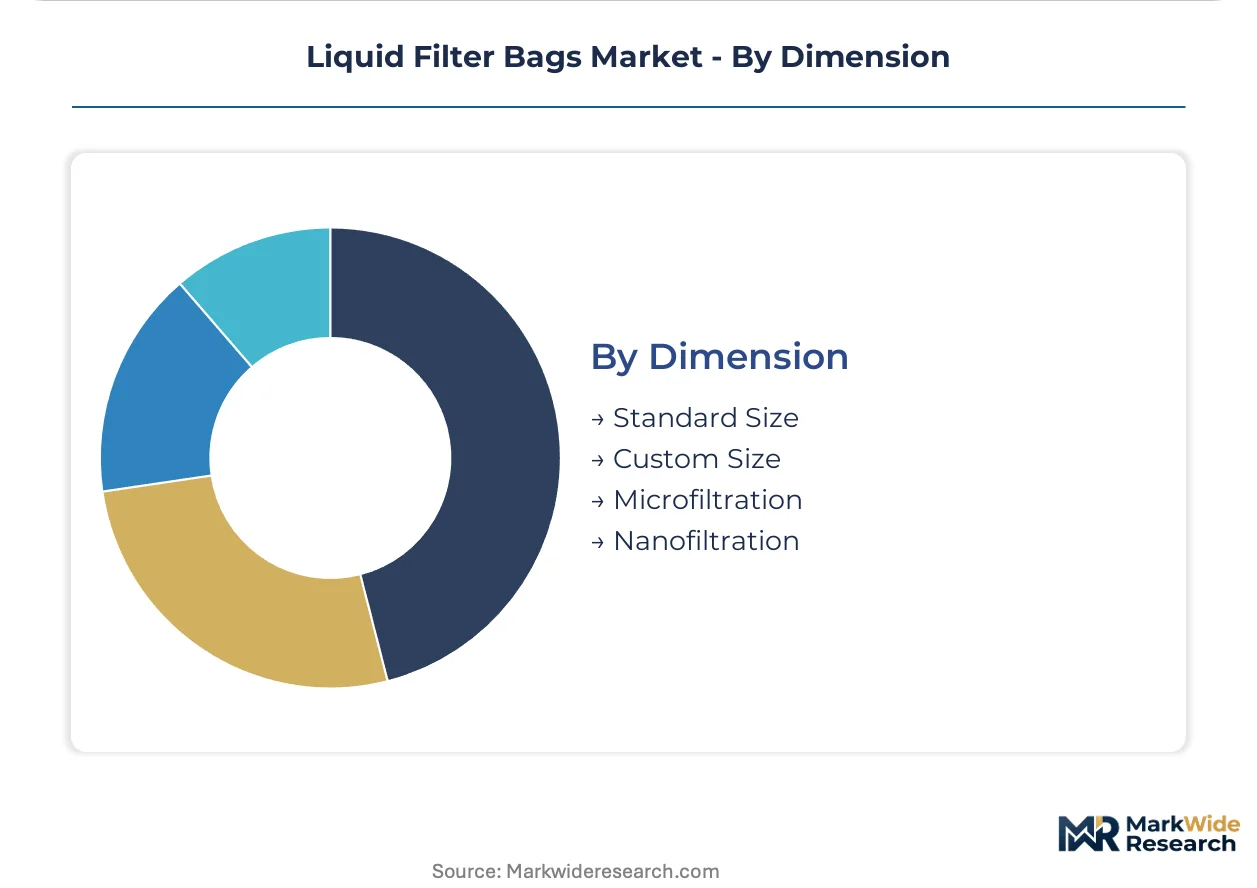
- Standard Size:Industry-dimensioned bags (7"x16", 7"x32", 4"x9") fit common housing specifications across water treatment and chemical processing. Inventory efficiency and interchangeability drive procurement for high-volume applications.
- Custom Size:Proprietary dimensions engineered for specific housing geometries or process constraints in pharmaceutical and specialty chemical applications. Tooling costs and minimum order quantities segment this tier toward larger processors.
- Microfiltration:0.1-10 micron retention ratings for bacteria and fine particulate removal in pharmaceutical water systems and electronics chemical processing. Hollow-fiber membrane modules are displacing 1-5 micron bags where endotoxin removal is critical.
- Nanofiltration:Sub-micron and molecular weight cut-off applications increasingly served by membrane technology rather than depth filtration media. Bag technology faces structural substitution pressure below 0.1 micron.
Standard size maintains procurement volume dominance; custom size captures the highest value per filtration event.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss pharmaceutical-grade polyester supply chains, while Chinese polypropylene converters compete on volume in water treatment corridors where local MEE enforcement drives retrofit demand.
United States
Chemical processors along the Gulf Coast are expanding filtration capacity ahead of EPA effluent limitation guideline deadlines. FDA 510(k) documentation requirements for pharmaceutical-grade bags create regulatory barriers for imported media. Houston and Louisiana petrochemical clusters specify nylon bags for hydrocarbon filtration where mechanical durability outweighs chemical resistance trade-offs.
Germany
Rhine-Ruhr chemical parks are retrofitting with 1-50 micron rated polypropylene bags under stricter REACH discharge protocols. ECHA restrictions on perfluorinated compounds force reformulation of surface treatments historically used for oleophobic performance. Three nonwoven producers in Baden-Württemberg and Bavaria control pharmaceutical-grade polyester supply, creating bottleneck risk for FDA-compliant bag converters.
China
Industrial water treatment corridors in Jiangsu and Shandong provinces are retrofitting municipal and chemical plants with fine-rated bag systems. Local MEE enforcement tightens discharge protocols, pulling demand for polypropylene media with documented performance profiles. Yangtze River Delta manufacturing clusters face propylene feedstock price volatility that compresses margins for commoditized 25-100 micron specifications.
India
Active pharmaceutical ingredient manufacturing clusters around Hyderabad and Ahmedabad are accelerating demand for certified polyester bags. CDSCO alignment with FDA inspection protocols elevates extractables documentation requirements. Domestic converters compete with imported media on cost while building ISO 9001 quality management capabilities for multinational OEM procurement.
Japan
Electronics chemical processors in the Kanto and Kansai regions specify gradient-density multilayer structures for sub-micron retention. METI-supported nanofiber development programs fragment the supplier base into specialists with captive production lines. Osaka-based housing OEMs increasingly specify captive bag supply through backward integration partnerships.
Liquid Filter Bags Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with membrane science specialists commanding premium positioning in pharmaceutical applications while volume-driven converters compete on polypropylene bag specifications. The competitive structure fragments across three strategic tiers: technology-heavy specialists with in-house nonwoven production, diversified industrial conglomerates with standardized platforms, and regional converters serving fragmented maintenance channels. Dominant competitive moves include backward integration into media production and direct OEM contracting that bypasses distribution intermediaries.
Within the technology-specialist tier, Pall Corporation and Donaldson Company, Inc. exemplify divergent strategic positions. Pall leverages membrane science heritage to anchor high-purity pharmaceutical applications where extractables documentation commands specification authority. Donaldson anchors industrial positioning through upstream control over nonwoven media production, insulating margin structures from merchant supply volatility. Parker Hannifin Corporation occupies a diversified industrial channel position, competing across standardized bag platforms that serve fragmented procurement relationships. These three entities collectively illustrate how polymer engineering capabilities and regulatory certification depth determine competitive positioning in a market bifurcating between premium specialty and commoditized volume segments.
| Leading Market Players |
|---|
| 3M |
| Pentair |
| Donaldson Company, Inc. |
| Amazon Filters |
| Filpro Corporation |
| Parker Hannifin Corporation |
| Pall Corporation |
| Sefar |
| Eaton Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between German nonwoven producers and pharmaceutical bag converters lock in both polypropylene resin supply and price visibility across multi-year horizons, insulating specialist tier players from propylene feedstock volatility that compresses commoditized water treatment margins.
Pricing Analysis
Configured-to-order pricing for FDA-compliant polyester bags with extractables documentation commands 40-60% premiums over standard 25-100 micron polypropylene specifications for municipal water treatment. Three-tier pricing structure across pharmaceutical-grade certified, industrial-standard, and economy bulk tiers segments buyer archetypes by contamination risk tolerance. Cost compression in the economy tier is intensifying because Chinese converters are absorbing propylene volatility to defend volume share in Jiangsu province retrofits. Municipal water operators exhibit highest price sensitivity; sterile pharmaceutical processors show least sensitivity due to 510(k) validation costs dominating procurement economics.
Supply Chain Analysis
China, Germany, and the United States anchor liquid filter bag manufacturing, with China dominating polypropylene volume conversion and Germany controlling pharmaceutical-grade polyester nonwoven supply. Raw material dependencies rest on propylene monomer from Gulf Coast petrochemical complexes, melt-blown nanofiber equipment from Japanese specialists, and FDA-compliant polyester fiber from Baden-Württemberg producers. Single-source vulnerability concentrates in pharmaceutical-grade needle-punch media where three German suppliers control extractables-certified output. Distribution runs through direct OEM contracting that bypasses traditional industrial supply intermediaries, with housing manufacturers specifying captive bag supply to capture specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for extractables validation and filter housing compatibility testing are expanding faster than hardware unit sales, creating recurring revenue pools that pharmaceutical-grade suppliers are capturing through embedded service agreements.
For Market Incumbents: Secure backward integration into nonwoven media production to insulate margin structures from German pharmaceutical-grade polyester bottlenecks. Defend specification authority by embedding extractables documentation services within OEM housing partnerships, countering hollow-fiber membrane substitution in 1-5 micron pharmaceutical water systems through gradient-density nanofiber differentiation. For New Entrants and Emerging Players: Lead with fluorine-free surface treatment capabilities targeting Belgium and Netherlands chemical processors facing ECHA perfluorinated compound restrictions. India's CDSCO-aligned pharmaceutical clusters around Hyderabad offer the most penetrable geography for certified polyester bag supply, with ISO 9001 documentation capabilities serving as the critical go-to-market credential for multinational OEM procurement lists. For Investors and Strategic Acquirers: Nanofiber process specialists with captive melt-blown production lines represent the priority acquisition archetype, as their technology moats defend against commodity substitution. Long-term viability hinges on regulatory certification depth rather than conversion scale alone. Watch FDA 510(k) validation timeline compression as the signal indicating inflection toward service-integrated supplier models.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nonwoven Media | Captive polypropylene production insulates margins from propylene volatility in Chinese water treatment corridors. |
| PFAS-Free Surface Treatment Development | ECHA REACH Annex XVII compliance opens specification authority with Belgian and Dutch chemical processors. |
| Direct OEM Contracting Bypass | Housing manufacturers in Germany and Japan are consolidating bag supply through exclusive converter partnerships. |
| Extractables Documentation Services | Embedded validation capabilities capture recurring revenue from pharmaceutical 510(k) submission requirements. |
| Gradient-Density Nanofiber Capacity | Multilayer melt-blown production lines defend against hollow-fiber substitution in sub-2 micron retention applications. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at chemical processing facilities, procurement leads at filter housing OEMs, aftermarket service heads at industrial distributors, and regulatory affairs directors at pharmaceutical manufacturers, then refined against customs trade data, EPA effluent guideline filings, SEC 10-K disclosures from diversified filtration conglomerates, and MEE enforcement records from Jiangsu and Shandong provinces. Bottom-up segment sizing triangulated with top-down macro validation across polymer feedstock demand models.
Variance decomposition across product type, application purity tier, end-user procurement channel, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by average selling price evolution, with propylene feedstock cost curves and FDA 510(k) approval velocity serving as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained MEE enforcement intensity, REACH chemical compliance trajectory, or membrane substitution pace in pharmaceutical water systems would require recalibration. Forecasts reflect assumptions about regulatory continuity and polymer engineering talent availability. Recalibration cycles align with material shifts in EPA effluent guideline deadlines and ECHA perfluorinated substance restriction implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Fiberglass Filters Market
Filters
Global Industrial Filters Market
Filters
Industrial Filter Paper Market
Filters
US Baghouse Filters Market
Filters
Global Filter Market
Filters
Fabric Filters Market
Filters
Industrial Air Filtration Market
Filters
Global Tangential Flow Filtration Market
Filters
North America Gas Filtration Media Market
Filters
Global Baghouse Filters Market
Filters
Nonwoven Air Conditioning Filter Market
Filters
Anti-Microbial Filter Market
Filters
Global High Temperature Filters Market
Filters
High Purity Chemical Filters Market
Filters
Residential Filters Market
Filters
Filtration and Separation Market