
 Global Methyl Methacrylate (MMA) Adhesive Market | 2026-2036
Global Methyl Methacrylate (MMA) Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Global Methyl Methacrylate (MMA) Adhesive Market Foresight
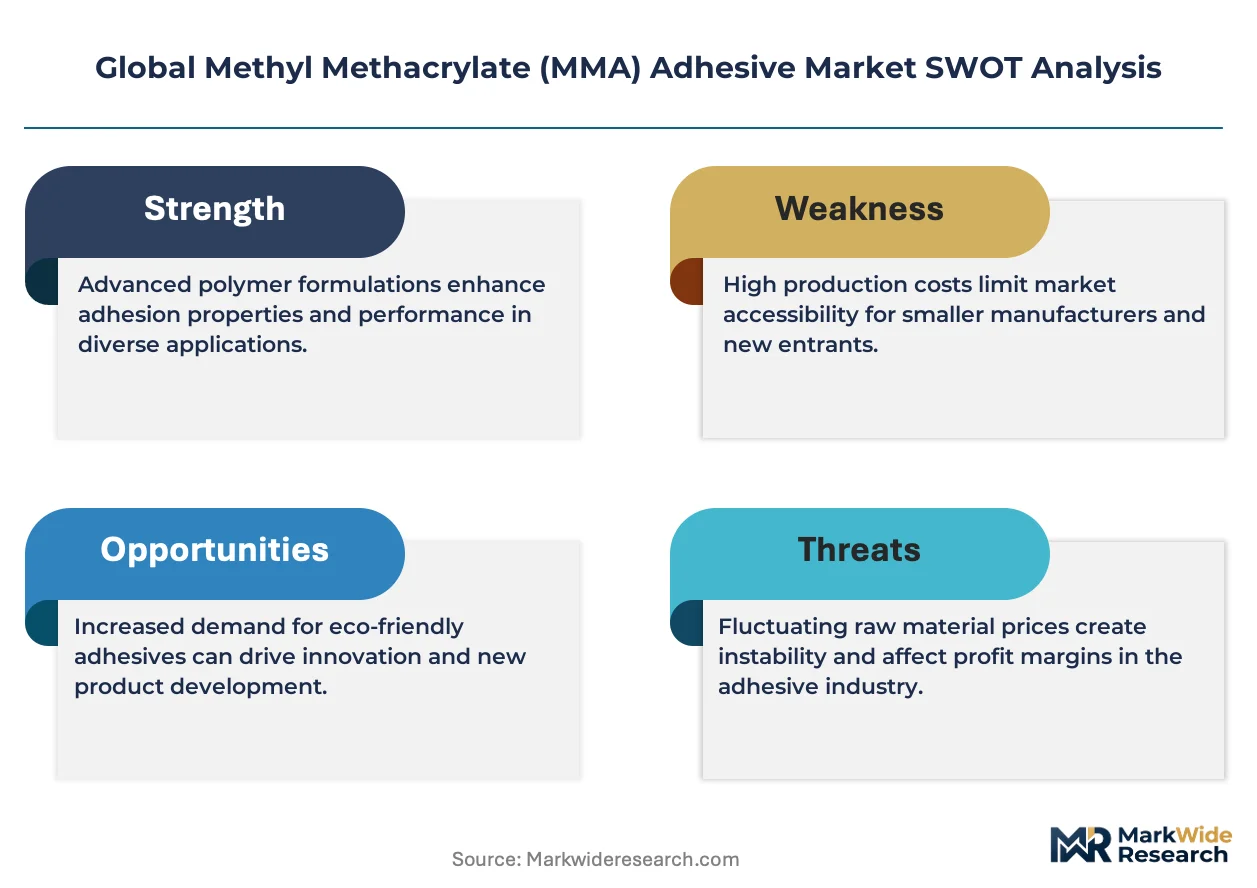
The premium structural adhesive tier is consolidating around aerospace-grade certification and automated dispensing compatibility, while commodity instant adhesives face margin compression from Asian manufacturing scale. Henkel AG & Co. KGaA leverages its reactive hot melt portfolio to dominate European transportation OEM channels. Sika AG anchors its position through deep vertical integration into construction-grade MMA formulations. Arkema specializes in UV curing systems for electronics assemblies, competing on cure-speed specifications rather than price.
Methyl methacrylate adhesive comprises acrylic monomer formulations that polymerize through free-radical initiation, achieving tensile shear strengths exceeding 25 MPa on engineered metals and composites. Industrial applications center on replacing mechanical fasteners in assemblies where vibration resistance, fatigue durability, and weight reduction converge. Structural adhesives command the deepest margin pools due to qualification barriers in aerospace and wind energy certification protocols. Water-based formulation technology is displacing solvent systems in European electronics assemblies as environmental compliance tightens. Two-component reactive systems lead transportation equipment bonding for their controlled cure kinetics and gap-filling tolerance.
EPA VOC regulations in the United States restrict solvent-based adhesive deployment in industrial settings, while REACH compliance in Europe mandates substance disclosure across supply chains. China's GB standards on volatile organic compound emissions from adhesive products are tightening manufacturing license requirements in Shandong and Jiangsu provinces. Japan's METI circular economy directives are pressuring OEMs to specify recyclable bonding systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
Automotive OEMs in Germany and China are aggressively expanding bonded assembly lines, forcing adhesive suppliers to synchronize cure kinetics with robotic dispensing speeds while navigating divergent VOC regimes across manufacturing jurisdictions.
Growth Catalysts
- REACH solvent restrictions:European electronics manufacturers are accelerating water-based and reactive technology migrations to maintain manufacturing licenses, creating captive demand for compliant formulations.
- Wind turbine blade certification:Aerospace-grade structural adhesives are penetrating renewable energy applications as blade lengths exceed 80 meters and mechanical fastening becomes impractical.
- Shandong-Jiangsu manufacturing clusters:China's tightening GB standards on volatile organic compound emissions are consolidating production capacity among licensed domestic suppliers serving coastal export zones.
Market Restraints
- Methyl methacrylate monomer volatility:Feedstock price swings tied to acetone cyanohydrin supply disruptions compress formulation margins during contract renegotiation windows.
- Two-component dispensing complexity:Transportation OEMs face capital intensity in retrofitting legacy mechanical fastening lines with meter-mix-dispense equipment and in-process cure monitoring.
- Epoxy structural substitution:Wind energy OEMs in Denmark and Spain are qualifying hybrid epoxy-urethane systems for blade root bonding, pressuring MMA share in renewable applications.
Strategic Opportunities
- India automotive assembly:Tamil Nadu and Maharashtra manufacturing corridors are underpenetrated for structural bonding as domestic OEMs transition from welded to hybrid-joined body-in-white architectures.
- UV-LED convergence:Electronics assemblers in South Korea are piloting dual-cure systems combining free-radical initiation with cationic secondary cure for shadow-area reliability.
- Japan METI circular economy mandates:OEM specification of debondable or recyclable adhesive systems is creating first-mover advantage for suppliers with reversible chemistry portfolios.
Industry Challenges
- Aerospace qualification timelines:OEMs face 18-36 month certification cycles for new structural adhesive grades, locking inventory positions and freezing formulation agility during specification windows.
- Automation integration friction:Mid-tier adhesive suppliers lack embedded process engineers to troubleshoot dispensing robotics on customer assembly floors, ceding specification control to integrated system vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Methyl Methacrylate (MMA) Adhesive Market |
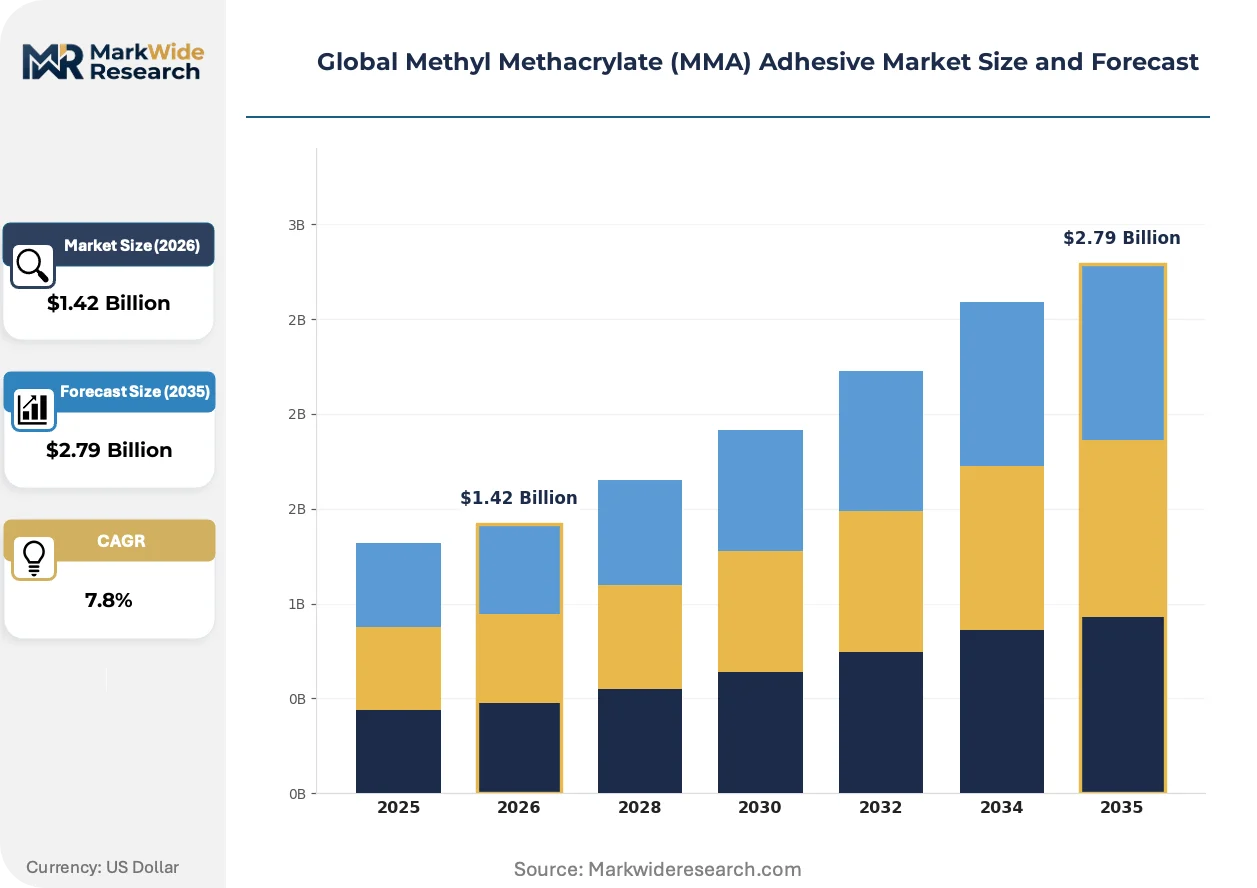
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Adhesives, UV Curing Adhesives, Two-Component Adhesives, Instant Adhesives, Flexible Adhesives Formulation Technology: Solvent-Based, Water-Based, Hot Melt, Reactive, UV Cure, Reactive Hot Melt Application: Transportation Equipment, Marine Components, Electronics Assemblies, Wind Turbine Blades, Aerospace Structures, Sporting Goods End User: OEMs, Aftermarket Suppliers, Contract Assemblers, Industrial Manufacturers, Equipment Fabricators |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Sika AG, Arkema, H.B. Fuller Company, Illinois Tool Works Inc., Huntsman International LLC, Bostik, Parker Hannifin Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Methyl Methacrylate (MMA) Adhesive Market Shifts & Advancements
Formulation chemistry is converging with process automation requirements, while regulatory jurisdictions are diverging on acceptable cure mechanisms and substance disclosure thresholds.
Dual-cure MMA-epoxy hybrid systems are unifying the gap-filling tolerance of methacrylates with the thermal resistance of epoxies. Automotive OEMs in Stuttgart and Wolfsburg are validating these for battery enclosure bonding where crashworthiness and thermal runaway containment converge. This convergence is compressing the historical segmentation between commodity instant adhesives and qualified structural grades.
EPA VOC regulations in the United States are restricting solvent-based adhesive deployment in industrial maintenance and repair operations. Manufacturers serving the Great Lakes industrial corridor are reformulating toward 100% reactive solids to maintain facility operating permits. The transportation equipment segment is absorbing the highest compliance costs as legacy repair specifications resist rapid substitution.
Specification authority is migrating from plant-level maintenance engineers to corporate EHS functions with consolidated purchasing leverage. Tier-1 suppliers in China's Pearl River Delta are responding with bundled adhesive-plus-dispensing-system contracts that lock in volume commitments through equipment financing. This concentration is most visible in consumer electronics assembly where brand OEMs have reduced qualified supplier pools from twelve to four over the past qualification cycle.
Global Methyl Methacrylate (MMA) Adhesive Market Segmentation
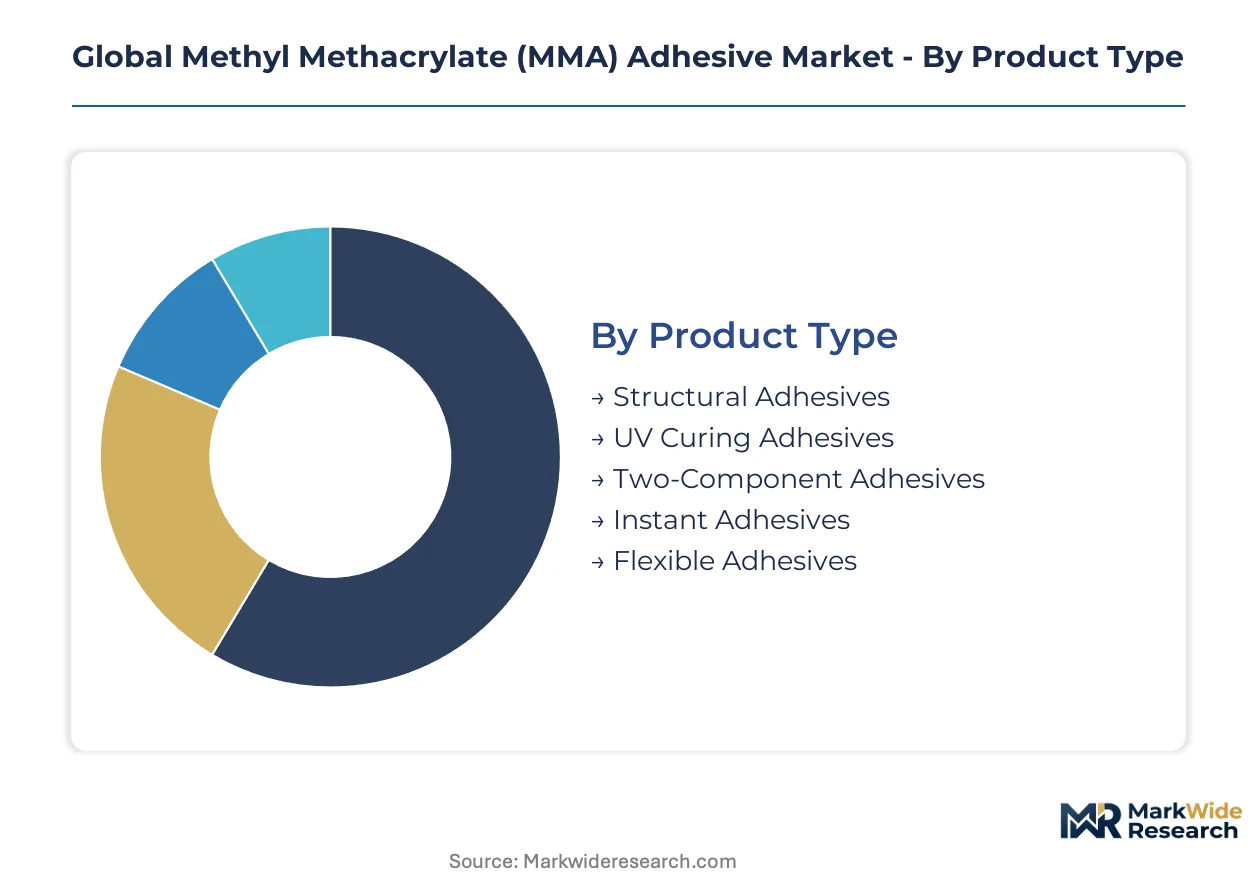
MMA adhesive segmentation reveals divergent margin architectures across product tiers. Structural grades command aerospace and automotive qualification premiums while commodity instant adhesives compete on throughput economics in consumer goods assembly.
Product Type:
Volume concentrates in transportation-grade reactive systems, while premium pricing attaches to certified structural formulations for regulated end-uses.
- Structural Adhesives:Free-radical polymerizing formulations achieve tensile shear strengths above 25 MPa on aluminum and carbon fiber composites. Demand clusters in Germany's automotive OEM bonded assembly lines and China's coastal wind turbine manufacturing zones, where 80-meter blade lengths have eliminated mechanical fastening feasibility.
- UV Curing Adhesives:Photoinitiator-activated systems cure in seconds under 365-405 nm LED arrays. Electronics assemblers in South Korea's Gyeonggi Province are piloting dual-cure variants combining free-radical initiation with cationic secondary cure for shadow-area reliability in smartphone camera module bonding.
- Two-Component Adhesives:Meter-mix-dispense systems dominate transportation equipment for controlled cure kinetics and gap-filling tolerance on irregular substrates.
- Instant Adhesives:Cyanoacrylate-class products face margin compression from Asian manufacturing scale in consumer goods assembly.
- Flexible Adhesives:Modified methacrylate formulations absorb dynamic loads in sporting goods and marine decking applications.
Mature deployment sits with structural adhesives in aerospace and wind energy certification protocols. Newer deployment is concentrated in UV curing systems for electronics miniaturization.
Formulation Technology:
Regulatory pressure is fragmenting technology adoption by geography, with reactive systems gaining in VOC-restricted jurisdictions and solvent-based formulations retreating to maintenance applications.
- Solvent-Based:VOC-emitting formulations face EPA restrictions in the US Great Lakes industrial corridor and REACH phase-out timelines in European electronics manufacturing. Remaining demand concentrates in industrial maintenance where legacy repair specifications resist rapid substitution.
- Water-Based:Emulsion polymer systems displace solvent formulations in European electronics assemblies as environmental compliance tightens. Henkel AG leverages reactive hot melt portfolios to dominate compliant transportation OEM channels.
- Hot Melt:Thermoplastic formulations serve high-speed packaging and temporary bonding operations with rapid green strength development.
- Reactive:100% solids systems absorb the highest compliance costs in transportation equipment as facilities retrofit toward permit-maintaining chemistries.
- UV Cure:Arkema specializes in these systems for electronics assemblies, competing on cure-speed specifications rather than price.
- Reactive Hot Melt:Hybrid systems combine initial thermoplastic tack with moisture-cure crosslinking for durable structural bonds.
Reactive and water-based platforms are climbing the fastest as regulatory jurisdictions tighten VOC thresholds. Solvent-based technology is retreating to non-regulated maintenance niches.
Application:
Application segmentation tracks the displacement of mechanical fastening across industries where vibration resistance, fatigue durability, and weight reduction converge.
- Transportation Equipment:Automotive OEMs in Stuttgart and Wolfsburg are validating dual-cure MMA-epoxy hybrids for battery enclosure bonding where crashworthiness and thermal runaway containment converge. This application absorbs the highest structural adhesive volumes.
- Wind Turbine Blades:Blade root bonding demands aerospace-grade certification as lengths exceed 80 meters. Denmark and Spain OEMs are qualifying hybrid epoxy-urethane substitutes, pressuring MMA share in this renewable energy segment.
- Electronics Assemblies:Miniaturized camera modules and display bonding in China's Pearl River Delta specification authority has migrated from plant engineers to corporate EHS functions.
- Marine Components:Deck-to-hull bonding and hardware mounting in fiberglass composite construction.
- Aerospace Structures:18-36 month qualification cycles lock inventory positions and freeze formulation agility during specification windows.
- Sporting Goods:Ski, snowboard, and bicycle frame bonding for vibration damping and impact resistance.
Transportation equipment represents the deepest volume pool. Wind turbine blade applications are gaining share fastest as blade scaling accelerates.
End User:
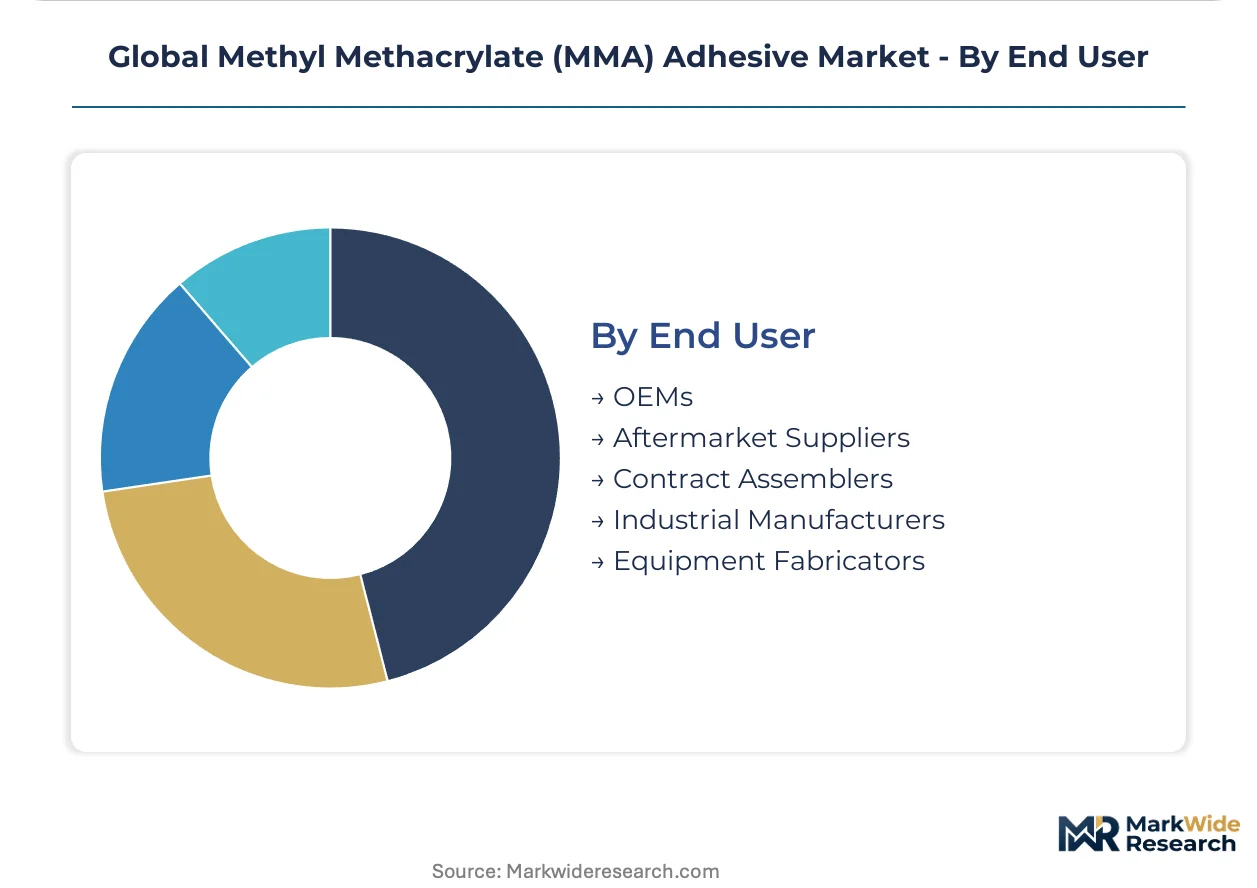
Procurement authority concentration varies sharply across end user types, with OEMs driving specification and contract assemblers competing on throughput economics.
- OEMs:Original equipment manufacturers in Germany and China are aggressively expanding bonded assembly lines, forcing adhesive suppliers to synchronize cure kinetics with robotic dispensing speeds. Corporate EHS functions now wield consolidated purchasing leverage over plant-level engineers.
- Contract Assemblers:Tier-1 suppliers in China's Pearl River Delta are responding to OEM consolidation with bundled adhesive-plus-dispensing-system contracts that lock volume commitments through equipment financing.
- Aftermarket Suppliers:Maintenance and repair operations face capital intensity in retrofitting legacy mechanical fastening lines with meter-mix-dispense equipment.
- Industrial Manufacturers:General fabrication demand concentrates in the US Great Lakes corridor where EPA VOC regulations restrict solvent-based deployment.
- Equipment Fabricators:Specialized machinery builders specify adhesives for vibration isolation and structural integrity in capital goods.
OEMs anchor premium structural adhesive demand through qualification barriers. Contract assemblers are expanding most quickly as outsourced manufacturing concentrates in coastal Chinese export zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong and Jiangsu provinces anchor production capacity expansion as China's GB standards on volatile organic compound emissions tighten manufacturing license requirements for adhesive suppliers serving coastal export zones.
China
Automotive OEMs in Shanghai and Guangzhou are aggressively expanding bonded assembly lines for lightweight vehicle structures. The Ministry of Ecology and Environment enforces tightening GB standards on VOC emissions that consolidate production among licensed domestic suppliers. Manufacturing gravity concentrates in Shandong and Jiangsu provinces where coastal export zones serve electronics and transportation equipment demand.
Germany
Stuttgart and Wolfsburg automotive clusters validate dual-cure MMA-epoxy hybrids for battery enclosure bonding applications. REACH restrictions on solvent-based formulations accelerate water-based and reactive technology migrations to maintain manufacturing licenses. The Baden-Württemberg and Lower Saxony industrial corridors absorb the deepest structural adhesive volumes in European transportation OEM channels.
United States
EPA VOC regulations restrict solvent-based adhesive deployment across the Great Lakes industrial corridor in Illinois, Michigan, and Ohio. Manufacturers reformulate toward 100% reactive solids to maintain facility operating permits. The transportation equipment segment absorbs the highest compliance costs as legacy repair specifications resist rapid substitution in maintenance operations.
Japan
Electronics assemblers in Tokyo and Osaka pilot dual-cure systems combining free-radical initiation with cationic secondary cure for shadow-area reliability. METI circular economy directives pressure OEMs to specify recyclable or debondable bonding systems. The Kanto and Kansai manufacturing belts create first-mover advantage for suppliers with reversible chemistry portfolios.
India
Tamil Nadu and Maharashtra manufacturing corridors remain underpenetrated for structural bonding as domestic OEMs transition from welded to hybrid-joined body-in-white architectures. The Bureau of Indian Standards and state industrial development corporations incentivize adhesive localization through production-linked incentive schemes. Chennai and Pune automotive clusters represent the fastest-expanding demand pools for meter-mix-dispense system integration.
Global Methyl Methacrylate (MMA) Adhesive Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation and dispensing system integration. The market structure consolidates around three tiers: multinational chemical conglomerates with captive monomer supply, specialized adhesive formulators with deep vertical integration into application engineering, and regional compounders competing on throughput economics. Strategic archetypes include aerospace-grade certifiers competing on qualification barriers, automotive system integrators bundling adhesive-plus-equipment contracts, and electronics specialists competing on cure-speed specifications. Dominant competitive moves involve backward integration into monomer production and geographic expansion through equipment financing partnerships that lock in volume commitments.
Within the multinational chemical tier, 3M and Henkel AG & Co. KGaA exemplify divergent strategic positions. 3M represents the diversified technology conglomerate archetype with cross-sector adhesive portfolios spanning industrial, electronics, and healthcare applications. Henkel occupies a position as a European-focused consumer and industrial adhesive specialist with deep roots in transportation OEM channels. Sika AG anchors the construction-grade formulation segment through in-house production of methacrylate resins and captive supply of application equipment. These three entities collectively illustrate how competitive positioning fragments across end-use specialization rather than converging on undifferentiated scale.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Sika AG |
| Arkema |
| H.B. Fuller Company |
| Illinois Tool Works Inc. |
| Huntsman International LLC |
| Bostik |
| Parker Hannifin Corp |
| Others |
Supply & Pricing Matrix
Captive monomer supply integration anchors pricing power for multinational chemical conglomerates while forcing mid-tier formulators toward equipment-financing bundling to defend margin positions. Henkel AG and Sika AG leverage backward integration into methacrylate resin production to command premium structural adhesive pricing, whereas regional compounders compete on throughput economics in instant adhesive commoditization.
Pricing Analysis
Value-based pricing anchored to aerospace-grade certification outcomes separates structural adhesive tiers from commodity formulations. Three-tier pricing structure across premium, standard, and economy levels reflects qualification barriers, with OEM procurement authority concentrating around automated dispensing compatibility. Cost compression in instant adhesives intensifies because Asian manufacturing scale erodes margin pools, while transportation equipment buyers show lowest price sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Single-source vulnerability sits with acetone cyanohydrin feedstock channels that draw from petroleum refining and acetone production clusters in China, Germany, and the United States. Methyl methacrylate monomer supply rests on petrochemical cracking capacity and hydrogen cyanide availability, with tariff exposure on imported specialty photoinitiators for UV curing systems. Distribution runs through direct OEM supply agreements for structural grades and chemical distributor networks for maintenance applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies a technology-transition phase where reactive and water-based formulations displace solvent-based legacy systems under tightening VOC regimes across manufacturing jurisdictions.
For Market Incumbents: Deepen captive monomer supply positions to offset feedstock volatility compression, while accelerating dual-cure MMA-epoxy hybrid R&D to defend against epoxy-urethane substitution in wind energy blade bonding. Prioritize certification investment for 80-meter-plus turbine specifications.
For New Entrants and Emerging Players: Begin with India's Tamil Nadu and Maharashtra automotive corridors where domestic OEM body-in-white architecture transitions create white-space demand for meter-mix-dispense system integration. Target contract assembler segments with adhesive-plus-equipment financing bundles.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of specialized adhesive formulators with deep application engineering capabilities and reversible chemistry portfolios aligned to Japan METI circular economy mandates. Watch for inflection in GB standard enforcement intensity across Shandong-Jiangsu manufacturing clusters as consolidation signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Captive acetone cyanohydrin supply secures margin stability against feedstock volatility. |
| Dual-Cure Formulation Development | MMA-epoxy hybrids unify gap-filling tolerance with thermal resistance for battery enclosures. |
| Equipment Financing Partnerships | Bundled adhesive-plus-dispensing contracts lock volume commitments in Pearl River Delta. |
| Reversible Chemistry Portfolio Investment | Debondable systems create first-mover advantage under Japan METI circular economy directives. |
| Aerospace-Grade Certification Acceleration | 18-36 month qualification cycles freeze competitor entry in wind turbine blade bonding. |
Research Methodology
Trade databases, customs records, and SEC 10-K filings formed the secondary backbone, supplemented by primary interviews with adhesive plant managers, OEM procurement leads at automotive and wind energy manufacturers, distribution channel partners, and technical R&D directors. Bottom-up volume modeling triangulated against top-down market sizing across formulation technology, application segment, and regional production hub dimensions.
Historical trendline analysis tracked segment growth trajectories across the projection horizon, with CAGR derivation reflecting penetration rates of water-based and reactive systems displacing solvent formulations. Segmentation modeling incorporated grade tier, end-use industry, packaging format, and regional regulatory cluster variables. Forecast inputs included automotive bonded assembly line expansion data and wind turbine blade length scaling curves.
Underlying measurement precision varies by segment; structural adhesives and transportation equipment applications carry tighter precision than commodity instant adhesives and aftermarket maintenance categories. Forecasts reflect assumptions around regulatory enforcement timelines and OEM qualification cycle durations, with feedstock volatility and substitute technology qualification posing revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
Global Human Fibrin Glue Market
Adhesives & Sealants
Asia-Pacific Cyanoacrylate Adhesives Market
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
US Pressure Sensitive Adhesives Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Europe Sealants Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
Packaging Adhesives Market
Adhesives & Sealants
Australia Adhesives Market
Adhesives & Sealants
North America Adhesives Market
Adhesives & Sealants
Construction Adhesives and Sealants Chemical Market
Adhesives & Sealants
Melamine Formaldehyde (MF) Market
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market