
 Middle-East and Africa Contact Adhesives Market | 2026-2036
Middle-East and Africa Contact Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Contact Adhesives Market Foresight
REACH compliance obligations for imported formulations are restructuring the cost-of-entry calculus for suppliers serving Middle-East and Africa distributors. Henkel AG & Co. KGaA leverages its European regulatory expertise to pre-certify adhesive lines for cross-border shipment into Gulf markets. Sika AG anchors its regional position through construction-specialized distribution networks spanning the United Arab Emirates and Egypt. Dow competes on solvent-free polymerization technology that aligns with tightening environmental standards across multiple jurisdictions.
Contact adhesives are one-component or two-component bonding systems formulated from polychloroprene, polyurethane, or natural rubber dispersions in solvent or water carriers, achieving immediate tack and high green strength upon contact pressure. These formulations serve primary industrial purposes in bonding decorative laminates, rubber gaskets, footwear components, and automotive interior trim where flexible, high-peel-strength joints resist thermal cycling and humidity exposure. Solvent-based contact adhesives still dominate volume in the Middle-East and Africa due to faster drying rates in high-temperature climates, though water-based systems are gaining share as polymerization technology improves open-time performance. Hot melt contact adhesives represent a smaller but expanding segment in automated furniture and packaging assembly lines where dispersion coating equipment limits throughput speed.
South Africa's Air Quality Act, Saudi Arabia's Saudi Green Initiative framework, and the UAE's Emirates Conformity Assessment Scheme collectively shape product registration timelines, VOC thresholds, and import documentation burdens for adhesive suppliers. Egypt's mandatory pre-shipment inspection requirements under its quality control protocols add another compliance layer for manufacturers without local blending facilities. Stakeholders must monitor how Gulf standardization bodies harmonize chemical substance restrictions with European REACH annexes, as this convergence will determine which formulation platforms retain multi-country eligibility without costly reformulation cycles.
Market Dynamics
Gulf Cooperation Council giga-project construction is compressing specification cycles for high-performance bonding systems while South Africa's Air Quality Act enforcement redirects formulation portfolios toward water-based chemistries. This dual pressure from demand acceleration and regulatory pivot defines current competitive positioning.
Growth Catalysts
- Saudi Green Initiative framework:The Saudi Green Initiative framework mandates lower-emission construction materials across Neom and Red Sea Project developments, creating sustained specification pull for compliant adhesive systems in facade bonding applications.
- Polyurethane dispersion advances:Improved open-time performance in water-based polyurethane dispersions is displacing solvent-based systems in high-temperature climates where drying speed previously dictated chemistry selection.
- UAE-Egypt distribution corridors:Construction-specialized distribution networks spanning Dubai and Cairo are reducing import documentation burdens for pre-certified adhesive lines serving North African fit-out markets.
Market Restraints
- Solvent feedstock volatility:Crude-derived aromatic solvent costs fluctuate with regional refining capacity constraints, compressing margin stability for polychloroprene-based formulations dominant in volume production.
- Pre-shipment inspection friction:Egypt's mandatory quality control protocols add 3-6 week clearance delays for manufacturers without local blending facilities, advantaging regional compounders with in-country presence.
- Hot-melt substitution ceiling:Automated furniture assembly lines in Morocco and Tunisia face throughput limitations from dispersion coating equipment speeds, capping hot-melt contact adhesive penetration despite performance advantages.
Strategic Opportunities
- Kenya's infrastructure pipeline:Kenya's Standard Gauge Railway extension and port modernization projects represent underpenetrated demand for high-peel-strength bonding in transportation interior trim and marine applications.
- Emirates Conformity Assessment Scheme alignment:Gulf standardization bodies harmonizing chemical substance restrictions with European REACH annexes create multi-country eligibility for pre-certified formulation platforms without costly reformulation cycles.
- Water-based and reactive hot-melt convergence:Hybrid systems combining moisture-cure polyurethane chemistry with hot-melt application speed are opening specification windows in Saudi automotive interior assembly previously locked to solvent systems.
Industry Challenges
- Formulation chemist scarcity:Technical expertise in VOC-compliant polymerization sits concentrated with European and Asian compounders, constraining local product development capacity across Gulf blending facilities.
- REACH documentation burden:Imported formulations face extended registration timelines for cross-border shipment into Middle-East and Africa distributors, restructuring cost-of-entry calculus for smaller suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Contact Adhesives Market |
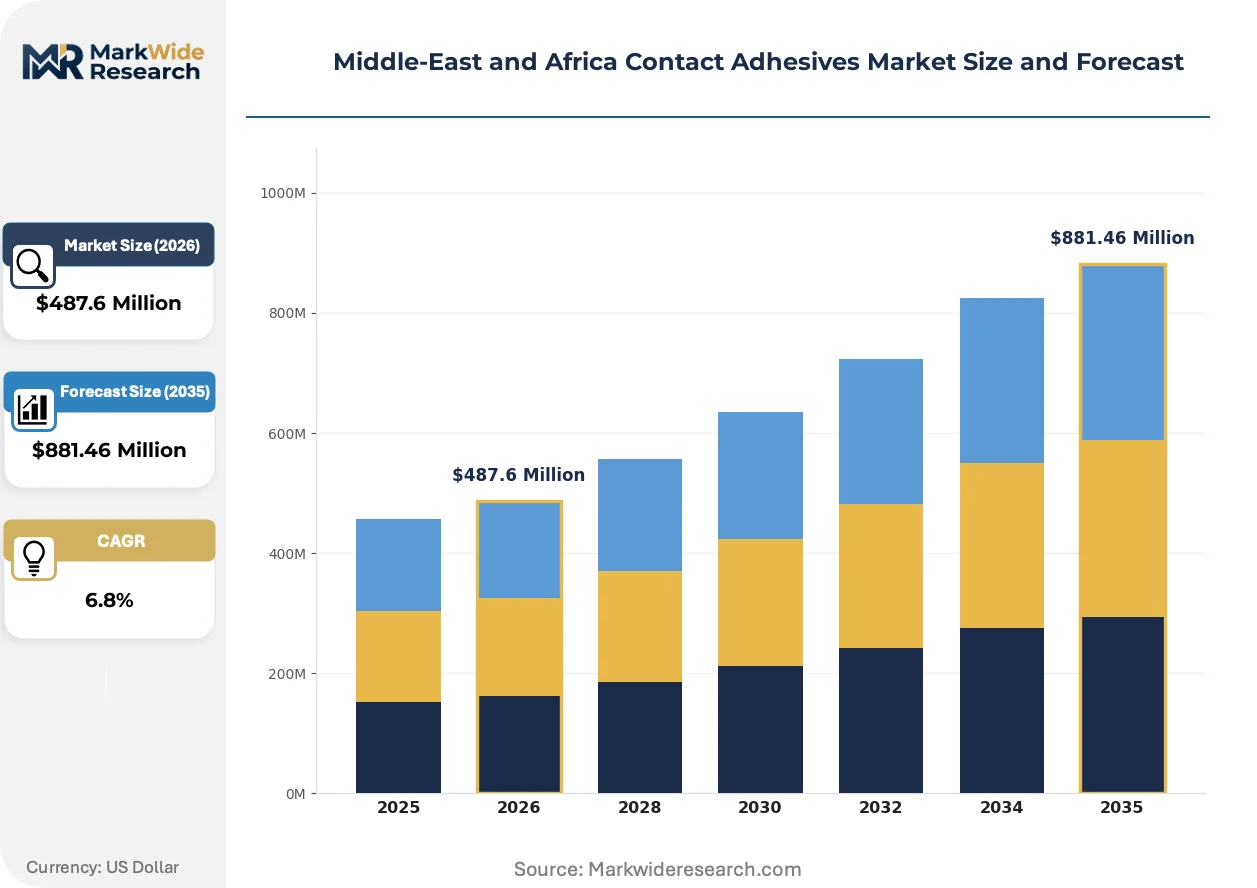
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Water-Based, Hot Melt, Reactive End User: Automotive, Furniture, Construction, Footwear Application: Wood Bonding, Plastic Bonding, Metal Bonding, Textile Bonding Technology: Diffusion, Polymerization, Dispersion, Coating |
| Companies Covered | 3M, Arkema Group, Henkel AG & Co. KGaA, Sika AG, H.B. Fuller, Dow, Huntsman International LLC, Illinois Tool Works Inc., Avery Dennison Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Contact Adhesives Market Shifts & Advancements
Formulation chemistry and application equipment are converging to compress specification cycles while regulatory harmonization across Gulf markets reshapes product registration strategies. These forces are accelerating technology turnover in a market historically characterized by conservative specification lock-in.
Reactive polyurethane hot-melt systems are modularizing the competitive landscape for automotive interior trim bonding. Tier-one suppliers in Saudi Arabia and South Africa are adopting these chemistries at accelerating pace to bypass solvent-based drying limitations in high-throughput assembly environments. This technology is modularizing what were previously discrete specification categories—solvent, water-based, and conventional hot-melt—into unified platforms serving multiple end-use requirements.
South Africa's Air Quality Act enforcement is tightening VOC emission thresholds for industrial coatings and adhesives, forcing reformulation of polychloroprene and natural rubber dispersions toward water-based carriers. The industrial consequence is compressed product development timelines as compounders race to match open-time performance of legacy solvent systems. Decorative laminate fabricators in Gauteng and Western Cape provinces are most affected, responding by consolidating supplier relationships with firms possessing pre-certified water-based portfolios.
Buyer concentration among Gulf giga-project developers is compressing procurement cycles and unbundling after-sales technical service from material supply contracts. EPC contractors in Saudi Arabia and the UAE now demand standalone application training and on-site bonding audits, displacing traditional distributor-mediated support models. This pattern is most visible in Neom and Red Sea Project developments where single-source adhesive specifications span multi-billion dollar construction phases.
Middle-East and Africa Contact Adhesives Market Segmentation
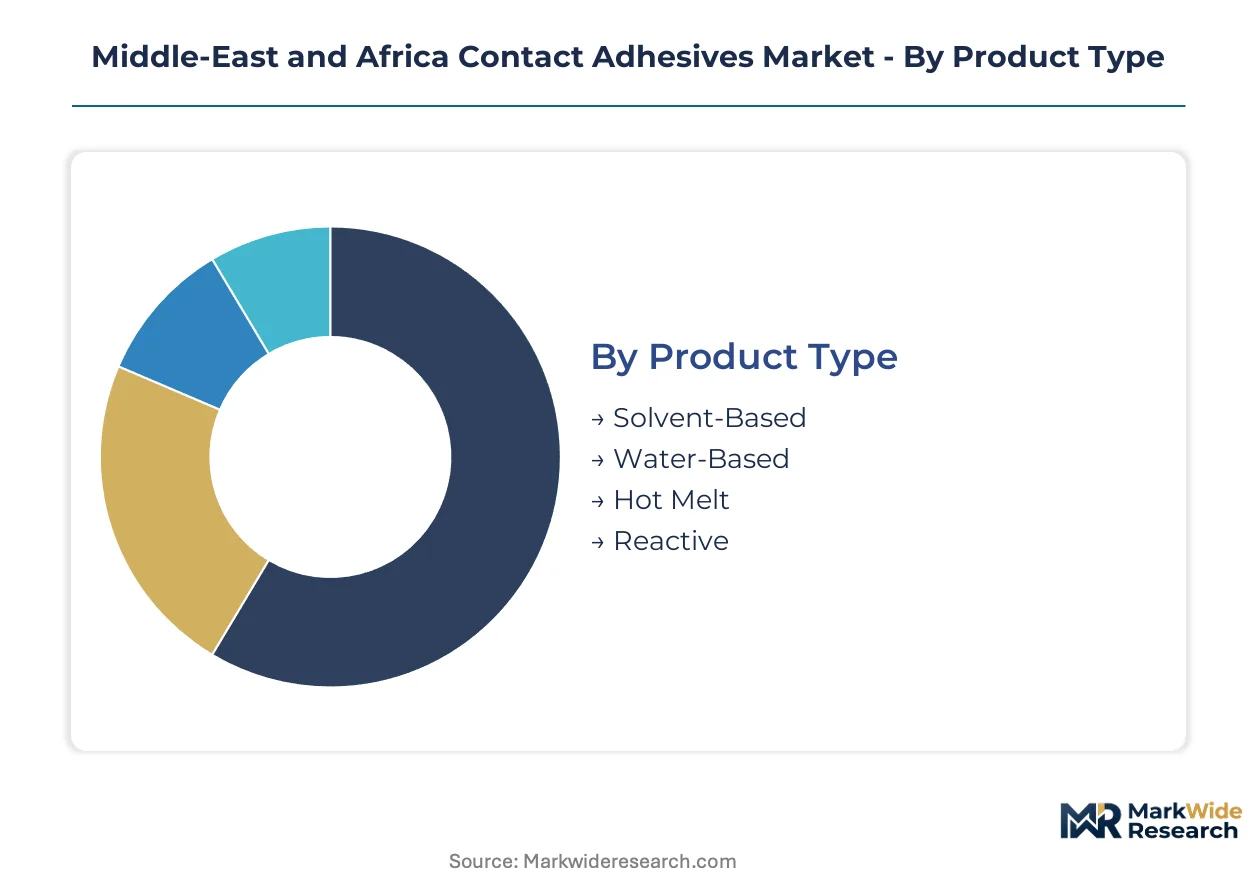
Contact adhesive procurement in the Middle-East and Africa splits across chemistry platforms, end-use specifications, and application methods that each carry distinct regulatory and climate burdens. Specification cycles compress when Gulf giga-projects demand multi-substrate bonding performance under single contract umbrellas.
Product Type:
Integration depth varies sharply: solvent and water systems dominate standalone manual applications, while reactive and hot-melt chemistries embed into automated production lines with captive dispensing equipment.
- Solvent-Based:Polychloroprene and natural rubber dispersions in aromatic hydrocarbon carriers deliver immediate tack and high green strength. Saudi Arabian facade bonding contractors specify these formulations for Neom and Red Sea Project developments where open-air drying rates offset VOC exposure concerns.
- Water-Based:Polyurethane and acrylic emulsions are displacing solvent systems in South African decorative laminate fabrication following Air Quality Act enforcement tightening VOC thresholds in Gauteng and Western Cape provinces.
- Hot Melt:EVA and polyolefin formulations serve automated furniture assembly in Morocco and Tunisia where throughput speed constraints limit dispersion coating alternatives.
- Reactive:Moisture-cure polyurethane systems bond automotive interior trim in Saudi assembly plants, combining hot-melt application speed with structural strength previously requiring solvent-based drying.
Solvent-based leads volumes today; water-based is gaining share fastest.
End User:
Cost tier stratification separates specification-intensive construction and automotive segments from price-sensitive furniture and footwear procurement.
- Construction:High-peel-strength bonding of aluminum composite panels and stone cladding dominates Gulf Cooperation Council specification pull, with EPC contractors demanding standalone application training and on-site bonding audits unbundled from material supply.
- Automotive:Tier-one suppliers in Saudi Arabia and South Africa adopt reactive hot-melt systems for interior trim assembly, bypassing solvent drying limitations in high-throughput environments.
- Furniture:Decorative laminate fabricators in Egypt and Morocco face margin compression from pre-shipment inspection delays, advantaging regional compounders with local blending facilities.
- Footwear:Natural rubber and polychloroprene cement bonding of sole units persists in Ethiopian and Kenyan production clusters serving export markets, with water-based migration constrained by open-time performance gaps.
Construction commands premium pricing; automotive is climbing the fastest.
Application:
Volume concentration tracks substrate thermal expansion coefficients and humidity exposure severity across regional climate zones.
- Wood Bonding:Decorative laminate-to-substrate applications in furniture and interior fit-out drive water-based polyurethane specification in South Africa's Air Quality Act compliance environment.
- Plastic Bonding:Polypropylene and ABS trim attachment in Saudi automotive assembly favors reactive hot-melt systems with primerless adhesion to low-surface-energy substrates.
- Metal Bonding:Aluminum composite panel facade systems in UAE and Qatar developments specify high-solids solvent or silyl-modified polymer systems resisting thermal cycling stress.
- Textile Bonding:Automotive headliner and seat fabric lamination employs water-based polyurethane dispersions with flame-retardant additives meeting Emirates Conformity Assessment Scheme protocols.
Wood bonding retains the largest application base; plastic bonding shows steepest expansion trajectory.
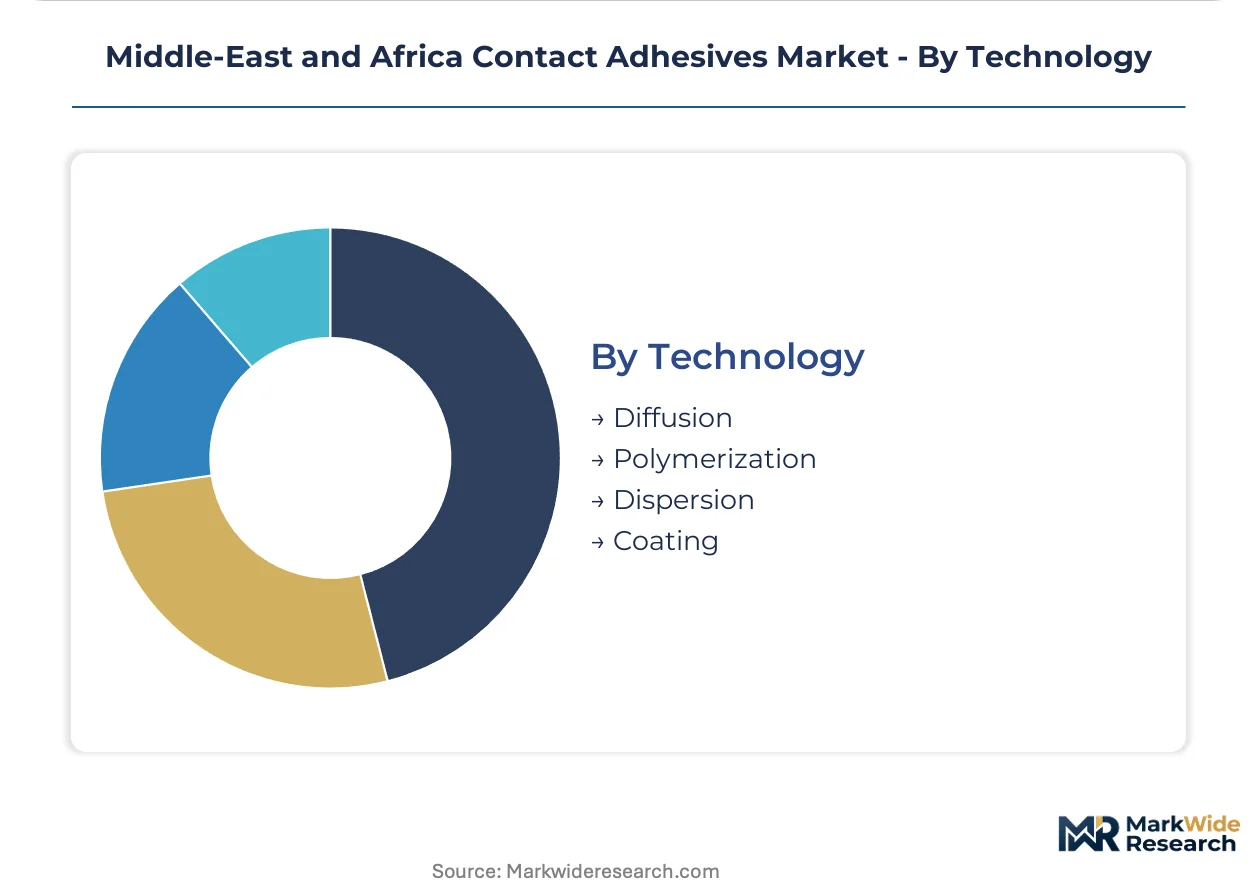
Technology:
Supply concentration sits with European and Asian compounders possessing polymerization expertise, constraining local development capacity across Gulf blending facilities.
- Diffusion:Solvent-borne systems relying on polymer chain entanglement across substrate interfaces dominate high-temperature climate applications where rapid solvent release enables immediate handling.
- Polymerization:Reactive moisture-cure chemistry in hot-melt and liquid systems creates covalent crosslinking post-application, serving Saudi automotive specifications demanding heat resistance beyond physical drying mechanisms.
- Dispersion:Water-based polymer emulsions stabilized with surfactants require coalescing agents for film formation, with open-time performance gaps narrowing through polyurethane dispersion advances.
- Coating:Roller and spray application equipment compatibility dictates viscosity and solids content specifications, with automated lines in Moroccan furniture plants favoring hot-melt coating speeds.
Diffusion technology anchors current procurement; polymerization is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical formulation expertise concentrates with European and Asian compounders, constraining indigenous development capacity across Gulf blending facilities and South African manufacturing zones.
Saudi Arabia
Neom and Red Sea Project giga-developments generate sustained specification pull for high-performance facade bonding systems. The Saudi Green Initiative framework mandates lower-emission construction materials across these developments. Riyadh-based EPC contractors now demand standalone application training unbundled from material supply contracts.
United Arab Emirates
Dubai and Abu Dhabi construction activity drives consumption in aluminum composite panel bonding and interior fit-out applications. The Emirates Conformity Assessment Scheme shapes VOC thresholds and import documentation burdens for adhesive suppliers. Jebel Ali distribution corridors reduce clearance timelines for pre-certified European formulations.
South Africa
Decorative laminate fabricators in Gauteng and Western Cape provinces face compressed product development timelines. The Air Quality Act enforces tightening VOC emission thresholds for industrial coatings and adhesives. Regional compounders with local blending facilities capture share from importers facing pre-shipment inspection friction.
Egypt
Furniture assembly and construction fit-out applications concentrate demand in Cairo and Alexandria industrial zones. Mandatory pre-shipment inspection requirements under quality control protocols add clearance delays for manufacturers without local presence. Egyptian distributors increasingly consolidate supplier relationships with firms possessing in-country blending capacity.
Morocco
Automated furniture assembly lines in Casablanca and Tangier-Med industrial zones favor hot-melt contact adhesive systems. Throughput limitations from dispersion coating equipment speeds constrain penetration despite performance advantages. Regional manufacturers serve European export markets with price-competitive bonding solutions.
Middle-East and Africa Contact Adhesives Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with construction-specialized distribution networks. European and North American multinationals anchor premium specification tiers, while regional compounders compete on import documentation agility and local blending proximity. Three archetypes dominate: diversified adhesive specialists with cross-sector portfolios, construction-chemical pure-plays with project-specific technical service capabilities, and regional compounders with in-country formulation facilities. Capacity expansion and strategic distribution partnerships represent the dominant competitive moves, as Gulf giga-project timelines compress procurement cycles.
Among diversified chemical conglomerates, 3M and Henkel AG & Co. KGaA exemplify the premium-tier archetype through their European regulatory expertise and pre-certified formulation platforms. Sika AG occupies a position within the construction-chemical specialization vector, anchoring regional presence through project-specific technical service capabilities. Dow represents the technology-driven archetype, competing on solvent-free polymerization platforms that align with tightening environmental standards across multiple Middle-East and Africa jurisdictions.
| Leading Market Players |
|---|
| 3M |
| Arkema Group |
| Henkel AG & Co. KGaA |
| Sika AG |
| H.B. Fuller |
| Dow |
| Huntsman International LLC |
| Illinois Tool Works Inc. |
| Avery Dennison Corporation |
| Others |
Supply & Pricing Matrix
Gulf giga-project procurement consolidation toward single-source adhesive specifications is forcing compounders to absorb unbundled technical service costs into material pricing, compressing margin structures for European suppliers without regional blending assets.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive pricing tiers across Middle-East and Africa markets. Three-tier pricing structure across premium, standard, and economy levels separates pre-certified European formulations with REACH documentation from regional compounders with local blending and import-dependent distributors facing clearance delays. Price differentiation hinges on certification grade under Emirates Conformity Assessment Scheme protocols and after-sales technical service bundling. Cost compression in the standard tier is intensifying because South African Air Quality Act compliance is forcing rapid water-based portfolio redevelopment. Construction EPC contractors show least price sensitivity due to specification lock-in, while furniture fabricators in Egypt and Morocco face acute margin pressure from pre-shipment inspection friction.
Supply Chain Analysis
Formulation chemist scarcity in Saudi Arabia and the UAE constrains indigenous production capacity, forcing reliance on European and Asian polymerization expertise. Supply concentrates in Germany, Belgium, and South Korea for polyurethane dispersion feedstocks, with aromatic solvents drawing from regional refining capacity in Saudi Arabia and Kuwait. Raw material dependencies span polychloroprene rubber, isocyanate prepolymers, and petroleum-derived solvents. Single-source vulnerability sits with moisture-cure polyurethane catalysts from limited Asian suppliers. Distribution runs through Jebel Ali and Cairo corridor hubs serving North African fit-out markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH-compliant European formulations command premium positioning in Gulf markets against South Africa's regulatory-driven water-based transition, creating divergent cost curves across the region.
For Market Incumbents: Lock in construction-specialized distribution networks before Gulf giga-project procurement cycles compress further. Prioritize backward integration into polyurethane dispersion production in Saudi Arabia to bypass import documentation burdens. Defend against regional compounders by pre-certifying formulation platforms under harmonized Gulf standardization protocols. For New Entrants and Emerging Players: E-commerce-enabled technical service platforms offer low-friction entry into Kenyan and Ethiopian footwear and transportation interior trim markets. Target Kenya's Standard Gauge Railway extension projects with water-based systems priced below European imports. Pursue joint venture structures with Egyptian distributors possessing in-country blending facilities to circumvent pre-shipment inspection delays. For Investors and Strategic Acquirers: Asymmetric upside sits with regional compounders possessing Gulf blending facilities and pre-certified water-based portfolios. Long-term viability centers on water-based and reactive hot-melt convergence platforms serving automotive interior assembly. Monitor Emirates Conformity Assessment Scheme alignment with REACH annexes as inflection signal for multi-country eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Saudi blending facilities capture Neom and Red Sea Project specification pull before import competitors clear documentation. |
| Backward Integration | In-house polyurethane dispersion production reduces feedstock exposure to Asian isocyanate supply volatility. |
| Green Manufacturing Transition | Water-based portfolio redevelopment aligns with Saudi Green Initiative and South Africa Air Quality Act thresholds. |
| Long-term Supply Agreement | Multi-year contracts with Gulf EPC contractors secure volume against spot-market volatility in solvent feedstocks. |
| Joint Venture | Local partnerships in Egypt and Kenya circumvent pre-shipment inspection friction and accelerate market access. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged adhesive formulators, EPC contractor procurement leads, decorative laminate fabricators, and distribution channel partners across Saudi Arabia, UAE, South Africa, and Egypt. Secondary validation drew from customs and trade data, Gulf standardization body publications, SEC filings of diversified chemical conglomerates, and construction project development databases. Bottom-up volume estimates by chemistry platform and end-use segment were cross-checked against top-down market sizing from regional production and import flows.
Segment-weighting approaches assigned differential growth coefficients across solvent-based, water-based, hot-melt, and reactive chemistry platforms. The analytical framework modeled chemistry type, end-use industry, application method, and regional regulatory cluster across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves tied to construction spending forecasts and automotive production schedules. Industry-specific inputs included VOC threshold enforcement timelines under South Africa's Air Quality Act and giga-project completion phases in Saudi Arabia.
The model assumes a particular technology adoption path; alternative pathways for moisture-cure polyurethane hot-melt systems would alter the outlook if open-time performance gaps close faster than projected. Forecasts reflect assumptions about regulatory harmonization pace and construction cycle continuity. Material deviation in Gulf standardization body alignment with REACH annexes or sudden solvent feedstock disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
Wood Glue Market
Adhesives & Sealants
Global Solvent Pressure Sensitive Adhesives Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Anti-Seize Compounds Market
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
Latin America Adhesives and Sealants Market
Adhesives & Sealants
Flock Adhesives Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Temporary Bonding Adhesives Market
Adhesives & Sealants
South America Acrylic Adhesives Market