
 IoT Software Engineering Market | 2026-2036
IoT Software Engineering Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Software Engineering Market Foresight
The gap between premium embedded systems and commodity device firmware is expanding as industrial buyers demand real-time analytics at the edge while consumer applications tolerate latency. Microsoft leverages its Azure IoT stack to anchor enterprise deployments across manufacturing verticals. Amazon Web Services competes through serverless compute integrations that reduce provisioning overhead for connected fleets. Siemens sustains dominance in European industrial automation through deep domain expertise in programmable logic controller interoperability.
IoT software engineering encompasses the design, development, and validation of firmware, middleware, and cloud-native orchestration layers that enable physical devices to collect, transmit, and act on sensor data with sub-second latency requirements. Its primary purpose is to bridge heterogeneous hardware protocols into unified data pipelines for operational decision-making. Cloud-based deployment leads in revenue contribution as enterprises prioritize elastic scaling over capital-intensive infrastructure ownership. Edge computing represents the fastest-expanding segment where latency-sensitive applications in autonomous systems and robotic process control command premium engineering rates. Security solutions within the solution stack concentrate margin pools as regulatory mandates harden baseline encryption and identity management requirements.
FDA cybersecurity guidance for connected medical devices and FCC spectrum allocations for unlicensed IoT bands shape product development timelines and certification costs in the United States. GDPR data residency rules and EU AI Act risk classifications constrain cross-border data architectures for European deployments. Stakeholders must monitor how NIST post-quantum cryptography standards will force firmware refactoring cycles across installed device bases.
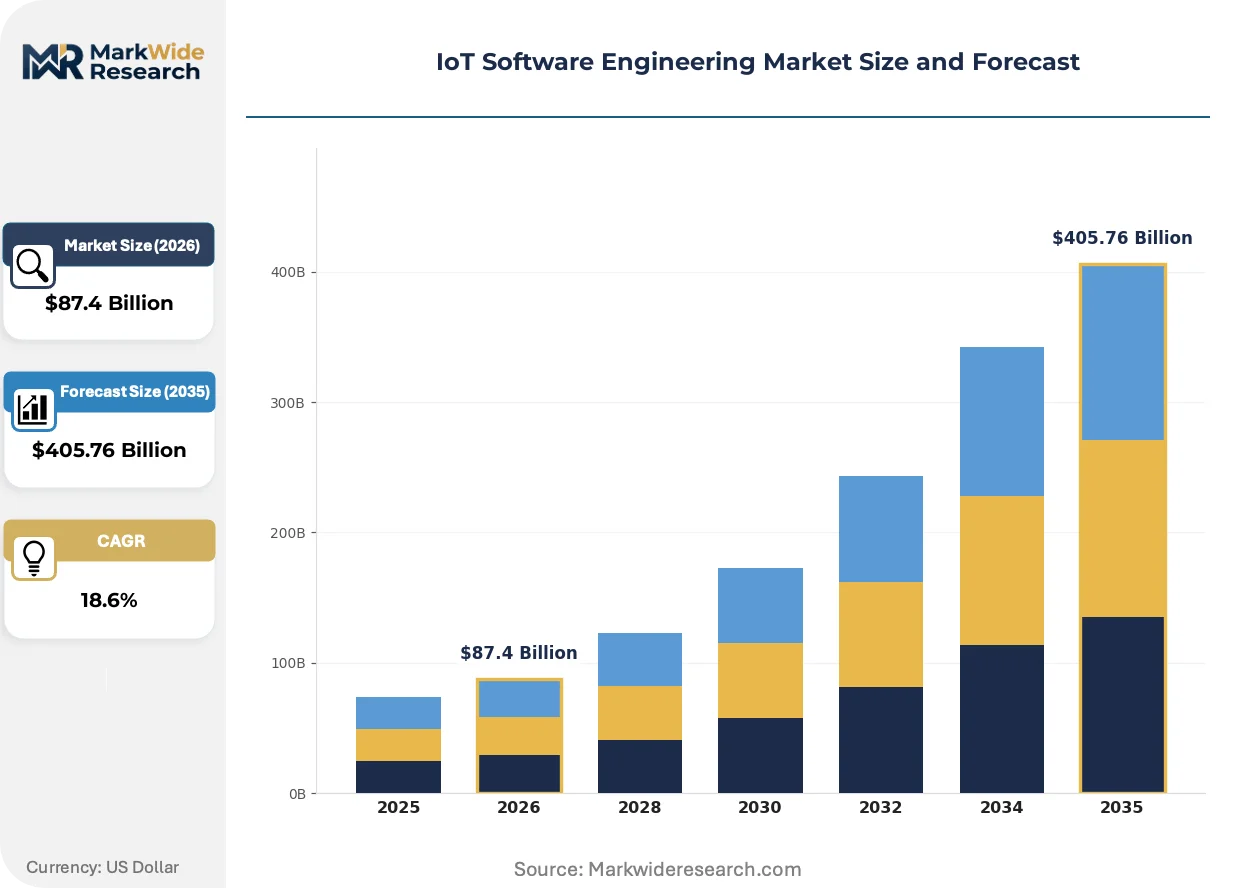
Market Dynamics
Industrial operators are consolidating software procurement around edge-native architectures that compress latency for predictive maintenance, forcing engineering vendors to restructure delivery models away from cloud-centric subscriptions toward hybrid deployment expertise.
Growth Catalysts
- FCC unlicensed spectrum allocations:New IoT-specific bands in the 900 MHz and 2.4 GHz ranges reduce deployment friction for connected asset networks in US manufacturing facilities.
- Predictive maintenance mandates:Automotive and machinery clusters in Germany are requiring sub-100ms edge analytics for robotic process control, pulling premium engineering services into industrial automation.
- GDPR-aligned data governance:European procurement criteria now mandate residency-compliant middleware, creating specification pull for regional engineering specialists.
Market Restraints
- Semiconductor supply concentration:Edge AI chip fabrication concentrates in Taiwan and South Korea, exposing firmware development timelines to foundry allocation volatility.
- NIST post-quantum cryptography timelines:Upcoming firmware refactoring mandates will force installed device base updates, compressing margin on legacy support contracts.
- Specialized talent scarcity:Embedded systems security expertise concentrates in Munich, Stuttgart, and Silicon Valley, inflating project rates for cross-border deployments.
Strategic Opportunities
- EU AI Act risk classification compliance:High-risk IoT system certification creates service attach revenue for engineering firms with notified body relationships.
- India industrial corridor expansion:PLI scheme incentives for electronics manufacturing are pulling connected asset platform deployments into Gujarat and Tamil Nadu.
- Digital twin convergence:Integration of physics-based simulation with live sensor streams is opening new specification categories for middleware vendors.
Industry Challenges
- Programmable logic controller interoperability:Heterogeneous legacy automation hardware fragments integration architectures, extending project timelines.
- FDA cybersecurity validation cycles:Connected medical device software updates require 90-180 day documentation reviews, compressing release velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Software Engineering Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $405.76 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Healthcare, Manufacturing, Transportation, Agriculture Application: Smart Home, Industrial Automation, Smart Cities, Wearable Devices Solution: Device Management, Data Analytics, Security, Connectivity |
| Companies Covered | Microsoft, Amazon Web Services, Siemens, IBM, Cisco, Oracle, PTC, SAP, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Software Engineering Market Shifts & Advancements
Containerized edge runtimes are displacing monolithic middleware stacks as industrial buyers demand granular scalability without cloud dependency, restructuring how engineering firms architect firmware delivery pipelines.
Embedded Linux distributions with pre-certified security modules are modularizing how automotive Tier-1 suppliers assemble infotainment and telematics stacks. BMW and Volkswagen procurement teams now specify containerized middleware from multiple vendors rather than single-source platforms. This architecture is modularizing supplier relationships and compressing integration testing timelines from 18 months to 6 months.
The EU AI Act's risk-based conformity assessment is forcing IoT software vendors to restructure documentation practices for high-risk industrial applications. Engineering firms serving German machinery exporters must now maintain technical file traceability from sensor firmware through cloud orchestration layers. Medical device and autonomous system categories face the steepest compliance cost escalation.
Asset-as-a-service financing models are restructuring how manufacturing buyers contract for connected platform engineering. Industrial operators in the US Midwest now prefer outcome-linked payment structures tied to uptime guarantees rather than capitalized software licenses. This shift is concentrating contract awards with vendors offering bundled hardware-software-service stacks.
IoT Software Engineering Market Segmentation
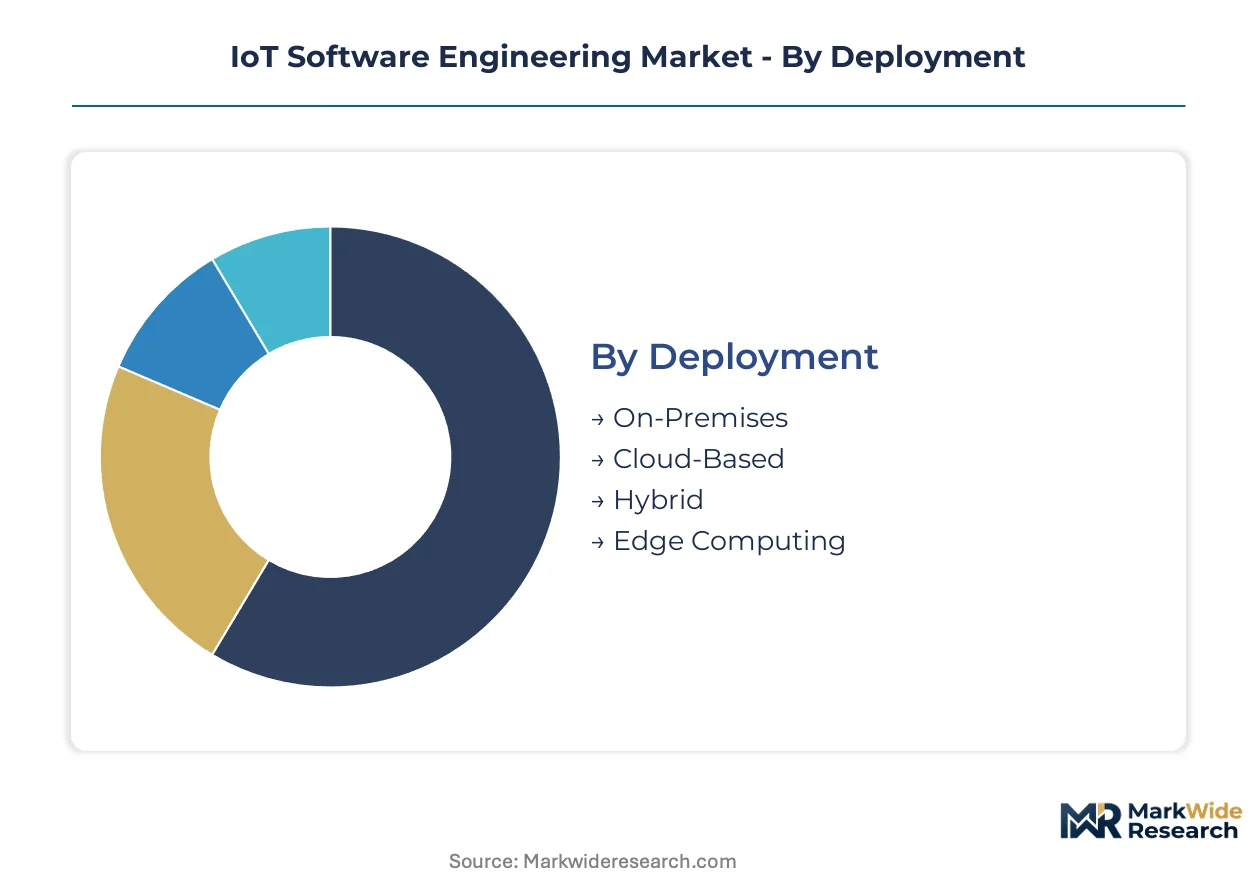
Engineering procurement patterns diverge sharply across deployment topologies and end-use verticals. Industrial buyers prioritize latency specifications and residency compliance, while consumer applications optimize for cost and interoperability breadth.
Deployment:
Supply concentration in edge-native tooling chains is restructuring how vendors architect firmware delivery pipelines and certification workflows.
- Cloud-Based:Elastic orchestration layers dominate enterprise procurement for connected asset fleets requiring centralized analytics. Manufacturing clusters in Germany specify multi-tenant architectures with GDPR-aligned data residency, pulling premium engineering rates for compliance-heavy deployments.
- Edge Computing:Sub-100ms latency requirements for robotic process control are concentrating demand in automotive and machinery verticals. Taiwan and South Korea foundry allocations for edge AI chips expose firmware development timelines to supply volatility, compressing margin on accelerated delivery schedules.
- Hybrid:Split architectures balance cloud elasticity with local autonomy for intermittent connectivity scenarios.
- On-Premises:Air-gapped installations persist in defense and critical infrastructure sectors with sovereignty mandates.
Today's leader: Cloud-Based. Tomorrow's challenger: Edge Computing.
End User:
Cost tier stratification separates capital-intensive industrial automation from outcome-linked service contracts in emerging verticals.
- Manufacturing:Predictive maintenance mandates from German automotive OEMs specify sub-second edge analytics for robotic welding and assembly lines. Siemens and Bosch procurement teams now require containerized middleware with PLC interoperability certifications, extending vendor qualification timelines.
- Healthcare:FDA cybersecurity guidance for connected medical devices imposes 90-180 day validation cycles on firmware updates. Cardiac monitors and insulin pumps face the steepest documentation requirements, compressing release velocity for engineering contractors.
- Transportation:Fleet telematics and autonomous navigation systems demand real-time sensor fusion with fail-operational redundancy.
- Agriculture:Precision irrigation and livestock monitoring platforms prioritize low-power wide-area connectivity over latency performance.
Manufacturing commands premium engineering rates. Healthcare faces the steepest regulatory cost escalation.
Application:
Volume concentration in consumer wearables contrasts with margin pools in industrial automation where certification barriers limit vendor entry.
- Industrial Automation:Physics-based digital twin integration with live sensor streams is opening new specification categories for middleware vendors. German machinery exporters now require technical file traceability from sensor firmware through cloud orchestration under EU AI Act risk classifications.
- Smart Home:Fragmented protocol ecosystems and price-sensitive mass markets tolerate higher latency than industrial counterparts. Amazon and Google voice assistant integrations dominate procurement criteria for thermostat and lighting control firmware.
- Smart Cities:Municipal traffic management and environmental monitoring deployments span multi-decade maintenance horizons.
- Wearable Devices:Battery-constrained form factors drive optimization for milliwatt-scale compute and intermittent connectivity.
Industrial Automation captures the steepest expansion trajectory. Smart Home dominates unit volume.
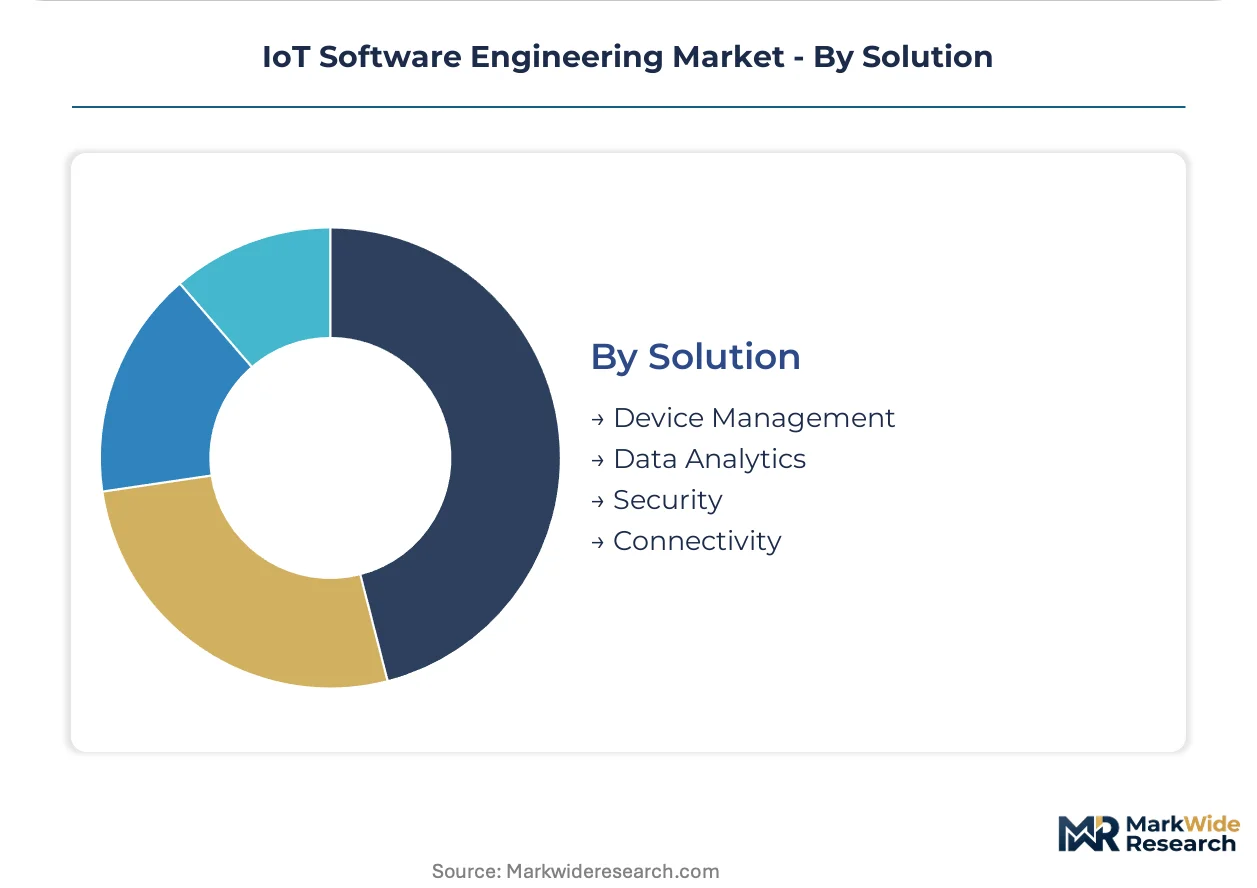
Solution:
Margin accrual concentrates in security modules where NIST post-quantum cryptography mandates force firmware refactoring cycles across installed device bases.
- Security:Embedded encryption and identity management layers command premium engineering rates as regulatory baselines harden. Munich and Stuttgart talent scarcity for secure boot and hardware root-of-trust implementations inflates project rates for cross-border deployments.
- Data Analytics:Real-time stream processing and anomaly detection capabilities differentiate vendor positioning in predictive maintenance contracts. US Midwest manufacturing operators now prefer outcome-linked payment structures tied to uptime guarantees rather than capitalized software licenses.
- Device Management:Over-the-air update orchestration and fleet monitoring tools standardize across deployment scales.
- Connectivity:Protocol translation and network abstraction layers bridge heterogeneous hardware into unified data pipelines.
Security commands the highest engineering margins. Data Analytics is gaining share fastest through outcome-based contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive clusters command premium engineering rates for sub-100ms edge analytics, while the United States concentrates cloud-native orchestration demand around FCC spectrum allocations for unlicensed IoT bands.
United States
FDA cybersecurity guidance for connected medical devices and FCC unlicensed spectrum allocations in the 900 MHz and 2.4 GHz ranges drive procurement criteria. The FDA imposes 90-180 day validation cycles on firmware updates for cardiac monitors and insulin pumps. Silicon Valley and Austin embedded systems talent pools concentrate secure boot and hardware root-of-trust expertise.
Germany
Automotive OEM predictive maintenance mandates and machinery cluster demand for robotic process control specify sub-100ms edge analytics. GDPR data residency rules and EU AI Act risk classifications constrain cross-border data architectures. Munich and Stuttgart engineering firms maintain technical file traceability for machinery exporters under notified body relationships.
China
MIIT industrial internet initiatives and dual carbon goals accelerate connected asset platform deployments in manufacturing corridors. GB standards and SAMR cybersecurity requirements shape firmware certification workflows. Yangtze River Delta electronics manufacturing clusters pull edge AI chip demand from Taiwan and South Korea foundries.
India
PLI scheme incentives for electronics manufacturing and CEA grid modernization mandates expand connected asset platform procurement. BIS certification requirements and TRAI spectrum policies influence device connectivity specifications. Gujarat and Tamil Nadu industrial corridors concentrate new manufacturing operator demand for predictive maintenance systems.
Japan
METI Society 5.0 initiatives and JIS standards for industrial automation drive edge-native architecture specifications. PMDA digital health regulations shape connected medical device software validation requirements. Kanto and Kansai manufacturing belts specify containerized middleware with fail-operational redundancy for robotic systems.
IoT Software Engineering Market Competitive Landscape
Top-tier vendors anchor cloud-native orchestration stacks, while specialized engineering boutiques capture premium rates for edge-native compliance-heavy deployments. The vendor base stratifies across hyperscale platform providers, industrial automation incumbents with deep PLC interoperability expertise, and regional specialists with notified body relationships. Two dominant competitive moves are reshaping positioning: M&A activity targeting edge AI talent pools, and strategic partnerships bundling hardware-software-service stacks under outcome-linked contracts.
Among hyperscale platform providers, Microsoft and Amazon Web Services exemplify contrasting approaches to enterprise IoT orchestration, with the former anchoring manufacturing verticals through Azure stacks and the latter competing via serverless compute integrations. Siemens occupies a position within the industrial automation archetype, sustaining European dominance through programmable logic controller interoperability expertise rather than cloud-native scale.
| Leading Market Players |
|---|
| Microsoft |
| Amazon Web Services |
| Siemens |
| IBM |
| Cisco |
| Oracle |
| PTC |
| SAP |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up engineering specialists in Munich and Stuttgart anchor premium-rate positioning for EU AI Act compliance services, while their asset-light delivery models compress fixed-cost exposure and sustain margin discipline against commodity cloud-native competitors.
Pricing Analysis
Bundled hardware-software-service stacks command premium positioning against unbundled SaaS subscriptions in manufacturing verticals. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated medical device firmware from industrial automation middleware and consumer-grade connectivity modules. Cost compression in the standard tier intensifies because hyperscaler platform competition erodes per-seat orchestration fees. Healthcare operators prove least price-sensitive due to 90-180 day validation cycle lock-in, while agricultural buyers prioritize low-power hardware economics over software feature depth.
Supply Chain Analysis
Certification and qualification gating through notified body relationships in Germany and Japan fragments vendor eligibility for high-risk industrial applications. Edge AI chip fabrication concentrates in Taiwan and South Korea, while embedded systems security talent clusters in Munich, Stuttgart, and Silicon Valley. Firmware development timelines hinge on foundry allocation volatility for neural processing units. Distribution runs through direct enterprise sales teams for manufacturing accounts and hyperscaler marketplaces for cloud-native deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where engineering talent cost differentials between Germany and India enable margin expansion for vendors with dual-shore delivery capabilities.
For Market Incumbents: To counter hyperscaler platform commoditization, deepen PLC interoperability certifications for Siemens and Bosch procurement teams while building captive edge AI chip supply relationships with Taiwan foundries to buffer allocation volatility. For New Entrants and Emerging Players: Launch via outcome-linked contracts targeting US Midwest manufacturing operators seeking uptime-guaranteed predictive maintenance systems, bypassing capital-intensive certification barriers through strategic partnerships with established notified bodies. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, consolidating edge-native engineering boutiques to fill EU AI Act compliance capability gaps. Target acquisition archetypes include Munich-based firmware specialists with technical file traceability workflows. Monitor NIST post-quantum cryptography standard finalization as the inflection signal forcing legacy device base refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | EU AI Act notified body relationships transfer compliance capability to acquirers seeking German machinery exporter contracts. |
| Platform Integration | Containerized middleware unification reduces Siemens and Bosch vendor qualification timelines from 18 months to 6 months. |
| Geographic Expansion | India PLI scheme incentives in Gujarat and Tamil Nadu pull predictive maintenance deployment demand from cost-sensitive manufacturing operators. |
| Strategic Partnership | Hardware-software-service bundling aligns with US Midwest outcome-linked payment preferences for uptime-guaranteed contracts. |
| Product Launch | Pre-certified embedded Linux security modules accelerate automotive Tier-1 supplier infotainment stack assembly timelines. |
Research Methodology
Multiple input streams — primary interviews with CTOs and platform engineers at industrial automation firms, IT procurement officers at manufacturing operators, and integration specialists at hyperscaler partners — were reconciled against secondary validation from SEC filings, hyperscaler capex disclosures, and FDA cybersecurity guidance documents. Bottom-up segment sizing across deployment topologies and end-use verticals was triangulated with top-down market aggregation.
Historical growth patterns were cross-referenced against panel input from industry practitioners to anchor projections across the analysis window. Segmentation dimensions modeled include deployment topology, end-use vertical, application category, and solution stack component, with regional adoption patterns capturing GDPR residency mandates and FCC spectrum allocation impacts. CAGRs were derived from elasticity-adjusted demand curves incorporating edge AI chip supply constraints and regulatory compliance cost escalations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NIST post-quantum cryptography timeline acceleration or Taiwan foundry allocation disruptions. A model refresh is warranted upon material change in EU AI Act enforcement intensity or India PLI scheme incentive structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Device Management Platform Market
Internet of Things (IoT)
Global IoT Engineering Services Market
Internet of Things (IoT)
IoT Infrastructure Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
Internet of Things in BFSI Market
Internet of Things (IoT)
North America IoT Device Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
Europe IoT Services Market
Internet of Things (IoT)
North America and Europe IoT Gateway Market
Internet of Things (IoT)
5G IIOT Market
Internet of Things (IoT)
IoT Services Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market
Internet of Things (IoT)
IoT Gateway Devices Market
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
IoT Solutions Market
Internet of Things (IoT)
Global Agile IoT Market