
 Australia Medtech Market | 2026-2036
Australia Medtech Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Medtech Market Intelligence
Software-defined diagnostics is repositioning how Australian medtech firms monetize hardware, shifting revenue toward recurring licensing and remote monitoring subscriptions. Cochlear Limited leverages its implant ecosystem to sustain high-margin service attach rates across audiology clinics. ResMed Inc. anchors sleep apnea therapy through cloud-connected device platforms that capture longitudinal patient data. Device Technologies competes by controlling distribution breadth across tertiary hospitals and private surgical centers.
Medtech encompasses medical devices, equipment, and digital health systems engineered to diagnose, monitor, or treat clinical conditions, typically regulated under risk-classification frameworks based on invasiveness and software dependency. The primary commercial purpose centers on improving patient outcomes while reducing procedural cost and recovery time across acute and chronic care settings. Diagnostic Devices leads product-type revenue due to sustained capital replacement cycles in radiology and pathology, while Wearable Technology captures the fastest expansion as remote patient monitoring integrates with cardiology and rehabilitation workflows. Cloud-Based delivery mode concentrates margin pools among platforms achieving hospital EMR interoperability, whereas On-Premise systems retain dominance in surgical navigation and high-acuity settings where latency constraints persist.
TGA's software-as-a-medical-device framework and the Therapeutic Goods Act shape market access by classifying AI-enabled diagnostics under escalating scrutiny levels that extend approval timelines for algorithm-dependent tools. ISO 13485 quality management requirements and the MDSAP audit program govern manufacturing standards, compelling exporters to maintain dual compliance for Australian and US FDA market participation. Stakeholders must monitor how TGA's evolving digital health guidance intersects with state-based hospital procurement frameworks to determine which platform architectures secure sustainable reimbursement pathways.
Market Dynamics
TGA's software-as-a-medical-device framework is compressing product development cycles while elevating compliance costs, forcing domestic manufacturers to restructure R&D roadmaps around algorithm validation requirements rather than hardware iteration alone.
Growth Catalysts
- Remote patient monitoring infrastructure:Victoria's Melbourne biomedical precinct anchors cloud-connected cardiac and respiratory device deployment, with public hospital procurement expanding for telemetry-integrated systems.
- TGA digital health pathway:The regulator's streamlined SaMD classification for lower-risk algorithms accelerates market entry for AI-enabled diagnostic tools, particularly in pathology workflow automation.
- Aged care technology mandate:Federal funding for in-home monitoring devices drives wearable adoption across chronic disease management, with reimbursement codes now covering continuous glucose and blood pressure tracking.
Market Restraints
- Algorithm validation costs:Clinical evidence requirements for machine-learning diagnostics under TGA's Class IIa and IIb rules extend development timelines and burn capital before revenue realization.
- Component import dependency:Precision sensors and semiconductor substrates concentrate in East Asian supply chains, exposing Australian assemblers to shipping volatility and currency fluctuation.
- Surgical robot substitution:Leasing models for da Vinci systems and competing platforms displace standalone instrument purchases in tertiary hospitals, compressing capital equipment budgets for domestic manufacturers.
Strategic Opportunities
- Queensland regional health networks:Underpenetrated public hospital procurement outside Melbourne and Sydney creates first-mover advantage for connected diagnostic platforms targeting distributed care models.
- ISO 13485-MDSAP convergence:Dual certification alignment opens simultaneous Australian and FDA market access, reducing per-market compliance overhead for export-oriented device firms.
- Rehabilitation-robotics integration:Exoskeleton and assistive device convergence with telehealth platforms addresses post-acute care gaps, with NDIS funding expanding eligible equipment categories.
Industry Challenges
- Embedded systems engineering scarcity:Firmware and real-time operating system expertise for Class III devices concentrates in a small talent pool, inflating recruitment costs and project delays.
- EMR interoperability fragmentation:Proprietary data formats across Cerner, Epic, and regional hospital systems force redundant integration work for cloud-based device platforms.
- Post-market surveillance burden:TGA's mandatory reporting for software updates and algorithm modifications consumes engineering resources that would otherwise feed product enhancement pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Medtech Market |
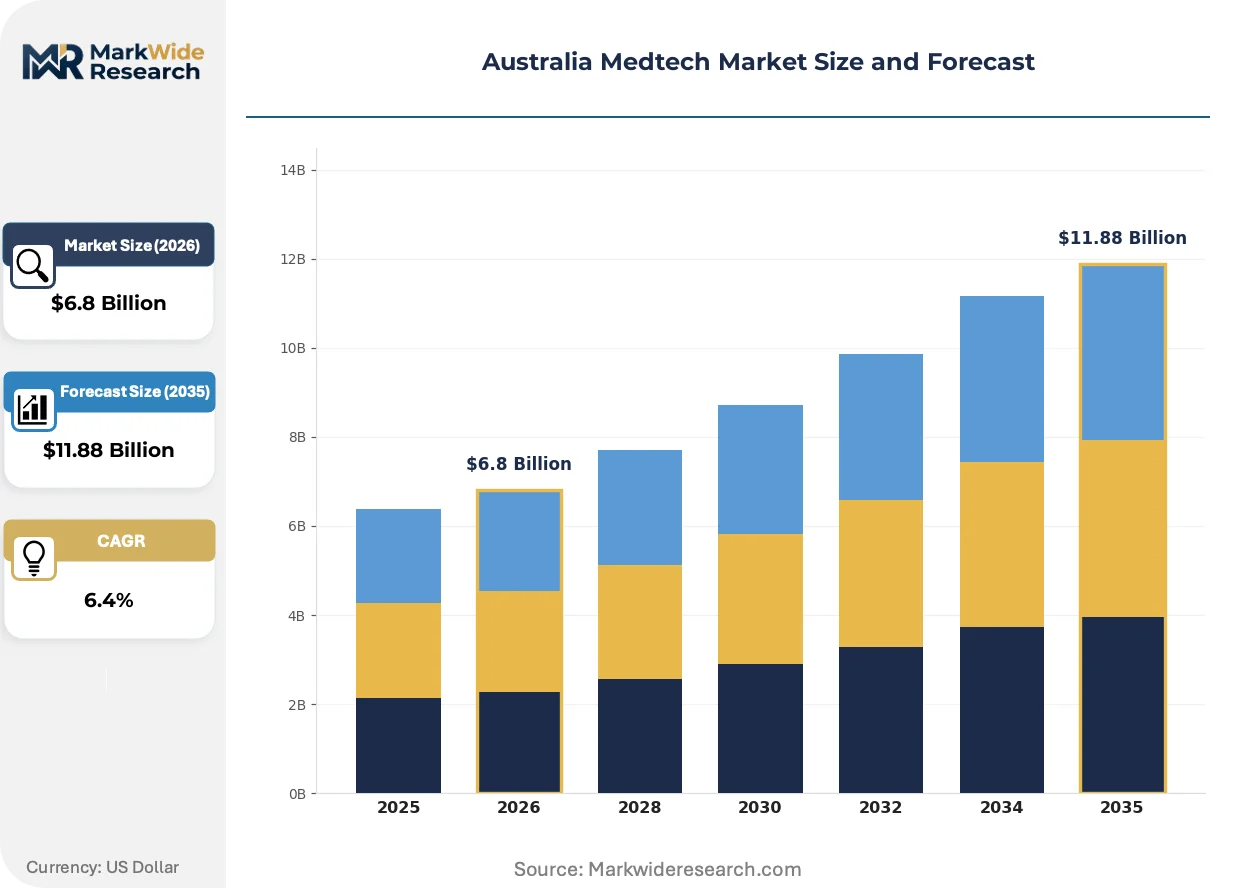
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Devices, Surgical Instruments, Wearable Technology, Healthcare IT End User: Hospitals, Clinics, Diagnostic Labs, Rehabilitation Centers Delivery Mode: Telemedicine, On-Premise, Cloud-Based, Mobile Health Application: Cardiology, Orthopedics, Neurology, Urology |
| Companies Covered | Cochlear Limited, ResMed Inc., Paragon Care Group, Device Technologies, Alcidion Group Limited, Anatomics Pty Ltd, Sirtex Medical Limited, Artrya, Pro Medicus, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Medtech Market Strategic Shifts & Innovations
Digital-native device architectures are displacing legacy hardware-centric business models, with revenue attaching to data services and longitudinal patient relationships rather than single-unit sales. This structural shift permeates regulatory strategy, supply chain configuration, and competitive positioning across the Australian medtech base.
Artificial intelligence embedded in point-of-care diagnostics is rewriting how pathology and radiology workflows allocate labor and capital. Public hospital networks in New South Wales and Victoria are piloting AI-augmented imaging interpretation for stroke and fracture detection, compressing report turnaround from hours to minutes. The technology is rewriting specialist workforce deployment, enabling centralized oversight of distributed emergency departments without proportional consultant hiring.
TGA's evolving guidance on adaptive algorithms and continuous learning systems is tightening evidentiary standards for software updates that modify diagnostic performance. Manufacturers must now submit predetermined change control plans before market authorization, locking development trajectories into regulatory filings. Cardiology monitoring devices and diabetic retinopathy screening platforms face the steepest compliance burden, with sponsors building dedicated clinical affairs teams to manage post-approval algorithm drift.
Public hospital procurement is consolidating purchasing authority through state-level health department frameworks, displacing individual hospital tendering for high-value capital equipment. New South Wales Health Infrastructure and HealthShare Victoria now negotiate multi-year supply agreements for imaging and patient monitoring fleets, concentrating vendor selection power in centralized procurement offices. This concentration is most visible in metropolitan tertiary centers, where standardized device platforms reduce training and maintenance complexity across hospital networks.
Australia Medtech Market Segmentation
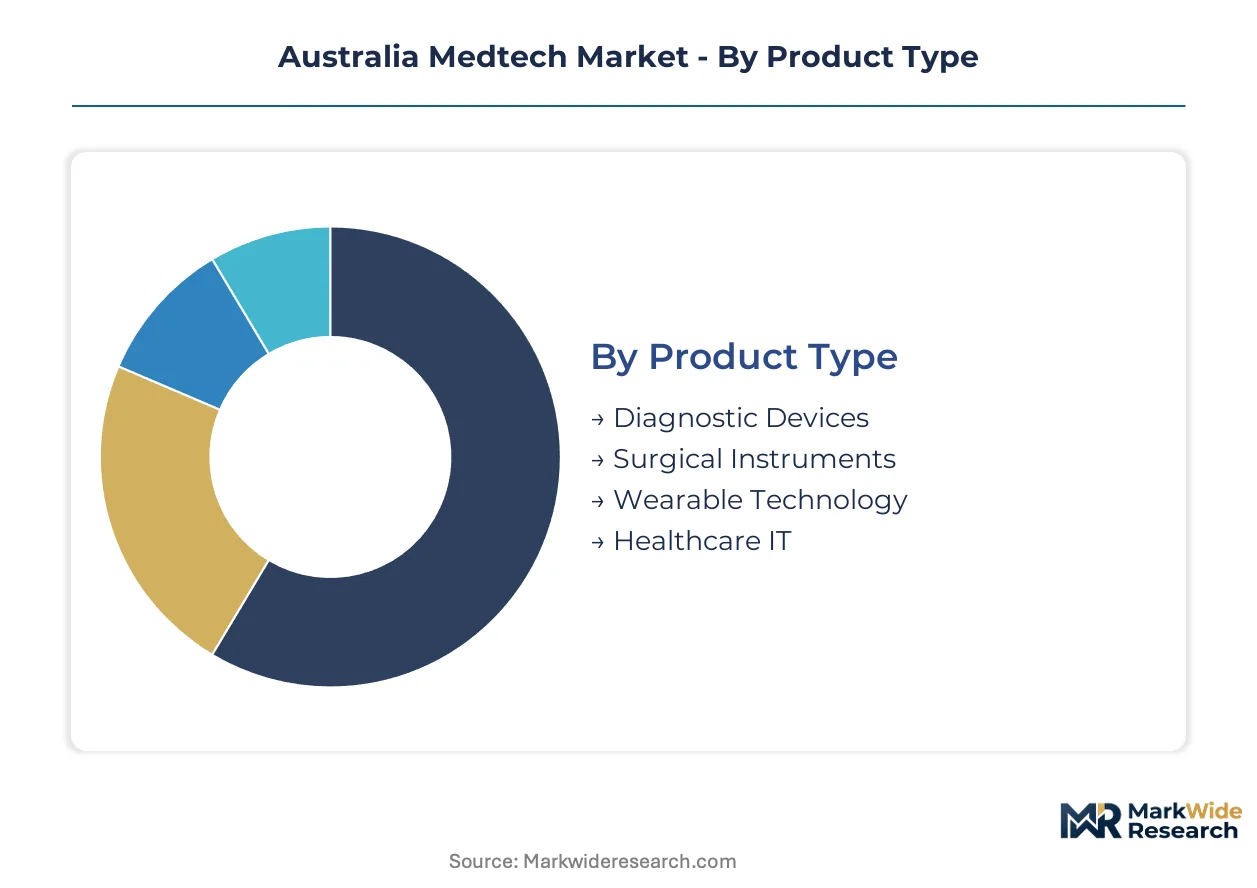
Segmentation in the Australian medtech market exposes how procurement concentration in Victoria and New South Wales shapes product development priorities. TGA's risk-classification framework further stratifies segments by compliance burden, creating divergent margin structures across hardware and software-defined categories.
Product Type:
Supply concentration for precision components and semiconductor substrates concentrates manufacturing advantage among firms with established East Asian supplier relationships.
- Diagnostic Devices:Capital equipment spans radiology, pathology, and point-of-care testing platforms with embedded software for image analysis. Public hospital procurement in Sydney and Melbourne drives replacement cycles for MRI, CT, and molecular diagnostic systems.
- Wearable Technology:Continuous monitoring devices integrate biosensors with cloud connectivity for cardiac, respiratory, and metabolic tracking. Federal aged care technology mandates accelerate adoption across chronic disease management in regional Queensland and Western Australia.
- Surgical Instruments:Electromechanical tools and disposable consumables serve open and minimally invasive procedures in tertiary hospitals.
- Healthcare IT:Clinical workflow software, electronic medical records modules, and interoperability platforms bridge device data with hospital information systems.
Diagnostic Devices absorbs the bulk of installed capacity; Wearable Technology is expanding most quickly.
End User:
Customer concentration patterns reveal how state-level health department frameworks reshape vendor access across metropolitan and regional networks.
- Hospitals:Tertiary centers in Melbourne, Sydney, and Brisbane deploy high-acuity capital equipment requiring intensive clinical engineering support. HealthShare Victoria and New South Wales Health Infrastructure consolidate multi-year procurement agreements, concentrating vendor selection authority.
- Diagnostic Labs:Pathology networks automate high-throughput testing with AI-augmented interpretation for histology and molecular diagnostics. Sonic Healthcare and Healius operations in metropolitan hubs drive platform standardization.
- Clinics:General practice and specialist outpatient settings adopt point-of-care diagnostics with lower regulatory classification.
- Rehabilitation Centers:Post-acute facilities integrate assistive robotics and telehealth platforms under NDIS funding expansion.
Hospitals command the dominant share of capital expenditure; Diagnostic Labs are climbing the fastest as automation penetrates pathology workflows.
Delivery Mode:
Margin distribution across deployment architectures reflects the engineering trade-offs between latency sensitivity and scalability.
- Cloud-Based:SaaS platforms for remote patient monitoring and diagnostic image storage achieve hospital EMR interoperability through API integration. Victorian public hospital networks pilot telemetry-integrated cardiac monitoring with centralized data lakes.
- On-Premise:Surgical navigation systems and high-acuity patient monitors require sub-millisecond response times, locking deployment to hospital server rooms. Latency constraints preserve dominance in operating theaters and intensive care units.
- Telemedicine:Real-time video consultation platforms with integrated diagnostic peripherals serve rural and remote patient populations.
- Mobile Health:Smartphone-native applications for chronic disease self-management leverage consumer device ubiquity.
On-Premise retains the largest installed base; Cloud-Based is gaining share fastest as interoperability standards mature.
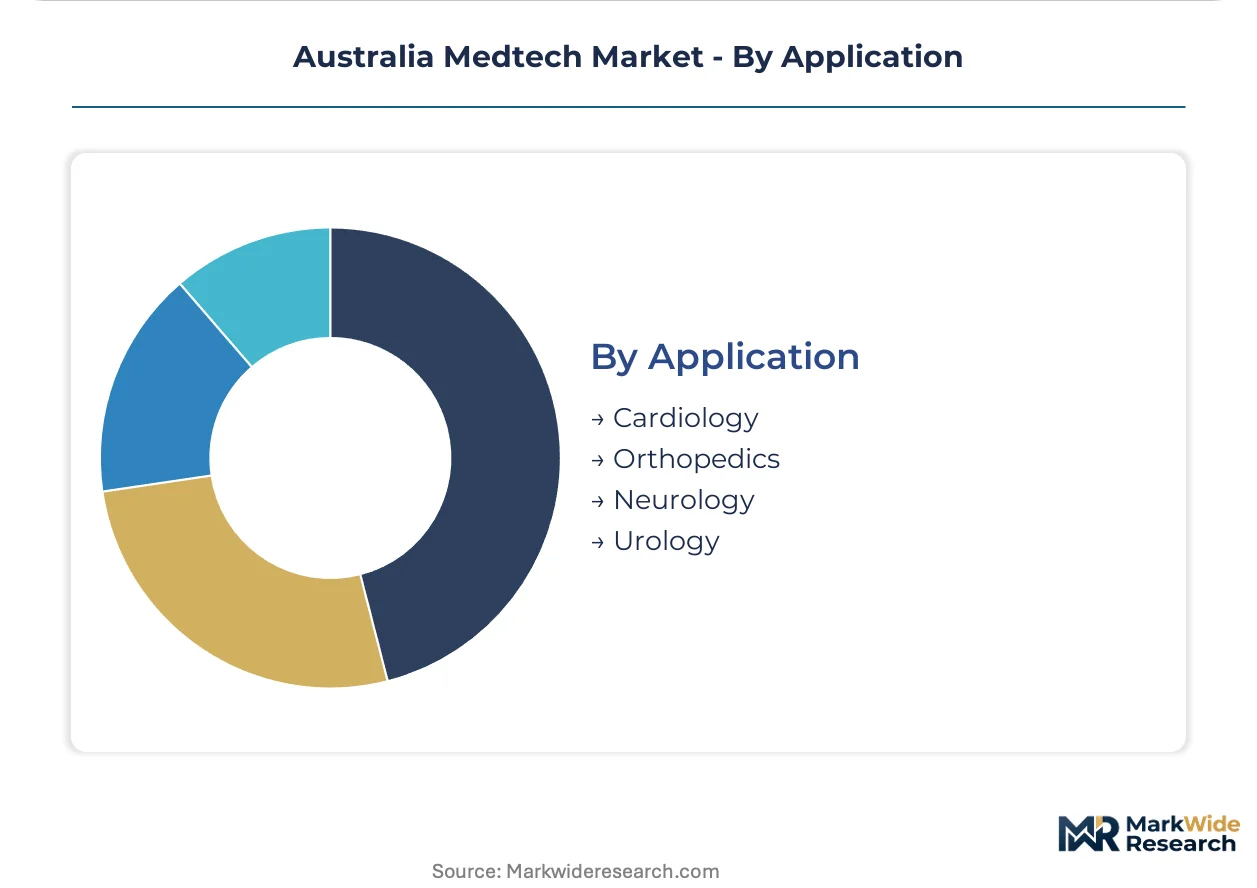
Application:
Clinical specialization determines the intensity of regulatory scrutiny and the structure of reimbursement pathways across TGA risk classifications.
- Cardiology:Implantable pacemakers, defibrillators, and external monitoring systems face Class III device regulations with extensive clinical evidence requirements. Melbourne biomedical precinct firms concentrate R&D on telemetry-integrated arrhythmia detection.
- Orthopedics:Joint replacement implants and surgical navigation tools serve aging demographics with high procedural volumes in Sydney and Melbourne private hospitals.
- Neurology:Deep brain stimulation and epilepsy monitoring devices address smaller patient populations with premium pricing.
- Urology:Endoscopic tools and incontinence management systems span diagnostic and therapeutic indications.
Cardiology captures the deepest regulatory investment; Orthopedics shows the steepest expansion trajectory as robotic-assisted surgery proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's medtech production concentrates in Victoria and New South Wales, while consumption spreads across state hospital networks with distinct procurement frameworks. This geographic split shapes where firms locate R&D versus sales operations.
New South Wales
Sydney's tertiary hospitals drive demand for high-acuity capital equipment through Health Infrastructure NSW consolidated purchasing. TGA's software-as-a-medical-device framework governs AI diagnostic approvals sought by local developers. The Westmead Health Precinct anchors medical imaging and pathology automation pilots.
Victoria
Melbourne's biomedical precinct hosts implantable device manufacturers and cardiac monitoring specialists serving public hospital telemetry programs. State-level procurement through HealthShare Victoria standardizes device fleets across metropolitan networks. The Parkville medical research cluster concentrates preclinical testing and regulatory consulting capacity.
Queensland
Regional health networks outside Brisbane present underpenetrated demand for connected diagnostic platforms. Federal aged care technology mandates accelerate wearable adoption for chronic disease management in Townsville and Cairns. The Queensland Health procurement office consolidates purchasing authority for distributed care models.
Western Australia
Perth's private hospital sector drives demand for surgical navigation and robotic-assisted systems. Component import dependency exposes local assemblers to shipping volatility through Fremantle port logistics. The Fiona Stanley Hospital precinct hosts telehealth infrastructure serving remote patient populations.
Australia Medtech Market Key Industry Players
Capital-heavy producers compete with asset-light designers across Australia's medtech base, with implantable device manufacturers maintaining captive manufacturing while diagnostic software firms outsource hardware production. The market structures around three tiers: multinational subsidiaries with established TGA registrations, domestic mid-caps leveraging local clinical relationships, and emerging SaaS platforms seeking SaMD pathway authorization. Strategic moves concentrate on securing HealthShare Victoria and NSW Health Infrastructure procurement contracts, plus building EMR interoperability with Cerner and Epic deployments.
Among ASX-listed device specialists, Cochlear Limited and ResMed Inc. exemplify the integrated hardware-service archetype, anchoring revenue through implant ecosystems and cloud-connected therapy platforms respectively. Device Technologies occupies a position within the distribution-centric tier, controlling access pathways across tertiary hospitals and private surgical centers. These three firms represent divergent responses to TGA's digital health framework, with varying emphasis on recurring licensing versus capital equipment sales.
| Leading Market Players |
|---|
| Cochlear Limited |
| ResMed Inc. |
| Paragon Care Group |
| Device Technologies |
| Alcidion Group Limited |
| Anatomics Pty Ltd |
| Sirtex Medical Limited |
| Artrya |
| Pro Medicus |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up distribution specialists now control hospital procurement channels across New South Wales and Victoria, compressing vendor margins while concentrating negotiating leverage in fewer hands. This ownership consolidation reshapes both upstream component sourcing discipline and downstream pricing power for device manufacturers competing under TGA's escalating compliance burden.
Pricing Analysis
Margin tightening in mid-tier diagnostic equipment reflects HealthShare Victoria's multi-year fleet standardization contracts, which trade volume guarantees for single-digit price escalators. Three-tier pricing structure across premium, standard, and economy levels separates TGA Class III implantables from Class IIa diagnostics and unregulated consumables. Cost compression accelerates in surgical instruments as leasing models for robotic platforms displace capital purchases. Public hospital procurement committees exhibit highest price sensitivity, while private surgical centers absorb premium positioning for brand reputation and after-sales service bundling.
Supply Chain Analysis
Domestic-content mandates remain absent in Australian medtech procurement, leaving assemblers exposed to East Asian component concentration without local sourcing requirements. Precision sensors and semiconductor substrates draw from Taiwan, South Korea, and Japan, while lithium-ion cells and biosensor membranes hinge on Chinese chemical processing. Single-source vulnerability concentrates in advanced imaging sensor arrays where replacement qualification spans 18-24 months. Distribution runs through Device Technologies and Paragon Care Group networks that consolidate logistics across tertiary hospital systems and private surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
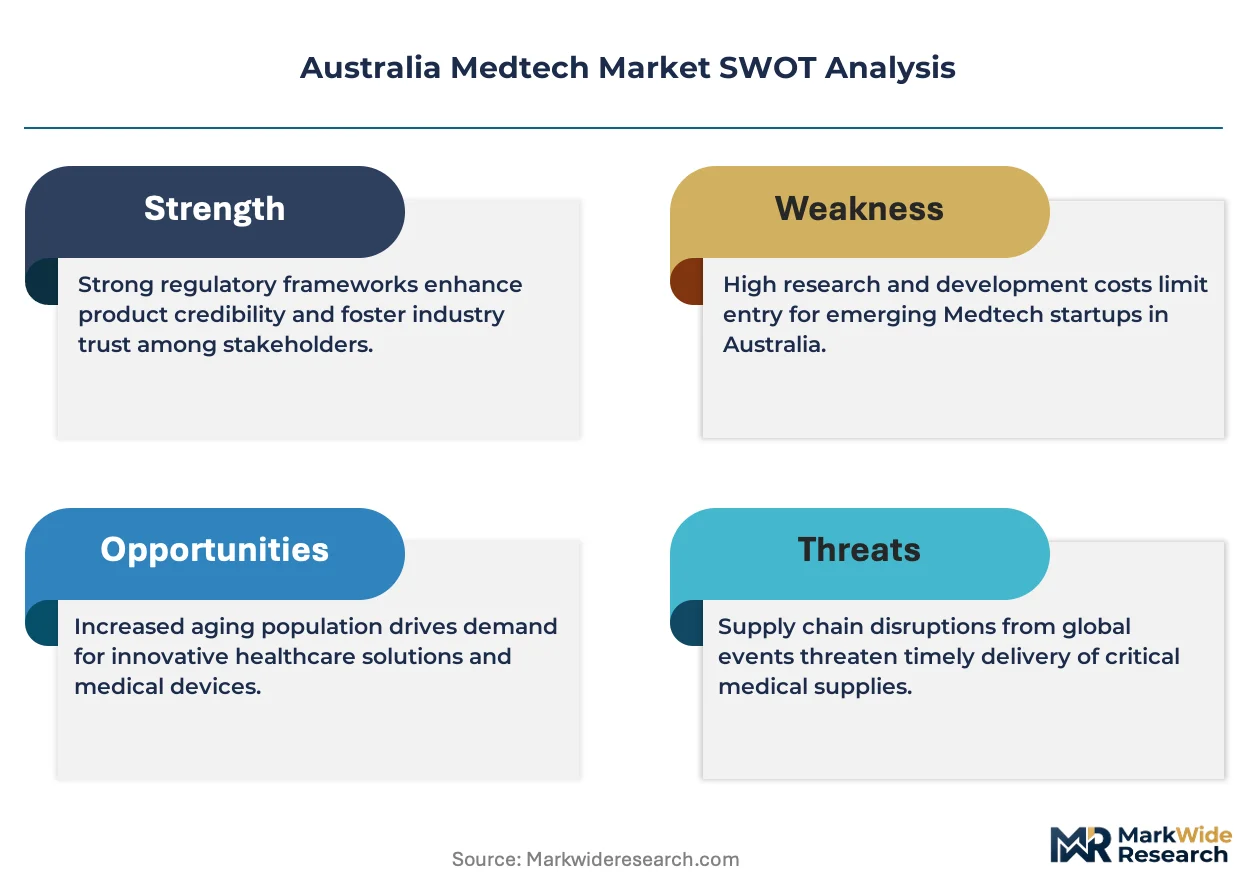
TGA's software-as-a-medical-device framework has erected a cost-of-compliance barrier that favors incumbents with dedicated clinical affairs teams and pre-submission track records, locking out capital-constrained challengers.
For Market Incumbents: Deepen algorithm validation capabilities to defend against AI-native diagnostics entrants seeking SaMD pathway fast-track. Build backward integration into precision sensor supply through strategic partnerships with Taiwanese foundries, insulating against shipping volatility while capturing margin pools currently leaking to East Asian subcontractors. For New Entrants and Emerging Players: Capture Queensland regional health networks where HealthShare Victoria-style procurement consolidation has not yet displaced individual hospital tendering. Target cloud-connected cardiac monitoring for distributed care models, leveraging federal aged care technology mandates as reimbursement tailwind alongside NDIS funding expansion for assistive devices. For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 13485-MDSAP dual-certified device firms in Melbourne biomedical precinct with established TGA registration portfolios. Long-term viability centers on SaaS revenue attach rates exceeding hardware depreciation cycles; watch for inflection when hospital EMR interoperability standards mature sufficiently to reduce redundant integration costs.| Strategic Initiative | Industry Significance |
|---|---|
| TGA SaMD Pre-Submission Investment | Accelerates market authorization timelines for AI-enabled diagnostics competing against established pathology workflows. |
| HealthShare Victoria Procurement Contract | Locks multi-year revenue visibility through state-level fleet standardization across metropolitan hospital networks. |
| Cerner-Epic EMR Interoperability Build | Reduces integration friction for cloud-based remote monitoring platforms seeking hospital adoption. |
| NDIS Eligible Equipment Category Expansion | Opens reimbursement pathways for rehabilitation robotics and assistive devices in post-acute care settings. |
| MDSAP Certification Alignment | Enables simultaneous Australian and FDA market access without duplicative audit overhead for export-oriented manufacturers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and TGA regulatory consultants. TGA software-as-a-medical-device guidance documents, HealthShare Victoria procurement frameworks, and NSW Health Infrastructure tender databases provided institutional sourcing. Bottom-up device shipment estimates triangulated against top-down healthcare expenditure flows from Australian Institute of Health and Welfare aggregates.
Reconciliation of unit economics, reimbursement code valuations, and capital expenditure cycles shaped the analytical framework across the projection horizon. Segmentation dimensions spanned product type, end user, delivery mode, and application, with TGA risk classification tiers introducing regulatory-cluster granularity. CAGRs derived from fitted growth curves calibrated to historical procurement cycle lengths and technology replacement patterns. Forecast inputs incorporated state-level health department budget trajectories and NDIS funding envelope expansions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to TGA algorithm validation requirement changes and East Asian semiconductor supply disruptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
Pressure Mapping Systems in Healthcare Market
Medical Devices
Coronary Guidewires Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
Cyberknife Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Nanomedical Devices Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Global Medical Kiosk Market
Medical Devices
Global Stent Graft Balloon Catheter Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
ADA Substitute Market
Medical Devices
Implantable Defibrillators Market