
 Mediastinoscope Market | 2026-2036
Mediastinoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Mediastinoscope Market Insights
The shortage of thoracic surgeons trained in advanced endoscopic staging is unwinding capacity expansion across major health systems. Olympus Corporation leverages its integrated imaging stack to dominate video mediastinoscope placements in academic medical centers. Karl STORZ SE & Co. KG anchors its position through rigid instrument specialization and direct hospital service networks. Boston Scientific Corporation competes by extending its interventional pulmonology portfolio into navigated biopsy platforms.
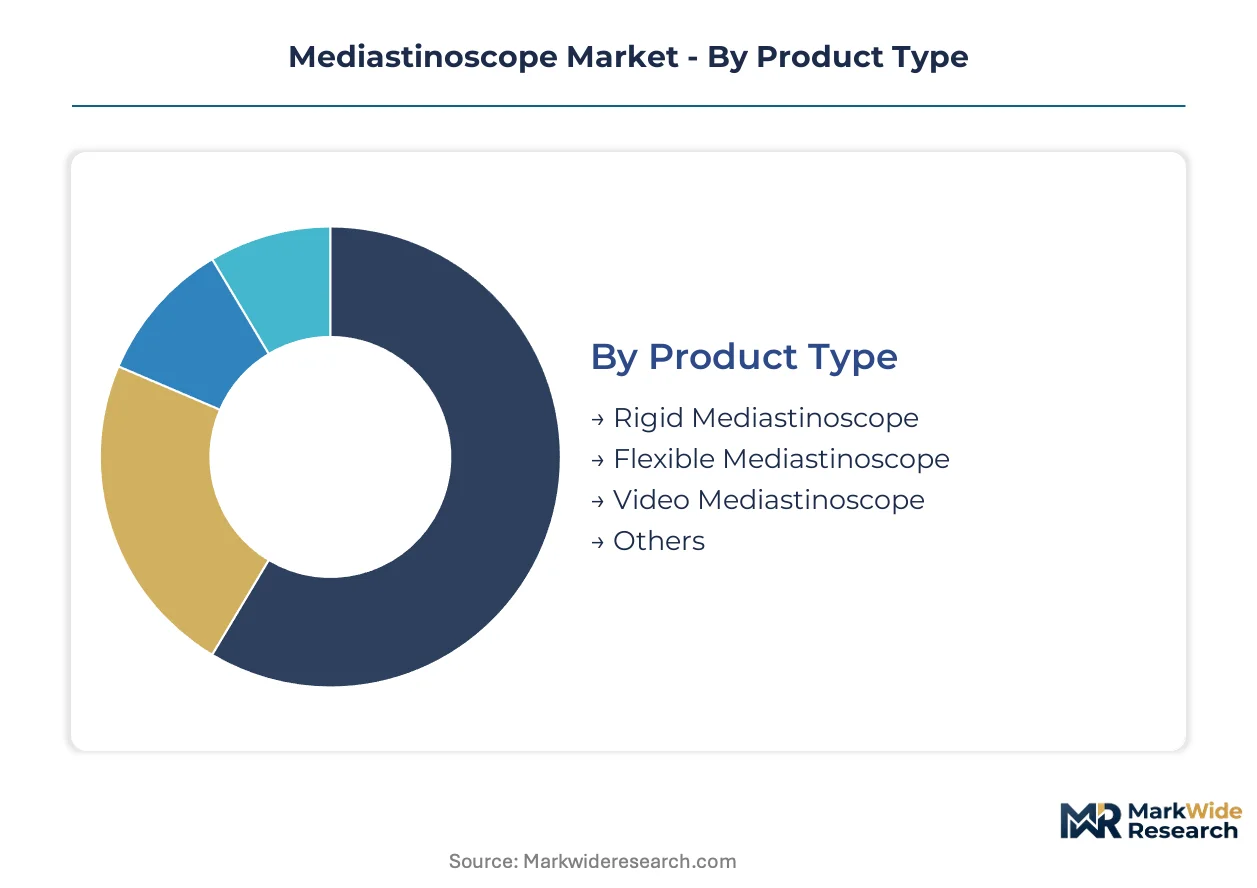
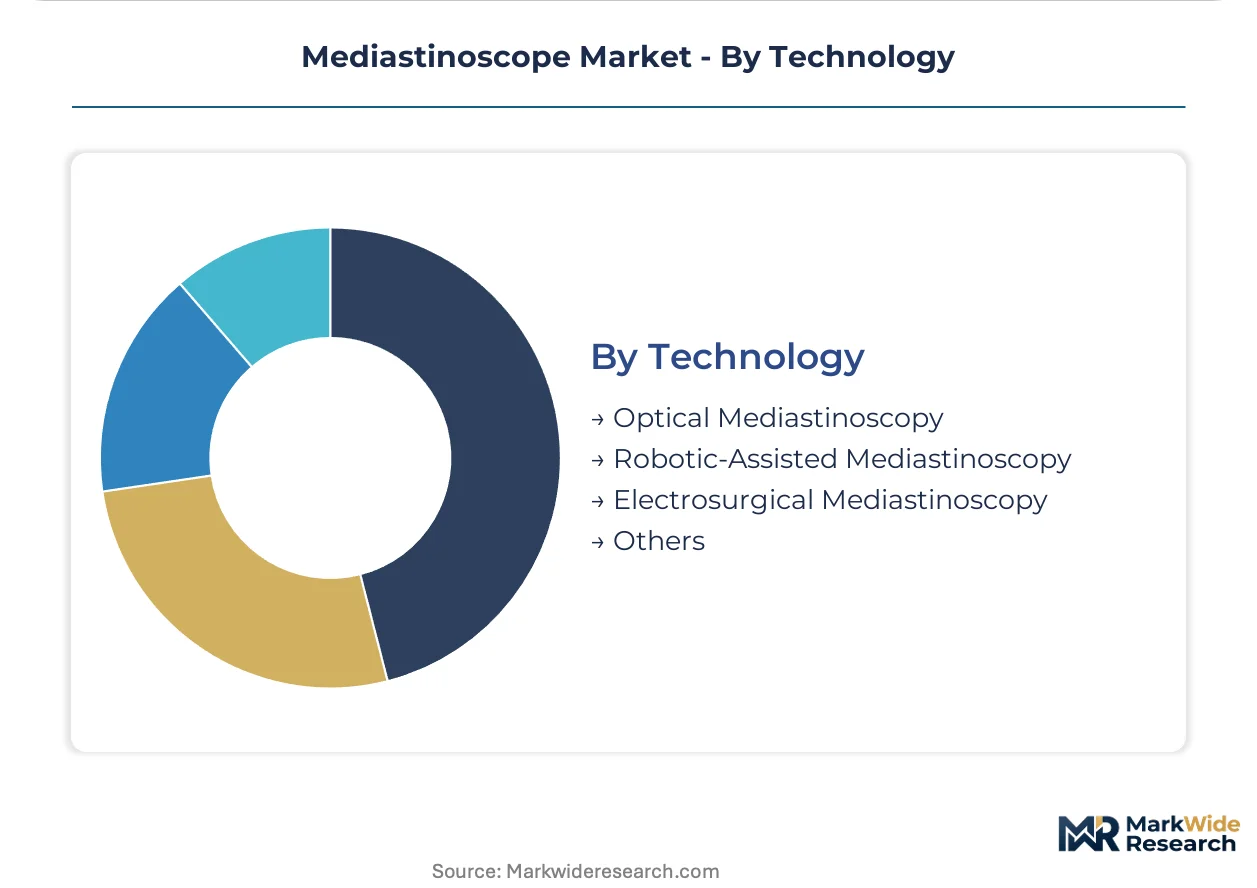
A mediastinoscope is a rigid or flexible endoscopic instrument, typically 5–10 mm in diameter with integrated fiberoptic or digital video channels, designed for visual examination and tissue sampling within the mediastinum through a cervical incision. The device enables direct visualization of paratracheal and subcarinal lymph node stations to stage lung cancer and diagnose mediastinal pathology without thoracotomy. Video mediastinoscopes now command the premium tier as hospitals replace aging optical systems with high-definition platforms that support teaching and documentation. Robotic-assisted mediastinoscopy represents the fastest-growing technology segment, though electrosurgical platforms retain the largest installed base due to lower capital requirements and broader surgeon familiarity. Rigid instruments still occupy the majority of procedural volume, particularly in lymph node dissection applications where instrument stability proves critical.
FDA 510(k) pathways govern device clearance in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements for reusable surgical endoscopes. Japan's PMDA maintains distinct biocompatibility and sterilization validation standards that shape product design for Asian markets. Stakeholders must monitor reimbursement coding evolution for robotic-assisted thoracic procedures, as coverage decisions will determine whether capital-intensive platforms achieve sustainable utilization rates.
Market Dynamics
The transition from fiberoptic to digital video mediastinoscopes is compressing replacement cycles in tertiary hospitals and academic medical centers, forcing manufacturers to accelerate imaging stack integration while surgical training programs scramble to update competency curricula.
Growth Catalysts
- Lung Cancer Screening Expansion:National screening programs in the United States, Germany, and Japan are driving procedural volume for mediastinal staging, creating sustained demand for both rigid and video-assisted platforms.
- EU Medical Device Regulation (MDR):Strengthened clinical evidence requirements for reusable surgical endoscopes are accelerating hospital upgrades to validated video systems that meet post-market surveillance standards.
- Robotic-Assisted Platforms:Capital investment in navigated biopsy systems is expanding the addressable procedural base beyond traditional thoracic surgery into interventional pulmonology departments.
Market Restraints
- Thoracic Surgeon Shortage:Limited fellowship training capacity in advanced endoscopic staging is constraining procedural throughput across major health systems regardless of equipment availability.
- Capital Intensity:High-definition video stacks and robotic platforms require substantial upfront investment, creating procurement friction at mid-tier hospitals and regional medical centers.
- Reimbursement Uncertainty:Evolving CPT coding for robotic-assisted thoracic procedures creates utilization risk for capital-intensive installations before coverage determinations stabilize.
Strategic Opportunities
- Service Contract Unbundling:After-sales maintenance and sterilization validation services represent underdeveloped revenue streams as hospitals seek to outsource device lifecycle management.
- Japan PMDA Pathway Optimization:Distinct biocompatibility and sterilization standards create first-mover advantage for manufacturers designing Asian-market-specific product variants.
- Interventional Pulmonology Convergence:Integration of electromagnetic navigation with mediastinoscope platforms opens procedural access to physicians without formal thoracic surgery training.
Industry Challenges
- Cross-Functional Training Gaps:Operating room teams require coordinated competency in video system troubleshooting, electrosurgical safety, and specimen handling protocols.
- Legacy Optical System Integration:Hospitals with substantial fiberoptic installed base face workflow disruption and capital write-downs during phased digital transitions.
- Sterilization Validation Complexity:Reusable instrument reprocessing requirements under FDA and MDR frameworks extend quality assurance timelines and increase liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mediastinoscope Market |
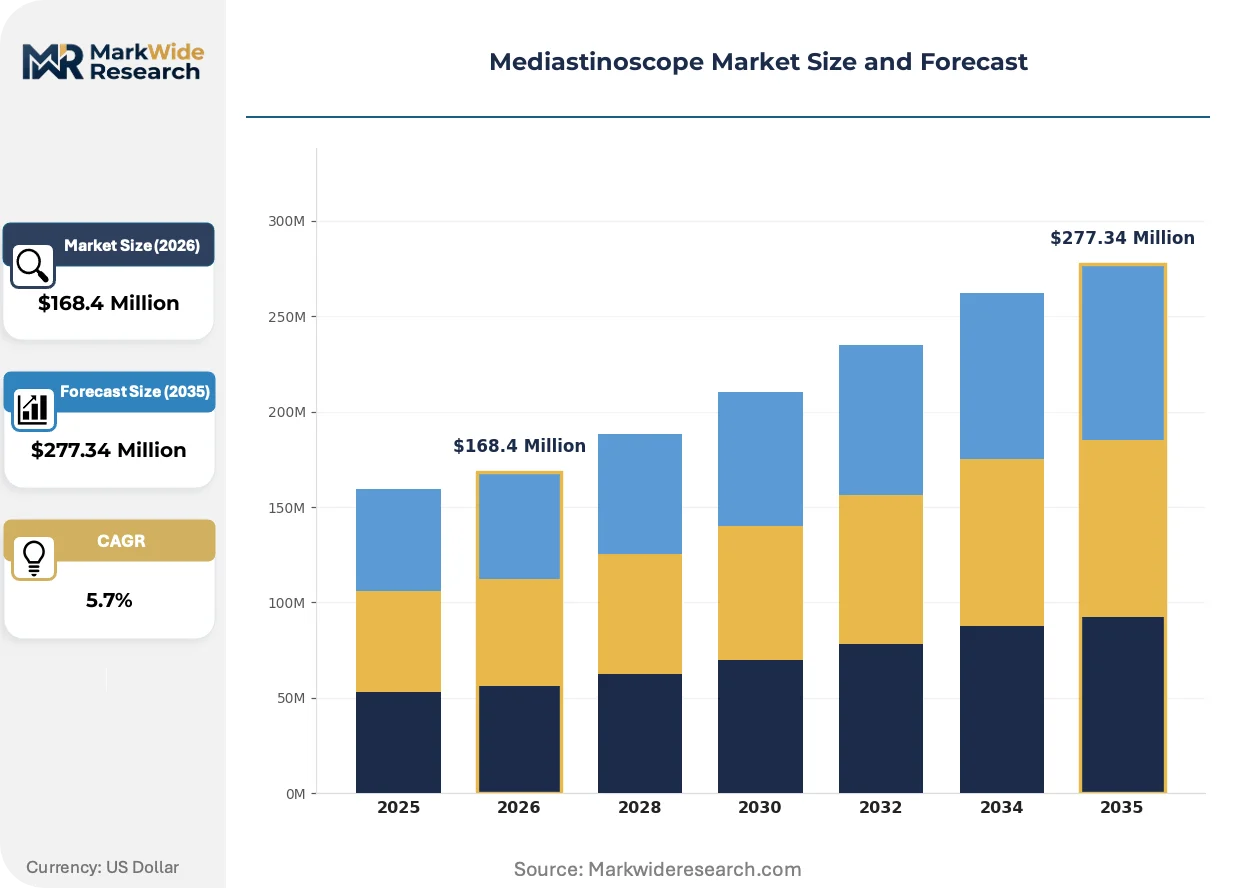
| Market Size in 2026 | $168.4 Million |
| Market Size in 2035 | $277.34 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Mediastinoscope, Flexible Mediastinoscope, Video Mediastinoscope, Others Application: Lung Biopsy, Mediastinal Lymph Node Dissection, Tumor Resection, Others End User: Hospitals, Surgical Centers, Clinics, Research Institutes Technology: Optical Mediastinoscopy, Robotic-Assisted Mediastinoscopy, Electrosurgical Mediastinoscopy, Others |
| Companies Covered | Olympus Corporation, Karl STORZ SE & Co. KG, Boston Scientific Corporation, FUJIFILM Corporation, HOYA Corporation, Stryker, Medtronic plc, Medline Industries, Inc., Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mediastinoscope Market Trends and Innovations
Digital imaging convergence and procedural navigation technologies are redefining competency boundaries between thoracic surgery and interventional pulmonology, while regulatory frameworks on both sides of the Atlantic reshape product development priorities.
High-definition CMOS sensor technology is miniaturizing within rigid mediastinoscope shafts, enabling 4K visualization through 5-7 mm instruments without compromising instrument stability. Academic medical centers in the United States and Germany are replacing aging fiberoptic towers at accelerated pace. This compression of replacement cycles is forcing manufacturers to bundle imaging processors with instrument sales rather than maintaining standalone upgrade paths.
The EU Medical Device Regulation's strengthened clinical evidence requirements for reusable surgical endoscopes are extending time-to-market for new mediastinoscope submissions. Manufacturers must now maintain post-market surveillance systems and periodic safety update reports across their installed European base. Video mediastinoscope platforms with pre-validated sterilization protocols command procurement preference as hospitals seek to minimize regulatory compliance burden.
Hospital procurement committees are consolidating vendor relationships for thoracic surgery platforms, bundling mediastinoscopes with staplers, energy devices, and robotic navigation systems under multi-year enterprise agreements. This concentration of purchasing authority is displacing traditional distributor networks in favor of direct manufacturer contracting. The shift is most visible in United States integrated delivery networks and German hospital federations seeking volume-based pricing leverage.
Mediastinoscope Market Segmentation
Mediastinoscope procurement varies sharply across facility tiers and procedural applications, with regulatory validation requirements and capital intensity driving divergent adoption patterns. Understanding these segment boundaries clarifies where manufacturers must customize imaging stacks, sterilization protocols, and service architectures.
Product Type:
FDA 510(k) clearance timelines and EU MDR clinical evidence requirements create divergent competitive moats across instrument categories, with reusable validation protocols favoring established platforms over novel entrants.
- Rigid Mediastinoscope:Stainless steel shafts with fixed optical channels deliver instrument stability critical for lymph node dissection. Demand concentrates in German university hospitals and United States academic medical centers where thoracic surgery departments prioritize tactile feedback and dissection precision over imaging flexibility.
- Video Mediastinoscope:Integrated CMOS sensors and high-definition processors enable 4K visualization through 5-7 mm rigid shafts. Japanese tertiary hospitals and United States integrated delivery networks are replacing aging fiberoptic towers, compressing replacement cycles as procurement committees bundle imaging stacks with instrument sales.
- Flexible Mediastinoscope:Deflectable distal tips with steerable channels accommodate anatomical variation in subcarinal access. Adoption remains limited by instrument stability constraints during nodal dissection.
- Others:Disposable single-use variants and hybrid platforms occupy niche applications where sterilization validation burden exceeds capital efficiency thresholds.
Established volume favors rigid instruments; emerging adoption favors video platforms.
Application:
Procedural reimbursement coding and clinical outcome data shape capital allocation across surgical departments, with staging accuracy requirements driving technology selection.
- Lung Biopsy:Tissue acquisition for histopathological diagnosis demands visualization precision and sampling instrument compatibility. United States lung cancer screening expansion and Japan's CT-screening protocols are driving procedural volume in interventional pulmonology departments seeking navigated biopsy integration.
- Mediastinal Lymph Node Dissection:Systematic nodal sampling for lung cancer staging requires instrument stability and electrosurgical capability. German thoracic surgery federations and United States National Comprehensive Cancer Network centers maintain rigid instrument preference for complete dissection protocols.
- Tumor Resection:En-bloc mediastinal mass removal combines visualization with energy device integration. Application volume concentrates in high-complexity referral centers.
- Others:Diagnostic mediastinitis evaluation and congenital anomaly assessment represent sporadic demand with limited technology differentiation.
Staging protocols anchor lymph node dissection volume; biopsy applications are climbing the fastest as screening programs expand addressable patient pools.
End User:
Capital availability and procedural case-mix determine purchasing authority concentration, with service contract complexity favoring direct manufacturer relationships over distributor networks.
- Hospitals:Tertiary academic centers and community hospital systems command the installed base, with United States integrated delivery networks and German hospital federations consolidating vendor relationships under multi-year enterprise agreements.
- Surgical Centers:Ambulatory facilities with limited thoracic surgery volume favor flexible platforms and outsourced sterilization validation to minimize regulatory compliance burden.
- Clinics:Pulmonology practices with diagnostic staging requirements drive demand for compact video systems with simplified workflow integration.
- Research Institutes:Preclinical and outcomes research applications generate limited but high-specification demand for advanced imaging and navigation platforms.
Procurement concentration favors hospital systems; point-of-care expansion favors clinic and surgical center segments.
Technology:
Surgeon training pathways and capital depreciation schedules create technology lock-in, with robotic platforms requiring interventional pulmonology convergence to expand beyond thoracic surgery departments.
- Optical Mediastinoscopy:Fiberoptic light transmission through rigid scopes retains installed base in mature European markets where capital replacement cycles lag digital adoption. German and Japanese facilities with validated sterilization protocols for fiberoptic towers face workflow disruption during phased transitions.
- Robotic-Assisted Mediastinoscopy:Navigated biopsy platforms with electromagnetic tracking extend procedural access to physicians without formal thoracic surgery training. United States interventional pulmonology departments and Japanese advanced endoscopy centers are expanding capital investment despite reimbursement coding uncertainty.
- Electrosurgical Mediastinoscopy:Integrated energy devices for hemostasis and tissue dissection command the largest installed base due to lower capital requirements and broader surgeon familiarity across United States community hospitals.
- Others:Confocal laser endomicroscopy and augmented reality overlay systems remain investigational with limited commercial validation.
Electrosurgical platforms dominate current utilization; robotic-assisted systems are gaining share fastest as navigation technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mediastinoscope utilization patterns diverge sharply across major markets, with the United States and Germany prioritizing rigid instruments for systematic lymph node dissection while Japan accelerates video platform adoption for screening-integrated workflows.
United States
Lung cancer screening expansion under the U.S. Preventive Services Task Force guidelines is driving procedural volume for mediastinal staging in academic medical centers. FDA 510(k) clearance pathways for video-assisted platforms are compressing time-to-market for new device entrants. Integrated delivery networks in Texas and the Northeast Corridor are consolidating vendor relationships under multi-year enterprise agreements that bundle imaging stacks with instrument procurement.
Germany
Thoracic surgery federations maintain rigid instrument preference for complete dissection protocols mandated by national cancer care standards. EU Medical Device Regulation strengthened clinical evidence requirements are accelerating hospital upgrades to validated video systems with pre-established sterilization protocols. University hospitals in Bavaria and North Rhine-Westphalia anchor demand concentration as regional referral centers for complex mediastinal pathology.
Japan
CT-based lung cancer screening protocols generate sustained demand for diagnostic mediastinoscopy in tertiary hospitals. PMDA maintains distinct biocompatibility and sterilization validation standards that shape product design for domestic manufacturers. Advanced endoscopy centers in the Kanto and Kansai regions are expanding capital investment in navigated biopsy platforms despite reimbursement coding uncertainty.
United Kingdom
National Health Service cancer pathway targets are expanding minimally invasive staging capacity across thoracic surgery networks. MHRA operates under retained EU MDR alignment for device registration, maintaining equivalent clinical evidence thresholds for reusable surgical endoscopes. London and Southeast England hospital trusts concentrate procurement authority for high-definition video systems that support teaching and documentation requirements.
China
Rising lung cancer incidence is expanding addressable patient pools for mediastinal staging procedures in provincial tertiary hospitals. NMPA device registration pathways are lengthening for imported reusable surgical instruments as domestic validation requirements tighten. Yangtze River Delta medical centers in Shanghai and Jiangsu are piloting robotic-assisted platforms through hospital-industry collaboration agreements.
Mediastinoscope Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding procurement relationships through bundled imaging stacks and the latter competing on instrument specialization and direct service networks. The structure consolidates around three archetypes: diversified endoscopy conglomerates with full-stack imaging integration, rigid instrument specialists with deep surgeon training relationships, and interventional pulmonology platform extenders seeking navigation convergence. Dominant competitive moves include portfolio diversification into robotic-assisted systems and geographic expansion through direct hospital contracting that displaces traditional distributor networks.
Within the diversified imaging tier, Olympus Corporation and FUJIFILM Corporation represent integrated endoscopy conglomerates leveraging CMOS sensor and processor manufacturing depth. Karl STORZ SE & Co. KG anchors the rigid instrument specialist position through its German manufacturing heritage. Boston Scientific Corporation exemplifies the interventional pulmonology extender archetype, occupying a position where navigated biopsy platform development converges with mediastinal access technology.
| Leading Market Players |
|---|
| Olympus Corporation |
| Karl STORZ SE & Co. KG |
| Boston Scientific Corporation |
| FUJIFILM Corporation |
| HOYA Corporation |
| Stryker |
| Medtronic plc |
| Medline Industries, Inc. |
| Merit Medical Systems |
| Others |
Pricing and Supply Chain Analysis
Ninety-day sterilization validation cycles for reusable surgical endoscopes compress inventory turns and concentrate pricing power with manufacturers holding pre-validated MDR documentation, while hospitals face capital write-downs on aging fiberoptic towers that limit procurement flexibility.
Pricing Analysis
Long-term enterprise agreements dominate hospital procurement, with United States integrated delivery networks and German hospital federations bundling imaging stacks, instruments, and service contracts under multi-year offtake structures. Price differentiation separates video platforms with 4K CMOS integration from standard-definition optical systems, with FDA 510(k) clearance tier and sterilization protocol validation commanding premiums. Cost compression in mid-tier hospital segments is intensifying because procurement committees consolidate vendor relationships to extract volume leverage. Community hospitals and regional medical centers exhibit highest price sensitivity due to capital constraint, while academic medical centers prioritize imaging performance over unit cost.
Supply Chain Analysis
Germany and Japan anchor precision instrument manufacturing for rigid mediastinoscope shafts and optical components, with the United States commanding CMOS sensor and imaging processor production. Supply chains draw from stainless steel surgical-grade alloys, fiberoptic cable assemblies, and high-definition camera modules. Single-source vulnerability concentrates in specialized electrosurgical generator integration, where few suppliers meet FDA biocompatibility requirements. Distribution runs through direct manufacturer contracting with hospital procurement committees, displacing traditional distributor networks as integrated delivery networks consolidate purchasing authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as lung cancer screening program expansion drives replacement demand for aging fiberoptic systems, with procedural volume growth creating sustainable equipment upgrade cycles.
For Market Incumbents: Compound installed base advantage by integrating imaging processors with instrument sales to lock hospital procurement committees into multi-year service contracts, while accelerating sterilization validation documentation to capture EU MDR-driven upgrade demand. Threat from interventional pulmonology platform extenders demands defensive certification investment in navigated biopsy compatibility. For New Entrants and Emerging Players: Lead with robotic-assisted platform development targeting Japanese advanced endoscopy centers and United States interventional pulmonology departments, where reimbursement coding uncertainty has frozen incumbent capital deployment. White-space opportunity concentrates in compact video systems for clinic-based diagnostic staging, with go-to-market through GPO contract participation offering fastest hospital access. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement authority concentration favors diversified imaging conglomerates with full-stack manufacturing depth over specialist instrument manufacturers. Acquisition target archetype: rigid instrument specialists with validated German manufacturing heritage and direct hospital service networks. Signal to watch is stabilization of robotic-assisted thoracic procedure reimbursement coding, which would unlock capital deployment for navigated platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses time-to-market for video mediastinoscope platforms in United States academic medical centers. |
| Hospital System Partnership | Locks procurement relationships through bundled imaging stack and instrument enterprise agreements. |
| CE Marking Pathway Investment | Captures EU MDR-driven upgrade demand with pre-validated sterilization protocols. |
| Software Companion Development | Enables electromagnetic navigation integration for interventional pulmonology department expansion. |
| Reimbursement Strategy | Secures coverage determination for robotic-assisted thoracic procedures before competitor platform deployment. |
Research Methodology
Initial hypotheses were tested against primary input from thoracic surgeons, hospital procurement committee directors, biomedical engineers, and GPO contracts managers, and refined through secondary validation against FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up instrument shipment analysis triangulated with top-down procedural volume estimates across lung cancer screening programs.
Variance decomposition across product type, application, end user, technology, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from modeled replacement cycle compression and procedural volume expansion across the projection horizon. Forecast inputs incorporated thoracic surgeon fellowship training capacity constraints and sterilization validation timeline assumptions.
The analysis sits within stated boundaries; outcomes outside sustained lung cancer screening program funding or stabilized robotic reimbursement coding would require recalibration. Forecasts reflect documented assumptions regarding EU MDR compliance timelines and PMDA biocompatibility standard evolution. Recalibration cycles align with material shifts in national screening program expansion or regulatory framework amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Tracheostomy Tubes Market
Medical Devices
Global Ileostomy Market
Medical Devices
Cyberknife Market
Medical Devices
High Volume Dispensing Systems Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Anesthesia Circuits Market
Medical Devices
Global Automated Suturing Devices Market
Medical Devices
Facial Pumps Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
Active Humidifier Devices Market
Medical Devices
Europe Breast Implant Market
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market
Medical Devices
AI Colonoscopy Withdrawal Quality Monitoring System Market
Medical Devices
Endoscopic Mucosal Resection Device Market
Medical Devices
Italy Medical Device Regulatory Affairs Market