
 Healthcare Biosensors IoT Market | 2026-2036
Healthcare Biosensors IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Biosensors IoT Market Intelligence
The substitution of rigid silicon substrates with flexible polymers for wearable sensors is hardening the economic case for continuous patient monitoring. Medtronic leverages its extensive portfolio in implantable devices to integrate advanced sensor technologies. Abbott Laboratories dominates the continuous glucose monitoring space with its specialized electrochemical sensor platforms. Siemens Healthineers competes by integrating sensor data into its broader digital health and diagnostic imaging ecosystems.
Healthcare biosensors for IoT are analytical devices that convert a biological response from an analyte into a transmissible digital signal. These systems typically pair a bioreceptor with a physicochemical transducer to enable remote, real-time physiological data collection. Wearable sensors represent the largest product category by volume, driven by ease of use in non-clinical settings. Within applications, chronic disease management commands the highest value, while home care settings exhibit the most rapid expansion among end users.
Regulatory frameworks from the US FDA and the European Medicines Agency (EMA) mandate stringent clinical validation and cybersecurity protocols for connected medical devices. In parallel, market access into China requires adherence to NMPA standards for data localization and device approval. A critical strategic decision for all vendors revolves around developing open, interoperable data platforms versus creating closed, proprietary ecosystems to lock in users.
Market Dynamics
The convergence of advanced material science, specifically the use of flexible polymers, with stringent data security mandates from global regulators like the FDA and EMA, is the central force shaping the Healthcare Biosensors IoT market's competitive and product development landscape.
Growth Catalysts
- Regulatory Mandates:The European Union's Medical Device Regulation (MDR) imposes higher clinical evidence and post-market surveillance requirements, compelling manufacturers to develop more sophisticated and reliable biosensor systems for market access.
- Material Science Advancement:The substitution of rigid silicon with flexible polymer substrates in wearable sensors enhances patient comfort and compliance for long-term use, directly supporting expansion in the continuous monitoring of chronic diseases.
- Chronic Disease Prevalence:A rising incidence of conditions like diabetes and cardiovascular disease globally, particularly in aging populations, creates persistent demand for remote patient monitoring solutions in home care settings.
Market Restraints
- High Validation Costs:The substantial financial and time investment required for clinical trials to meet stringent validation protocols from bodies like the US FDA and EMA acts as a significant barrier to entry for smaller innovators.
- Interoperability Deficits:A lack of standardized data protocols across different proprietary device ecosystems creates data silos, hindering the seamless integration of patient information into centralized electronic health records (EHRs).
- Cybersecurity Vulnerabilities:The risk of data breaches in connected medical devices presents a major structural restraint, increasing liability for providers and eroding patient trust, which can slow adoption rates.
Strategic Opportunities
- Emerging Market Penetration:Expanding healthcare infrastructure and digital health initiatives in countries like India and Brazil present significant opportunities for introducing cost-effective IoT biosensor solutions for remote and rural populations.
- Predictive Analytics Integration:The convergence of biosensor data streams with AI and machine learning algorithms offers a major opportunity to shift from reactive monitoring to predictive health analytics for early disease detection.
- Decentralized Clinical Trials:Biosensors enable the collection of real-world patient data outside of traditional clinical settings, creating an opportunity to improve the efficiency and reduce the cost of pharmaceutical and medical device trials.
Industry Challenges
- Fragmented Regulatory Navigation:Manufacturers face operational complexity in securing and maintaining device approval across disparate regulatory jurisdictions, including the FDA in the US, the EMA in Europe, and the NMPA in China.
- Legacy System Integration:Integrating high-frequency data from modern IoT biosensors with older, often proprietary, hospital IT infrastructures and EHR systems presents a significant technical and logistical challenge for healthcare providers.
- Specialized Talent Scarcity:A shortage of professionals with combined expertise in medical device engineering, data science, and cybersecurity creates a bottleneck in product development and secure implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Biosensors IoT Market |
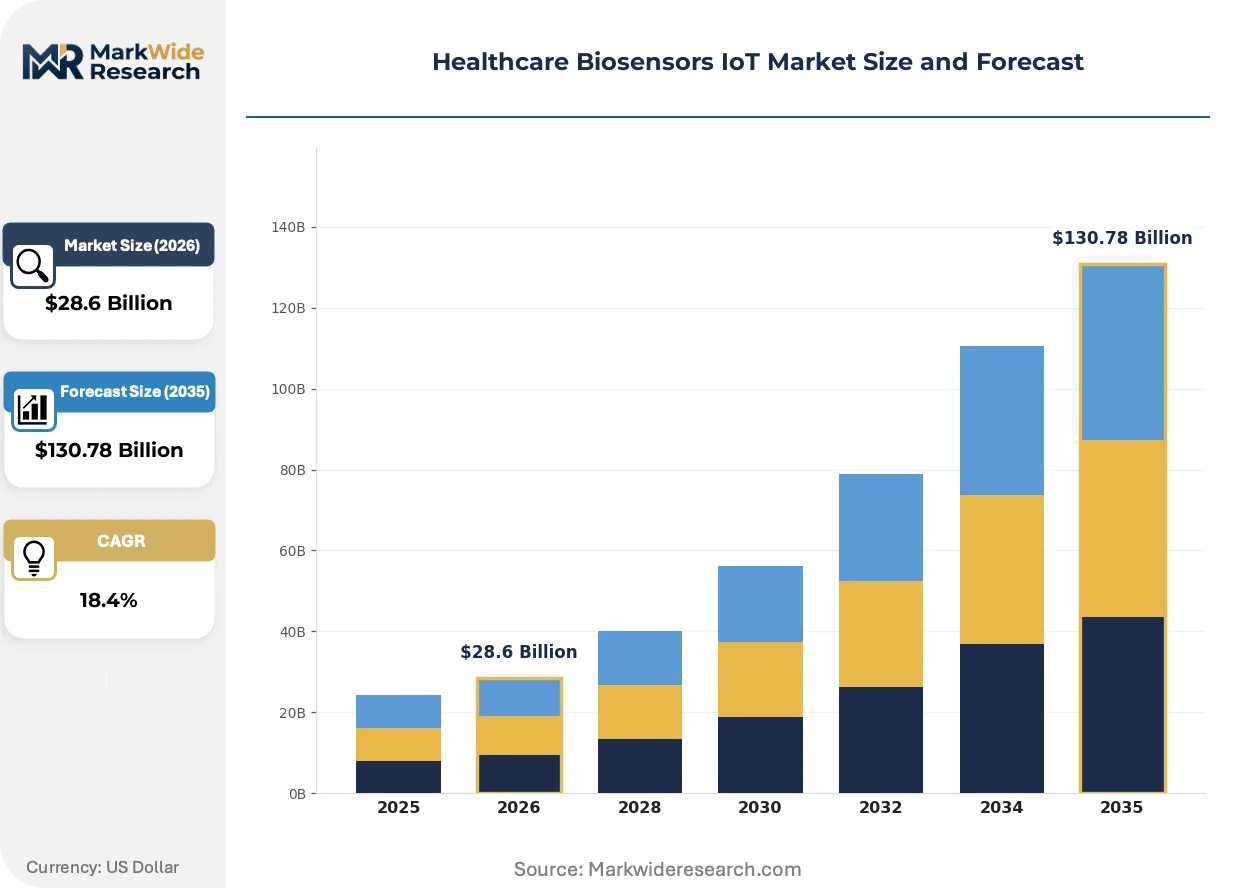
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $130.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Implantable Sensors, Non-invasive Sensors, Invasive Sensors Technology: Optical, Electrochemical, Thermal, Acoustic Application: Chronic Disease Management, Health Monitoring, Diagnostics, Rehabilitation End User: Hospitals, Home Care, Research Laboratories, Fitness Centers |
| Companies Covered | Medtronic, Abbott Laboratories, GE Healthcare, Koninklijke Philips, F. Hoffmann-La Roche Ltd, Dexcom, Boston Scientific Corporation, Siemens Healthineers, Masimo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Biosensors IoT Market Strategic Shifts & Innovations
The market's evolution is defined by a technological pivot from simple physiological data capture toward the creation of integrated, intelligent systems. This shift emphasizes diagnostic value and secure data interoperability, moving beyond the capabilities of standalone monitoring devices.
Lab-on-a-chip (LoC) technology integrates complex biochemical analyses onto a micro-scale device. Point-of-care testing facilities and diagnostic laboratories are the primary adopters, seeking to reduce sample-to-result times. This innovation is modularizing diagnostic workflows by enabling the creation of customizable, application-specific sensor arrays that can be rapidly deployed for diverse analytical needs.
Regulatory frameworks for data security are becoming more prescriptive. The US FDA's cybersecurity guidance for medical devices now requires manufacturers to implement a secure product development framework and provide a software bill of materials (SBOM). This directly impacts developers of wearable and implantable sensors, who must re-engineer data transmission and storage protocols to mitigate vulnerabilities and ensure patient safety.
A significant behavioral shift is occurring as healthcare systems move from device-centric procurement to platform-based investment. This change disrupts the traditional one-time hardware sale model in favor of vendors offering extensible ecosystems that can integrate data from various third-party sensors. This pattern is most pronounced in large hospital networks in the United States and Germany, which require unified data architectures for population health management.
Healthcare Biosensors IoT Market Segmentation
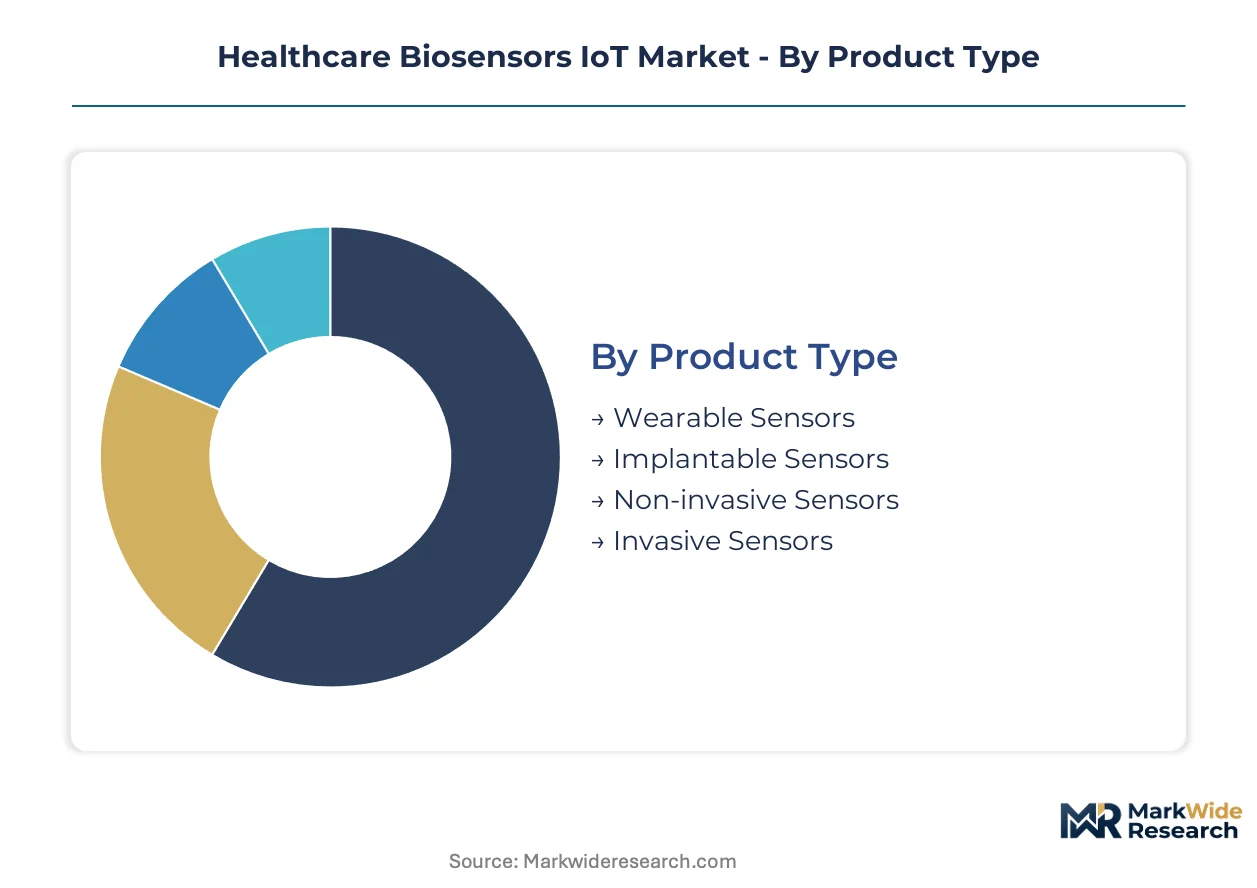
The Healthcare Biosensors IoT market exhibits distinct segmentation patterns shaped by technological advancements and evolving healthcare delivery models. Understanding these segments is crucial for identifying areas of concentrated demand and strategic investment across the diverse ecosystem.
Product Type:
Buyers in the product type category differentiate their choices based on the invasiveness and placement requirements for physiological data collection.
- Wearable Sensors:These devices are applied externally to the body, often incorporating flexible polymer substrates for enhanced comfort and user compliance. Demand concentrates in continuous monitoring for chronic diseases and wellness tracking in non-clinical settings.
- Implantable Sensors:Surgically embedded within the body, these sensors provide highly accurate, long-term data for critical physiological parameters. Medtronic leverages its extensive portfolio in implantable devices to integrate advanced sensor technologies for specialized medical applications.
- Non-invasive Sensors:These devices capture biological data without penetrating the skin, relying on technologies like optical or acoustic measurements. They are widely utilized for routine health checks and preventive monitoring in various end-user environments.
- Invasive Sensors:Requiring entry into the body, these sensors are used for precise, often short-term, measurements in clinical or diagnostic contexts.
Volume sits with Wearable Sensors; growth tilts toward Implantable Sensors.
Technology:
The selection of biosensor technology is primarily driven by the specific analytical requirements and desired application-specific functionality.
- Electrochemical:This technology detects biological reactions through electrical signals, commonly used in glucose monitoring and other metabolite assays. Abbott Laboratories dominates the continuous glucose monitoring space with its specialized electrochemical sensor platforms.
- Optical:Optical biosensors utilize light to detect changes in biological samples, enabling non-invasive measurements of heart rate, oxygen saturation, and other vital signs. These sensors are integral to many wearable devices for health monitoring.
- Thermal:Thermal biosensors measure heat changes associated with biological interactions or metabolic processes. These are often employed in diagnostic applications requiring temperature-sensitive detection.
- Acoustic:Acoustic biosensors detect mass changes on a sensor surface, translating biological binding events into measurable frequency shifts. They find utility in pathogen detection and biomarker analysis.
Precision in measurement defines the Electrochemical segment, while Optical methods expand non-invasive monitoring.
Application:
Patient outcome priorities and the criticality of real-time data collection guide the differentiation within application segments.
- Chronic Disease Management:This application involves continuous or periodic monitoring of conditions like diabetes, cardiovascular disease, and respiratory illnesses. Chronic disease management commands the highest value within the market due to the persistent demand for remote patient monitoring solutions.
- Health Monitoring:Focused on general wellness, fitness tracking, and early detection of potential health issues, this segment encompasses a broad range of consumer-grade and medical-grade devices. Wearable sensors are extensively used for health monitoring in non-clinical settings.
- Diagnostics:Biosensors in diagnostics provide rapid and accurate analysis of biological samples for disease identification and progression tracking. Lab-on-a-chip technology integrates complex biochemical analyses onto micro-scale devices for point-of-care testing facilities.
- Rehabilitation:This segment utilizes biosensors to track patient progress, monitor movement, and provide biofeedback during physical therapy or recovery. Sensor data can optimize treatment plans for improved patient outcomes.
The largest market share belongs to Chronic Disease Management, with Health Monitoring demonstrating rapid expansion.
End User:
The operational environment and preferred care delivery model significantly influence end-user procurement of IoT biosensor solutions.
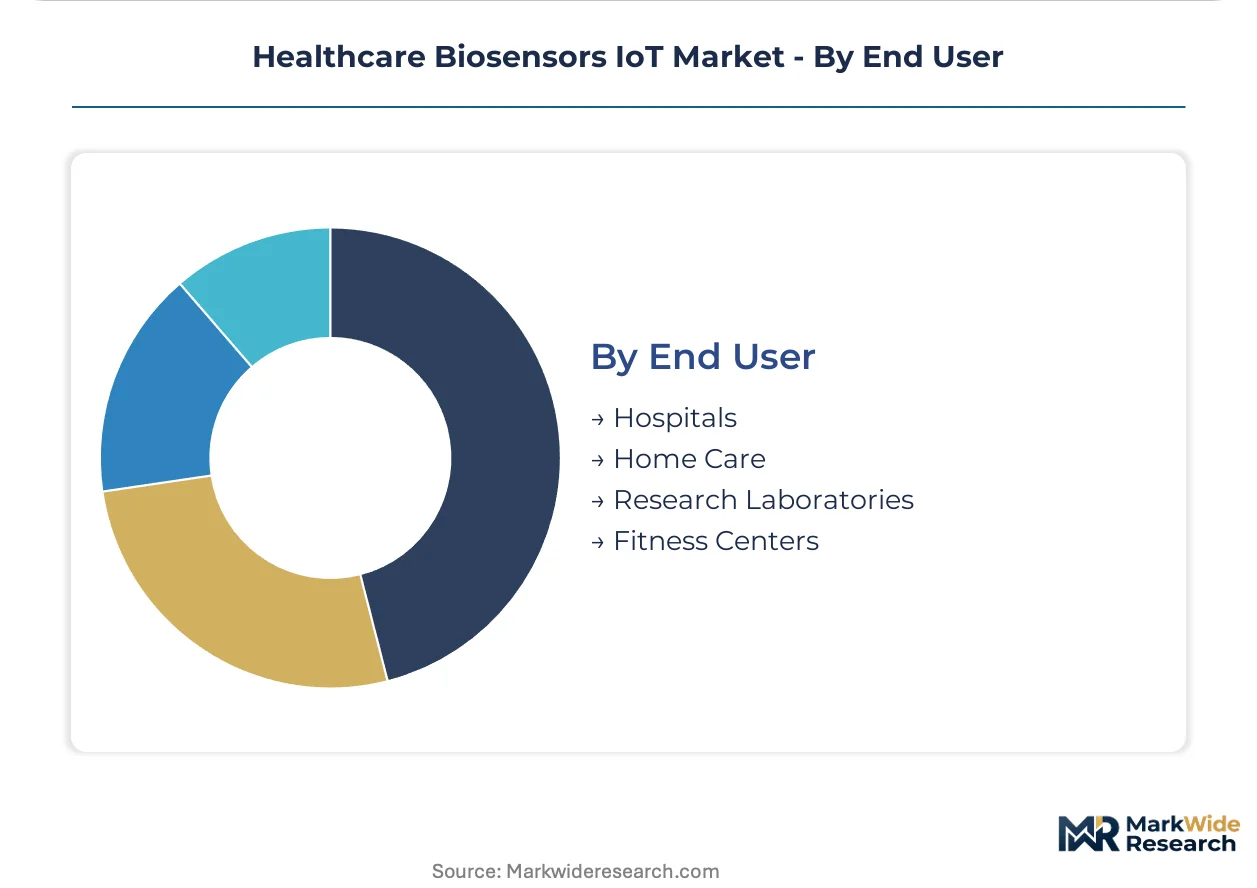
- Home Care:This segment includes patients monitoring their health remotely from home, often managing chronic conditions or recovering from illness. Home care settings exhibit the most rapid expansion among end users, driven by aging populations and cost-efficiency.
- Hospitals:Hospitals integrate biosensors into patient monitoring systems, intensive care units, and diagnostic laboratories for real-time data collection and clinical decision support. Siemens Healthineers integrates sensor data into its broader digital health and diagnostic imaging ecosystems for hospital environments.
- Research Laboratories:These facilities use biosensors for fundamental research, drug discovery, and development of new diagnostic assays. Lab-on-a-chip technology is particularly relevant for modularizing diagnostic workflows in research.
- Fitness Centers:Fitness centers employ biosensors for performance tracking, activity monitoring, and personalized exercise guidance. These applications focus on consumer wellness and athletic optimization.
Traditional institutional demand anchors Hospitals, as Home Care drives market transformation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' advanced healthcare infrastructure and significant patient monitoring needs establish it as a primary zone for healthcare biosensor IoT demand concentration. This environment fosters innovation, attracting significant investment in medical device development. Regulatory clarity from agencies like the FDA further solidifies its market position.
United States
The United States drives significant demand for healthcare biosensors, fueled by an aging population and increasing chronic disease prevalence. US FDA regulations mandate stringent clinical validation and cybersecurity protocols. Major innovation hubs like Boston and Silicon Valley host numerous firms developing cutting-edge sensor technologies.
Germany
Germany exhibits strong demand for integrated biosensor solutions within its well-developed hospital networks and digital health ecosystems. The EU's Medical Device Regulation (MDR) influences device design and data security. Cities like Erlangen and Tuttlingen form medical technology clusters, focusing on diagnostic imaging and advanced sensor integration.
China
China represents a rapidly expanding market for IoT biosensors, driven by its vast population and significant digital health initiatives. Market access into China requires strict adherence to NMPA standards for data localization and device approval. Technology hubs in the Yangtze River Delta and Pearl River Delta are actively deploying connected medical devices.
India
India offers substantial opportunities for cost-effective IoT biosensor solutions, addressing healthcare needs in remote and rural populations. The Central Drugs Standard Control Organization (CDSCO) governs medical device approval and quality standards. Bengaluru and Hyderabad are becoming centers for digital health and medical technology innovation.
United Kingdom
The United Kingdom shows sustained demand for biosensors, driven by NHS initiatives to modernize patient care and manage chronic conditions. Post-Brexit, the UK aligns with many European Medicines Agency (EMA) guidelines for medical device validation. London and Cambridge are prominent research and development hubs, fostering medical technology firm collaboration.
Healthcare Biosensors IoT Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with a notable concentration among established medical device firms. The market structure reflects a tiered landscape, featuring large diversified conglomerates, specialized sensor developers, and niche solution providers. Dominant competitive moves include strategic partnerships to integrate sensor data into broader digital health platforms and portfolio diversification into new application areas like predictive analytics. Companies also engage in geographic expansion to penetrate emerging markets and leverage localized healthcare demands.
Within the established medical device sector, Medtronic leverages its extensive portfolio in implantable devices, representing a significant player in specialized medical applications that require long-term, accurate data. Abbott Laboratories, known for its specialized electrochemical sensor platforms, exemplifies leadership in the continuous glucose monitoring space, catering to a high-demand chronic disease management segment. Siemens Healthineers, a Germany-based corporation, occupies a position integrating sensor data into its broader digital health and diagnostic imaging ecosystems, emphasizing comprehensive hospital solutions.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| GE Healthcare |
| Koninklijke Philips |
| F. Hoffmann-La Roche Ltd |
| Dexcom |
| Boston Scientific Corporation |
| Siemens Healthineers |
| Masimo |
| Others |
Cost & Logistics Intelligence
The European Union's Medical Device Regulation (MDR) gates qualified supply for biosensors, influencing premium-tier pricing for compliant devices. Manufacturers must meet these rigorous standards to access key markets.
Pricing Analysis
Short lead times for bespoke biosensor configurations command premium pricing, while standard inventory often sees volume discounts. The dominant model blends per-unit transactional hardware sales with subscription-tiered data platform access. Price differentiation stems from device certification levels and integration with existing electronic health records. Pricing softness runs through basic wearable sensors due to commoditization, making individual home care users highly price-sensitive compared to hospitals seeking integrated solutions.
Supply Chain Analysis
Certification requirements for medical-grade components gate access for many biosensor suppliers. The supply chain concentrates heavily in China for manufacturing and the United States for advanced R&D, drawing from flexible polymer substrates and specialized electrochemical sensor platforms. Single-source vulnerability for specific components presents a structural risk. Distribution runs through direct sales to large hospital networks and third-party medical device distributors for smaller clinics and home care providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Healthcare Biosensors IoT market is in a technology-transition phase, as flexible polymer substrates displace rigid silicon in wearable sensors. This shift enables more comfortable and continuous patient monitoring solutions.
For Market Incumbents: Anticipate continued regulatory pressure from US FDA and EMA, requiring sustained investment in cybersecurity protocols. Deepen vertical integration into specialized sensor component manufacturing to mitigate supply chain risks. Expand digital health ecosystems through strategic partnerships, countering the threat of fragmented data silos. Focus R&D on predictive analytics integration to maintain competitive positioning against emerging AI-driven solutions.
For New Entrants and Emerging Players: Remote and rural populations in emerging markets like India represent a significant white-space opportunity for cost-effective IoT biosensor solutions. Target the home care segment with user-friendly, non-invasive wearable sensors for chronic disease management. A go-to-market angle focused on local partnerships and simplified data platforms can overcome existing infrastructure barriers. Prioritize NMPA and CDSCO compliance for market access in China and India.
For Investors and Strategic Acquirers: Widespread adoption of open data platforms is the leading indicator that market fragmentation is receding, signaling long-term viability for integrated solutions. Seek acquisition targets specializing in AI-driven predictive analytics or secure interoperable data ecosystems. Companies with robust cybersecurity frameworks and established regulatory compliance profiles offer strong strategic value. Monitor the rate of EHR integration with third-party biosensor data as a key inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying diverse biosensor data streams enhances diagnostic value for clinicians. |
| Geographic Expansion | Penetrating emerging markets addresses unmet healthcare needs in remote populations. |
| Regulatory Approval Pathway | Securing US FDA and EU MDR certifications ensures market access and patient trust. |
| Software Companion Development | Integrating AI algorithms with sensor data enables predictive health analytics. |
| Hospital System Partnership | Collaborating with large networks drives adoption of unified data architectures for population health. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with industry stakeholders. We engaged clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Secondary sources included US FDA guidance documents, EMA submissions, and company annual reports. A rigorous bottom-up and top-down triangulation process validated all market estimates.
Data-stream reconciliation integrated various market parameters into a robust analytical framework across the analysis window. The study segmented by product type, technology, application, end user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected adoption rates. Chronic disease prevalence and material science advancements served as critical forecast inputs.
Revisions become necessary when unforeseen regulatory shifts or significant technological breakthroughs materialize, altering market fundamentals. Forecasts reflect assumptions regarding cybersecurity vulnerabilities and interoperability deficits. A model refresh is warranted upon material change in global healthcare policy directives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
Heart Beat Monitor and Sensor Market
Patient Monitoring
Middle East and Africa Cardiac Monitoring Market
Patient Monitoring
Drowsiness Monitoring System Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
Global IOT Sensors in Healthcare Market
Patient Monitoring
Respiration Monitor Belt Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
Home Care Monitoring and Diagnostics Market
Patient Monitoring
Global Vital Sign Monitoring Market
Patient Monitoring
Asia Pacific Wireless Healthcare Market
Patient Monitoring
Wearable Ambulatory Monitoring Device Market
Patient Monitoring
Clinical Alarm Management Market
Patient Monitoring
Body Fat Measurement Market