
 Advanced Carbon Dioxide (CO2) Sensors Market | 2026-2036
Advanced Carbon Dioxide (CO2) Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Carbon Dioxide (CO2) Sensors Market Intelligence
A shortage of photonics engineers and MEMS fabrication specialists is redrawing competitive boundaries across the sensor value chain. Honeywell International Inc. leverages its vertical integration in infrared source manufacturing to control cost structures in non-dispersive infrared modules. Sensirion AG specializes in miniaturized photoacoustic cells, anchoring its position in portable and wearable monitoring applications. Vaisala Oyj dominates meteorological and greenhouse calibration standards, sustaining premium positioning through ISO-certified reference-grade accuracy.
Advanced carbon dioxide sensors are precision instruments that detect and quantify ambient CO2 concentrations through optical absorption, electrochemical reaction, or acoustic resonance principles, typically achieving measurement resolutions below 50 parts per million for environmental and safety-critical applications. These devices serve primary industrial purposes including ventilation control, process safety, agricultural yield optimization, and regulatory compliance monitoring in enclosed spaces. Non-Dispersive Infrared products command the largest revenue share due to established reliability in building automation, while photoacoustic technology represents the fastest-expanding segment driven by demand for compact, low-power designs in portable devices. Indoor Air Quality applications generate the deepest margin pools as commercial building operators face escalating liability exposure from poor ventilation management.
The U.S. EPA's indoor air quality guidelines and the EU Green Deal's building renovation targets are tightening CO2 monitoring requirements across commercial real estate and public infrastructure. Japan's METI energy efficiency standards mandate sensor-based demand-controlled ventilation in large facilities, creating hardware pull-through across Pacific supply chains. China's GB standards for indoor environmental quality and MEE industrial emissions protocols add compliance layers for multinational equipment suppliers. Stakeholders must monitor divergence between regional calibration certification regimes and the pace of wireless interoperability standardization to anticipate which technology platforms will capture retrofit versus new-build deployment cycles.
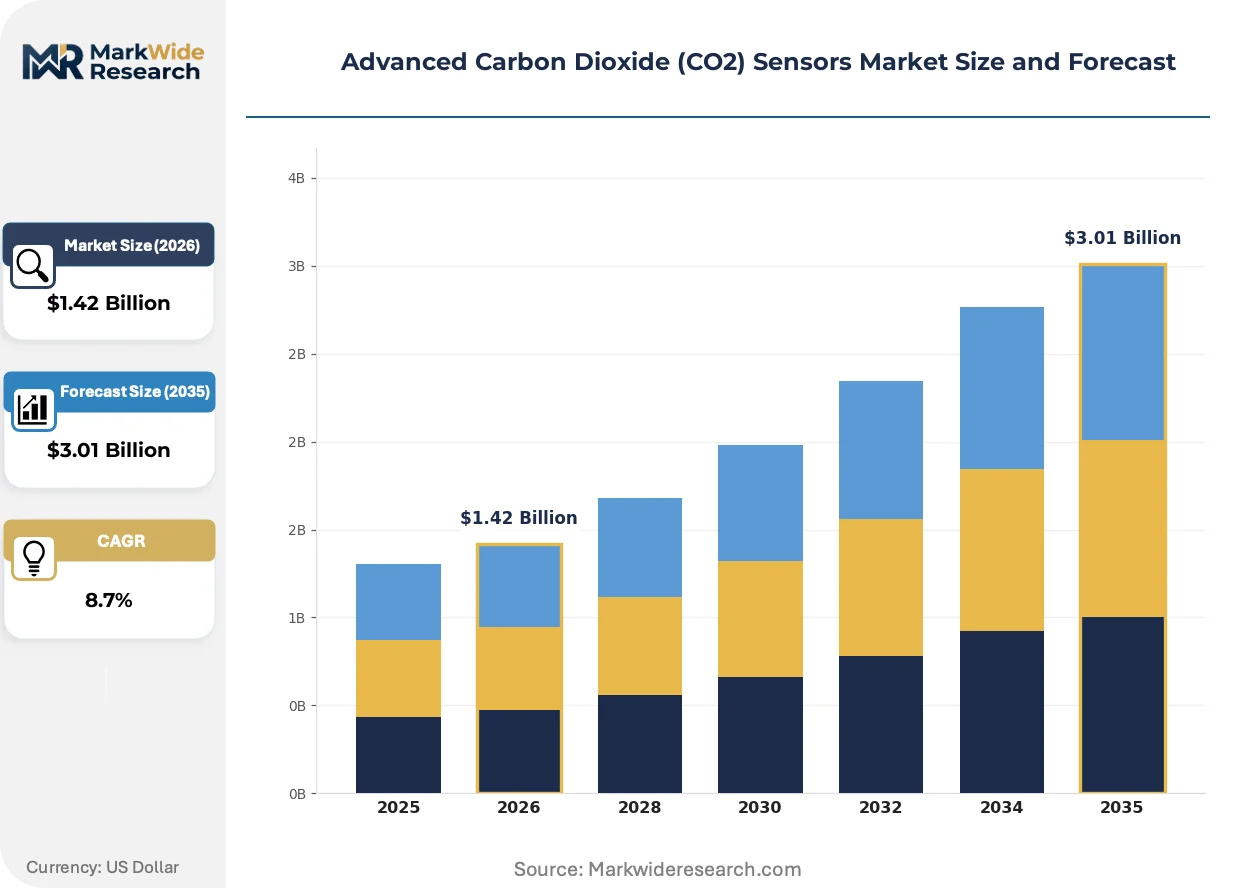
Market Dynamics
The EU Green Deal's building renovation targets and Japan's METI energy efficiency mandates are forcing synchronized sensor deployment across commercial real estate portfolios, compressing procurement cycles and elevating accuracy requirements for HVAC-integrated CO2 monitoring systems.
Growth Catalysts
- Smart Building Mandates:The EU Green Deal requires comprehensive indoor air quality monitoring in renovated commercial structures, mandating sensor density thresholds that hardware suppliers must meet to participate in public procurement.
- Demand-Controlled Ventilation:Japan's METI standards obligate large facilities to deploy sensor-based DCV systems, creating hardware pull-through across Pacific supply chains for precision optical sensing modules.
- Photoacoustic Miniaturization:Advances in MEMS-fabricated photoacoustic cells enable sub-50ppm resolution in battery-powered form factors, opening wearable and portable monitoring segments previously inaccessible to NDIR architectures.
Market Restraints
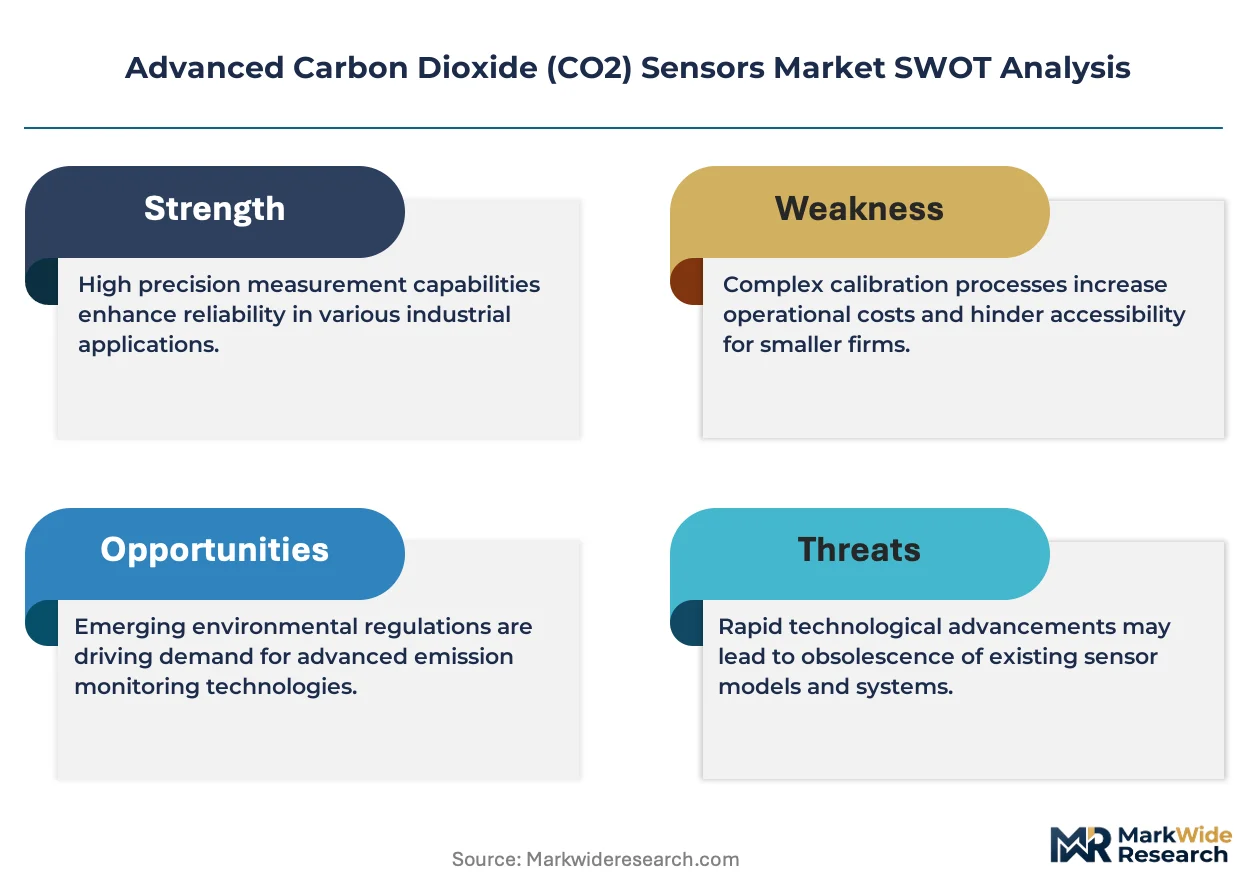
- Photonics Talent Scarcity:A structural shortage of MEMS fabrication specialists and infrared optical engineers concentrates design expertise in Germany, Japan, and the United States, limiting new entrant capacity expansion.
- Calibration Infrastructure Costs:ISO-certified reference-grade accuracy requires capital-intensive climatic chamber networks and gas standard traceability chains that mid-tier suppliers cannot replicate economically.
- Electrochemical Substitution:Low-cost electrochemical sensors satisfy basic safety-threshold applications in price-sensitive residential and small commercial installations, capping premium optical sensor penetration at the economy tier.
Strategic Opportunities
- Agricultural Greenhouse Automation:Precision horticulture operations in the Netherlands and Spain are deploying CO2 enrichment feedback loops that require continuous monitoring, creating demand for corrosion-resistant, high-humidity-rated sensor variants.
- Wireless Interoperability Gaps:Fragmentation between LoRaWAN, Zigbee, and proprietary building automation protocols creates white space for module suppliers offering multi-protocol firmware stacks that simplify integrator deployment.
- Retrofit Installation Services:Commercial building operators face liability exposure from poor ventilation management, generating attach revenue streams for sensor vendors bundling hardware with commissioning and calibration maintenance contracts.
Industry Challenges
- Cross-Border Certification Complexity:Divergence between EPA indoor air quality guidelines, EU F-Gas Regulation calibration requirements, and China's GB standards forces suppliers to maintain multiple product SKUs and testing regimens.
- Legacy BAS Integration Friction:BACnet and Modbus protocol variants across installed building automation systems demand custom gateway development, extending sales cycles and requiring field engineering resources that strain scaling vendors.
- Supply Chain Reconfiguration Costs:Relocation of MEMS foundry capacity from established clusters to alternative geographies triggers qualification delays and yield ramp risks for optical sensing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Carbon Dioxide (CO2) Sensors Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Dispersive Infrared, Electrochemical, Laser, Photoacoustic Application: Indoor Air Quality, Greenhouses, Refrigeration, Industrial Processes End User: Commercial Buildings, Residential Homes, Agriculture, Laboratories Technology: Wireless, Wired, Portable, Fixed |
| Companies Covered | Honeywell International Inc., Siemens AG, Vaisala Oyj, Amphenol Corporation, SenseAir (Asahi Kasei), Sensirion AG, Gas Sensing Solutions Ltd., Cubic Sensor and Instrument Co. Ltd., Johnson Controls International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Carbon Dioxide (CO2) Sensors Market Strategic Shifts & Innovations
Technology convergence between optical sensing architectures and wireless connectivity stacks is compressing module footprints while elevating data granularity expectations from building automation integrators and facility management platforms.
Photoacoustic sensing is supplanting traditional NDIR modules in portable and wearable applications. The technology achieves comparable accuracy at one-third the optical path length, enabling sub-cubic-centimeter form factors. Fitness device manufacturers and personal exposure monitors are adopting these cells aggressively. This shift is compressing addressable market boundaries between industrial fixed-installation and consumer mobility segments.
The EU F-Gas Regulation and its phasedown of hydrofluorocarbon refrigerants is accelerating sensor deployment in commercial refrigeration leak detection systems. Industrial cold chain operators must install permanent monitoring infrastructure to maintain operating licenses. Food retail and pharmaceutical logistics verticals in Germany, France, and Italy are absorbing the highest compliance-driven hardware volumes.
Facility management procurement is consolidating around outcome-based ventilation performance contracts rather than capital equipment purchases. Sensor vendors are unbundling hardware from analytics subscriptions, with data platform recurring revenue displacing upfront module margins. This restructuring is most visible in United States commercial office portfolios undergoing ESG-driven operational upgrades.
Advanced Carbon Dioxide (CO2) Sensors Market Segmentation
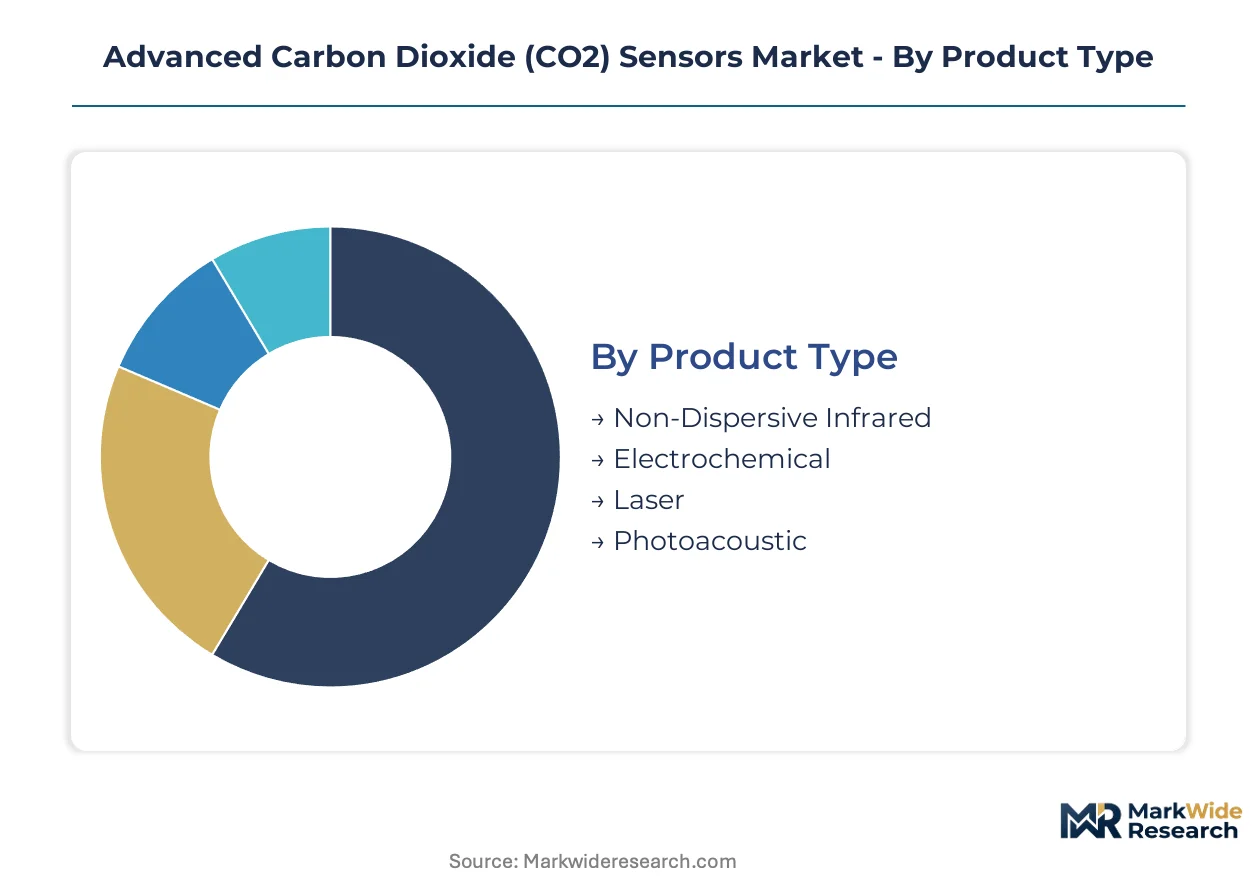
Technology substitution pressures and regulatory fragmentation create divergent growth trajectories across sensor architectures. Each segment category demands distinct manufacturing competencies and certification pathways that reshape vendor positioning.
Product Type:
Electrochemical sensors exert intense price pressure on optical platforms in residential safety applications, forcing premium suppliers to defend accuracy differentiation.
- Non-Dispersive Infrared:These sensors measure CO2 concentration by detecting infrared light absorption at specific wavelengths using optical benches with precision-machined gas chambers. Building automation integrators in Germany and the United States specify NDIR modules for HVAC feedback loops where drift tolerance below 50ppm maintains energy efficiency credits.
- Photoacoustic:MEMS-fabricated cells detect pressure waves generated by pulsed infrared absorption, achieving comparable precision in one-third the physical volume. Wearable device manufacturers in Japan and South Korea are adopting these modules for personal exposure monitoring where battery life constraints dominate design trade-offs.
- Electrochemical:Amperometric cells using liquid electrolytes offer sub-dollar unit economics for basic safety-threshold alarms in residential smoke-CO2 combo units.
- Laser:Tunable diode absorption spectroscopy delivers parts-per-billion resolution for scientific and metrology applications requiring traceable calibration chains.
Non-Dispersive Infrared retains volume leadership; Photoacoustic holds the steepest expansion curve.
Application:
Margin concentration varies sharply by liability exposure and calibration rigor demanded by end-use environments.
- Indoor Air Quality:Continuous monitoring systems for commercial office ventilation control require ISO-certified accuracy to satisfy LEED and WELL building standards. Facility operators in California and New York face escalating insurance scrutiny over CO2-related productivity claims, driving specification upgrades.
- Greenhouses:Enrichment feedback systems in Dutch and Spanish horticulture operations demand corrosion-resistant housings and humidity compensation algorithms. These installations prioritize measurement stability over absolute precision.
- Refrigeration:Leak detection mandates under the EU F-Gas Regulation require permanent monitoring infrastructure in industrial cold chains across Germany, France, and Italy.
- Industrial Processes:Cement and chemical production facilities deploy extractive sampling systems with heated lines to prevent condensation in stack monitoring configurations.
Indoor Air Quality commands the deepest margin pools; Greenhouse applications are expanding most quickly.
End User:
Procurement sophistication separates price-sensitive residential volumes from specification-driven commercial contracts.
- Commercial Buildings:Large portfolio operators negotiate enterprise-wide sensor specifications with embedded calibration service agreements. REITs undergoing ESG-driven operational upgrades in the United States are consolidating vendor relationships around outcome-based ventilation performance contracts.
- Agriculture:Precision horticulture cooperatives in the Netherlands deploy networked sensor arrays for CO2 enrichment optimization in controlled-environment agriculture.
- Residential Homes:Basic safety-threshold alarms dominate unit volumes with minimal feature differentiation and compressed replacement cycles.
- Laboratories:Research institutions require NIST-traceable calibration documentation and multi-gas capability for cell culture incubation and analytical instrument support.
Commercial Buildings dominate absolute revenue; Agriculture is gaining share fastest.
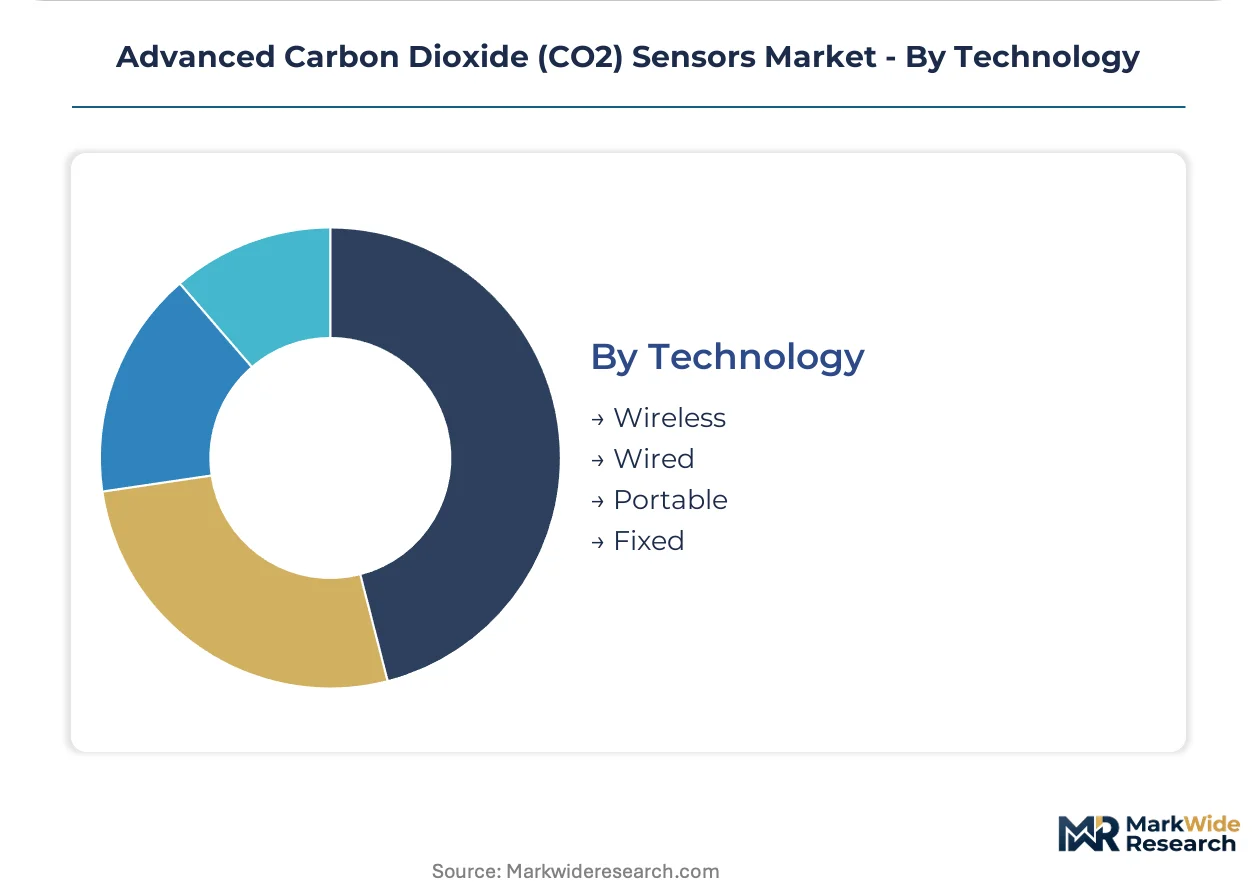
Technology:
Wireless protocol fragmentation creates integration friction that favors modular suppliers offering firmware flexibility.
- Wireless:Battery-powered LoRaWAN and Zigbee modules eliminate conduit costs in retrofit installations. Building automation integrators face interoperability gaps between proprietary protocols that extend commissioning timelines.
- Fixed:Hardwired 4-20mA and BACnet MS/TP installations remain standard in new commercial construction where power budgets accommodate continuous operation.
- Portable:Handheld validation instruments with data logging capability serve commissioning engineers and regulatory inspectors requiring spot-check mobility.
- Wired:Analog voltage output modules persist in legacy industrial control systems with limited digital infrastructure.
Fixed installations retain deployment volume leadership; Wireless is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA anchors the most influential regulatory framework for indoor air quality monitoring, though sensor deployment intensity varies sharply across manufacturing clusters and compliance regimes worldwide.
United States
Commercial real estate operators in California and New York face escalating insurance scrutiny over CO2-related productivity claims, driving specification upgrades for ventilation control systems. The EPA's indoor air quality guidelines tighten monitoring requirements across federal buildings and publicly financed infrastructure projects. REITs undergoing ESG-driven operational upgrades in major metropolitan corridors are consolidating vendor relationships around outcome-based performance contracts.
Germany
Industrial cold chain operators must install permanent monitoring infrastructure to maintain operating licenses under the EU F-Gas Regulation phasedown schedule. The EU Green Deal mandates comprehensive indoor air quality monitoring in renovated commercial structures, forcing synchronized sensor deployment across portfolios. Precision engineering firms in Bavaria and Baden-Württemberg concentrate manufacturing capacity for next-generation optical sensing platforms.
Japan
Large facilities must deploy sensor-based demand-controlled ventilation systems under METI energy efficiency standards, creating hardware pull-through across Pacific supply chains. Fitness device manufacturers and personal exposure monitor developers in Tokyo and Osaka are adopting MEMS-fabricated photoacoustic cells aggressively. The Kanto region houses precision optical engineering expertise for miniaturized sensing modules.
China
Multinational equipment suppliers face additional compliance layers from GB standards for indoor environmental quality and MEE industrial emissions protocols. Building automation integrators in the Yangtze River Delta and Pearl River Delta specify high-volume sensor deployments for smart city infrastructure. Domestic module suppliers compete on cost while foreign precision vendors defend accuracy differentiation.
Netherlands
Precision horticulture operations deploy CO2 enrichment feedback loops requiring continuous monitoring in controlled-environment agriculture. The EU Green Deal's building renovation targets accelerate sensor deployment across commercial greenhouse portfolios. Wageningen and surrounding agricultural technology clusters drive demand for corrosion-resistant, high-humidity-rated sensor variants.
Advanced Carbon Dioxide (CO2) Sensors Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the sensor value chain, creating a tiered competitive structure. Consolidated positions exist among precision optical engineering specialists with captive calibration infrastructure, while fragmented competition characterizes the electrochemical and basic safety-threshold segments. Three strategic archetypes dominate: vertically integrated industrial conglomerates with infrared source manufacturing capabilities, MEMS-fabrication specialists focused on miniaturization, and meteorological calibration houses with ISO-certified reference-grade positioning. Capacity expansion and strategic partnerships represent the dominant competitive moves, as suppliers seek to secure photonics engineering talent and climatic chamber networks.
Within the precision optical tier, Honeywell International Inc. and Vaisala Oyj exemplify divergent strategic positions. Honeywell represents the vertically integrated industrial archetype with backward control over infrared source manufacturing. Vaisala occupies the meteorological calibration specialist position, anchoring premium positioning through reference-grade accuracy standards. Sensirion AG sits within the MEMS miniaturization specialist category, representing the photoacoustic technology vector for portable and wearable applications.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Vaisala Oyj |
| Amphenol Corporation |
| SenseAir (Asahi Kasei) |
| Sensirion AG |
| Gas Sensing Solutions Ltd. |
| Cubic Sensor and Instrument Co. Ltd. |
| Johnson Controls International |
| Others |
Cost & Logistics Intelligence
ISO-certified reference-grade accuracy requirements gate both supplier qualification timelines and premium pricing tiers, forcing mid-tier vendors into economy positioning while concentrating margin pools among calibration infrastructure owners. This dual-gating mechanism compresses procurement cycles for building automation integrators who cannot absorb qualification delays.
Pricing Analysis
German and Japanese optical modules command 40-60% premiums over Chinese electrochemical alternatives in commercial building specifications. Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified NDIR platforms from MEMS-fabricated photoacoustic cells and basic safety-threshold electrochemical units. Cost compression in the economy tier is intensifying because residential smoke-CO2 combo manufacturers source sub-dollar amperometric cells from domestic Chinese suppliers. Facility management procurement teams show lowest price sensitivity for Indoor Air Quality applications where liability exposure dominates total cost of ownership calculations.
Supply Chain Analysis
Germany, Japan, and the United States concentrate precision optical engineering and MEMS fabrication capacity for next-generation sensing platforms. Infrared source manufacturing draws from specialized foundries in Bavaria and Baden-Württemberg, while photoacoustic cell production rests on wafer-level MEMS processing in Kanto region facilities. Single-source vulnerability concentrates in climatic chamber networks required for ISO-certified calibration traceability chains. Distribution runs through building automation integrators and OEM sensor module suppliers who bundle hardware with commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent optical sensor vendors face sustained substitution pressure from electrochemical alternatives in price-sensitive residential segments, requiring defensive repositioning around accuracy differentiation and calibration service bundling.
For Market Incumbents: Shield premium positioning by deepening captive supply of infrared sources and expanding climatic chamber networks for faster calibration turnaround. Electrochemical encroachment into basic safety applications demands accelerated R&D investment in sub-50ppm photoacoustic miniaturization to capture wearable segment growth before MEMS specialists consolidate.
For New Entrants and Emerging Players: Retrofit installation services represent the most penetrable white space where incumbents under-serve commercial building operators facing liability exposure. Agricultural greenhouse automation in the Netherlands and Spain offers specification entry points with lower certification barriers than Indoor Air Quality applications. A calibration-maintenance subscription model bypasses capital equipment procurement committees and locks in recurring revenue.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across photoacoustic MEMS fabrication as yield ramp risks and qualification delays extend payback periods. Long-term viability favors meteorological calibration houses with ISO-certified reference-grade positioning and established traceability chains. The signal to monitor is divergence between regional certification regimes that would force multi-SKU strategies and compress returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Infrared Sources | Honeywell's captive supply of NDIR emitters compresses cost structures against modular competitors. |
| MEMS Photoacoustic Cell Miniaturization | Sensirion's sub-cubic-centimeter form factors unlock wearable and portable monitoring segments. |
| Calibration Infrastructure Expansion | Vaisala's climatic chamber networks defend premium positioning through ISO-certified accuracy. |
| Multi-Protocol Wireless Firmware Development | Module suppliers bridging LoRaWAN-Zigbee fragmentation capture retrofit installation growth. |
| Outcome-Based Ventilation Performance Contracts | REIT procurement consolidation favors vendors unbundling hardware from analytics subscriptions. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EPA indoor air quality guidelines, EU F-Gas Regulation filings, METI energy efficiency standards, and GB certification databases. Interviews with building automation integrators, HVAC procurement officers, MEMS fabrication specialists, and facility management executives combined with bottom-up sensor deployment estimates and top-down regulatory mandate analysis. Secondary validation drew from SEC 10-K disclosures, customs trade data for optical component flows, and ISO certification registry records.
Segmentation dimensions modeled include technology architecture, application environment, end-user procurement sophistication, and wireless connectivity protocol across the projection horizon. CAGRs were derived from regulatory mandate timing, building renovation cycle analysis, and technology substitution elasticity estimates. Forecast inputs incorporated MEMS yield ramp assumptions and climatic chamber capacity expansion timelines for calibration infrastructure.
Material uncertainties — divergence between regional certification regimes, electrochemical substitution acceleration, and MEMS foundry relocation delays — sit outside the modeled envelope. Forecasts reflect assumptions about standardization convergence and wireless interoperability adoption without guarantee of realization. Recalibration cycles align with material shifts in EU Green Deal implementation pace and METI mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Capacitive Ceramic Pressure Sensors Market
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
Automotive MEMS Market
Sensors and Controls
Sensor Screwdrivers Market
Sensors and Controls
Printed and Flexible Sensors Market
Sensors and Controls
North America Proximity Sensor Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Safety Sensors Market
Sensors and Controls
Global Optogenetics Actuators and Sensors Market
Sensors and Controls
Electric Pipette Controllers Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
Capacitive Position Sensors Market
Sensors and Controls
Smart Haptic Devices Market
Sensors and Controls
Global Collision Avoidance Sensors Market
Sensors and Controls
Dew Point Thermometer Market