
 LAMEA Active Sensor Market | 2026-2036
LAMEA Active Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Active Sensor Market Insights
A shift from single-source to multi-source procurement is hardening across LAMEA industrial automation supply chains. Siemens AG leverages its regional manufacturing footprint to anchor long-term service contracts in South Africa and the UAE. Honeywell International Inc. competes through backward integration into sensor calibration and field-support networks across Latin America. Robert Bosch GmbH specializes in radar-based active sensor modules for automotive OEMs in Brazil and Mexico.
Active sensors in the LAMEA region are self-powered or externally energized transducers that convert physical stimuli—temperature, pressure, proximity, or electromagnetic reflection—into processable electrical signals, typically operating at sampling frequencies above one kilohertz for real-time industrial feedback. Their primary commercial purpose spans factory floor automation, vehicle safety systems, and grid infrastructure monitoring. Temperature sensors and pressure sensors occupy the mature volume tier, while radar technology segments capture expanding margin pools in automotive and robotics applications. Optical sensors sustain premium positioning within healthcare monitoring and smart home deployments, where precision requirements justify higher unit economics.
Brazil's ANVISA and Mexico's national metrology institute shape medical and industrial sensor certification pathways, while the UAE's central energy authority and South Africa's CEA enforce smart grid interoperability standards that dictate product compliance. These regulatory frameworks fragment market access, forcing vendors to maintain multiple certification portfolios across Latin America, the Middle East, and Africa. Stakeholders must monitor divergence between Gulf standardization initiatives and sub-Saharan African technical regulations to anticipate where harmonization or fragmentation will govern procurement decisions.
Market Dynamics
The LAMEA active sensor market pivots on automotive OEMs' transition from passive to radar-based safety architectures, a shift compressing supplier qualification timelines and fragmenting certification requirements across Latin American, Middle Eastern, and African regulatory jurisdictions.
Growth Catalysts
- ANVISA medical device pathways:Brazil's regulator has streamlined active sensor approvals for patient monitoring equipment, accelerating hospital procurement cycles in São Paulo and Rio de Janeiro health networks.
- Smart grid interoperability mandates:South Africa's CEA enforcement of IEC 61850 standards is forcing utility procurement of pressure and temperature sensors for distribution automation.
- Radar module localization:Mexican automotive clusters near Querétaro are absorbing radar-based active sensors for export-bound vehicle platforms, creating captive demand pools.
Market Restraints
- Semiconductor input volatility:MEMS foundry capacity concentration in East Asia exposes LAMEA sensor assemblers to wafer cost swings and extended lead times.
- Regulatory fragmentation:Divergent electromagnetic compatibility standards between Gulf Cooperation Authority frameworks and sub-Saharan African technical regulations multiply certification costs for single-SKU strategies.
- Optical sensor substitution:Machine vision systems using CMOS image sensors are capturing quality-control applications previously served by laser-based proximity sensors in Brazilian packaging lines.
Strategic Opportunities
- Angolan grid rehabilitation:Post-conflict infrastructure reconstruction is creating first-mover advantages for pressure sensor vendors targeting hydroelectric turbine monitoring.
- LiDAR-radar convergence:Autonomous mining vehicle trials in Chile's Atacama operations are opening specifications for fused active sensor arrays combining electromagnetic and optical ranging.
- Digital marketplace channels:Industrial sensor procurement through UAE-based B2B platforms is disintermediating traditional distributor networks for mid-volume factory automation buyers.
Industry Challenges
- Embedded firmware talent scarcity:Real-time signal processing expertise for kilohertz-sampling industrial sensors remains concentrated in São Paulo and Dubai, constraining localization in secondary markets.
- Legacy system integration friction:Factory retrofit programs in South Africa's automotive component sector face protocol mismatches between modern active sensors and 1990s-era PLC architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Active Sensor Market |
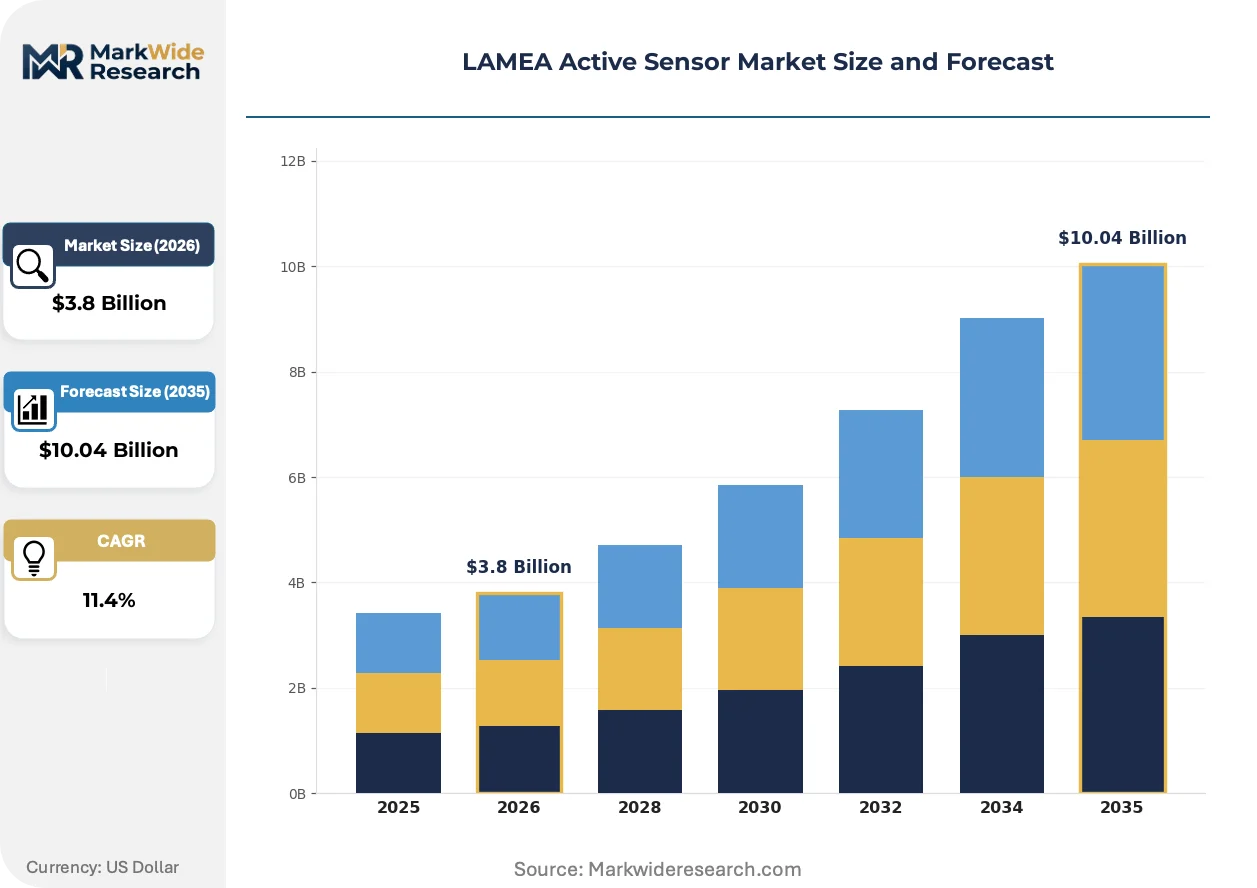
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Proximity Sensors, Pressure Sensors, Image Sensors Technology: Ultrasonic, Capacitive, Optical, Radar End User: Consumer Electronics, Automotive, Industrial Automation, Smart Home Application: Robotics, Healthcare Monitoring, Smart Grids, Environmental Monitoring |
| Companies Covered | Emerson Electric Co., Honeywell International Inc., Siemens AG, Infineon Technologies AG, TE Connectivity Ltd., Robert Bosch GmbH, ABB Ltd., Sensirion AG, NXP Semiconductors, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Active Sensor Market Trends and Innovations
Technology convergence between automotive radar and industrial automation is eroding traditional segment boundaries, while regulatory divergence between Gulf and African standardization bodies is fragmenting product roadmaps.
Frequency-modulated continuous-wave radar is expanding into industrial collision-avoidance systems, offering superior range resolution than ultrasonic alternatives in dusty mining environments. Brazilian steel mills and Chilean copper concentrators are piloting these units for haul truck proximity detection. The technology is expanding into applications previously reserved for mechanical limit switches, compressing the addressable market for legacy electromechanical sensor categories.
CEA smart grid interoperability standards in South Africa are mandating IEC 61850-9-2LE compliance for all new distribution automation sensors, forcing vendors to redesign analog front-ends for sampled value transmission. Industrial consequence includes accelerated obsolescence of 4-20mA output sensors in utility procurement. The pressure sensor segment faces the steepest redesign burden, with South African municipalities rejecting non-compliant bids for substation monitoring tenders.
Multi-source procurement contracts are displacing sole-source agreements in UAE industrial automation corridors, with Emirates Global Aluminium and Saudi Aramco facilities requiring redundant supplier qualification for critical pressure and temperature loops. Traditional authorized distributors are losing exclusivity premiums as direct vendor relationships proliferate. This pattern is most visible in Dubai's Jebel Ali industrial zone, where factory engineering teams maintain parallel technical dialogues with three to four sensor vendors per application category.
LAMEA Active Sensor Market Segmentation
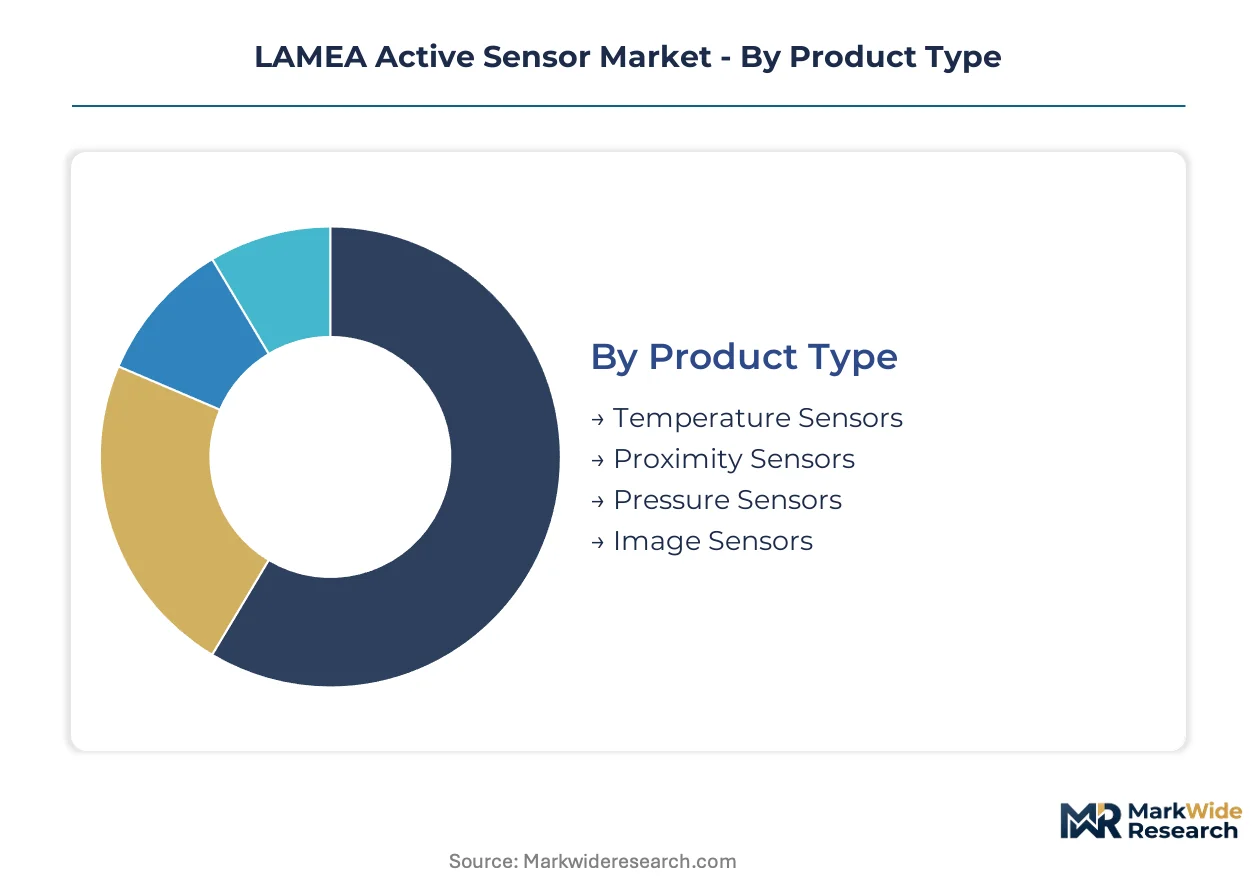
Active sensor procurement across Latin America, the Middle East, and Africa fragments along four axes: physical measurement domain, signal transduction mechanism, buyer industry vertical, and deployment environment. Each axis carries distinct certification burdens and supplier qualification timelines that reshape competitive positioning.
Product Type:
Measurement physics determines calibration protocols and regulatory pathways across LAMEA jurisdictions.
- Temperature Sensors:Thermocouple and RTD elements dominate factory automation retrofits in South Africa's automotive component sector. IEC 61850-9-2LE compliance mandates from the country's CEA are accelerating replacement of analog-output units in substation monitoring.
- Proximity Sensors:Inductive and capacitive variants serve collision-avoidance systems in Chilean copper mining haul trucks. Dust-resistant housing specifications from Brazilian steel mill operators are driving IP67-rated procurement above ultrasonic alternatives.
- Pressure Sensors:MEMS-based transducers monitor hydroelectric turbine performance in Angolan grid rehabilitation projects. Piezoresistive designs face redesign pressure from sampled-value transmission requirements.
- Image Sensors:CMOS arrays capture quality-control applications in Brazilian packaging lines, displacing laser-based proximity sensors for defect detection at conveyor speeds.
Temperature sensors lead on scale; proximity sensors lead on momentum.
Technology:
Signal generation method shapes range resolution, environmental tolerance, and integration complexity for LAMEA deployments.
- Ultrasonic:Time-of-flight measurement serves liquid-level monitoring in UAE desalination facilities. Humidity-induced signal attenuation limits adoption in Gulf industrial corridors compared to radar alternatives.
- Capacitive:Dielectric sensing detects material proximity without physical contact in food processing lines near São Paulo. ANVISA sanitary equipment certifications govern electrode material selection for pharmaceutical packaging.
- Optical:Photodiode arrays and laser triangulation sustain premium positioning in Dubai smart home deployments. Precision requirements for healthcare monitoring justify higher unit economics against electromechanical substitutes.
- Radar:Frequency-modulated continuous-wave modules penetrate dust and moisture in Atacama mining operations. Mexican automotive clusters near Querétaro absorb these units for export-bound vehicle platforms with ADAS architectures.
Radar climbs the fastest; optical holds margin concentration.
End User:
Buyer sophistication and procurement scale separate volume tiers from specification-intensive segments.
- Consumer Electronics:Smartphone and wearable integration demands miniaturized MEMS accelerometers and gyroscopes. Brazilian assembly plants source these through UAE-based B2B platforms, disintermediating traditional distributor networks.
- Automotive:OEM transition from passive to active safety architectures compresses supplier qualification timelines. Radar-based modules for Brazilian and Mexican production lines carry fragmented certification requirements across ANVISA, NHTSA-aligned Mexican standards, and internal OEM protocols.
- Industrial Automation:Factory retrofit programs in Dubai's Jebel Ali zone deploy pressure and temperature sensors for process control. Multi-source procurement contracts now require redundant supplier qualification for critical measurement loops.
- Smart Home:Occupancy detection and climate control systems in UAE residential towers integrate passive infrared and humidity sensors. Interoperability with building management systems dictates Modbus and BACnet protocol support.
Industrial automation leads on scale; automotive leads on specification intensity.
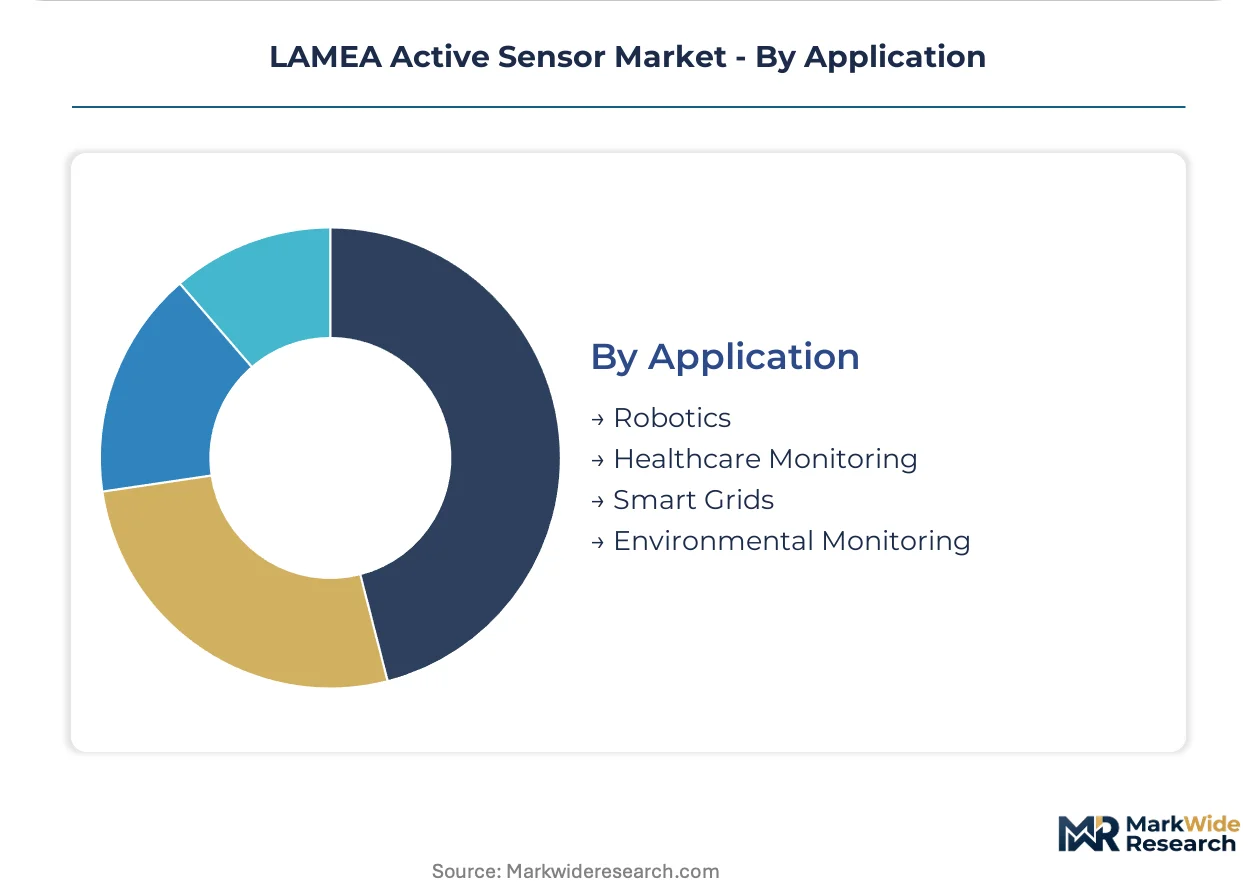
Application:
Deployment environment determines sampling frequency requirements, connectivity standards, and maintenance access constraints.
- Robotics:Six-axis force-torque sensors and joint-position encoders enable collaborative robot deployments in São Paulo automotive supplier plants. Real-time control loops demand kilohertz-sampling rates with sub-millisecond latency.
- Healthcare Monitoring:Pulse oximetry and continuous glucose monitoring devices serve hospital networks in Rio de Janeiro and São Paulo. ANVISA streamlined approval pathways for patient monitoring equipment are accelerating procurement cycles.
- Smart Grids:Distribution automation sensors across South African municipalities must demonstrate IEC 61850-9-2LE sampled-value compliance. Pressure and temperature transducers for substation monitoring face rejection if analog 4-20mA outputs persist.
- Environmental Monitoring:Air quality and water level sensors support regulatory compliance in Chilean mining concession areas. Solar-powered telemetry with LoRaWAN backhaul addresses grid connectivity gaps in remote installations.
Smart grids lead on regulatory forcing function; healthcare monitoring gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's Jebel Ali industrial zone concentrates procurement authority for pressure and temperature sensors across Gulf factory automation corridors, while São Paulo's automotive supplier ecosystem drives radar module demand for export-bound vehicle platforms.
Brazil
ANVISA streamlined approval pathways for patient monitoring equipment accelerate hospital procurement cycles in Rio de Janeiro and São Paulo health networks. The national health surveillance agency governs active sensor certifications for medical devices. Brazilian steel mills near Belo Horizonte pilot frequency-modulated continuous-wave radar for haul truck proximity detection in dusty mining environments.
Mexico
Automotive clusters near Querétaro absorb radar-based active sensors for export-bound vehicle platforms with advanced driver assistance architectures. The national metrology institute shapes industrial sensor certification pathways alongside NHTSA-aligned Mexican standards. Factory engineering teams in the Bajío Region maintain parallel technical dialogues with multiple sensor vendors per application category.
South Africa
CEA enforcement of IEC 61850-9-2LE standards forces utility procurement of pressure and temperature sensors for distribution automation. The national energy regulator mandates sampled-value transmission compliance for substation monitoring tenders. Municipal procurement offices in Johannesburg and Cape Town reject non-compliant bids for grid infrastructure rehabilitation.
United Arab Emirates
Emirates Global Aluminium and Saudi Aramco facilities require redundant supplier qualification for critical pressure and temperature measurement loops. The central energy authority enforces smart grid interoperability standards that dictate product compliance. Dubai's Jebel Ali industrial zone hosts multi-source procurement contracts displacing sole-source distributor agreements.
Chile
Autonomous mining vehicle trials in the Atacama operations open specifications for fused active sensor arrays combining electromagnetic and optical ranging. The national mining concession framework supports environmental monitoring sensor deployments for regulatory compliance. Copper concentrators in the Antofagasta Region pilot radar-based collision-avoidance systems for haul truck fleets.
LAMEA Active Sensor Market Competitive Landscape
Global majors compete with regional champions across certification portfolios and field-service networks. Siemens AG leverages its regional manufacturing footprint to anchor long-term service contracts, while Honeywell International Inc. competes through backward integration into sensor calibration networks. Three archetypes dominate: diversified industrial conglomerates with captive distribution, semiconductor specialists with MEMS foundry relationships, and automotive-tier suppliers with radar module expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves across Latin American and Middle Eastern procurement corridors.
Within the diversified industrial tier, Siemens AG and Honeywell International Inc. occupy positions defined by service contract anchoring and calibration network density. Robert Bosch GmbH exemplifies the automotive-tier archetype through radar module specialization. Emerson Electric Co. and ABB Ltd. sit within the process automation segment with pressure and temperature sensor portfolios. These five entities represent the competitive core, with Infineon Technologies AG, NXP Semiconductors, and Sensirion AG anchoring the semiconductor-specialist tier through MEMS and signal processing capabilities.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Honeywell International Inc. |
| Siemens AG |
| Infineon Technologies AG |
| TE Connectivity Ltd. |
| Robert Bosch GmbH |
| ABB Ltd. |
| Sensirion AG |
| NXP Semiconductors |
| Others |
Pricing and Supply Chain Analysis
Backward integration into sensor calibration networks anchors Honeywell's pricing power across Latin American industrial corridors, while Siemens leverages its regional manufacturing footprint to lock in long-term service premiums in South Africa and the UAE. This integration choice separates vendors who capture aftermarket value from those competing on transactional hardware margins.
Pricing Analysis
MEMS wafer cost pass-through from East Asian foundries compresses margins for LAMEA sensor assemblers unable to forward-contract silicon inputs. Pricing stratifies across IEC 61850-certified premium tiers for South African utility procurement, standard industrial grades for Brazilian factory automation, and economy ultrasonic units facing displacement by radar alternatives. Price erosion runs through economy proximity sensors as CMOS image sensors capture Brazilian packaging line applications. Automotive OEMs in Mexico's Querétaro cluster exhibit lowest price sensitivity due to ADAS specification intensity, while Angolan hydroelectric rehabilitation projects drive volume sensitivity in pressure sensor tenders.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Emirates Global Aluminium and Saudi Aramco facilities, while authorized distributors retain footholds in mid-volume Brazilian and South African factory retrofits. MEMS foundry capacity concentrates in Taiwan, South Korea, and China, exposing LAMEA assemblers to wafer lead time volatility. The supply chain draws from silicon wafers, rare-earth magnetic materials for radar modules, and specialized ceramic substrates for high-temperature pressure transducers. Single-source vulnerability in East Asian semiconductor inputs represents the dominant structural risk, with tariff exposure on Chinese-sourced components amplifying cost uncertainty for Brazilian and Mexican automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LAMEA active sensor market functions as a regulatory compounder, where South Africa's CEA enforcement of IEC 61850-9-2LE standards is forcing utility procurement cycles that favor pre-certified vendors with localized calibration networks.
For Market Incumbents: To counter optical sensor substitution in Brazilian quality-control applications, radar specialists must deepen firmware talent pools in São Paulo and Dubai while anchoring multi-source procurement contracts through redundant supplier qualification programs. Certification investment in ANVISA medical device pathways and CEA grid interoperability standards remains the critical defensive lever against emerging semiconductor specialists. For New Entrants and Emerging Players: Frequency-modulated continuous-wave radar expertise offers entry into Chilean mining collision-avoidance specifications where dust-tolerant performance requirements exceed ultrasonic capabilities. Angolan hydroelectric rehabilitation and UAE-based B2B platform channels represent the most penetrable white-space targets, with digital marketplace disintermediation enabling direct factory relationships without legacy distributor overhead. For Investors and Strategic Acquirers: Roll-up economics work for regional calibration and field-service networks because certification fragmentation across ANVISA, CEA, and Gulf Cooperation Authority frameworks forces buyers toward integrated service providers. Platform-rollup strategies targeting São Paulo and Dubai service hubs offer five-to-ten year viability, with the signal to watch being convergence between automotive radar and industrial automation specification standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Calibration Networks | Captures recurring service revenue from South African utility IEC 61850 compliance mandates. |
| Multi-Source Procurement Qualification | Secures placement in Emirates Global Aluminium redundant supplier programs for critical measurement loops. |
| Firmware Talent Localization | Addresses embedded signal processing scarcity constraining secondary market expansion beyond São Paulo and Dubai. |
| Radar-Optical Sensor Fusion Development | Opens specifications for autonomous mining vehicle trials in Chile's Atacama operations. |
| Digital Marketplace Channel Expansion | Disintermediates traditional distributors for mid-volume factory automation buyers in UAE industrial zones. |
Research Methodology
Multiple input streams — primary interviews with industrial automation procurement managers, MEMS foundry operations leads, and utility grid planning officers; secondary validation through IEC standard documentation, ANVISA regulatory filings, and customs trade data — were reconciled through bottom-up unit shipment modeling and top-down market value triangulation.
Historical volume trajectories were cross-referenced against expert panel inputs across the projection horizon, with segmentation dimensions including physical measurement domain, signal transduction mechanism, buyer industry vertical, and deployment environment. CAGRs were derived from slope analysis of normalized growth curves, incorporating automotive OEM platform transition timelines and smart grid infrastructure investment cycles as industry-specific forecast inputs.
The model holds under stable regulatory enforcement and foundry capacity utilization; deviation in East Asian semiconductor supply constraints or Gulf-African standardization divergence would shift volume and value outputs. Periodic stress-testing of base assumptions against CEA procurement tender outcomes and ANVISA approval pathway velocity is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Smart Glove Market
Sensors and Controls
Motion Sensor Market
Sensors and Controls
Ceramic Transducers Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Oxygen Gas Sensors Market
Sensors and Controls
US Temperature Sensors Market
Sensors and Controls
Automation Control Components and Devices Market
Sensors and Controls
Quantum Sensors Market
Sensors and Controls
Seismic Monitoring Equipment Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
United States Sensor Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
Asia-Pacific Current Transducer Market
Sensors and Controls
Meteorological Devices Market
Sensors and Controls
Global PH Sensor Market