
 Insulation Coating Market | 2026-2036
Insulation Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Insulation Coating Market Analysis
A capital-intensity divergence between integrated resin producers and specialty formulators is unwinding competitive stability in the insulation coating sector. AkzoNobel N.V. leverages its European manufacturing footprint and in-house alkyd and epoxy resin capabilities to control raw material quality and supply security. PPG Industries, Inc. anchors its position through aerospace-certified thermal barrier systems that meet stringent FAA airworthiness standards. BASF SE differentiates via polyurethane chemistry leadership and backward integration into isocyanate feedstocks that sustain margin capture across industrial equipment applications.
Insulation coating denotes a functional layer engineered to reduce heat transfer, attenuate sound transmission, or impede flame propagation, typically formulated with ceramic microspheres, aerogel dispersions, or intumescent additives and applied at dry-film thicknesses ranging from 0.5 mm to 10 mm depending on performance class. The primary industrial purpose centers on energy conservation, personnel protection, and regulatory compliance in thermally extreme or acoustically sensitive environments. Thermal insulation products lead volume consumption across building envelopes and process equipment, while fire-resistant coatings command premium pricing in commercial construction and marine end users where IMO SOLAS and classification society rules mandate passive fire protection. Acrylic materials are gaining formulation share in DIY and light industrial segments due to water-borne compatibility and lower application skill requirements, though epoxy and polyurethane continue to dominate specification-driven aerospace and transportation applications.
The EU Green Deal and REACH frameworks in Europe restrict solvent content and hazardous substance thresholds, forcing reformulation investments that favor established players with regulatory affairs infrastructure. In the United States, OSHA thermal hazard standards and EPA VOC emissions rules under the Clean Air Act shape product development priorities and regional distribution strategies. China's MEE enforces dual carbon goals that tighten industrial energy efficiency requirements, directly expanding demand for high-performance thermal barrier systems in steel, petrochemical, and power generation facilities. Stakeholders must monitor evolving carbon border adjustment mechanisms and building energy codes that will determine which material platforms and application segments warrant sustained capacity commitment.
Market Dynamics
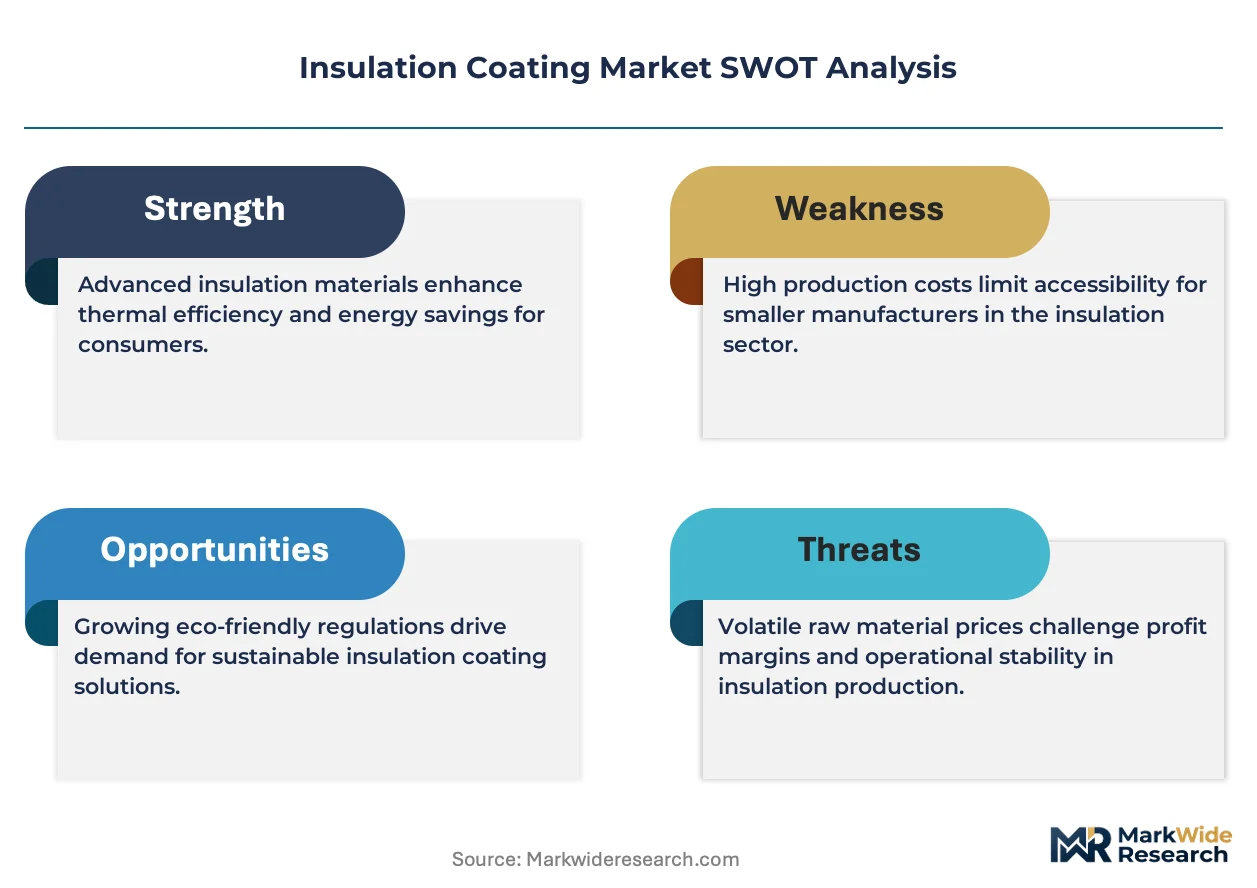
Reformulation pressure from REACH and EU Green Deal mandates is fragmenting competitive advantage between integrated resin producers and specialty formulators. The capital burden of low-VOC and bio-based chemistry transitions favors established players with captive regulatory affairs infrastructure.
Growth Catalysts
- EU Green Deal thermal efficiency mandates:Building envelope retrofit programs across Germany, France, and Italy are accelerating specification of high-performance thermal barrier systems in commercial and residential construction.
- China MEE dual carbon enforcement:Steel, petrochemical, and power generation facilities face tightening energy efficiency requirements that expand demand for industrial-grade insulation coatings on process equipment and pipelines.
- Aerogel dispersion technology:Super-insulating nano-porous materials are penetrating aerospace and cryogenic applications where thermal performance per unit thickness commands specification priority.
Market Restraints
- Isocyanate feedstock volatility:Polyurethane system costs fluctuate with benzene and propylene pricing, compressing margins for formulators without backward integration into MDI or TDI supply.
- Epoxy resin supply concentration:Asian producers dominate bisphenol-A and epichlorohydrin output, creating geographic single-source risk for European and North American coating manufacturers.
- Intumescent coating cure limitations:Thick-film application requirements and humidity-sensitive curing constrain deployment in high-throughput construction schedules.
Strategic Opportunities
- India industrial infrastructure buildout:PLI scheme incentives and BIS energy efficiency standards are opening specification windows for thermal barrier systems in steel and cement plants.
- Marine SOLAS retrofit cycle:IMO fire safety amendments are forcing passenger and cargo vessel upgrades, expanding addressable demand for hydrocarbon-resistant passive fire protection coatings.
- Water-borne acrylic DIY channel:Home improvement retailers are capturing application-skilled homeowners seeking lower-VOC interior insulation solutions for basement and attic projects.
Industry Challenges
- Intumescent applicator certification gaps:Fire-resistant coating installation requires specialized training and third-party witness testing that extends project timelines and limits contractor pool depth.
- Legacy substrate compatibility:New low-VOC formulations often fail adhesion on weathered alkyd or oil-based primers, forcing costly surface preparation or complete coating system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulation Coating Market |
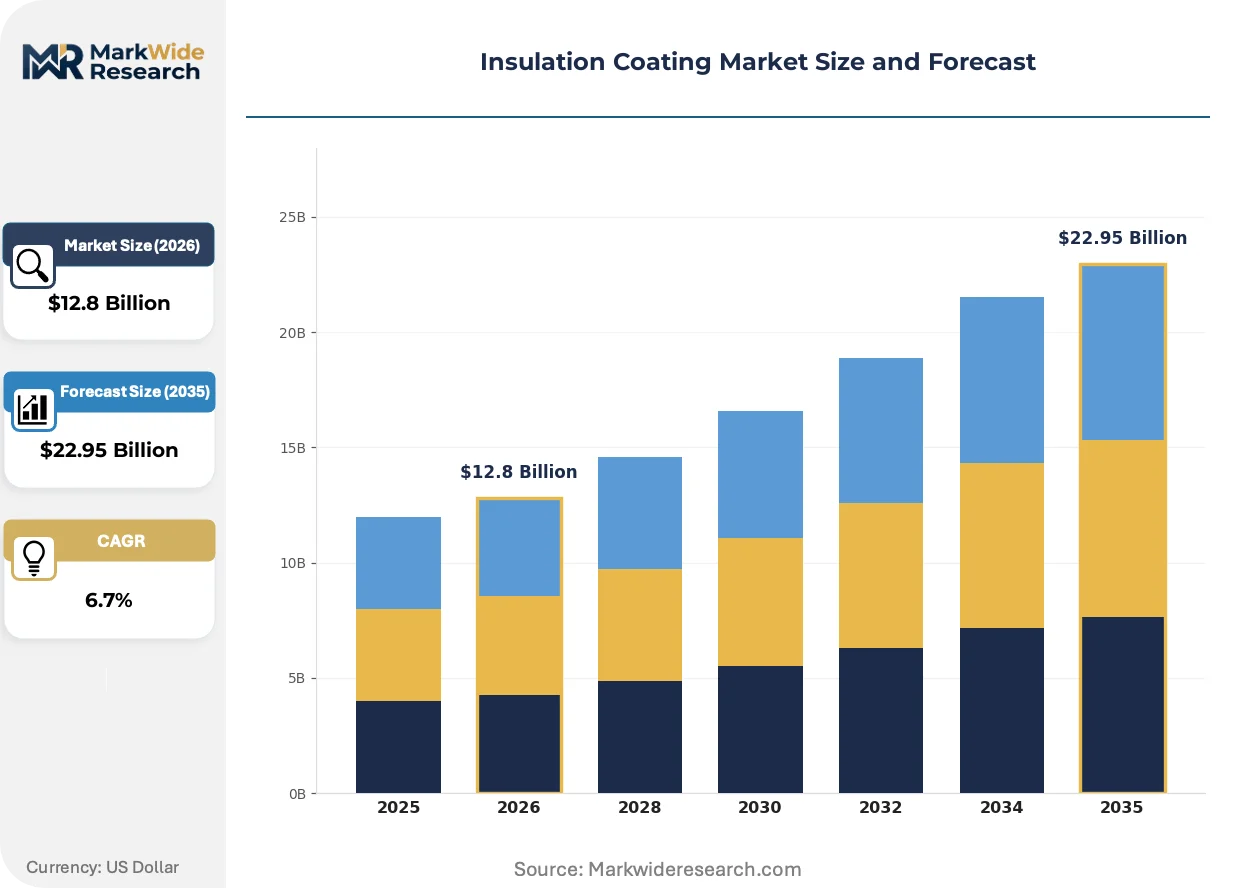
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Insulation, Acoustic Insulation, Fire-Resistant Coating, Waterproof Coating Application: Industrial Equipment, Building & Construction, Transportation, Aerospace Material: Polyurethane, Epoxy, Silicone, Acrylic End User: Manufacturing, Construction, Automotive, Marine |
| Companies Covered | AkzoNobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, BASF SE, Jotun A/S, Nippon Paint Holdings Co., Ltd., Dow Chemical Company, Kansai Paint Co., Ltd., Carboline Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulation Coating Market Emerging Trajectories
Ceramic microsphere technology is decomposing traditional insulation performance hierarchies. Formulators are converging thermal, acoustic, and fire-resistant functions into single-coat systems. Distribution channels are fragmenting between specification-driven project sales and volume retail.
Aerogel-embedded water-borne dispersions are decomposing the thickness-performance tradeoff that has governed insulation coating specification for decades. Aerospace thermal protection engineers and cryogenic equipment fabricators are specifying sub-millimeter dry films that deliver equivalent R-value to 5-10 mm ceramic systems. This compression is enabling weight-critical applications in satellite launch vehicles and LNG transport where every kilogram of coating mass carries fuel-cost penalties.
REACH authorization procedures for chromium trioxide in corrosion-inhibiting primers are forcing reformulation of intumescent basecoats used in commercial steel construction. Coatings manufacturers with established regulatory dossier capabilities are securing continuity of supply while smaller competitors face substance sunset deadlines. The commercial construction segment in Germany and the Netherlands is absorbing price premiums for compliant systems as project specifications harden against grandfathered chemistries.
Certification-driven procurement is consolidating buyer power around approved vendor lists maintained by classification societies and insurance underwriters. Marine newbuild and retrofit contractors are narrowing supplier pools to Lloyd's Register, DNV, and Bureau Veritas pre-qualified coating systems. This concentration is most visible in Singapore, South Korea, and UAE shipyard clusters where project financing ties to hull and machinery insurance coverage.
Insulation Coating Market Segmentation
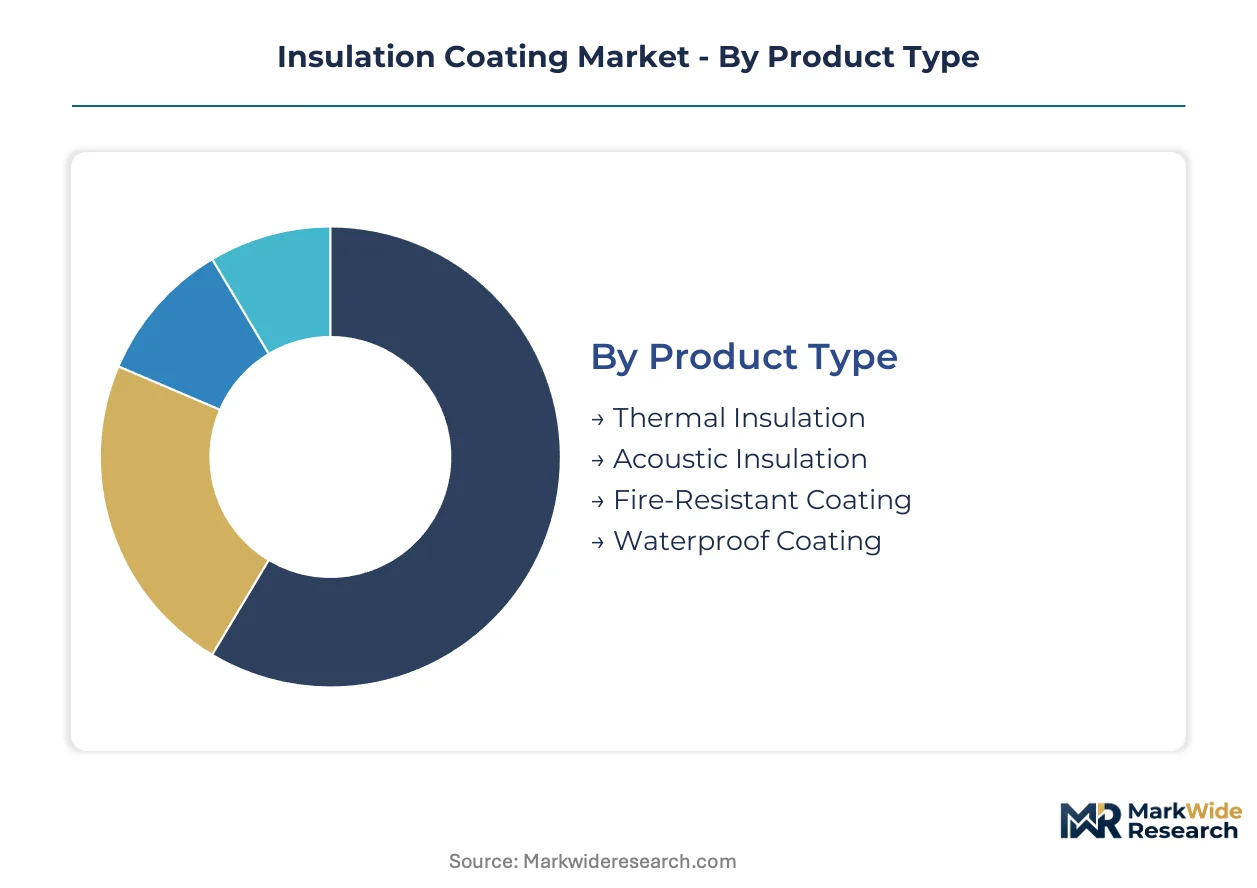
Insulation coating specification diverges sharply across thermal, acoustic, and fire-protection functions, with material chemistry and application thickness determining both performance tier and margin capture. Understanding where volume concentrates versus where premium pricing holds reveals strategic entry points for formulation investments.
Product Type:
Thermal insulation coatings command the deepest margin pools due to energy efficiency compliance mandates driving specification upgrades across building envelopes and process equipment.
- Thermal Insulation:Ceramic microsphere and aerogel-dispersed formulations reduce heat transfer in building envelopes and industrial pipelines. Demand concentrates in China where MEE dual carbon enforcement tightens energy efficiency requirements across steel and petrochemical facilities.
- Fire-Resistant Coating:Intumescent systems expand under heat to form protective char layers on structural steel. IMO SOLAS retrofit cycles in Singapore, South Korea, and UAE shipyards are expanding specification windows for hydrocarbon-resistant marine grades.
- Acoustic Insulation:Viscoelastic polymer layers dampen sound transmission in automotive and architectural applications. Mass-loaded vinyl and asphaltic composites serve HVAC ductwork and vehicle cabin applications.
- Waterproof Coating:Elastomeric membranes block moisture ingress while providing secondary thermal benefits. Below-grade basement and roofing applications in Germany and the Netherlands absorb compliant low-VOC formulations.
The dominant share belongs to Thermal Insulation, while Fire-Resistant Coating is closing the gap fastest.
Application:
Cost tier stratification separates specification-driven project sales from volume-driven maintenance coatings, with aerospace and industrial equipment commanding formulation premiums.
- Building & Construction:Water-borne acrylics penetrate residential retrofits as EU Green Deal thermal efficiency mandates accelerate envelope upgrade programs across Germany, France, and Italy. DIY channel growth through home improvement retailers captures application-skilled homeowners.
- Industrial Equipment:Epoxy and polyurethane systems insulate boilers, tanks, and pipelines in thermally extreme process environments. Backward integration into isocyanate feedstocks sustains margin capture for integrated producers.
- Aerospace:FAA-certified thermal barrier systems meet airworthiness standards for engine components and airframes. Aerogel-embedded sub-millimeter films enable weight-critical satellite launch vehicle applications.
- Transportation:Rail and commercial vehicle manufacturers specify acoustic and thermal composites for passenger comfort and fuel efficiency. LNG transport applications prioritize cryogenic insulation performance per unit thickness.
Building & Construction holds volume leadership, though Aerospace delivers the steepest expansion trajectory as aerogel technology penetrates weight-sensitive platforms.
Material:
Supply concentration in Asian bisphenol-A and epichlorohydrin production shapes geographic cost structures for epoxy systems.
- Polyurethane:Isocyanate-cured formulations dominate industrial equipment and transportation with superior adhesion and chemical resistance. Benzene and propylene feedstock volatility compresses margins for non-integrated formulators.
- Epoxy:Bisphenol-A and epichlorohydrin-based systems anchor specification-driven aerospace and marine applications. REACH authorization pressures on chromium trioxide corrosion primers force intumescent basecoat reformulation investments.
- Acrylic:Water-borne compatibility and lower application skill requirements penetrate DIY and light industrial segments. Interior basement and attic projects in residential construction favor lower-VOC solutions.
- Silicone:High-temperature stability serves exhaust systems and industrial stacks where thermal cycling exceeds organic polymer limits. Premium pricing reflects specialized curing chemistry and limited formulator base.
Polyurethane retains the largest installed base, yet Acrylic is expanding most quickly through retail channel penetration and regulatory-driven VOC reduction.
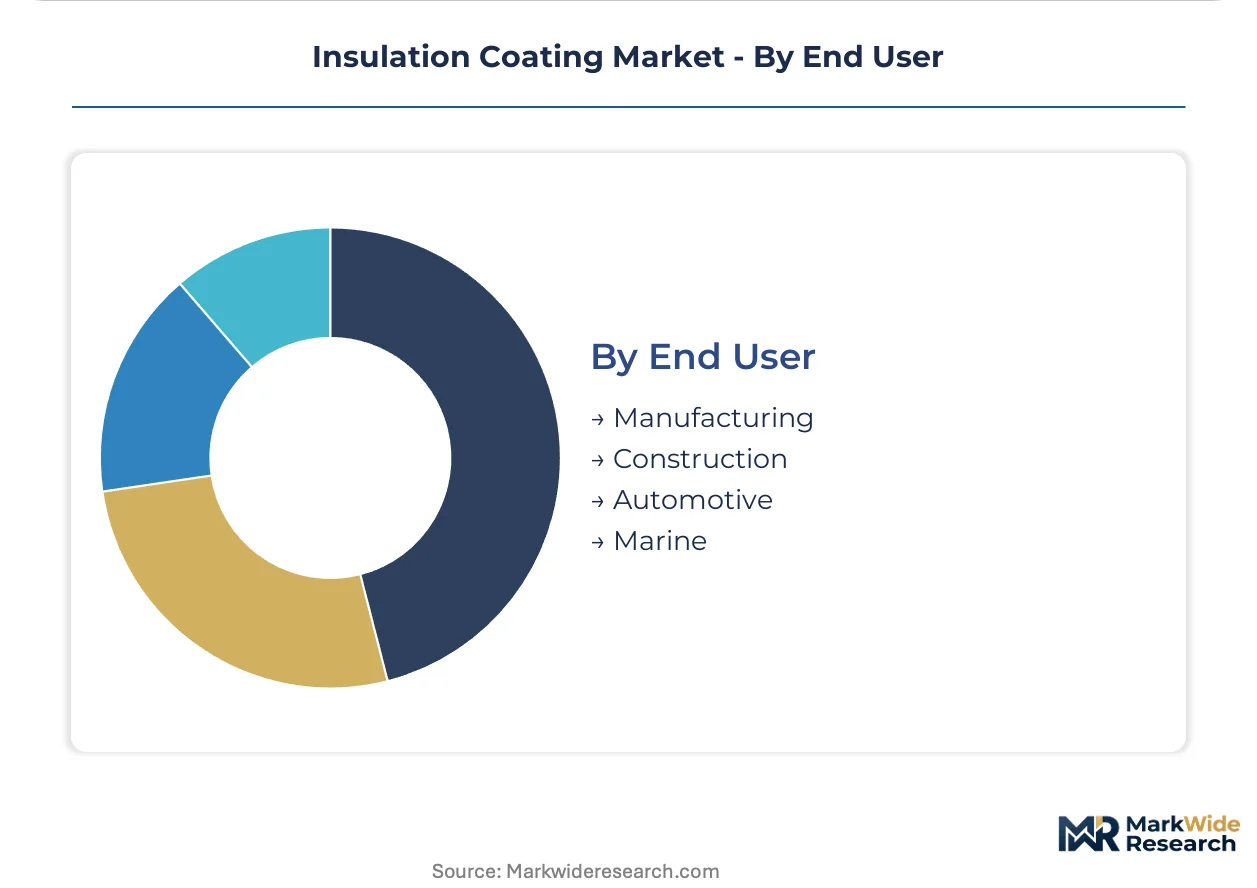
End User:
Customer type fragmentation separates certified applicator-dependent marine and construction markets from manufacturing procurement with technical specification authority.
- Construction:Commercial steel projects in Germany and the Netherlands absorb REACH-compliant intumescent premiums as specifications harden against grandfathered chemistries. Certified applicator gaps extend project timelines and limit contractor pool depth.
- Manufacturing:Steel, cement, and power generation facilities in China face tightening MEE enforcement that directly expands thermal barrier system procurement. Process equipment insulation carries energy efficiency compliance documentation requirements.
- Marine:Lloyd's Register, DNV, and Bureau Veritas pre-qualified coating systems consolidate buyer power in Singapore, South Korea, and UAE shipyard clusters. Hull and machinery insurance coverage ties to approved vendor list compliance.
- Automotive:OEM thermal and acoustic specifications for electric vehicle battery enclosures and cabin comfort create material qualification cycles. Lightweighting priorities favor thin-film high-performance solutions.
Construction maintains the dominant procurement volume, while Marine is gaining share fastest through IMO-mandated SOLAS retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and the Netherlands where REACH-compliant intumescent systems absorb premiums, while cost-sensitive volume procurement dominates in Chinese industrial clusters. Regulatory stringency in European commercial construction contrasts with scale-driven efficiency mandates across Asian process industries.
United States
Aerospace thermal barrier demand anchors specification premiums in FAA-certified applications, while OSHA thermal hazard standards reshape industrial equipment coatings. EPA VOC emissions rules under the Clean Air Act accelerate water-borne acrylic penetration in residential retrofits. Houston and Gulf Coast petrochemical corridors drive procurement of high-temperature pipeline insulation systems.
Germany
Commercial steel construction absorbs REACH-compliant intumescent premiums as specifications harden against grandfathered chromium trioxide chemistries. EU Green Deal thermal efficiency mandates accelerate building envelope retrofit programs across industrial zones. The Ruhr industrial basin and Bavarian manufacturing clusters concentrate demand for process equipment thermal barriers.
China
Steel, petrochemical, and power generation facilities face tightening MEE dual carbon enforcement that directly expands thermal barrier procurement. Industrial energy efficiency retrofit programs widen specification windows for high-performance insulation on boilers and pipelines. Yangtze River Delta and Pearl River Delta manufacturing corridors concentrate infrastructure buildout demand.
Singapore
Marine SOLAS retrofit cycles expand specification windows for hydrocarbon-resistant passive fire protection coatings in shipyard clusters. Lloyd's Register and DNV pre-qualified coating systems consolidate buyer power among repair contractors. The Tuas shipyard complex and Jurong marine engineering hub anchor regional demand for classification-society-approved systems.
India
PLI scheme incentives and BIS energy efficiency standards open specification windows for thermal barrier systems in steel and cement plants. Industrial infrastructure buildout across process industries widens addressable demand for high-temperature equipment coatings. Gujarat and Maharashtra industrial corridors concentrate procurement from manufacturing facilities facing compliance documentation requirements.
Insulation Coating Market Vendor Landscape
Concentration sits with integrated resin producers who control alkyd, epoxy, and polyurethane feedstock quality. Specialty formulators compete on application expertise and certification maintenance. Three archetypes dominate: European chemical conglomerates with captive resin production, Asian coating specialists with regional distribution density, and aerospace-certified systems houses with FAA airworthiness credentials. Competitive moves center on backward integration into isocyanate supply and regulatory dossier investments for REACH continuity.
Among European-integrated chemical producers, AkzoNobel N.V. and BASF SE exemplify the archetype of captive resin capability sustaining margin capture across specification-driven segments. PPG Industries, Inc. anchors the aerospace-certified tier where FAA thermal barrier standards create qualification barriers. These three represent distinct competitive positions: feedstock control, regulatory infrastructure scale, and certification-driven specification lock-in.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| BASF SE |
| Jotun A/S |
| Nippon Paint Holdings Co., Ltd. |
| Dow Chemical Company |
| Kansai Paint Co., Ltd. |
| Carboline Company |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between European formulators and Asian epoxy resin suppliers lock in feedstock access while capping price visibility against benzene and propylene volatility. These arrangements concentrate procurement power with integrated producers who can absorb margin compression during raw material spikes.
Pricing Analysis
The customization-premium spread separates specification-driven project pricing from volume retail. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and application thickness requirements. Pricing pressure stems from isocyanate feedstock volatility compressing margins for non-integrated formulators. DIY channel buyers exhibit highest price sensitivity, while aerospace-certified procurement shows lowest elasticity due to FAA airworthiness qualification barriers.
Supply Chain Analysis
Bisphenol-A and epichlorohydrin production chokepoints in China, South Korea, and Taiwan concentrate epoxy resin supply for coating manufacturers. Formulation draws from isocyanate feedstocks, ceramic microsphere additives, and aerogel dispersions. Single-source vulnerability in Asian resin output exposes European and North American coaters to geographic concentration risk. Distribution runs through specification-driven project sales for industrial and marine segments alongside retail channels for water-borne acrylic DIY applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against pre-formed insulation boards and spray foam systems that threaten coating-based thermal barriers in building envelope applications.
For Market Incumbents: Compound regulatory dossier investments to secure REACH continuity of supply while smaller competitors face substance sunset deadlines. Deepen backward integration into MDI and TDI isocyanate feedstocks to sustain margin capture against benzene and propylene volatility. Certification maintenance with Lloyd's Register and DNV locks in marine retrofit specification windows.
For New Entrants and Emerging Players: Anchor in India's PLI scheme corridors where BIS energy efficiency standards are opening specification windows for thermal barrier systems in steel and cement plants. Target water-borne acrylic retail channels serving application-skilled homeowners in EU Green Deal retrofit zones. Partner with home improvement retailers for DIY channel distribution bypassing certified applicator requirements.
For Investors and Strategic Acquirers: Capital is best deployed toward European-integrated chemical producers with captive alkyd and epoxy resin capabilities that control raw material quality and supply security. The five-to-ten year viability window favors formulators with regulatory affairs infrastructure scale. Monitor carbon border adjustment mechanism developments as inflection indicator for regional capacity commitment decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Feedstocks | Captive MDI/TDI supply insulates margin capture against benzene and propylene volatility. |
| REACH Dossier Investment for Continuity of Supply | Regulatory infrastructure secures market position as chromium trioxide authorization deadlines approach. |
| Aerogel Dispersion Technology Scale-Up | Sub-millimeter dry films enable weight-critical aerospace and cryogenic equipment specifications. |
| Marine Classification Society Pre-Qualification | Lloyd's Register and DNV approval consolidates buyer power in Singapore and South Korean shipyards. |
| Water-Borne Acrylic Retail Channel Expansion | DIY penetration captures EU Green Deal residential retrofit demand with lower-VOC formulations. |
Methodological Framework
A spread of perspectives from coating formulators, plant engineers at steel and petrochemical facilities, certified intumescent applicators, and marine classification society surveyors converged on the working assumptions. Primary fieldwork combined with secondary validation from customs trade data, SEC 10-K filings, ECHA substance dossiers, and Cefic industry reports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled include product type, application, material chemistry, and end-user procurement authority across the analysis window. CAGRs derived from production capacity buildout trajectories, regulatory enforcement timelines, and energy efficiency retrofit program commitments. Aerogel technology penetration rates and IMO SOLAS retrofit cycle timing served as industry-specific forecast inputs.
Material uncertainties — feedstock price volatility, REACH authorization delays, carbon border adjustment implementation — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and industrial infrastructure investment continuity. Practitioners should keep alternative scenarios live as MEE dual carbon enforcement intensity and EU Green Deal funding allocation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Hydrophilic Coatings Market
Coatings
Conductive Shielding Coatings for Battery Management Systems Market
Coatings
Trim Coatings Market
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
Anti-Graffiti Coatings Market
Coatings
Extrusion Coating Market
Coatings
Global Metal Coatings Market
Coatings
Global Abrasion Resistant Coatings Market
Coatings
Zero Friction Coatings Market
Coatings
Urethane Surface Coatings Market
Coatings
Solvent Borne Coatings Market
Coatings
United States Automotive OEM Coatings Market
Coatings
PU Coatings Market
Coatings
Global Diamond Coatings Market
Coatings
Europe Coil Coatings Market
Coatings
Global Nanocoatings Market