
 Dielectric Fluid Market | 2026-2036
Dielectric Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Dielectric Fluid Market Outlook
Utility procurement for transformer fluids is consolidating around fewer, larger fleet operators with standardized specifications. Shell leverages its integrated base oil supply chain to compete on volume contracts across European and Asian utilities. ExxonMobil Corporation anchors its position through backward integration into Group II and Group III base stocks, sustaining cost advantages in mineral oil dielectrics. 3M Company differentiates via fluorinated fluid technology leadership in niche high-voltage and electronics cooling segments.
Dielectric fluid is an electrically insulating liquid formulated to suppress corona discharge, arcing, and thermal runaway in high-voltage equipment, with key specifications including breakdown voltage above 30 kV, low dissipation factor, and controlled viscosity across operating temperatures. Mineral oil retains dominant volume share in legacy transformer fleets, though synthetic ester and natural ester categories are capturing fastest growth as fire-safety regulations tighten and utilities prioritize biodegradable alternatives. Silicone fluids occupy premium positioning in capacitors and specialty switchgear where thermal stability and wide temperature range performance justify higher unit economics.
The EPA governs PCB phase-out requirements for electrical equipment in the United States, directly compelling transformer retrofits and fluid replacements. ECHA implements REACH restrictions on persistent organic pollutants across Europe, steering manufacturers toward bio-based ester chemistries and away from certain halogenated formulations. ASTM D3487 and IEC 60296 standards define minimum performance thresholds for mineral and synthetic insulating oils, creating compliance barriers for new entrants. Stakeholders must monitor evolving fire-safety codes and carbon-accounting rules to align product portfolios with procurement criteria that utilities are embedding into long-term maintenance contracts.
Market Dynamics
Grid operators are consolidating transformer procurement around fire-safety compliance mandates, forcing dielectric fluid suppliers to reconfigure formulations and certification pathways. This structural pressure is compressing product development cycles while elevating biodegradable esters above legacy mineral oils in utility specifications.
Growth Catalysts
- EPA PCB Phase-Out Mandates:Equipment replacement schedules in the United States are accelerating fluid procurement for transformer retrofits. Utilities must decommission PCB-contaminated assets by fixed deadlines.
- Data Center Thermal Management:Hyperscale facilities in Northern Virginia and Texas are specifying synthetic ester fluids for fire-safe high-voltage infrastructure. Rack density requirements demand improved thermal stability.
- EU F-Gas Regulation Tightening:Restrictions on fluorinated greenhouse gases are redirecting capacitor and switchgear manufacturers toward silicone and ester alternatives. Formulation R&D budgets are reallocating accordingly.
Market Restraints
- Base Oil Supply Concentration:Group II and Group III base stock production clusters in the US Gulf Coast and Singapore. Geopolitical disruptions or refinery outages transmit directly to dielectric fluid pricing.
- Natural Ester Oxidation Limits:Vegetable-based formulations exhibit faster degradation at elevated temperatures. This technical ceiling restricts deployment in heavily loaded distribution transformers.
- REACH Compliance Burden:ECHA registration requirements for novel bio-based chemistries extend time-to-market by 18-24 months. Small formulation houses lack dedicated regulatory affairs capacity.
Strategic Opportunities
- India Grid Expansion:Power Grid Corporation of India and state utilities are tendering for 765 kV transformer fleets. Ester fluid penetration remains below 15% in this procurement wave.
- Offshore Wind Converter Platforms:Synthetic ester demand is converging with subsea cable insulation requirements. North Sea and US Atlantic Coast projects specify fire-safe fluids for unmanned installations.
- Carbon Accounting Integration:EU CSRD disclosure rules are embedding lifecycle emissions into utility procurement scoring. Bio-based fluid suppliers gain preference weighting against mineral oil incumbents.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in high-voltage insulation chemistry and biodegradability testing concentrates at a handful of European and US research institutes. Recruitment pipelines are inadequate.
- ASTM D3487 Revision Lag:Updated standards for natural ester performance thresholds remain in committee. Certification delays are freezing product launches for 12-18 month windows.
- Legacy Fleet Compatibility Testing:Utilities demand exhaustive gasket and seal material validation before approving fluid retrofits. Laboratory backlog extends field trial timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dielectric Fluid Market |
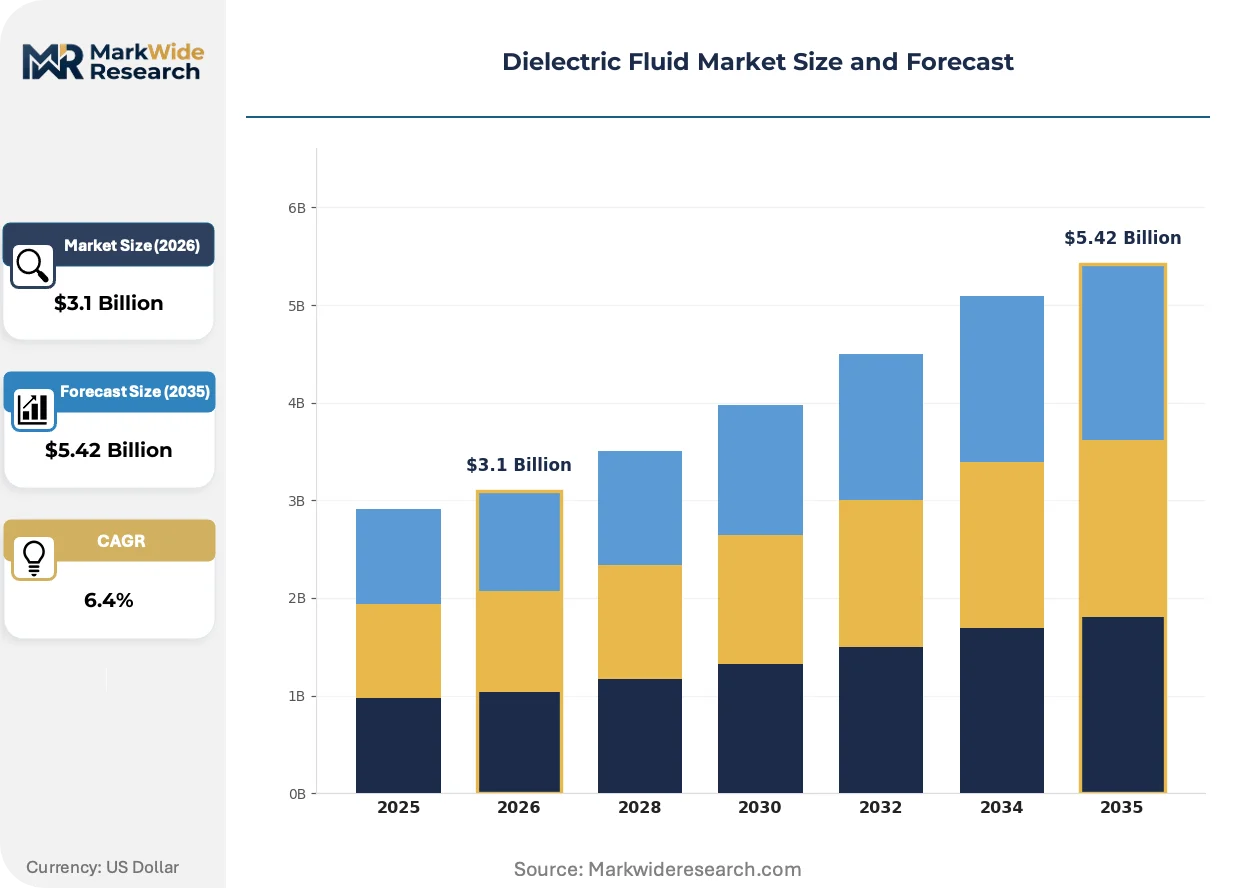
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Ester, Natural Ester, Silicone Application: Transformers, Capacitors, Switchgear, Cooling Systems End User: Utilities, Manufacturing, Renewable Energy, Data Centers Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Shell, ExxonMobil Corporation, 3M Company, Castrol Limited, TotalEnergies, FUCHS, Dow Inc., Engineered Fluids, The Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dielectric Fluid Market Strategic Shifts
Dielectric fluid technology is bifurcating between performance-optimized synthetics for extreme conditions and cost-engineered bio-based formulations for mass-market utilities. This divergence is fragmenting R&D investment and reshaping supplier-specialization boundaries.
Synthetic ester chemistry is converging with nanofluid additive systems to enhance thermal conductivity without sacrificing dielectric strength. Transformer OEMs in Germany and Japan are piloting these hybrid formulations for 500 kV+ applications. The convergence is compressing the performance gap between esters and traditional silicone fluids in high-temperature operating environments.
REACH restrictions on persistent organic pollutants are compelling European manufacturers to eliminate certain halogenated fire-retardant additives from capacitor fluids. Industrial consequence includes accelerated reformulation programs and supply contract renegotiations. Specialty chemical suppliers serving the switchgear segment are most affected, with several shifting production to bio-based phosphorus ester alternatives.
Utility procurement departments are unbundling fluid supply from transformer OEM maintenance contracts, creating direct purchasing relationships with specialized dielectric suppliers. This channel disintermediation is most visible in US municipal utilities and cooperative networks. Independent fluid testing laboratories are capturing new revenue streams by certifying third-party compatibility for retrofits.
Dielectric Fluid Market Segmentation
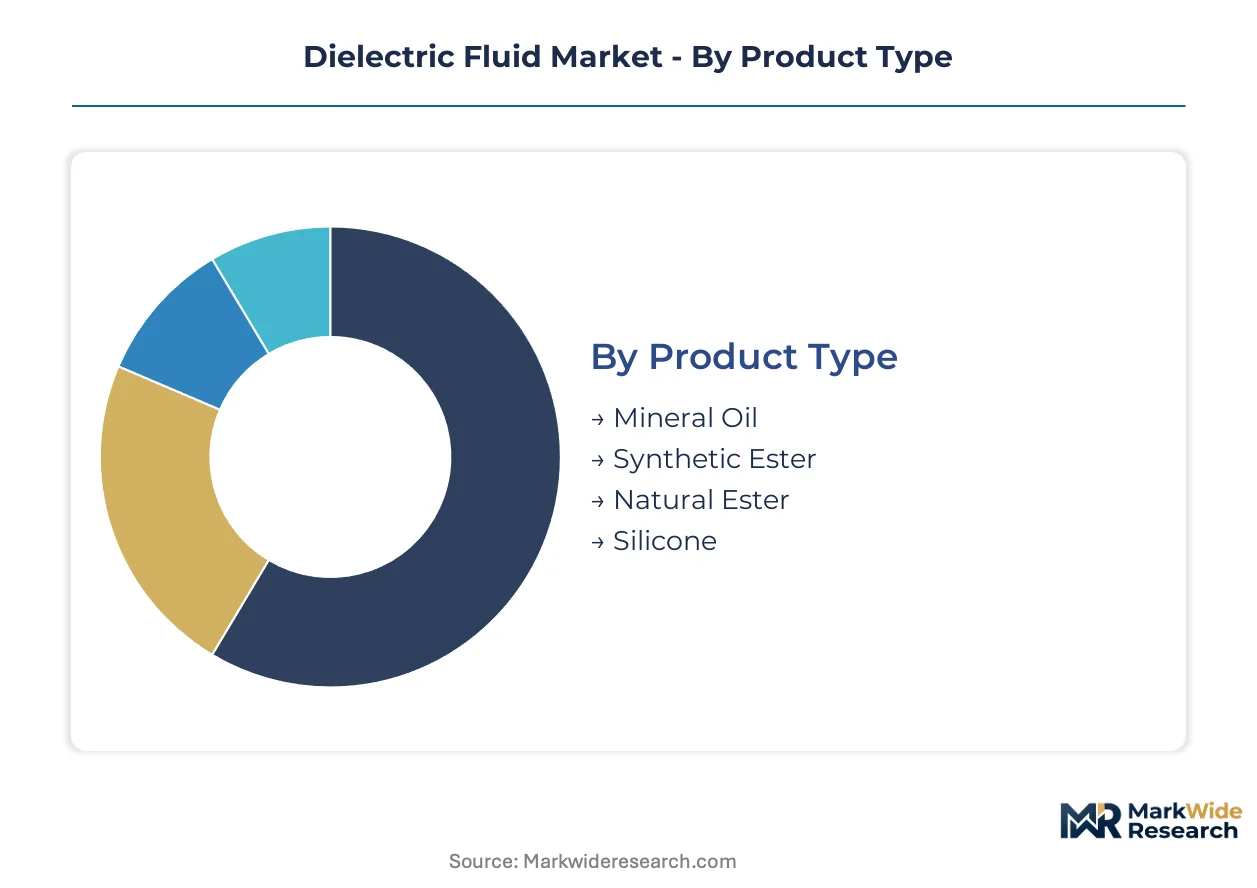
Dielectric fluid procurement patterns diverge sharply across product chemistries and end-use applications. Utility fleet operators, data center developers, and renewable project sponsors each impose distinct specification hierarchies that reshape supplier prioritization and formulation investment.
Product Type:
Transformer fleet replacement cycles and fire-safety code upgrades are redistributing volume across fluid chemistries as utilities phase out legacy mineral oil systems.
- Mineral Oil:Refined petroleum-based insulating fluid with established ASTM D3487 compliance pathways. Demand concentrates in United States municipal utilities completing scheduled maintenance on pre-2010 transformer fleets where retrofit economics remain unfavorable.
- Synthetic Ester:Engineered ester chemistry delivering fire-safe performance with biodegradability credentials. Procurement from Northern Virginia and Texas data center operators is accelerating as rack density requirements outstrip mineral oil thermal limits.
- Natural Ester:Vegetable oil-derived formulations meeting IEC 62770 specifications. European distribution network operators specify these for urban substation retrofits under EU Green Deal procurement scoring.
- Silicone:Polydimethylsiloxane-based fluid occupying premium thermal stability positioning. Deployed in Japanese capacitor manufacturing and German 500 kV+ switchgear where wide temperature range justifies unit cost premiums.
Mineral oil sits at the top of the volume ranking, with synthetic ester climbing the fastest.
Application:
Equipment-specific thermal profiles and voltage stress environments segment demand into four distinct procurement channels with diverging specification stringency.
- Transformers:Power and distribution transformers consume the largest fluid volumes per installation. United States investor-owned utilities are consolidating procurement around synthetic ester for new 138 kV+ fleet additions.
- Capacitors:Film-foil and metallized film capacitor designs require low-viscosity impregnation fluids. REACH restrictions on halogenated additives are forcing European manufacturers toward bio-based phosphorus ester alternatives.
- Switchgear:Gas-insulated and air-insulated switchgear specify dielectric fluids for arc quenching and insulation. Offshore wind converter platforms in the North Sea specify fire-safe synthetic esters for unmanned installations.
- Cooling Systems:Direct liquid cooling for high-power electronics and traction systems. Data center thermal management requirements in Singapore and Ireland are piloting synthetic ester loops for server rack immersion.
Transformers command the dominant share of procurement volume, while cooling systems applications gain share fastest.
End User:
Customer-type segmentation reveals diverging price sensitivity and technical specification authority across institutional buyers.
- Utilities:Grid operators with centralized engineering standards and long-term maintenance contracts. United States cooperative utilities are unbundling fluid supply from transformer OEM agreements to negotiate direct supplier relationships.
- Manufacturing:Industrial facilities with captive transformer fleets and process-critical power infrastructure. German automotive battery plants specify synthetic ester for fire-safe medium-voltage distribution.
- Renewable Energy:Wind and solar project developers with EPC-contracted electrical infrastructure. Indian solar park operators represent emerging demand as domestic content requirements expand local transformer manufacturing.
- Data Centers:Hyperscale and colocation operators with rack-density-driven thermal constraints. Ashburn, Virginia and Dallas-Fort Worth clusters are specifying synthetic ester for 345 kV substation buildouts.
Utilities anchor procurement volume, with data centers expanding most quickly.
Distribution Channel:
Channel structure reflects the technical validation requirements and procurement scale of different end-user categories.
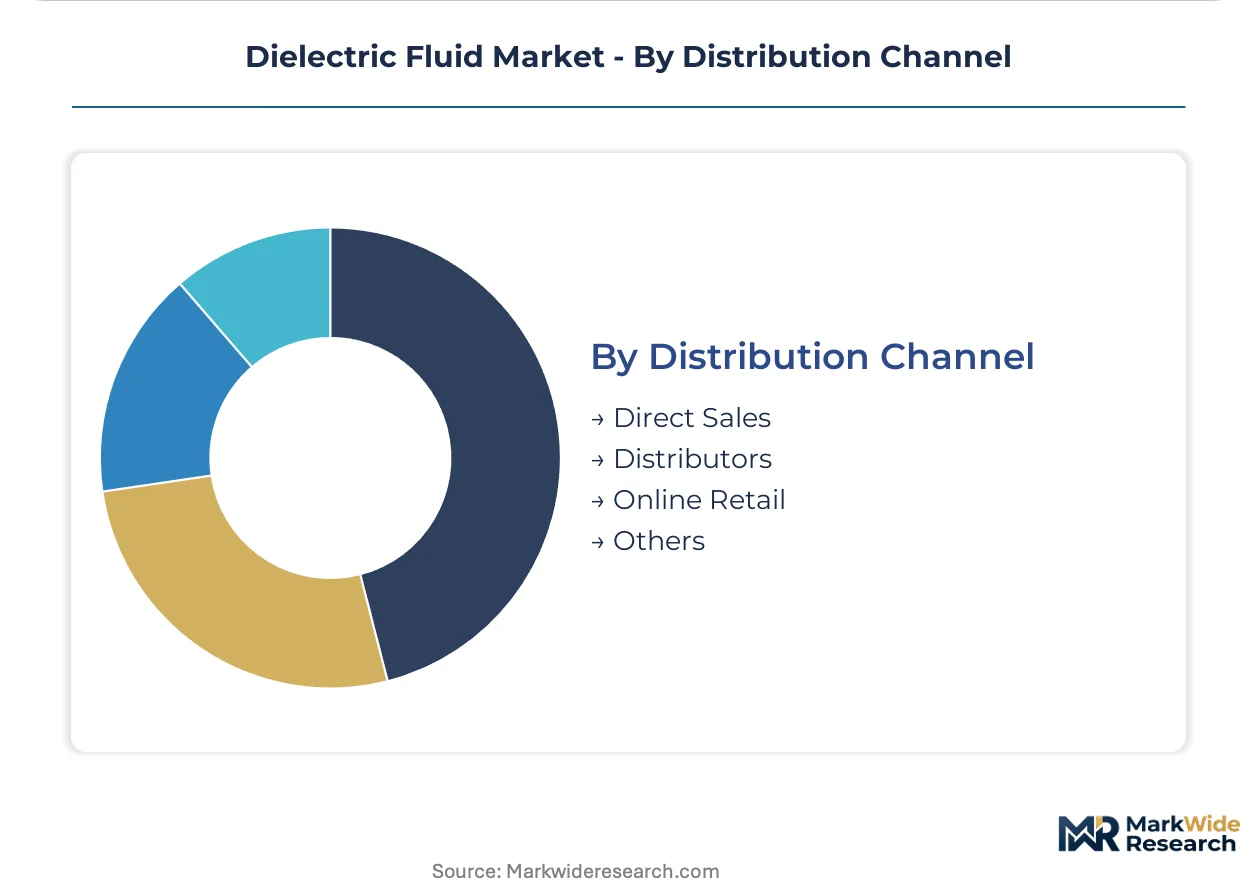
- Direct Sales:Manufacturer-to-utility relationships for fleet-scale contracts with embedded testing protocols. ExxonMobil and Shell compete for United States IOU volume agreements through dedicated account engineering teams.
- Distributors:Regional stocking distributors serving municipal utilities and industrial maintenance departments. European electrical wholesalers carry synthetic ester inventory for same-day transformer service calls.
- Online Retail:E-commerce platforms for small-volume maintenance, testing equipment, and compatibility kits. Limited to drum quantities and ancillary products rather than bulk fluid procurement.
- Others:Fluid-as-a-service contracts and transformer OEM bundled supply arrangements. Channel share is contracting as utilities disintermediate OEMs for direct fluid purchasing.
Direct sales holds the volume leadership position, with distributor relationships gaining operational importance in service-intensive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States utilities outpace German grid operators in synthetic ester procurement volumes, while Indian state electricity boards lag both markets in fire-safe fluid adoption despite comparable fleet ages.
United States
Investor-owned utilities in Texas and Virginia are specifying synthetic ester fluids for 345 kV substation buildouts serving data center clusters. EPA PCB phase-out mandates compel transformer retrofits across municipal fleets. Northern Virginia's Ashburn-Loudoun corridor anchors hyperscale facility procurement.
Germany
Transmission system operators prioritize synthetic esters for offshore wind converter platforms in the North Sea. ECHA REACH restrictions on halogenated additives accelerate reformulation programs. Bavarian transformer OEMs pilot nanofluid-enhanced ester formulations for 500 kV applications.
India
Power Grid Corporation tenders for 765 kV transformer fleets with ester penetration below 15% in current procurement waves. Central Electricity Authority efficiency standards tighten thermal performance requirements. Gujarat and Maharashtra industrial corridors drive captive transformer fluid demand.
Japan
Capacitor manufacturers specify silicone fluids for high-voltage film-foil designs under METI energy efficiency guidelines. JIS standards define dielectric performance thresholds for industrial switchgear. Kansai region chemical producers supply refined silicone formulations to domestic OEMs.
United Kingdom
Distribution network operators retrofit urban substations with natural ester fluids under EU Green Deal procurement scoring. Environment Agency regulations align with REACH pollutant restrictions. Scottish Power integrates bio-based fluid specifications into long-term maintenance contracts.
Dielectric Fluid Market Competitive Environment
North American producers anchor one tier; European specialists hold differentiated positioning in bio-based formulations. Market structure concentrates around integrated petroleum majors and focused chemical houses. Three archetypes dominate: backward-integrated base oil suppliers, synthetic ester technology licensors, and silicone fluid specialty manufacturers. Capacity expansion and direct utility procurement relationships constitute the dominant competitive vectors.
Within the integrated petroleum tier, Shell, ExxonMobil Corporation, and TotalEnergies exemplify scale-driven supply chain control. These entities occupy positions defined by captive base stock production and fleet-scale contract engineering. Dow Inc. and 3M Company represent specialty chemical positioning, anchoring premium thermal stability and fluorinated fluid segments respectively.
| Leading Market Players |
|---|
| Shell |
| ExxonMobil Corporation |
| 3M Company |
| Castrol Limited |
| TotalEnergies |
| FUCHS |
| Dow Inc. |
| Engineered Fluids |
| The Lubrizol Corporation |
| Others |
Value Chain & Pricing Dynamics
Backward integration into Group II and Group III base stock production anchors pricing power for integrated petroleum majors while compressing margins for formulation houses dependent on spot market purchases. Shell and ExxonMobil Corporation leverage captive refinery output to undercut competitors on volume contracts for United States investor-owned utilities.
Pricing Analysis
Capacity additions in Singapore and the US Gulf Coast are reshaping price floors for mineral oil dielectrics as new Group III base stock units come online. Contract-based long-term offtake dominates utility procurement, with price differentiation driven by certification tier and volume scale. Cost compression in synthetic esters is intensifying because Dow Inc. and specialty chemical suppliers are expanding esterification capacity. Municipal utilities exhibit highest price sensitivity, while data center operators prioritize fire-safety specifications over unit economics.
Supply Chain Analysis
Fluid recovery and re-refining programs for transformer retrofits are creating reverse-logistics revenue streams for specialized service providers in Germany and the United States. Base oil supply concentrates in the United States, Singapore, and South Korea, with formulation chemistry expertise clustering in Germany and Japan. Raw material flows draw from petroleum distillates, vegetable oil feedstocks, and siloxane precursors. Single-source vulnerability runs through Singapore refinery complexes for Asian utility procurement. Distribution runs through direct manufacturer-to-utility relationships for fleet-scale contracts, supplemented by regional electrical wholesalers for emergency service calls.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dielectric fluid market represents a late-cycle quality story as utility procurement shifts toward biodegradable ester specifications with embedded carbon accounting. Premium thermal stability and fire-safety credentials now command preference weighting in long-term maintenance contracts.
For Market Incumbents: Hedge against synthetic ester commoditization by securing backward integration into bio-based feedstock supply chains and accelerating REACH pre-registration for novel chemistries. Mineral oil incumbents face displacement risk from EU F-Gas Regulation tightening and EPA PCB phase-out mandates. Certification investment in IEC 62770 and ASTM D3487 compliance creates switching costs for utility customers.
For New Entrants and Emerging Players: Capture white-space in India's 765 kV transformer procurement wave where ester penetration remains below fifteen percent. Offshore wind converter platforms in the North Sea and US Atlantic Coast represent the most penetrable application segment for fire-safe synthetic esters. A direct sales model with embedded fluid testing protocols offers the strongest go-to-market angle against established distributor relationships.
For Investors and Strategic Acquirers: Roll-up economics work for synthetic ester technology licensors because formulation chemist scarcity concentrates expertise at a handful of European and US research institutes. Five-to-ten year viability favors suppliers with demonstrated utility direct procurement relationships and REACH registration capacity. Monitor ASTM D3487 revision timing and ECHA bio-based chemistry approval velocity as inflection indicators for product launch windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Stock Production | Captive refinery output secures cost position for United States utility volume contracts. |
| REACH Pre-Registration for Bio-Based Chemistries | ECHA compliance accelerates time-to-market for natural ester formulations in European distribution networks. |
| Direct Utility Procurement Relationships | Unbundling fluid supply from transformer OEM agreements captures margin from cooperative utilities. |
| Nanofluid Additive R&D Partnerships | German and Japanese OEM pilots for 500 kV+ applications compress performance gaps with silicone fluids. |
| Fluid Recovery and Re-Refining Infrastructure | Transformer retrofit mandates in the United States create recurring service revenue streams. |
Study Parameters
Direct dialogue with utility procurement directors, transformer OEM technical leads, specialty chemical R&D directors, and independent fluid testing laboratory managers grounded the qualitative assessment. Secondary validation drew from EPA enforcement databases, ECHA registration filings, IEC and ASTM standard committee records, and United States customs import data. Bottom-up segment sizing triangulated against top-down utility capital expenditure disclosures.
Market value and volume estimates emerged from modeling fluid demand across transformer, capacitor, switchgear, and cooling system applications over the projection horizon. Segmentation dimensions included product chemistry tier, equipment voltage class, end-user procurement authority, and regional regulatory framework. CAGRs derived from utility fleet replacement schedules, data center buildout pipelines, and renewable energy interconnection queues. Forecast inputs incorporated EPA PCB phase-out compliance deadlines and EU F-Gas Regulation amendment trajectories.
Underlying measurement precision varies by segment; synthetic ester procurement in United States data center clusters carries tighter precision than natural ester adoption in Indian state electricity boards. Forecasts embed assumptions about ASTM D3487 revision timing and ECHA bio-based chemistry registration velocity. Practitioners should monitor EPA enforcement intensity, EU CSRD disclosure adoption rates, and Indian Central Electricity Authority efficiency standard amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
OEM Insulation Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
Thermal Conductive Polymer Materials Market
Insulation Materials
Expanded Perlite Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Fire Resistant Cable Materials Market
Insulation Materials
Fiberglass Duct Wrap Insulation Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Global Pipe Insulation Market
Insulation Materials
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market
Insulation Materials
Microporous Insulation Material Market
Insulation Materials
Roofing Underlying Materials Market
Insulation Materials
Acoustic Materials Market
Insulation Materials
Technical Foam Market
Insulation Materials
Global Extruded Polypropylene Foam Market