
 Funeral Products and Services Market | 2026-2036
Funeral Products and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Funeral Products and Services Market Analytics
North American casket manufacturing is decoupling from traditional steel supply chains as regional producers shift toward biodegradable materials and domestic wood sourcing. Service Corporation International leverages its vertically integrated cemetery-funeral home network to sustain pricing power across key U.S. metropolitan corridors. Matthews International Corporation anchors the premium memorialization segment through bronze and granite monument production, while Dignity Plc competes in the British market with standardized service packages and pre-need funeral plan offerings.
Funeral products and services encompass the design, manufacture, and delivery of burial vessels, cremation containers, memorial artifacts, and ceremonial coordination for deceased individuals and their families. Casket production typically employs 18-gauge steel, solid hardwoods, or woven natural fibers with interior fabric lining and sealing mechanisms to ensure dignified transport and interment. Cremation services now lead volume growth as municipal cemetery capacity tightens and religious prohibitions weaken across Christian denominations. Memorial items capture expanding margin pools as families commission personalized urns, digital legacy platforms, and keepsake jewelry containing processed remains.
The U.S. Federal Trade Commission enforces the Funeral Rule, requiring itemized price disclosures that strip bundled service packages and empower consumer comparison shopping. State cemetery boards and environmental regulators in California, Florida, and New York impose groundwater protection standards for embalming chemical discharge and burial vault permeability. Stakeholders must monitor how green burial certifications and alkaline hydrolysis permitting spread across jurisdictions, as these approvals determine which service providers can capture shifting preferences away from conventional interment practices.
Market Dynamics
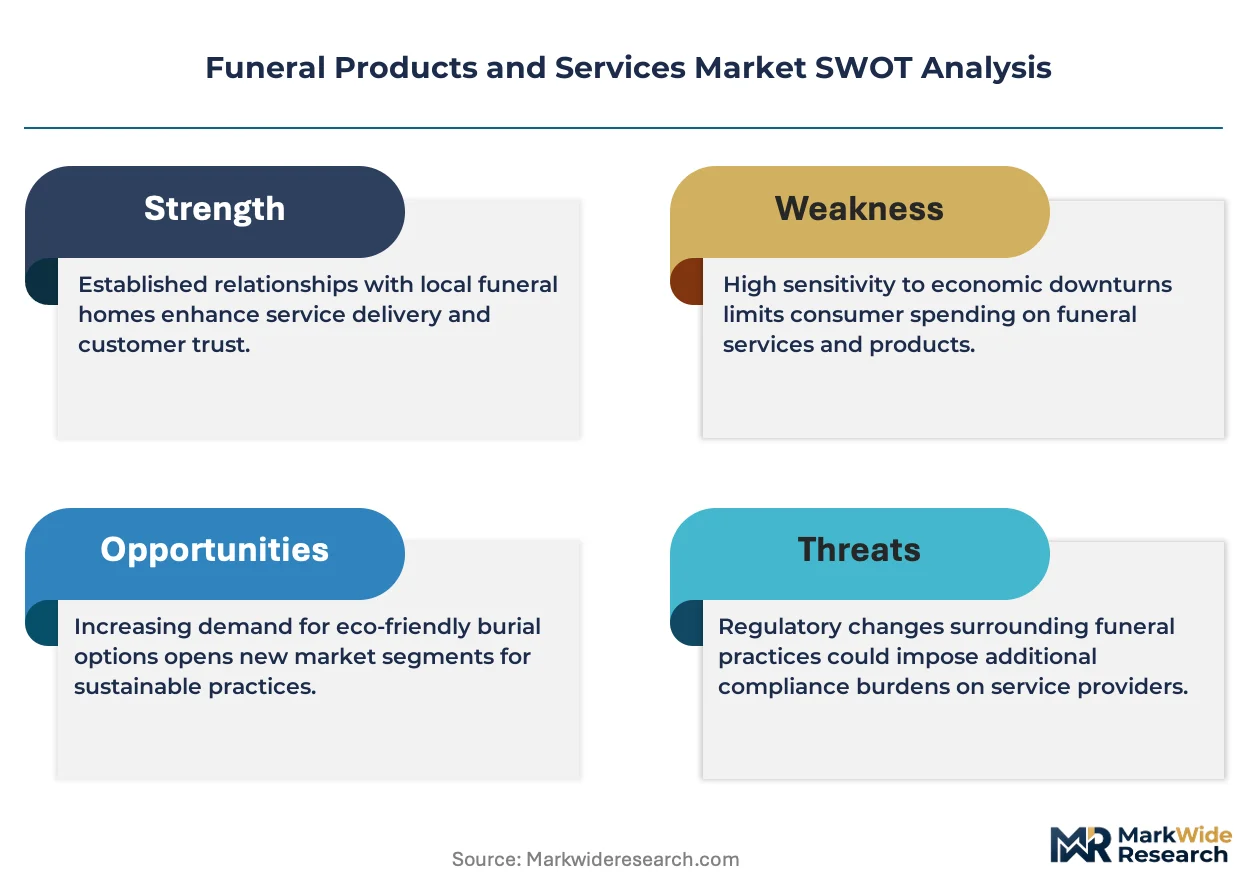
Cremation volume acceleration is compressing casket demand while expanding memorialization software and processed-remain keepsake production. The FTC Funeral Rule's itemized pricing mandate strips bundled service profitability and forces funeral homes to compete on transparency.
Growth Catalysts
- Urban cemetery capacity exhaustion:Municipal burial ground scarcity in Shanghai, Los Angeles, and Mumbai accelerates cremation adoption and drives demand for columbarium niches and scattering gardens.
- REACH-compliant biodegradable materials:European Union chemical safety standards incentivize hemp, mycelium, and untreated wood casket production, opening premium green burial segments.
- Alkaline hydrolysis permitting expansion:Water-based disposition technology gains regulatory approval in California, Colorado, and Florida, offering lower-emission alternatives to flame cremation.
Market Restraints
- Steel input cost volatility:18-gauge steel sheet price fluctuations squeeze casket manufacturer margins and complicate long-term funeral home contract pricing.
- Embalming chemical discharge regulations:California, New York, and Florida impose groundwater protection standards that elevate compliance costs for traditional full-service funeral operations.
- Direct cremation substitution:No-ceremony disposition strips ancillary revenue from memorial services, flowers, and viewing facilities.
Strategic Opportunities
- Digital legacy platform integration:Cloud-based tribute services and AI-generated memorial content create recurring revenue streams from annual subscription renewals.
- Pre-need funeral plan penetration:Aging demographics in Germany, Japan, and Italy expand advance payment contract pools that lock in future service volume.
- Green burial certification expansion:Green Burial Council and Conservation Burial Alliance standards enable price premiums for unembalmed interment in protected natural areas.
Industry Challenges
- Embalmer workforce attrition:Mortuary science program enrollment declines create licensed practitioner shortages in rural service territories.
- Crematory retort upgrade cycles:EPA mercury emissions standards and fuel efficiency mandates force capital-intensive equipment replacement at independent operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Funeral Products and Services Market |
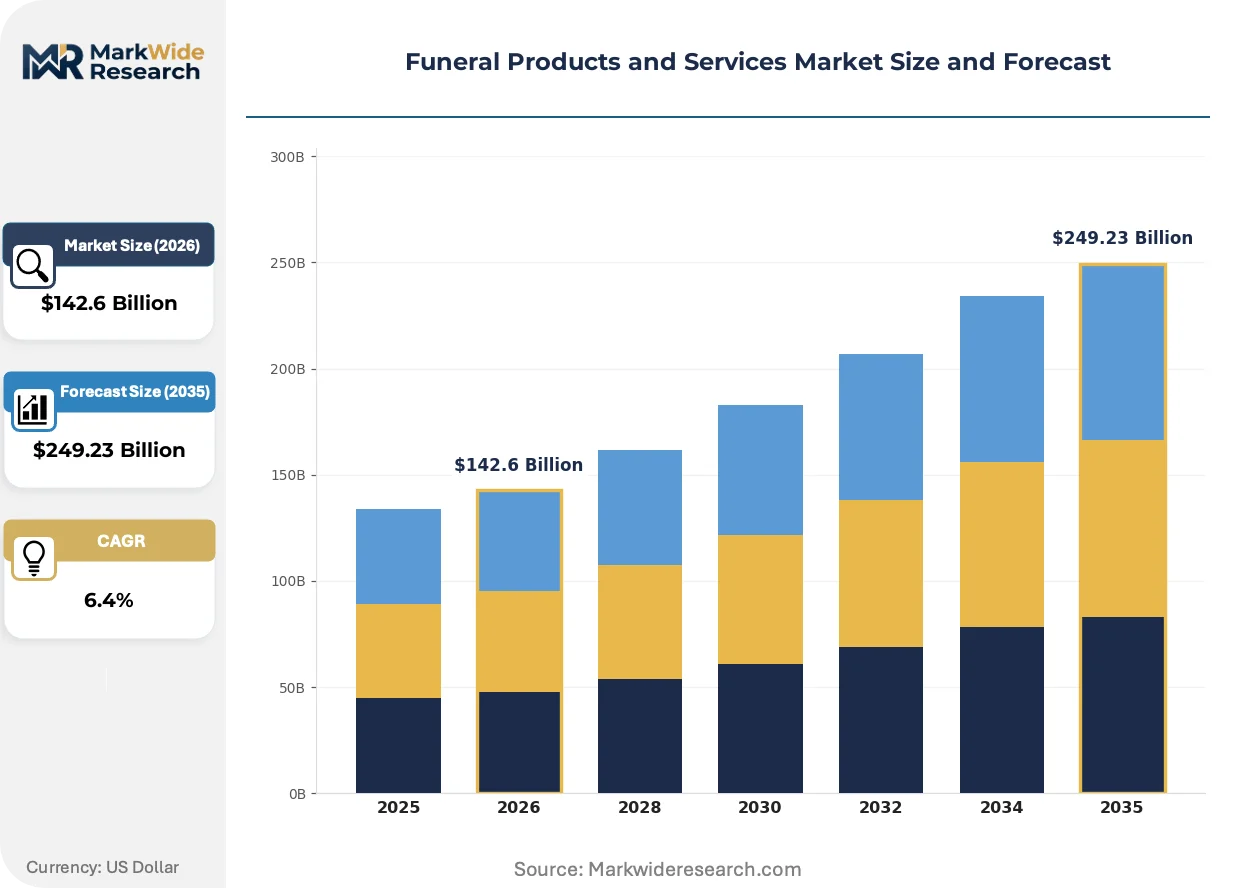
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $249.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
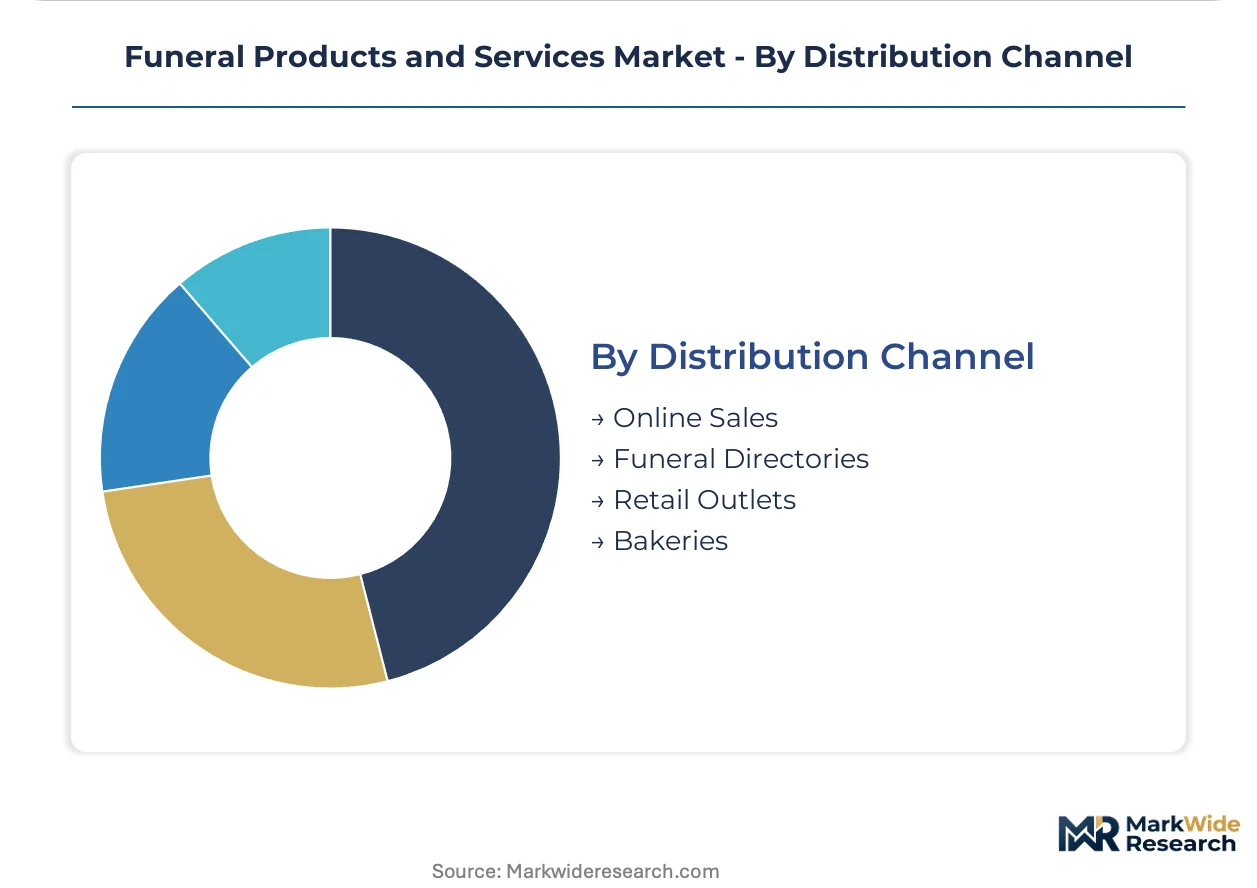
| Segmentation | Product Type: Caskets, Urns, Memorial Items, Burial Vaults Service Type: Funeral Planning, Cremation Services, Grief Counseling, Memorial Services Customer Type: Individuals, Families, Funeral Homes, Religious Organizations Distribution Channel: Online Sales, Funeral Directories, Retail Outlets, Bakeries |
| Companies Covered | Service Corporation International, Matthews International Corporation, Dignity Plc, Carriage Services, InvoCare Ltd., StoneMor Partners, Fu Shou Yuan International Group, Nirvana Asia Ltd., Park Lawn Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Funeral Products and Services Market Evolving Landscape
Memorialization technology is digitizing grief rituals while regulatory pressure accelerates environmental compliance investments. Service delivery models fragment as direct-to-consumer channels bypass traditional funeral home intermediaries.
Biodegradable casket fabrication is converging with mycelium composite engineering and 3D-printed cellulose structures. Green burial councils in Germany and the United Kingdom certify mushroom-based vessels that decompose within 45 days. This convergence compresses conventional hardwood casket demand in environmentally conscious urban markets.
The EU Green Deal's circular economy action plan mandates extended producer responsibility for funeral product packaging and chemical inputs. French and Italian regulators now require biodegradability testing for burial containers sold in protected watershed zones. Casket manufacturers serving Western Europe respond by reformulating glues and sealants to eliminate formaldehyde and synthetic polymers.
Buyer behavior shifts toward unbundled service procurement as online price comparison platforms expose funeral home markup dispersion. Direct cremation brokers in Texas, Arizona, and Nevada disintermediate traditional funeral directors by coordinating transport, paperwork, and disposition through centralized call centers. This channel compression concentrates volume at low-cost operators while squeezing full-service incumbents in price-transparent metropolitan corridors.
Funeral Products and Services Market Segmentation
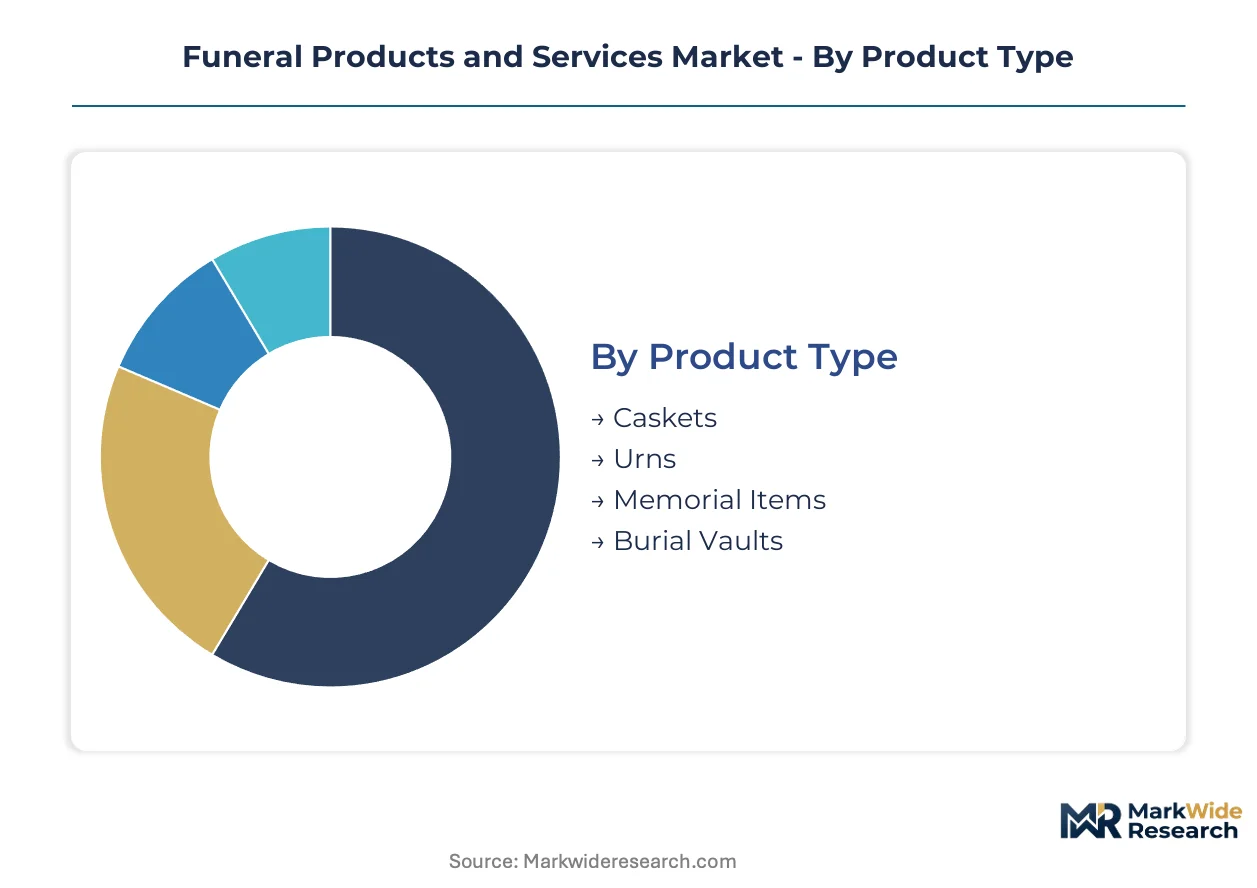
Segmentation in funeral products and services reveals how regulatory burdens, material specifications, and channel economics fragment purchasing behavior. Certification requirements for burial containers vary sharply across green burial standards versus conventional interment, while service delivery splits between licensed funeral directors and direct-to-consumer platforms.
Product Type:
Certification burdens cluster around material biodegradability and groundwater protection standards, with REACH compliance and Green Burial Council seals determining market access in premium European and North American jurisdictions.
- Caskets:Fabricated from 18-gauge steel, solid hardwoods, or woven natural fibers with sealed interiors and gasket mechanisms. Demand concentrates in rural U.S. markets and religious communities where traditional interment persists, constrained by steel price volatility and embalming chemical discharge regulations in California, New York, and Florida.
- Urns:Range from cast bronze and carved granite to biodegradable cellulose and salt-based vessels designed for water or land scattering. Volume growth accelerates in Shanghai, Los Angeles, and Mumbai where municipal cemetery exhaustion drives cremation adoption and columbarium niche demand.
- Memorial Items:Personalized keepsake jewelry, digital tribute platforms, and processed-remain artifacts command expanding margin pools.
- Burial Vaults:Concrete, metal, or polymer liners required by cemetery operators to prevent ground collapse.
Leading the category by volume: Caskets. Growing fastest: Urns.
Service Type:
Cost tiers separate full-service ceremonial coordination from stripped-down disposition, with price transparency mandates compressing bundled package profitability.
- Cremation Services:Flame-based retort operations and alkaline hydrolysis water-based disposition now lead volume expansion. Regulatory approval spreads across California, Colorado, and Florida for lower-emission alternatives, displacing conventional interment in capacity-constrained metropolitan corridors.
- Memorial Services:Ceremonial coordination including viewing facilities, floral arrangements, and transportation logistics. Demand fragments as direct cremation brokers in Texas, Arizona, and Nevada strip ancillary revenue through centralized call-center models.
- Funeral Planning:Pre-need contract structuring and advance payment administration.
- Grief Counseling:Licensed therapeutic support and support group facilitation.
Highest margin concentration: Memorial Services. Steepest expansion trajectory: Cremation Services.
Customer Type:
Procurement authority determines whether purchasing follows emotional preference or institutional procurement discipline.
- Families:Multi-generational decision units exercising itemized price comparison under FTC Funeral Rule mandates. Comparison shopping platforms expose markup dispersion, concentrating volume at transparent operators in price-sensitive metropolitan markets.
- Funeral Homes:Licensed operators sourcing caskets, urns, and vaults through manufacturer-direct contracts or wholesale distributors. Vertical integration by cemetery-funeral home networks sustains pricing power across key U.S. metropolitan corridors.
- Individuals:Single-purchaser pre-need planning.
- Religious Organizations:Institutional procurement for congregational burial grounds and ceremonial standards.
Dominant procurement volume: Funeral Homes. Fastest-growing contract pool: Families.
Distribution Channel:
Channel fragmentation accelerates as digital platforms disintermediate traditional funeral home intermediaries.
- Online Sales:Direct-to-consumer platforms for urns, memorial jewelry, and digital legacy subscriptions. Cloud-based tribute services and AI-generated memorial content create recurring revenue through annual subscription renewals.
- Funeral Directories:Aggregator platforms enabling price comparison and service matching. These directories compress regional pricing dispersion and steer families toward low-cost operators in Texas, Arizona, and Nevada.
- Retail Outlets:Big-box and specialty store distribution for pre-need casket and urn purchases.
- Bakeries:Local providers of ceremonial food service and reception coordination.
Largest transaction volume: Funeral Directories. Gaining share fastest: Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardwood forests in the Appalachian Mountains supply raw material for casket manufacturing across the eastern United States, while steel mills in northern China feed regional metal casket production. Cemetery land scarcity and cremation adoption rates create divergent demand patterns across major economies.
United States
Urban cemetery exhaustion in Los Angeles and New York accelerates cremation volume growth while compressing traditional casket demand. The FTC Funeral Rule mandates itemized price disclosures that strip bundled service profitability and empower consumer comparison shopping. Service Corporation International leverages its vertically integrated cemetery-funeral home network to sustain pricing power across key metropolitan corridors.
China
Aging demographics in Shanghai and Beijing drive demand for memorial parks and digital tribute platforms serving urban families. Fu Shou Yuan International Group expands cemetery operations while domestic operators develop columbarium niches for cremation growth. Municipal burial ground scarcity tightens supply in coastal megacities, redirecting volume toward flame-based retort services.
Germany
REACH compliance requirements incentivize hemp, mycelium, and untreated wood casket production for green burial segments. The EU Green Deal's circular economy mandates extended producer responsibility for funeral product packaging and chemical inputs. Green Burial Council certifications enable price premiums for unembalmed interment in protected natural areas across Bavaria and Baden-Württemberg.
Japan
Pre-need funeral plan penetration expands among aging demographics in Tokyo and Osaka metropolitan areas. METI guidelines shape service standardization while municipal cemetery capacity constraints accelerate cremation adoption. Memorial technology firms develop cloud-based tribute services for recurring subscription revenue from annual renewals.
United Kingdom
Dignity Plc competes through standardized service packages and advance payment contract administration. Cremation services now dominate volume in Greater London while regional funeral homes face price transparency pressure from online comparison platforms. The Competition and Markets Authority scrutinizes sector pricing practices and pre-need contract terms.
Funeral Products and Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable materials and digital memorial platforms. The vendor base concentrates around vertically integrated cemetery-funeral home networks, specialized casket manufacturers, and direct-to-consumer cremation brokers. Three archetypes dominate: scale-driven consolidators with property assets, premium memorialization specialists, and technology-enabled disintermediaries. Competitive moves center on M&A for cemetery footprint expansion and strategic partnerships for alkaline hydrolysis permitting.
Among North American consolidators, Service Corporation International and Matthews International Corporation represent scale-driven archetypes with integrated asset control. Dignity Plc anchors the British market's standardized service tier. Fu Shou Yuan International Group exemplifies the Asia-Pacific cemetery developer model with memorial park expansion and digital platform integration.
| Leading Market Players |
|---|
| Service Corporation International |
| Matthews International Corporation |
| Dignity Plc |
| Carriage Services |
| InvoCare Ltd. |
| StoneMor Partners |
| Fu Shou Yuan International Group |
| Nirvana Asia Ltd. |
| Park Lawn Corporation |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up funeral home networks anchor supply-side concentration across the United States, compressing procurement leverage for independent operators while enforcing pricing discipline through standardized service menus. Their control over cemetery-funeral home pairings in metropolitan corridors feeds back into casket and urn sourcing decisions, favoring long-term manufacturer contracts over spot-market flexibility.
Pricing Analysis
Warranty and service-bundling differentiation separates full-service funeral packages from stripped-down direct cremation offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and geographic delivery cost, with Green Burial Council seals commanding measurable premiums in California and Germany. Pricing pressure stems from FTC-mandated itemized disclosures that expose markup dispersion, forcing transparency. Families represent the most price-sensitive segment, while pre-need contract purchasers show lower sensitivity due to advance payment lock-in.
Supply Chain Analysis
Single-source vulnerability sits with Chinese steel mills feeding 18-gauge casket production and Appalachian hardwood suppliers serving traditional burial demand. Manufacturing draws from steel sheet mills in northern China, untreated timber operations in the eastern United States, and mycelium composite fabricators in Western Europe. Tariff exposure on imported metal inputs creates margin volatility for domestic producers. Distribution runs through vertically integrated cemetery-funeral home networks, wholesale distributors, and emerging direct-to-consumer online channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where FTC price transparency mandates and cremation volume shifts force subscale operators toward exit or acquisition.
For Market Incumbents: Acquire cemetery real estate in capacity-constrained metropolitan corridors to defend against direct cremation brokers stripping ancillary revenue. Cement pricing power through backward integration into biodegradable casket manufacturing, countering REACH compliance costs that squeeze independent competitors. Lock in pre-need contract volume through digital legacy platform subscriptions that generate recurring renewal revenue. For New Entrants and Emerging Players: The premium-to-economy price gap in memorialization software offers entry space for cloud-based tribute platforms with AI-generated content capabilities. Target Germany and Japan where aging demographics expand advance payment contract pools with limited digital incumbent presence. Pursue green burial certification as the go-to-market angle, leveraging Conservation Burial Alliance standards to bypass entrenched funeral home relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent funeral home operators in rural U.S. territories facing embalmer workforce attrition and crematory retort upgrade burdens. Long-term viability hinges on property-backed revenue streams and regulatory moats around alkaline hydrolysis permitting. Watch California and Florida regulatory approval trajectories for water-based disposition technology as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cemetery Real Estate Acquisition | Locks in irreplaceable burial capacity in Shanghai, Los Angeles, and Mumbai where municipal exhaustion accelerates. |
| Biodegradable Material Certification | Green Burial Council seals unlock premium pricing in REACH-regulated European markets. |
| Digital Legacy Platform Launch | Cloud-based tribute services generate recurring subscription revenue from annual memorial content renewals. |
| Alkaline Hydrolysis Permitting | California and Florida regulatory approvals create first-mover advantage in lower-emission disposition. |
| Pre-Need Contract Expansion | Advance payment administration in Germany and Japan locks in future service volume against cremation substitution. |
Research Methodology
Independent corroboration across funeral director interviews, cemetery operator consultations, and memorial technology developer discussions underwrites the qualitative findings. Primary fieldwork captured perspectives from licensed embalmers, pre-need sales consultants, green burial certification officers, and municipal cemetery administrators. Secondary validation drew from FTC enforcement records, state cemetery board filings, EU REACH compliance databases, and Green Burial Council certification registries. Bottom-up service volume estimates triangulated against top-down demographic mortality projections.
Rate-of-change decomposition separated cremation adoption velocity, casket demand erosion, and memorialization software penetration across the analysis window. Segmentation modeling incorporated product type, service tier, customer procurement authority, and distribution channel economics. CAGRs derived from cohort-level trend extrapolation adjusted for regulatory inflection points including alkaline hydrolysis permitting expansion and embalming chemical discharge restrictions. Forecast inputs included municipal cemetery capacity utilization rates and pre-need contract penetration by age demographic.
Underlying measurement precision varies by segment; cremation services and digital memorial platforms carry tighter precision than traditional casket manufacturing where steel price volatility introduces uncertainty. Forecasts reflect assumptions around regulatory approval timelines, demographic mortality patterns, and green burial certification adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Healthcare Staffing Market
Healthcare Services
United States Pharmaceutical Logistic Services Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
US Registered Nurses Market
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Global Corporate Wellness Solutions Market
Healthcare Services
Global Offsite Medical Case Management Market
Healthcare Services
Australia Senior Living Market
Healthcare Services
Global Value Based Healthcare Services Market
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
Global Urgent Care Center Market
Healthcare Services
US Long Term Care Market
Healthcare Services
Medical Devices and Equipment Logistics Market
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
Global Hospice Care Market