
 Global Argon Market | 2026-2036
Global Argon Market Size, Share, and Industry Trends Forecast 2026-2036
Global Argon Market Foresight
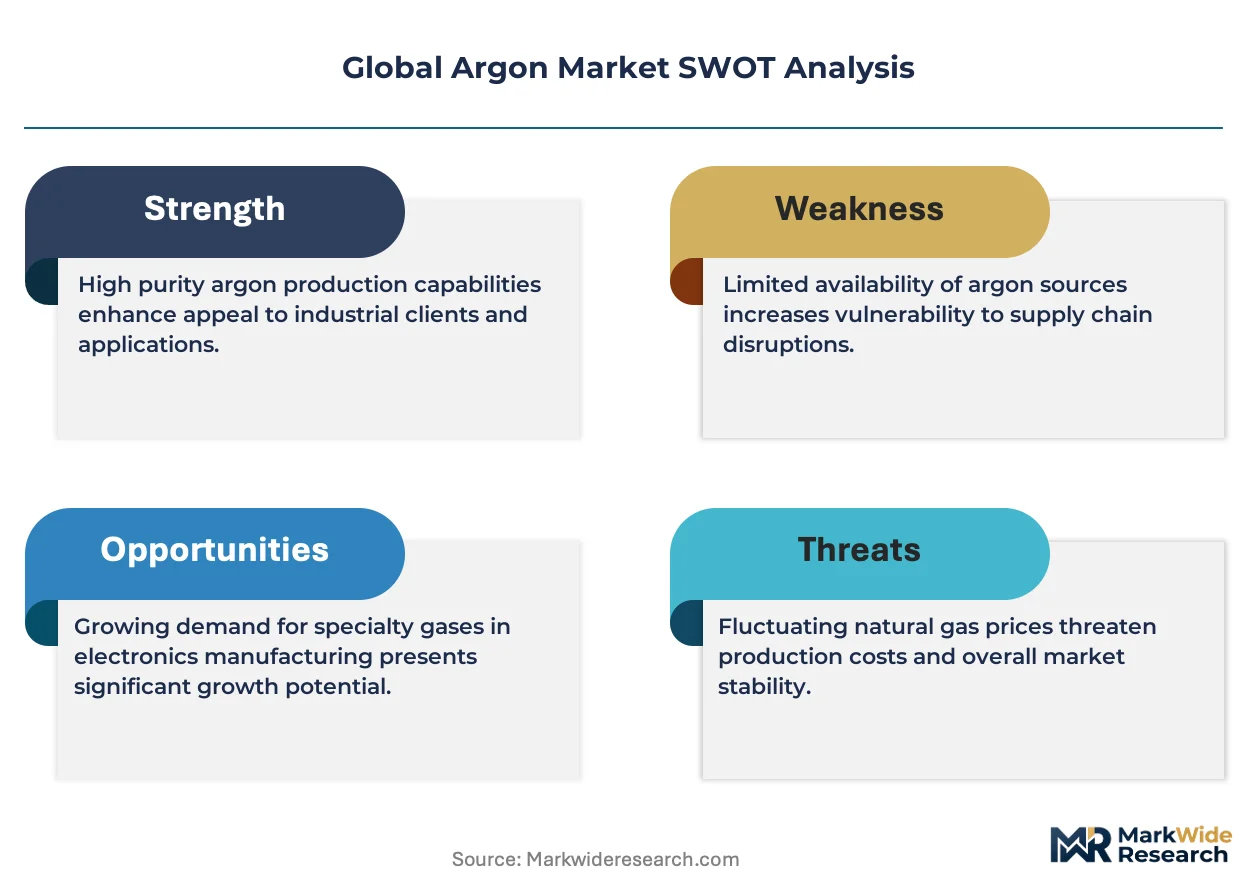
Long-term cylinder leasing and on-site generation contracts is rebalancing how buyers procure argon, shifting capital burdens from end users to suppliers. Linde plc leverages its cryogenic infrastructure to anchor bulk supply relationships with semiconductor fabs across East Asia. Air Liquide S.A. sustains competitive positioning through backward integration into air separation unit networks. Air Products and Chemicals Inc. specializes in high-purity argon purification for electronics-grade applications.
Argon is a monatomic noble gas comprising approximately 0.93% of Earth's atmosphere, extracted through cryogenic fractional distillation of liquid air at temperatures below -185.9°C, and serves primarily as an inert shielding medium in high-temperature industrial processes. Atmospheric argon dominates volume flows into welding and fabrication, where established infrastructure and lower purification thresholds preserve margin efficiency. High purity argon commands premium positioning within electronics manufacturing, where semiconductor lithography and crystal growth processes require impurity levels below one part per billion. Liquid argon occupies a structural growth corridor in metal production, particularly for stainless steel decarburization and ladle metallurgy.
The EPA enforces emissions controls on air separation facilities under the Clean Air Act, while the EU F-Gas Regulation restricts fluorinated alternatives that might otherwise displace argon in certain thermal applications. China's MEE implements ambient air quality standards that indirectly govern cryogenic plant siting and energy sourcing decisions. Buyers must monitor how carbon-border adjustment mechanisms and national hydrogen strategies reshape the electricity economics underlying air separation unit operations.
Market Dynamics
Semiconductor lithography processes are compressing impurity thresholds below one part per billion, forcing air separation suppliers to reengineer purification trains and recalibrate cylinder conditioning protocols across their installed base.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated thermal alternatives preserve argon's position in high-temperature shielding applications across European metal fabrication.
- Wafer fabrication scaling:Foundry expansions in Taiwan, South Korea, and China are pulling electronics-grade argon volumes into concentrated demand clusters.
- Cryogenic infrastructure deployment:On-site generation systems at stainless steel mills reduce logistics costs and lock in long-term offtake agreements.
Market Restraints
- Electricity cost volatility:Cryogenic distillation consumes substantial grid power, exposing margin structures to carbon-border adjustment mechanisms and national hydrogen strategies.
- Supply concentration risk:Bulk argon production clusters near industrial corridors in China, Germany, and the United States, creating geographic vulnerability to localized disruptions.
- Helium substitution pressure:Superconducting magnet applications in medical imaging and scientific research divert investment toward helium recovery systems.
Strategic Opportunities
- Indian electronics manufacturing:Production-linked incentive schemes for semiconductor fabs create virgin demand for high-purity argon in greenfield facilities.
- Solar silicon crystal growth:Photovoltaic ingot pulling processes require controlled argon atmospheres, opening volume opportunities outside traditional electronics.
- Additive manufacturing shielding:Laser powder bed fusion systems for titanium and aluminum alloys specify argon inerting for oxidation-sensitive builds.
Industry Challenges
- Cryogenic technician scarcity:Qualified personnel for air separation unit maintenance and cylinder transfill operations are concentrated among retiring cohorts in established markets.
- Certification timeline compression:Semiconductor customers demand simultaneous ISO 14644 cleanroom compliance and SEMI gas purity certifications, extending qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Argon Market |
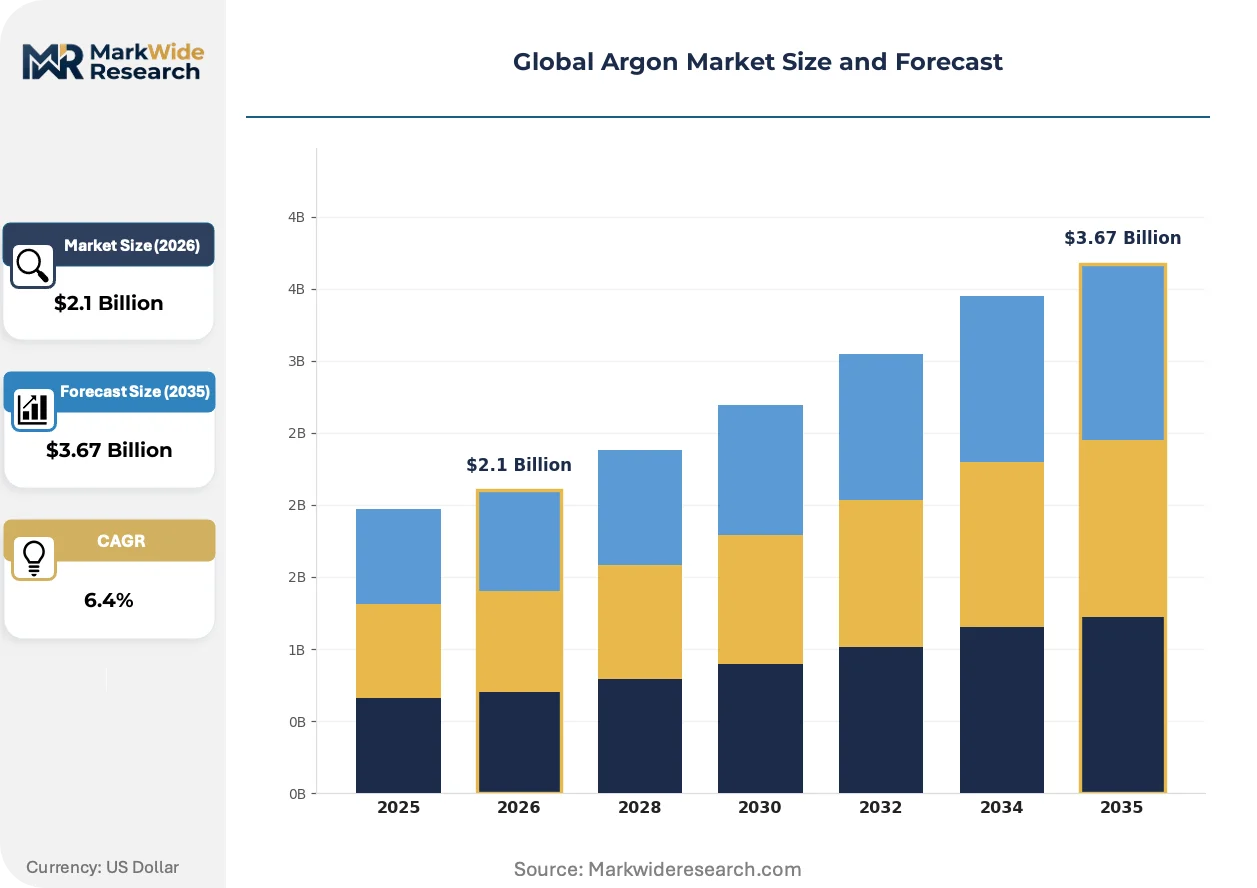
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atmospheric Argon, Liquid Argon, High Purity Argon, Argon Gas Cylinders, Industrial Argon Application: Welding & Fabrication, Metal Production, Electronics Manufacturing, Food Packaging, Chemical Processing End User: Fabrication Shops, Semiconductor Manufacturers, Food & Beverage Companies, Research Laboratories, Chemical Factories Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail Stores, Industrial Suppliers |
| Companies Covered | Linde plc, Air Liquide S.A., Air Products and Chemicals Inc., BASF SE, Messer Group GmbH, Taiyo Nippon Sanso Corporation, Iwatani Corporation, Matheson Tri-Gas Inc., Air Water Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Argon Market Shifts & Advancements
Argon supply economics are pivoting from commodity distribution toward integrated service architectures that bundle purification, storage, and consumption monitoring into continuous contracts.
Membrane-assisted cryogenic distillation is expanding into mid-scale air separation facilities. Steel mini-mills in Turkey and Vietnam are adopting skid-mounted units to bypass bulk liquid delivery infrastructure. This technology is expanding into regions where pipeline networks remain underdeveloped, compressing the capital threshold for captive argon supply.
China's MEE ambient air quality standards are tightening siting requirements for cryogenic plants near urban corridors. Facility planners must relocate energy-intensive separation units to industrial zones with dedicated renewable power purchase agreements. Electronics-grade producers in Jiangsu and Guangdong provinces are responding by co-lating generation assets with solar and offshore wind installations.
Long-term cylinder leasing agreements are displacing spot purchasing in welding and fabrication segments. Distributors in Mexico and Poland are bundling gas supply with equipment maintenance, converting transactional buyers into contracted accounts. This pattern is most visible among automotive tier suppliers seeking to outsource inventory management and cylinder tracking logistics.
Global Argon Market Segmentation
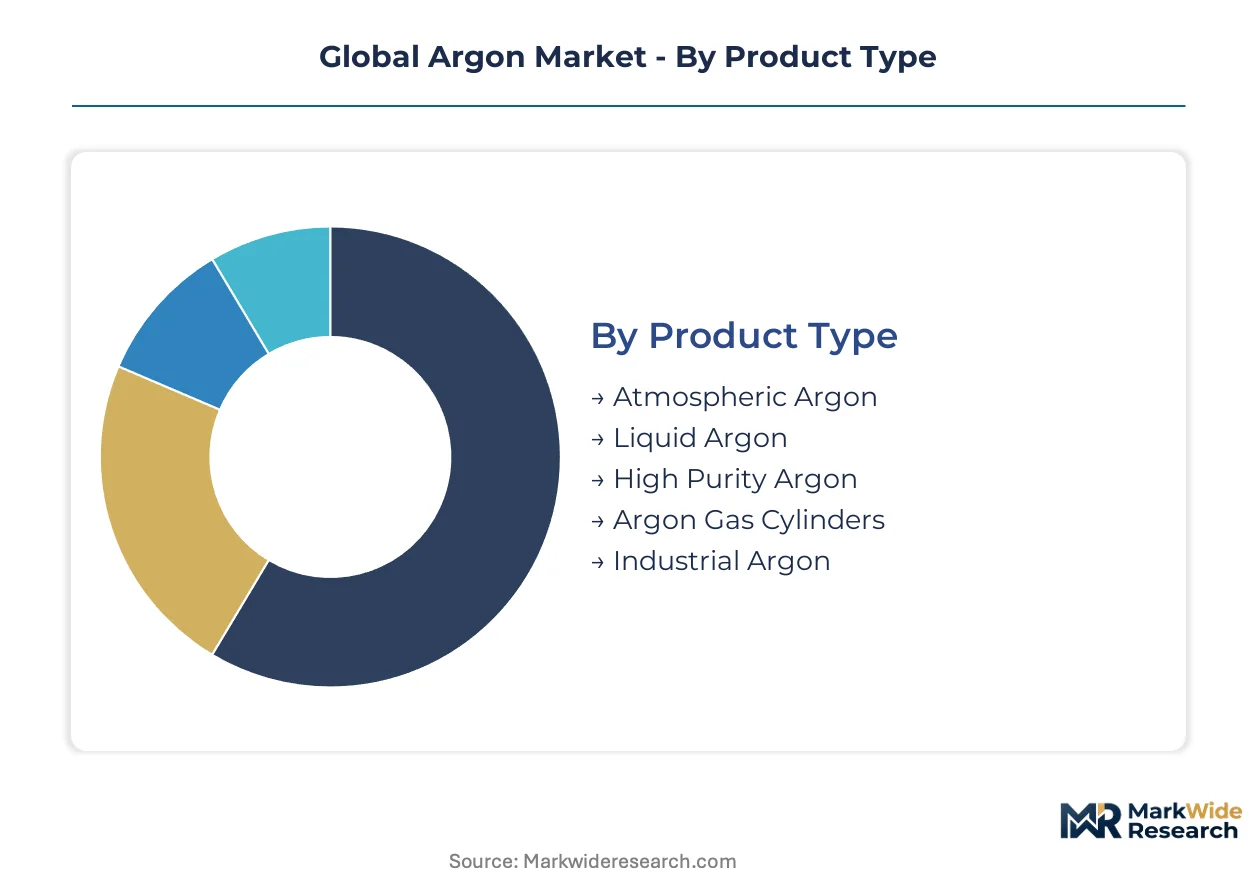
Argon supply architectures fragment across purity grades, physical states, and delivery mechanisms that carry vastly different margin profiles. Semiconductor lithography demands impurity thresholds below one part per billion, while welding applications tolerate atmospheric-grade specifications. Understanding these segment boundaries reveals where capital deployment concentrates and where substitution threats emerge.
Product Type:
Volume flows through commodity atmospheric grades, yet premium capture concentrates in specialized purification tiers where electronics manufacturers lock in long-term offtake.
- Atmospheric Argon:Extracted through standard cryogenic air separation without additional refinement, carrying 0.93% natural atmospheric concentration. Demand clusters in Chinese and German metal fabrication corridors where pipeline infrastructure minimizes logistics costs and spot pricing dominates procurement.
- High Purity Argon:Subjected to catalytic oxygen removal, molecular sieve dehydration, and cryogenic distillation to achieve sub-ppb impurity levels. Taiwan Semiconductor Manufacturing Company and Samsung Foundry specifications are compressing certification timelines and forcing cylinder conditioning protocol upgrades across East Asian supply bases.
- Liquid Argon:Dense-phase storage format favored by stainless steel mini-mills in Turkey and Vietnam for ladle metallurgy and decarburization.
- Argon Gas Cylinders:Packaged delivery mode for remote fabrication shops lacking bulk liquid infrastructure.
- Industrial Argon:Mid-tier specification serving general manufacturing with balanced cost-purity positioning.
Today's leader: Atmospheric Argon. Tomorrow's challenger: High Purity Argon.
Application:
End-use concentration tracks industrial development corridors, with electronics manufacturing pulling premium volumes into East Asian demand clusters.
- Electronics Manufacturing:Wafer fabrication, crystal growth, and lithography processes require controlled inert atmospheres with extreme purity guarantees. Foundry expansions in Hsinchu, Pyeongtaek, and Shanghai are concentrating electronics-grade consumption within 300-kilometer supply radii.
- Welding & Fabrication:Gas metal arc and tungsten inert gas processes consume atmospheric-grade argon as shielding medium. Mexican automotive tier suppliers are shifting from spot purchasing to bundled cylinder leasing agreements that outsource inventory management.
- Metal Production:Stainless steel decarburization and ladle metallurgy in electric arc furnaces.
- Food Packaging:Modified atmosphere packaging for shelf-life extension in processed proteins.
- Chemical Processing:Inert blanketing for oxidation-sensitive synthesis reactions.
Electronics Manufacturing commands the steepest expansion trajectory. Welding & Fabrication retains the largest installed volume base.
End User:
Customer sophistication tiers separate price-tolerant semiconductor fabs from cost-sensitive fabrication shops with diverging contract structures.
- Semiconductor Manufacturers:Foundry operators specifying SEMI gas purity certifications and ISO 14644 cleanroom compliance simultaneously. Qualification cycles extend 18-24 months, locking suppliers into exclusive multiyear agreements with penalty clauses for supply interruption.
- Fabrication Shops:Small and mid-sized welding contractors prioritizing cylinder availability over purity specifications. Polish and Mexican distributors are converting these transactional accounts to contracted service bundles covering gas supply, equipment maintenance, and cylinder tracking.
- Food & Beverage Companies:Modified atmosphere packaging operators with seasonal demand fluctuations.
- Research Laboratories:Scientific institutions requiring documented traceability for experimental reproducibility.
- Chemical Factories:Process industries using argon for reactor inerting and catalyst protection.
Semiconductor Manufacturers drive margin expansion. Fabrication Shops anchor volume throughput.
Distribution Channel:
Channel selection reflects customer scale, geographic density, and the economics of cryogenic logistics versus packaged gas handling.
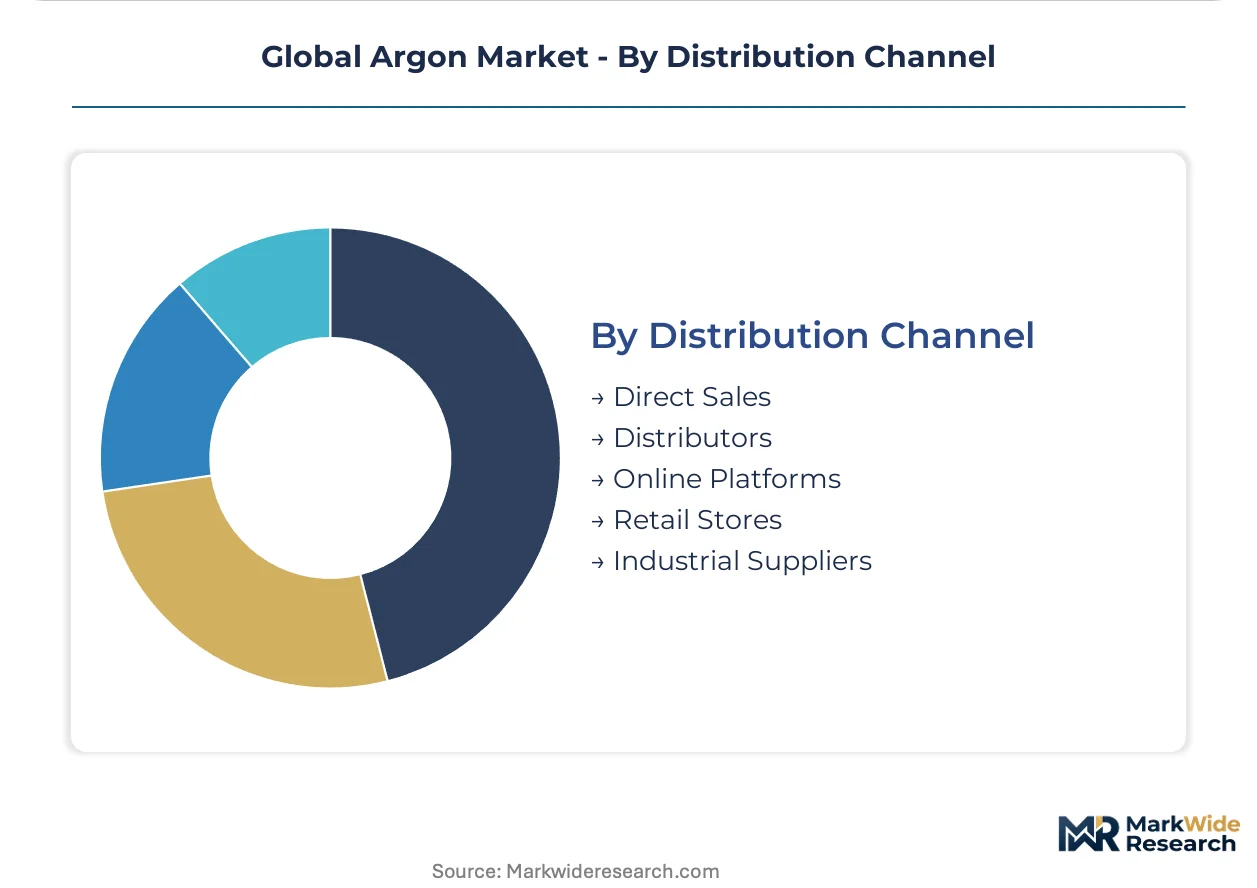
- Direct Sales:Bulk liquid and on-site generation contracts negotiated directly between air separation operators and large consumers. Linde plc anchors these relationships through cryogenic infrastructure investments at semiconductor fabs across South Korea and Taiwan.
- Distributors:Regional gas specialists bundling cylinder supply with equipment service for mid-market accounts. Long-term leasing agreements are displacing spot purchasing in Mexican automotive supply chains.
- Industrial Suppliers:Broad-line distributors serving fragmented maintenance-repair-operations demand.
- Online Platforms:Digital procurement channels for standardized cylinder specifications.
- Retail Stores:Consumer-facing outlets for hobbyist and light commercial welding applications.
Direct Sales commands the premium contract tier. Distributors are gaining share fastest through service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting cryogenic air separation capacity toward jurisdictions with lower electricity costs and less stringent siting requirements. The EU F-Gas Regulation preserves argon's competitive position against fluorinated alternatives in European metal fabrication, while China's MEE ambient air quality standards are pushing new plant construction toward renewable-powered industrial zones.
China
Semiconductor foundry expansions in Jiangsu and Guangdong provinces are pulling electronics-grade argon into concentrated demand clusters. The MEE implements tightening ambient air quality standards that indirectly govern cryogenic plant siting decisions. Facility planners in the Yangtze River Delta are co-locating generation assets with offshore wind installations to secure renewable power purchase agreements.
South Korea
Wafer fabrication scaling in Pyeongtaek and Yongin is compressing impurity thresholds below one part per billion for argon suppliers. The MFDS maintains pharmaceutical-grade gas standards that cross-apply to semiconductor process materials. Samsung Foundry and SK Hynix operations in the Seoul Capital Area anchor bulk liquid offtake agreements with on-site generation systems.
United States
Stainless steel mini-mills in Texas and the Southeast are adopting skid-mounted membrane-assisted distillation units. The EPA enforces emissions controls on air separation facilities under the Clean Air Act. Electric arc furnace operators in the Gulf Coast corridor are bypassing traditional bulk liquid delivery infrastructure through captive argon supply.
Germany
Automotive tier suppliers in Bavaria and Baden-Württemberg are converting from spot purchasing to bundled cylinder leasing agreements. The EU F-Gas Regulation restricts fluorinated thermal alternatives that might otherwise displace argon in welding applications. Industrial gas distributors in the Stuttgart manufacturing cluster are outsourcing inventory management and cylinder tracking logistics for mid-market fabrication accounts.
India
Production-linked incentive schemes for semiconductor fabs are creating virgin demand for high-purity argon in greenfield facilities. The BIS certifies industrial gas purity grades that semiconductor customers must meet for import substitution programs. Tamil Nadu and Gujarat sub-regions are concentrating electronics manufacturing investments with dedicated cryogenic infrastructure requirements.
Global Argon Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated air separation operators commanding bulk supply relationships while regional distributors capture packaged gas volumes. Three strategic archetypes dominate: cryogenic infrastructure owners with backward integration into air separation networks, purification specialists serving electronics-grade specifications, and service bundlers converting transactional welding accounts to long-term contracts. Competitive moves center on on-site generation deployments at semiconductor fabs and membrane-assisted distillation expansions for steel mini-mills.
Within the infrastructure-owner archetype, Linde plc and Air Liquide S.A. exemplify scale-driven positioning through cryogenic asset ownership across East Asian electronics corridors. Air Products and Chemicals Inc. occupies a specialization tier focused on high-purity purification protocols for sub-ppb semiconductor specifications. Among Japan-based industrial gas operators, Taiyo Nippon Sanso Corporation and Iwatani Corporation represent regional champions with concentrated exposure to domestic electronics manufacturing clusters. These named entities serve as anchors for understanding how geographic footprint and purity-grade focus differentiate competitive positioning without asserting specific market shares or strategic actions.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide S.A. |
| Air Products and Chemicals Inc. |
| BASF SE |
| Messer Group GmbH |
| Taiyo Nippon Sanso Corporation |
| Iwatani Corporation |
| Matheson Tri-Gas Inc. |
| Air Water Inc. |
| Others |
Supply & Pricing Matrix
Semiconductor foundry specifications compressing impurity thresholds below one part per billion force air separation suppliers to reengineer purification trains and recalibrate cylinder conditioning protocols, elevating capital intensity and compressing margin structures for unprepared operators.
Pricing Analysis
Distributor margins in packaged gas channels absorb logistics and cylinder tracking costs that bulk liquid contracts bypass entirely. Three-tier pricing structure across electronics-grade, industrial-grade, and atmospheric-grade specifications segments buyer willingness-to-pay by certification burden and volume commitment. Cost compression in atmospheric-grade spot markets is intensifying because Chinese pipeline infrastructure expansion reduces logistics premiums for metal fabrication clusters. Fabrication shops in Poland and Mexico exhibit highest price sensitivity, while semiconductor manufacturers in Taiwan and South Korea accept premium positioning for sub-ppb purity guarantees.
Supply Chain Analysis
Dual-sourcing requirements from Samsung Foundry and TSMC force qualified suppliers to maintain redundant purification capacity across East Asian supply bases. Bulk production clusters in China, Germany, and the United States anchor global volume, drawing from electricity markets and cryogenic equipment manufacturing in Japan and South Korea. Single-source vulnerability concentrates in electronics-grade argon where 18-24 month qualification cycles lock buyers into exclusive agreements. Distribution runs through direct sales for bulk liquid and on-site generation, with regional distributors capturing packaged cylinder volumes in fragmented fabrication segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation functions as a regulatory compounder, restricting fluorinated thermal alternatives and preserving argon's structural position in European metal fabrication through mandated substitution limitations.
For Market Incumbents: Cement cryogenic infrastructure ownership in East Asian electronics corridors through on-site generation deployments at expanding foundry complexes. Prioritize backward integration into renewable power purchase agreements to insulate margin structures from carbon-border adjustment mechanisms. Defend against membrane-assisted distillation entrants by locking stainless steel mini-mills into long-term offtake agreements with equipment leasing bundles.
For New Entrants and Emerging Players: Begin with solar silicon crystal growth applications in India and Vietnam, where photovoltaic ingot pulling processes require controlled argon atmospheres but purity thresholds remain less stringent than semiconductor lithography. Target steel mini-mills in Turkey adopting skid-mounted membrane-assisted units as the most penetrable segment. Pursue additive manufacturing shielding partnerships with laser powder bed fusion system integrators as the primary go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with purification specialists possessing SEMI gas purity certifications and ISO 14644 cleanroom compliance capabilities already embedded in their operational protocols. Long-term viability hinges on exposure to electronics manufacturing demand clusters with captive renewable energy sourcing. Monitor qualification timeline compression at leading foundries as the signal indicating inflection in supplier switching costs.
| Strategic Initiative | Industry Significance |
|---|---|
| On-Site Generation Deployment | Captures long-term offtake agreements with Samsung Foundry and SK Hynix in South Korea. |
| Membrane-Assisted Distillation Expansion | Reduces capital thresholds for Turkish and Vietnamese steel mini-mills bypassing bulk liquid infrastructure. |
| Renewable Power Purchase Agreements | Aligns Jiangsu and Guangdong cryogenic plants with China's MEE ambient air quality standards. |
| SEMI Gas Purity Certification Investment | Enables qualification for sub-ppb semiconductor lithography specifications at TSMC and Intel. |
| Cylinder Leasing Service Bundling | Converts spot-purchasing fabrication shops in Mexico and Poland to contracted recurring revenue accounts. |
Research Methodology
Multiple input streams — primary interviews with air separation plant managers, semiconductor procurement leads, and industrial gas distribution channel partners; secondary validation through customs/trade data, SEC filings of listed industrial gas operators, and MEE ambient air quality enforcement records — were reconciled using bottom-up volume triangulation against top-down market sizing across the analysis window.
Data-stream reconciliation anchored the forecast framework across purity grade tiers, end-use applications spanning electronics manufacturing to metal fabrication, physical state formats, and regional production hub clusters. CAGRs were derived from segment-level volume build-ups applied to pricing trajectories throughout the forecast period. Key inputs included foundry expansion timelines in Taiwan and South Korea, renewable power purchase agreement penetration in Chinese industrial zones, and membrane-assisted distillation adoption rates in emerging steel markets.
Several conditions sit outside the modeled scope, including abrupt shifts in national hydrogen strategies affecting electricity economics, unanticipated relaxation of EU F-Gas Regulation enforcement, and breakthrough helium recovery technologies diverting superconducting magnet applications. Deviation in semiconductor capital expenditure cycles or carbon-border adjustment mechanism implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Krypton Gas Market
Industrial Gases
Industrial Gas Regulator Market
Industrial Gases
North America Industrial Gases Market
Industrial Gases
Neon Gas for Laser Market
Industrial Gases
3D Printing Gases Market
Industrial Gases
Europe Syngas Market
Industrial Gases
Semiconductor Gases Market
Industrial Gases
US Industrial Gas Regulator Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
High Purity Argon Market
Industrial Gases
Global Sulfur Dioxide Market
Industrial Gases
North America Syngas Market
Industrial Gases
Syngas Market
Industrial Gases
Acetylene Gas Market
Industrial Gases
Europe Industrial Gases Market
Industrial Gases
Oxygen Market