
 Global Hydraulic Thermoplastic Hose and Couplings Market | 2026-2036
Global Hydraulic Thermoplastic Hose and Couplings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydraulic Thermoplastic Hose and Couplings Market Foresight
Skilled hydraulic assembly technician availability is collapsing across mature manufacturing economies, forcing OEMs and distributors to pre-assemble hose-and-coupling kits before shipment. Parker Hannifin Corporation leverages its captive distribution network to sustain kitting revenue streams that bypass field-assembly bottlenecks. Gates Corporation anchors North American aftermarket demand through private-label partnerships with national fluid-power distributors. Eaton Corporation competes on R&D intensity in high-pressure thermoplastic constructions rated above 10,000 psi for mining and marine applications.
Hydraulic thermoplastic hose and couplings comprise extruded polymer tubes reinforced with braided synthetic fiber or steel wire, terminated by crimped or reusable metallic fittings designed to convey pressurized fluid in dynamic machinery environments. Polyurethane dominates material composition for applications demanding abrasion resistance and flexibility at sub-zero temperatures, while nylon formulations lead where chemical compatibility with synthetic hydraulic fluids is paramount. Thermoplastic hose segments are displacing conventional rubber constructions in material handling and agricultural machinery as fleet operators prioritize extended service intervals and reduced maintenance downtime. Assembly kits represent the fastest-growing product type as distributor consolidation drives preference for pre-configured, warranty-backed hose solutions over cut-and-couple counter service.
EPA emissions standards for off-road diesel equipment in the United States are extending hydraulic system replacement cycles, indirectly boosting demand for durable thermoplastic hose constructions that outlast regulatory-mandated engine rebuild intervals. ECHA REACH restrictions on phthalate plasticizers and heavy-metal stabilizers are reshaping PVC and polyurethane formulation strategies among European compounders and extruders. ISO 18752 and SAE J517 standards govern pressure-rating certifications that determine market access for coupling manufacturers exporting into German automotive-hydraulic supply chains. Stakeholders must monitor how China's GB standards evolution and NMPA-aligned pressure-equipment rules affect import qualification pathways for multinational hose suppliers serving domestic OEMs.
Market Dynamics
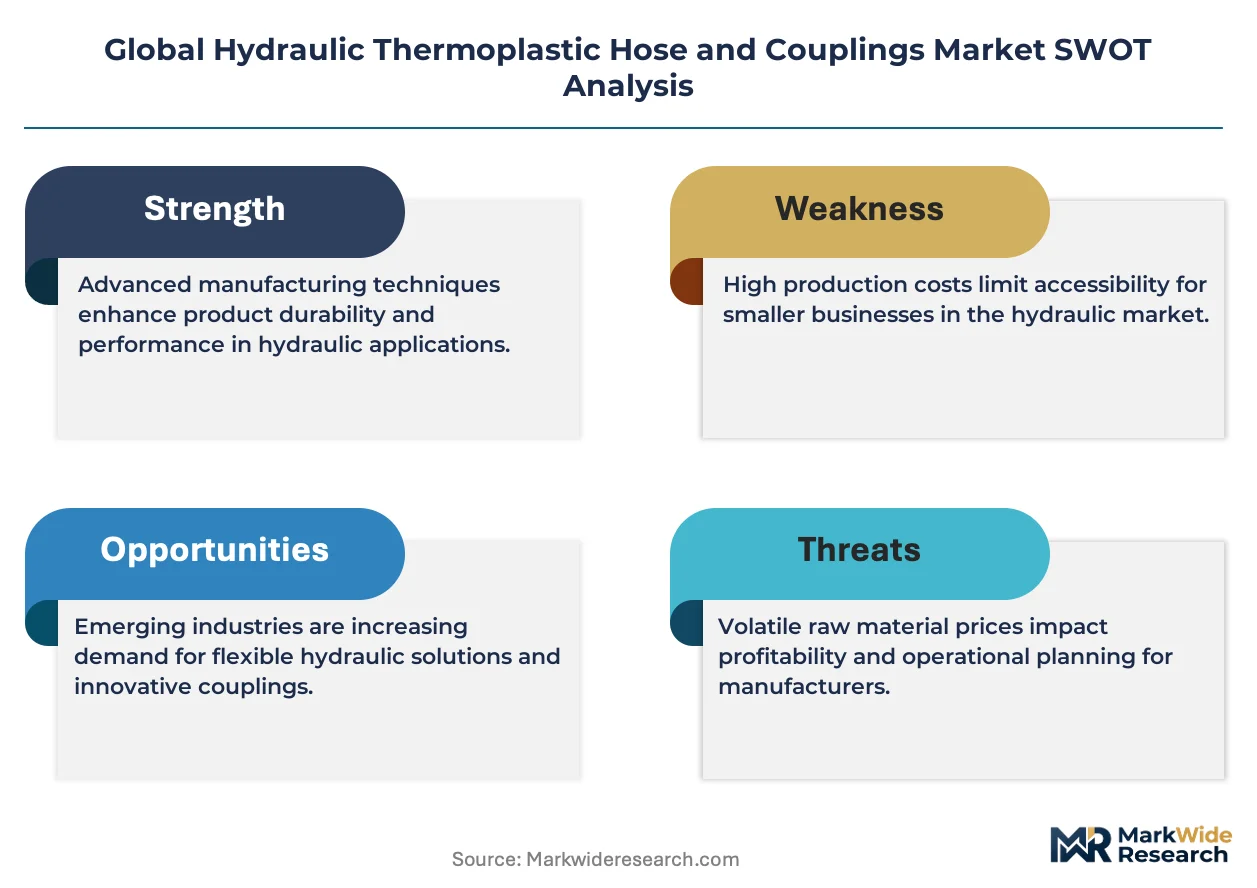
Construction equipment OEMs are systematically substituting rubber hydraulic hoses with thermoplastic constructions to achieve fleet weight targets and extend service intervals, compressing traditional supply relationships between rubber compounders and hydraulic distributors.
Growth Catalysts
- REACH and RoHS compliance mandates:European ECHA restrictions on phthalate plasticizers and heavy-metal stabilizers are accelerating formulation shifts toward polyurethane and nylon alternatives among compounders serving German automotive-hydraulic supply chains.
- Material handling fleet electrification:Battery-powered forklifts and AGVs generate thermal cycling demands that thermoplastic hoses withstand more reliably than rubber, driving aftermarket coupling replacement in warehouse automation.
- Sub-zero flexibility requirements:Arctic mining and offshore marine operators in Norway and Canada specify polyurethane constructions rated for temperatures below minus forty degrees Celsius, expanding addressable applications for synthetic fiber-reinforced designs.
Market Restraints
- Specialized crimping equipment capex:Thermoplastic-to-coupling termination requires precision crimpers distinct from rubber hose tooling, creating capital barriers for small distributors serving agricultural machinery repair shops.
- Polyether raw material concentration:Polyurethane precursor supply concentrates among Asian petrochemical producers, exposing European and North American extruders to freight cost volatility and inventory carrying pressure.
- Steel wire reinforcement substitution limits:Ultra-high-pressure mining applications above fifteen thousand psi still require steel wire braids that thermoplastic jackets cannot fully displace, capping penetration in underground extraction equipment.
Strategic Opportunities
- Indian construction equipment aftermarket:Domestic OEMs under BIS pressure-equipment certification requirements are qualifying imported thermoplastic hose assemblies for excavator and loader hydraulic rebuild programs.
- Pre-assembled kitting services:Distributor consolidation is creating demand for warranty-backed hose-and-coupling kits that bypass field-assembly bottlenecks caused by collapsing technician availability in mature manufacturing economies.
- GB standards alignment in China:Multinational suppliers serving domestic Chinese OEMs can capture import qualification advantages by preemptively certifying to evolving NMPA-aligned pressure-equipment rules before mandatory implementation.
Industry Challenges
- Hydraulic assembly technician scarcity:Skilled crimping and routing specialists are retiring faster than vocational programs replace them across Germany, the United States, and Japan, forcing OEMs to absorb kitting labor costs previously borne by distributors.
- ISO 18752 certification timeline compression:German automotive-hydraulic supply chains demand concurrent pressure-rating validations across multiple SAE J517 specification tiers, extending product development cycles for coupling manufacturers seeking market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydraulic Thermoplastic Hose and Couplings Market |
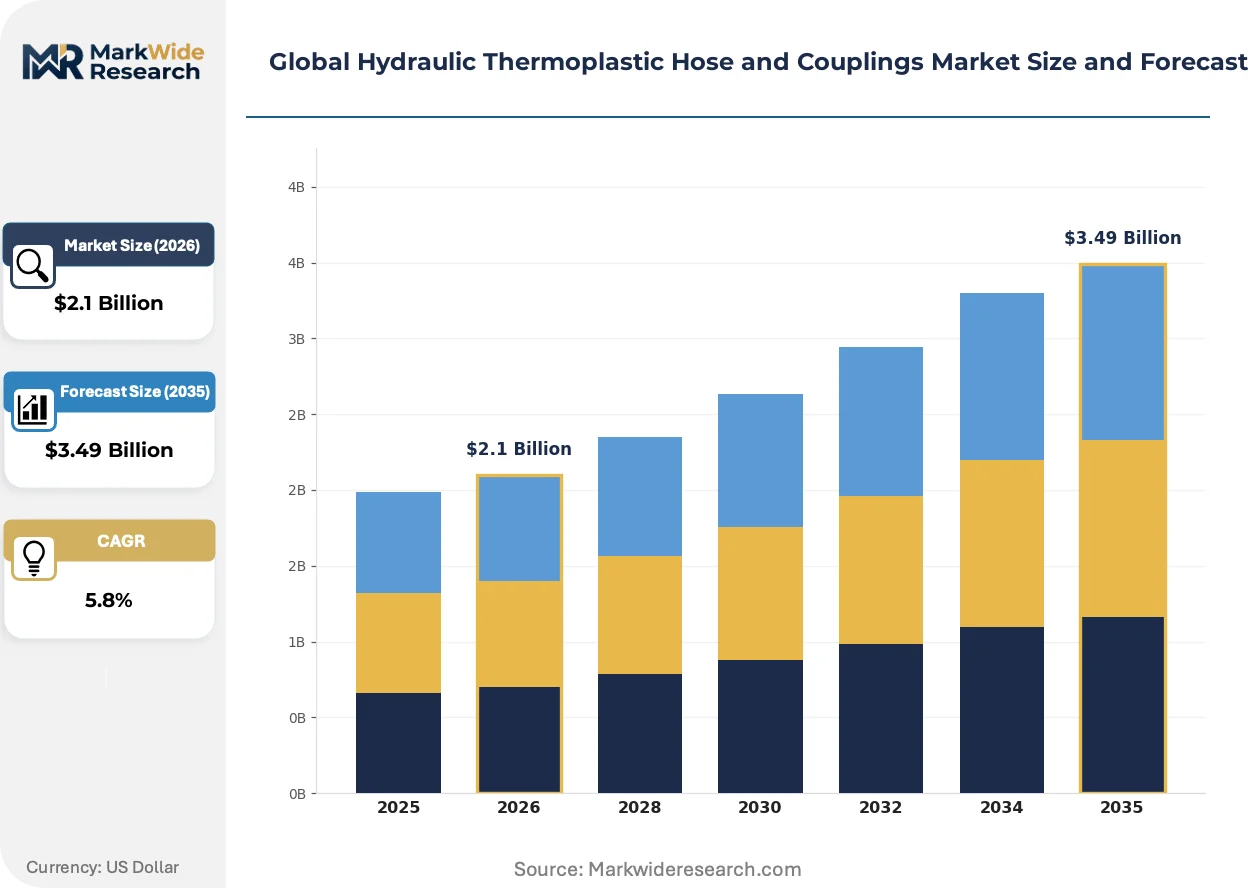
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Hose, Thermoplastic Hose, Hose Couplings, Assembly Kits, Connector Fittings Material Composition: Polyurethane, Nylon, Polyester, Polyethylene, PVC Application: Agricultural Machinery, Construction Equipment, Marine Systems, Mining Machinery, Material Handling End User Industry: Manufacturing Plants, Oil Exploration Firms, Power Generation Units, Heavy Equipment Dealers, Transportation Specialists |
| Companies Covered | Parker Hannifin Corporation, Gates Corporation, Eaton Corporation, Manuli Hydraulics, RYCO Hydraulics, Semperit, Alfagomma Group, Strongflex, Novafit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydraulic Thermoplastic Hose and Couplings Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are converging to reshape hose construction specifications, while distributor consolidation is forcing channel restructuring across aftermarket supply chains.
Multi-layer co-extruded thermoplastic barrier technology is decomposing the traditional separation between high-pressure hydraulic and pneumatic conveying applications. Mining equipment operators in Australia and Chile are adopting unified hose specifications across both fluid types to simplify maintenance inventory. This convergence is compressing SKU proliferation among distributors previously maintaining separate rubber and thermoplastic stockkeeping units.
ECHA REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing European compounders to reformulate PVC and polyurethane heat stabilizers for hydraulic hose jackets. German extruders are qualifying calcium-zinc and organic-based alternatives ahead of sunset dates, with certification costs disproportionately burdening mid-tier coupling manufacturers lacking in-house polymer laboratories. The regulatory pressure is accelerating consolidation among European specialty compounders serving fluid power applications.
Fleet maintenance departments are unbundling after-sales service contracts from original equipment procurement, sourcing hose assemblies directly from fluid-power distributors with captive crimping capabilities. Agricultural machinery operators in the US Midwest and Canadian Prairies are bypassing dealer networks for scheduled hydraulic maintenance, concentrating volume among national distributors with regional fabrication centers. This disintermediation is compressing margins for OEM captive parts operations while expanding addressable revenue for independent hose specialists.
Global Hydraulic Thermoplastic Hose and Couplings Market Segmentation
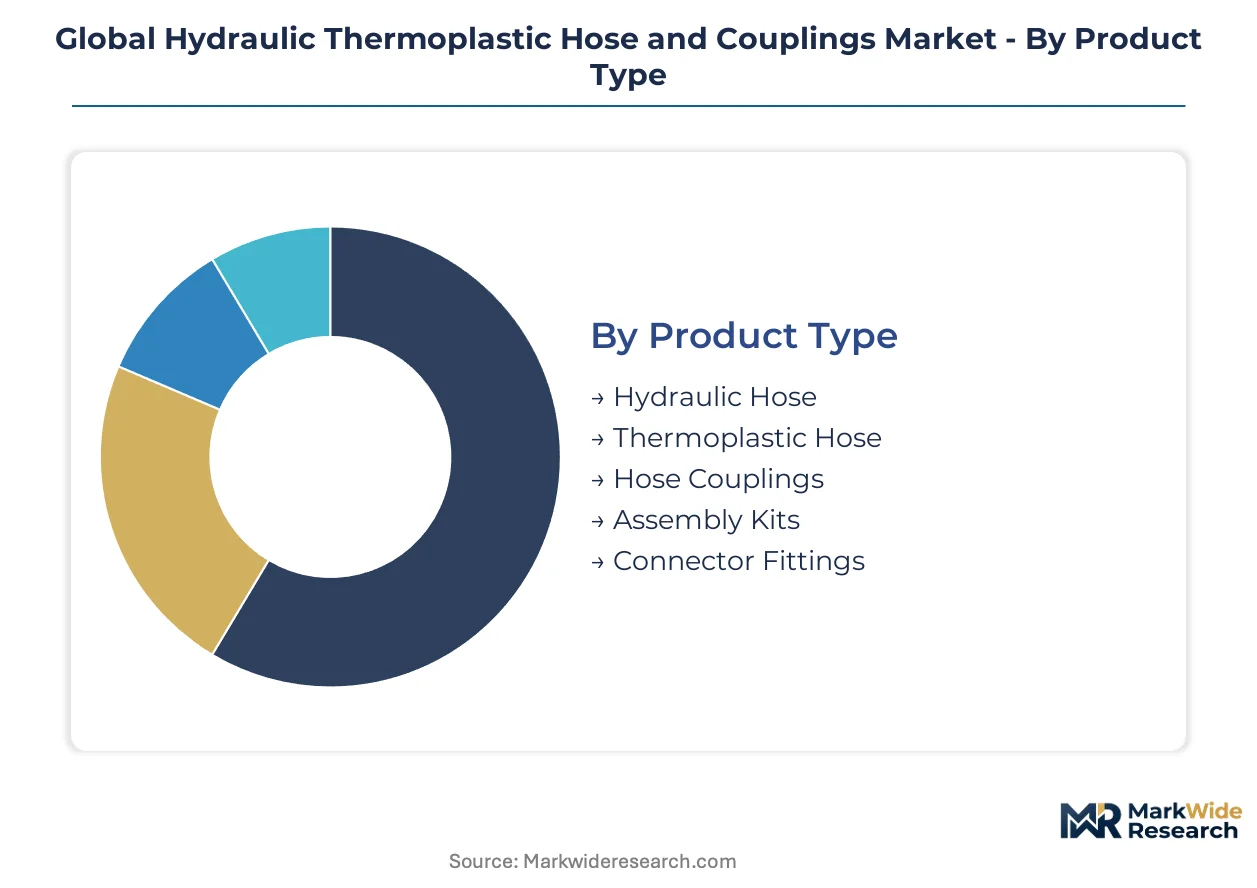
Thermoplastic hose procurement patterns diverge sharply across product configurations and material specifications. Fleet operators prioritize pre-assembled solutions that compress maintenance downtime, while compounders chase formulation premiums in regulated European supply chains.
Product Type:
Margin pools concentrate in value-added assemblies that bundle hoses, couplings, and certification documentation into single-SKU procurement solutions.
- Assembly Kits:Pre-configured hose-and-coupling bundles with pressure-test certificates and routing guides eliminate field crimping errors. Warehouse automation fleets in Germany and the United States are consolidating procurement through national distributors offering captive kitting services to bypass technician scarcity.
- Hydraulic Hose:Extruded thermoplastic tubes with synthetic fiber or steel wire reinforcement rated for dynamic flexing cycles dominate OEM specification sheets. Arctic mining operators in Canada specify polyurethane constructions for sub-zero flexibility, extending replacement intervals beyond conventional rubber alternatives.
- Thermoplastic Hose:Lightweight polymer constructions displace rubber in weight-sensitive mobile equipment. Agricultural machinery OEMs in the US Midwest specify these for boom sprayers and harvester hydraulics.
- Hose Couplings:Crimped or reusable metallic terminations require precision tooling distinct from rubber hose equipment. Small distributors serving repair shops face capital barriers to qualification.
- Connector Fittings:Adapters and transition pieces bridge incompatible thread standards across machinery generations. Aftermarket demand concentrates in legacy equipment rebuild programs.
Assembly Kits hold installed capacity. Thermoplastic Hose is rotating up the share rankings.
Material Composition:
Formulation premiums track regulatory chemistry restrictions and end-use thermal cycling demands rather than raw commodity spreads.
- Polyurethane:Abrasion-resistant elastomer with superior flex-fatigue performance at temperatures below minus forty degrees Celsius. Norwegian offshore operators and Canadian mining fleets specify this for exposed routing in Arctic conditions.
- Nylon:Semi-crystalline polyamide with exceptional chemical resistance to synthetic hydraulic fluids. German automotive-hydraulic suppliers favor this for compact high-pressure circuits in engine-bay environments.
- Polyester:Cost-competitive alternative with moderate chemical compatibility and UV stability. Agricultural machinery in price-sensitive markets adopts this for seasonal-use equipment.
- Polyethylene:Lower-pressure applications in pneumatic conveying and fluid transfer. Australian mining operators deploy this for unified hose specifications across hydraulic and pneumatic systems.
- PVC:Legacy jacket material facing ECHA REACH restrictions on phthalate plasticizers. European compounders are reformulating with calcium-zinc stabilizers ahead of sunset dates.
Polyurethane commands formulation premiums. Nylon is climbing the fastest among specification-grade alternatives.
Application:
Equipment utilization intensity and regulatory replacement cycles determine aftermarket coupling velocity more than fleet size alone.
- Construction Equipment:Excavators and loaders face extended hydraulic system replacement cycles under EPA emissions standards. Durable thermoplastic constructions outlast engine rebuild intervals, compressing traditional rubber supply relationships.
- Mining Machinery:Ultra-high-pressure underground extraction above fifteen thousand psi still requires steel wire braids that thermoplastic jackets cannot fully displace. Surface operations adopt synthetic fiber-reinforced designs more readily.
- Material Handling:Battery-powered forklifts and AGVs generate thermal cycling demands that thermoplastic hoses withstand more reliably than rubber. Warehouse automation in the United States drives aftermarket coupling replacement velocity.
- Agricultural Machinery:Seasonal use patterns with extended storage intervals favor corrosion-resistant thermoplastic constructions. US Midwest operators bypass dealer networks for scheduled maintenance.
- Marine Systems:Salt spray exposure and sub-zero offshore conditions specify polyurethane formulations. Norwegian operators lead adoption of synthetic fiber-reinforced designs.
Construction Equipment anchors replacement volume. Material Handling is gaining share fastest on electrification tailwinds.
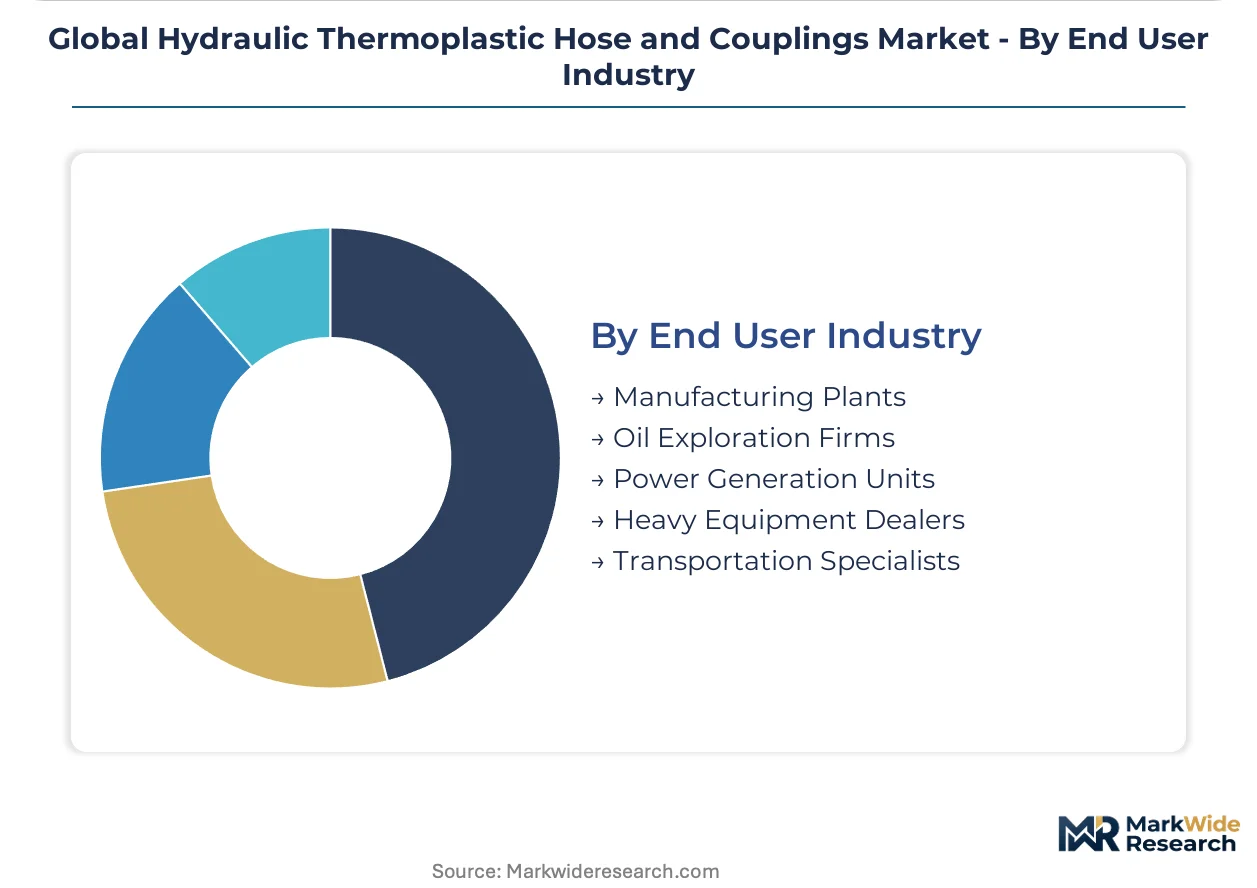
End User Industry:
Procurement authority is shifting from OEM captive parts operations toward independent distributors with regional fabrication capabilities.
- Heavy Equipment Dealers:Traditional channel facing margin compression as fleet maintenance departments unbundle after-sales contracts. National distributors with captive crimping capture volume previously routed through dealer networks.
- Manufacturing Plants:Continuous-operation environments prioritize extended service intervals and reduced downtime. Pre-assembled kits with warranty backing displace cut-and-couple counter service.
- Oil Exploration Firms:Remote operations demand inventory simplification through unified hose specifications. Multi-layer co-extruded barriers serve both hydraulic and pneumatic applications.
- Power Generation Units:Scheduled maintenance windows drive planned procurement of certified assemblies. BIS pressure-equipment requirements in India qualify imported thermoplastic hose for domestic rebuild programs.
- Transportation Specialists:Mobile repair operations require lightweight, flexible hose constructions for field service. Polyurethane specifications dominate sub-zero routing applications.
Heavy Equipment Dealers retain legacy volume. Manufacturing Plants are rotating up the share rankings on kitting preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes thermoplastic hose assemblies through automotive-hydraulic supply chains requiring REACH-compliant formulations, while China sources through domestic OEM qualification pathways under evolving GB standards. The United States anchors aftermarket volume through EPA-extended replacement cycles, with Canada and India rounding out demand concentration in Arctic mining and construction equipment rebuild programs respectively.
United States
Construction equipment fleets drive procurement through extended hydraulic system replacement cycles mandated by EPA emissions standards for off-road diesel machinery. Fleet operators prioritize durable thermoplastic constructions that outlast regulatory-mandated engine rebuild intervals. National fluid-power distributors with captive crimping capabilities concentrate in the Midwest agricultural belt and Texas energy corridor.
Germany
Automotive-hydraulic suppliers specify nylon formulations for compact high-pressure engine-bay circuits requiring chemical compatibility with synthetic fluids. ECHA REACH restrictions on phthalate plasticizers and heavy-metal stabilizers force compounders toward calcium-zinc alternatives ahead of sunset dates. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host extruders qualifying reformulated polyurethane and PVC jacket materials.
China
Domestic construction equipment OEMs under NMPA-aligned pressure-equipment rules are qualifying imported thermoplastic hose assemblies for excavator and loader hydraulic systems. GB standards evolution creates import qualification advantages for multinational suppliers certifying preemptively. Manufacturing concentration in the Yangtze River Delta and Pearl River Delta drives specification-grade demand for high-pressure constructions.
Canada
Arctic mining operators in Alberta and northern territories specify polyurethane constructions rated for temperatures below minus forty degrees Celsius. Sub-zero flexibility requirements extend replacement intervals beyond conventional rubber alternatives in exposed routing applications. Regional distributors serving the Prairie Provinces bypass dealer networks for scheduled hydraulic maintenance on agricultural machinery.
India
Domestic OEMs under BIS pressure-equipment certification requirements are qualifying imported thermoplastic hose assemblies for excavator and loader hydraulic rebuild programs. Construction equipment aftermarket expansion concentrates in Maharashtra and Gujarat manufacturing corridors. Fleet operators prioritize corrosion-resistant constructions suited to seasonal use patterns with extended storage intervals.
Global Hydraulic Thermoplastic Hose and Couplings Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive distribution networks and in-house polymer laboratories creating separation from mid-tier compounders lacking certification infrastructure. The market structures around three archetypes: multinational fluid-power conglomerates with global fabrication footprints, regional hose specialists serving national distributor networks, and captive OEM supply operations maintaining vertical control over critical assemblies. Competitive moves concentrate on distributor consolidation to capture kitting revenue and preemptive regulatory certification to secure market access ahead of compliance deadlines.
Among integrated North American conglomerates, Parker Hannifin Corporation and Gates Corporation exemplify the distribution-captive archetype, with Eaton Corporation occupying a position in high-pressure specification development. These three anchors represent contrasting strategic postures: captive channel control, aftermarket private-label partnerships, and R&D-intensive pressure-rating leadership respectively. Regional specialists including Manuli Hydraulics, RYCO Hydraulics, and Alfagomma Group sit within the tier serving national fluid-power distributors with regional fabrication capabilities. The competitive dynamic forces mid-tier compounders toward consolidation or niche specialization as certification costs disproportionately burden players lacking in-house polymer laboratories.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Gates Corporation |
| Eaton Corporation |
| Manuli Hydraulics |
| RYCO Hydraulics |
| Semperit |
| Alfagomma Group |
| Strongflex |
| Novafit |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between German automotive-hydraulic suppliers and polyurethane compounders lock in both supply access and price visibility, insulating qualified manufacturers from polyether raw material volatility while exposing non-contracted distributors to spot market swings. These arrangements concentrate procurement power among extruders with captive polymer laboratories capable of REACH-compliant formulation shifts.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational OEMs and certified European compounders, while spot transactions persist for small agricultural repair shops lacking volume scale. Price differentiation rests on ISO 18752 certification tier and captive crimping capability, with assembly kits commanding premiums over cut-and-couple counter service. Cost compression in standard-grade polyester constructions is intensifying because of distributor consolidation and private-label competition. Fleet operators with unbundled maintenance contracts show lowest price sensitivity; seasonal agricultural machinery users exhibit highest.
Supply Chain Analysis
China and South Korea anchor polyether polyol production for polyurethane precursors, while Germany and the United States host specialized extruders serving automotive-hydraulic supply chains. Thermoplastic hose manufacturing draws from Asian petrochemical feedstocks, European compounding expertise, and North American fabrication capacity. Single-source vulnerability concentrates in polyether raw material supply, exposing European and North American extruders to freight cost volatility. Distribution runs through national fluid-power distributors with regional captive crimping centers, bypassing traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates acquisition opportunities as distributor consolidation and technician scarcity fragment procurement authority across fleet operators, national distributors, and OEM captive parts operations.
For Market Incumbents: Consolidate regional fabrication capabilities to capture kitting revenue streams threatened by collapsing technician availability in Germany and the United States. Deepen backward integration into polyurethane compounding to secure REACH-compliant formulation capacity ahead of ECHA sunset dates, defending margin position against private-label competitors. For New Entrants and Emerging Players: Differentiate on preemptive GB standards certification for Chinese domestic OEM qualification pathways. Target Indian construction equipment aftermarket under BIS pressure-equipment rules, where imported assembly kit demand outpaces local supply. Pursue direct procurement relationships with warehouse automation fleets bypassing dealer networks. For Investors and Strategic Acquirers: Regional hose specialists with captive crimping networks and NMPA-aligned certification infrastructure represent priority acquisition targets. Long-term viability hinges on distributor consolidation tailwinds and regulatory compliance moats. Watch for inflection when Chinese GB standards adoption accelerates import qualification timelines for multinational suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Preemptive Regulatory Certification | ECHA REACH-compliant polyurethane formulations secure German automotive-hydraulic supply chain access ahead of compounder consolidation. |
| Captive Kitting Service Expansion | Regional fabrication centers bypass field-assembly bottlenecks caused by retiring hydraulic technicians across mature manufacturing economies. |
| Backward Integration into Compounding | In-house polymer laboratories reduce certification cost burdens and accelerate formulation response to ECHA restriction timelines. |
| GB Standards Alignment Investment | Preemptive NMPA-aligned qualification captures Chinese domestic OEM procurement previously reserved for local suppliers. |
| Distributor Network Consolidation | National fluid-power distributors with captive crimping concentrate volume from unbundled fleet maintenance contracts. |
Research Methodology
Operator-level perspectives from hydraulic assembly technicians, OEM procurement managers, fluid-power distributor operations heads, and compounder R&D directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC filings, customs trade data, ISO certification registries, and ECHA restriction timelines. Bottom-up demand modeling triangulated with top-down supply capacity assessments across the analysis window.
Sensitivity analysis tested forecast robustness across polyether price volatility scenarios, REACH compliance cost assumptions, and technician availability trajectories. Segmentation dimensions spanned product configuration, material composition, application intensity, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, fleet electrification penetration curves, and distributor consolidation velocity. Industry-specific inputs included EPA emissions standard replacement interval extensions and ECHA Annex XVII sunset date schedules.
The analysis sits within stated boundaries; outcomes outside sustained polyether supply continuity, stable REACH enforcement timelines, or technician retirement rates would require recalibration. Forecasts reflect documented assumptions regarding distributor consolidation pace and Chinese GB standards adoption trajectory. Recalibration cycles align with material shifts in ECHA regulatory enforcement and NMPA qualification pathway evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Global Fiberglass Pipe Market
Pipes and Tubes
Agricultural Pipes and Tubes Market
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
Saudi Arabia PVC Pipes Market
Pipes and Tubes
HDPE Corrugated Pipe Market
Pipes and Tubes
Gas Fittings and Components Market
Pipes and Tubes
Portugal PVC Pipes Market
Pipes and Tubes
Germany Acid Proof Lining Market
Pipes and Tubes
Drum Funnel Market
Pipes and Tubes
Steel Pipes and Tubes Market
Pipes and Tubes
United States Copper Pipes and Tubes Market
Pipes and Tubes
Global Titanium Tube Market
Pipes and Tubes
Global Cured-In-Place Pipe Market