
 Global Cured-In-Place Pipe Market | 2026-2036
Global Cured-In-Place Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cured-In-Place Pipe Market Foresight
Municipal sewer rehabilitation is realigning capital allocation across the trenchless sector as cities prioritize non-disruptive pipe renewal over open-cut replacement. Insituform Technologies leverages its installed base and lining fleet scale to dominate North American municipal contracts. Aegion Corporation anchors its position through integrated service delivery spanning inspection, cleaning, and cured-in-place installation. Saertex multiCom specializes in high-performance textile liners that compete on structural strength in European water utility networks.
Cured-in-place pipe consists of a resin-impregnated flexible tube, typically polyester or glass fiber, that hardens inside an existing conduit through thermal, UV, or steam curing to form a structural new pipe within the old. The process restores hydraulic capacity and eliminates infiltration without surface excavation, with standard liner thickness ranging from three to twelve millimeters depending on host pipe diameter and load requirements. UV cure systems lead on speed and environmental control, while thermal cure remains the volume workhorse for large-diameter sewer rehabilitation where installation method flexibility matters most. Steam cure occupies a narrower niche in industrial plant applications demanding rapid return to service.
The EPA enforces Clean Water Act consent decrees that compel municipalities to eliminate sanitary sewer overflows, directly expanding CIPP project pipelines across the United States. Germany's KBA and state water authorities enforce DWA standards for trenchless rehabilitation that shape product certification and contractor qualification requirements. France's ANSM and public health regulators impose strict resin leaching tests for drinking water applications, filtering market access for liner suppliers. Stakeholders must monitor how tightening per- and polyfluoroalkyl substance scrutiny reshapes resin chemistry choices and compliance costs across jurisdictions.
Market Dynamics
UV-cured liner systems are compressing project timelines and reshaping contractor fleet composition as water utilities prioritize speed over thermal cure flexibility for medium-diameter applications.
Growth Catalysts
- EPA Lead and Copper Rule Revisions:The United States Environmental Protection Agency mandates lining for aging potable water infrastructure, accelerating trenchless rehabilitation procurement across municipal water systems.
- Steam Cure Technology:Industrial plant operators adopt steam-cured CIPP for rapid return-to-service requirements in petrochemical and power generation facilities.
- German DWA Standards:State water authorities enforce rigorous product certification that elevates quality benchmarks and filters qualified contractors across European utility networks.
Market Restraints
- Resin Chemistry Volatility:Epoxy and vinyl ester resin prices fluctuate with petrochemical feedstock costs, squeezing contractor margins on fixed-price municipal contracts.
- Specialized Equipment Concentration:UV cure system manufacturing clusters in Germany and the United States, creating supply bottleneck risks for contractors in emerging markets.
- Per- and Polyfluoroalkyl Substance Scrutiny:France's ANSM and other health regulators impose leaching tests that restrict resin formulation choices and extend product approval timelines.
Strategic Opportunities
- India Urban Infrastructure:Smart city initiatives and AMRUT funding create pipeline for trenchless sewer rehabilitation in Delhi, Mumbai, and Bangalore metropolitan utilities.
- Drinking Water Lining Convergence:NSF/ANSI 61 certification combined with UV cure speed opens potable water applications previously dominated by thermal cure methods.
- Digital Inspection Integration:Robotic crawler and LiDAR data feeds enable predictive liner specification, shifting contractor value proposition from installation to asset management.
Industry Challenges
- Certified Installer Scarcity:UV cure equipment operation demands specialized training that outpaces vocational program output in North American and European markets.
- Legacy Host Pipe Assessment:Pre-lining condition evaluation requires ground-penetrating radar and CCTV expertise that many municipal maintenance departments lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cured-In-Place Pipe Market |
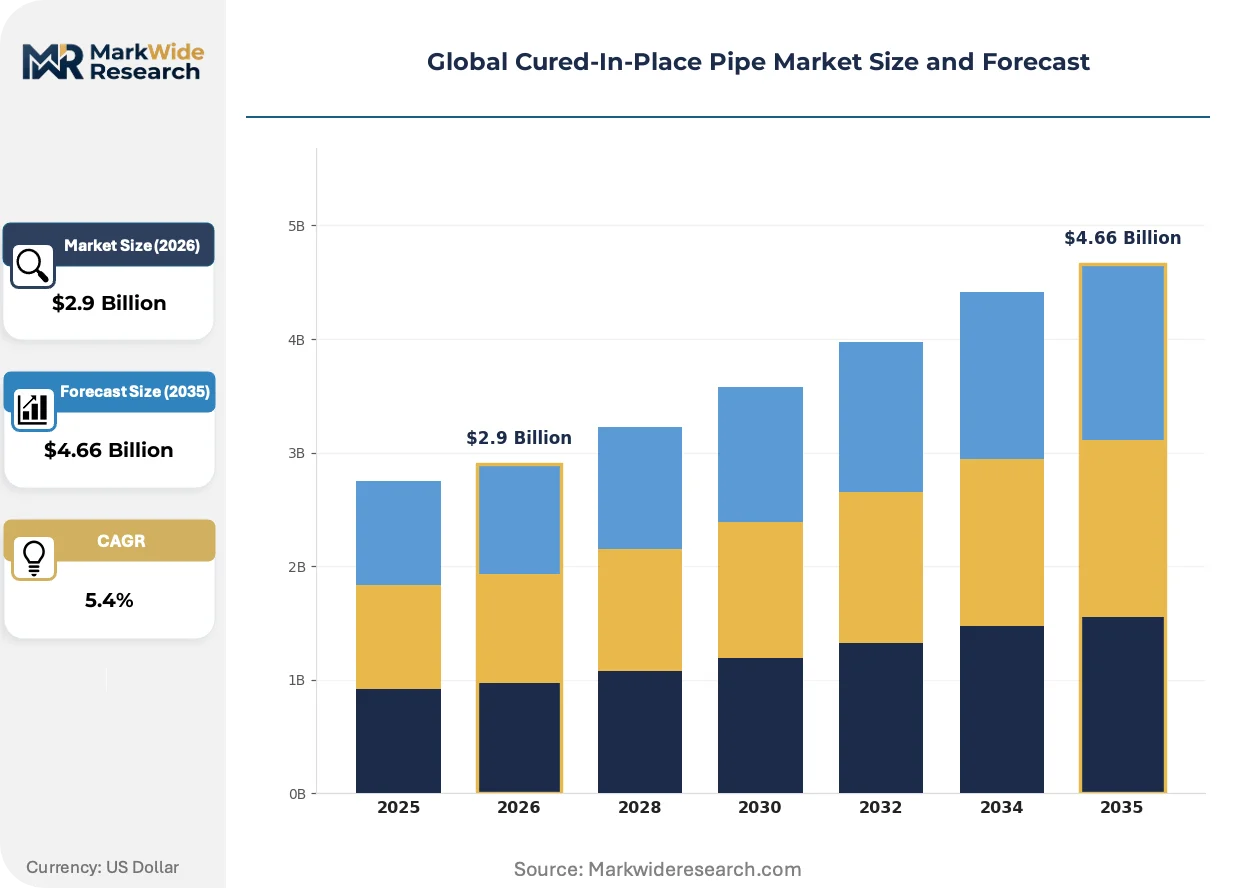
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $4.66 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV Cure, Thermal Cure, Ambient Cure, Steam Cure End User: Municipalities, Water Utilities, Industrial Plants, Oil & Gas Facilities Application: Sewage Rehabilitation, Stormwater Management, Drinking Water, Chemical Pipelines Installation Method: Slip Lining, Inversion, Pull-in-Place, Push-in-Place, Spiral Wound |
| Companies Covered | Insituform Technologies, Layne Inliner, Perma-Liner Industries, Inland Pipe Rehabilitation, Saertex multiCom, Ashimori Industry, Aegion Corporation, Trelleborg, Michels Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cured-In-Place Pipe Market Shifts & Advancements
Resin chemistry advances and curing automation are compressing project timelines while expanding structural liner applications beyond traditional gravity sewer rehabilitation into pressure-rated water mains and industrial process piping.
LED-UV curing systems is rewriting installation economics by enabling ambient-temperature cure without steam or hot water infrastructure. German water utilities specify LED-UV for diameter ranges below 800mm where speed outweighs capital cost premiums. The technology is compressing contractor fleet diversity as single-source UV platforms displace multi-cure equipment portfolios.
France's ANSM resin leaching protocols are forcing reformulation of styrene-based polyester resins used in potable water applications. Liner manufacturers face extended certification timelines as migration testing protocols expand from organoleptic parameters to full chemical constituent analysis. Suppliers with pre-validated epoxy vinyl ester formulations capture specification preference in French and Belgian drinking water contracts.
Performance-based rehabilitation contracts are displacing unit-rate procurement in United Kingdom water utilities. Thames Water and Anglian Water bundle inspection, cleaning, and lining under multi-year outcome guarantees that transfer infiltration risk to contractors. This procurement pivot favors integrated service providers with captive inspection and data analytics capabilities over installation-only specialists.
Global Cured-In-Place Pipe Market Segmentation
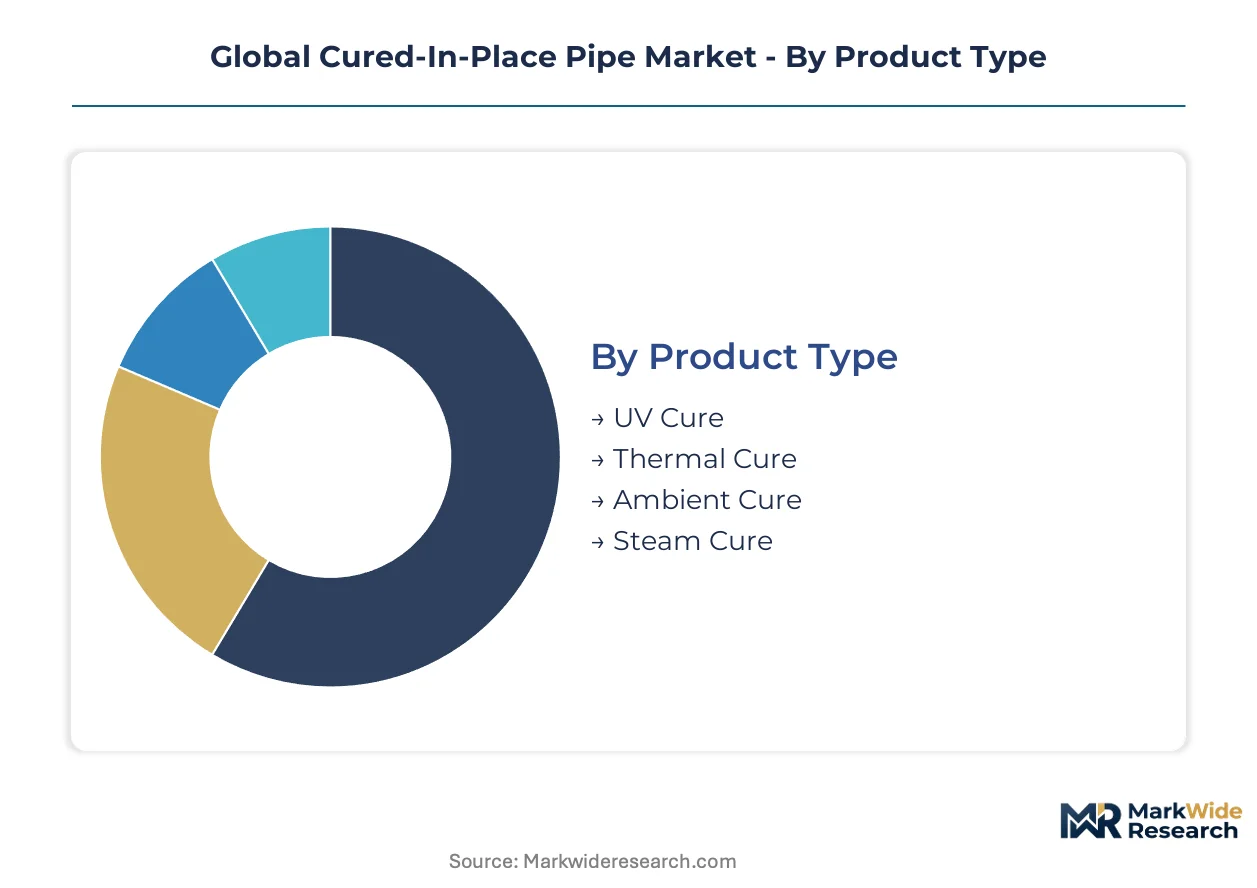
CIPP technology selection hinges on balancing cure speed against equipment capital requirements. Segmentation reveals how contractor fleet composition and utility procurement priorities diverge across curing methodologies, end-user risk profiles, and installation constraints.
Product Type:
Capital intensity varies sharply across curing technologies, with UV systems demanding the heaviest upfront equipment investment while ambient cure minimizes barrier to entry.
- UV Cure:LED-UV systems cure liners through ultraviolet radiation at ambient temperatures, eliminating steam or hot water infrastructure. German water utilities specify this technology for diameters below 800mm where project speed outweighs capital premiums. Equipment manufacturing concentrates in Germany and the United States, creating supply bottlenecks for contractors elsewhere.
- Thermal Cure:Hot water or steam circulation through the liner remains the volume workhorse for large-diameter sewer rehabilitation. Municipal contractors favor thermal systems where installation method flexibility matters more than speed, particularly in host pipes with complex geometries or significant ovality.
- Ambient Cure:Room-temperature resin systems require minimal specialized equipment, lowering entry barriers for regional contractors. Performance limitations restrict this segment to small-diameter, low-load applications where cure time extension is acceptable.
- Steam Cure:Rapid heat transfer enables industrial plant operators to achieve return-to-service timelines measured in hours. Petrochemical and power generation facilities specify steam cure for process piping where downtime carries substantial revenue impact.
Most installed capacity flows through Thermal Cure. Expansion is steepest in UV Cure.
End User:
Contractor margin structures diverge across customer types, with industrial facilities paying premium rates for speed guarantees that municipalities rarely authorize.
- Municipalities:City sewer departments dominate project volume, procuring CIPP through competitive bidding constrained by municipal budget cycles. EPA consent decrees compel overflow elimination investments, expanding project pipelines across United States cities.
- Water Utilities:Potable water rehabilitation demands NSF/ANSI 61 certification and resin leaching compliance that filters supplier pools. France's ANSM protocols extend approval timelines for styrene-based polyester formulations.
- Industrial Plants:Petrochemical, power generation, and manufacturing facilities prioritize rapid return-to-service over unit cost, accepting steam cure premiums to minimize production losses.
- Oil & Gas Facilities:Pipeline integrity regulations and corrosion management drive trenchless rehabilitation demand in downstream refining and midstream transmission infrastructure.
Procurement volume concentrates in Municipalities. Margin expansion is most pronounced in Industrial Plants.
Application:
Technical specifications and regulatory scrutiny intensity vary substantially across application types, with drinking water imposing the most stringent material compliance burdens.
- Sewage Rehabilitation:Gravity sewer lining constitutes the foundational CIPP application, with structural liners restoring hydraulic capacity and eliminating infiltration in aging municipal collection systems. EPA enforcement shapes project timelines across United States utilities.
- Stormwater Management:Separated storm sewer rehabilitation expands as cities address combined sewer overflow reduction mandates. Liner specifications emphasize hydraulic capacity restoration over structural load-bearing in low-pressure applications.
- Drinking Water:Potable water lining requires resin formulations validated for chemical migration limits under French ANSM and German DWA protocols. UV cure speed is displacing thermal methods previously dominant in this segment.
- Chemical Pipelines:Industrial process piping demands corrosion-resistant vinyl ester resins and specialized thickness calculations for pressure-rated service conditions.
Project volume aggregates in Sewage Rehabilitation. Regulatory tailwinds are strongest in Drinking Water.
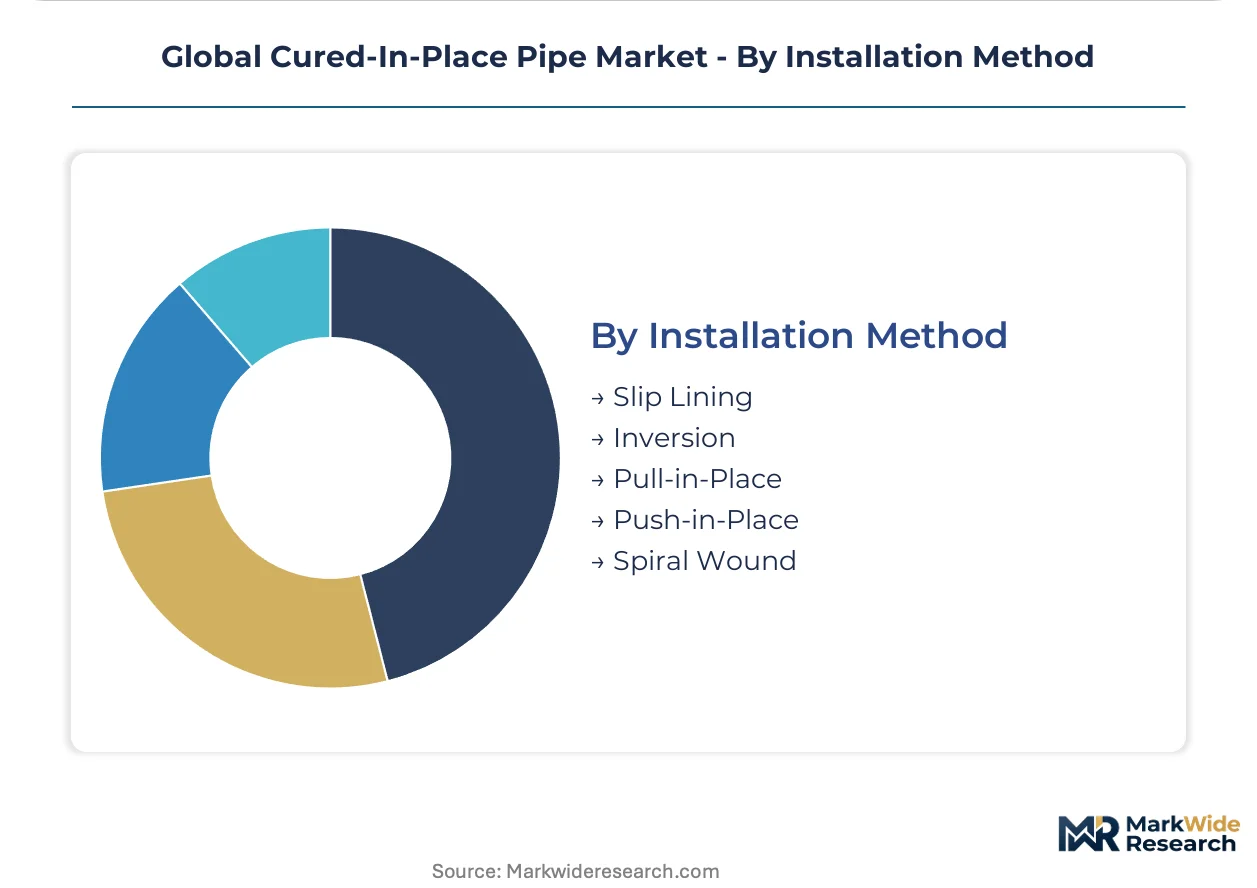
Installation Method:
Equipment specialization and crew training requirements create distinct competitive moats across installation methodologies.
- Slip Lining:Continuous liner insertion into deteriorated host pipes requires minimal excavation and accommodates moderate diameter reductions. United Kingdom water utilities specify slip lining for trunk sewer rehabilitation where flow capacity preservation is critical.
- Inversion:Air or water pressure turns resin-impregnated tubes inside-out during insertion, ensuring intimate host pipe contact. This method dominates municipal gravity sewer applications across North American and European markets.
- Pull-in-Place:Winch-based liner positioning enables precise placement in partially collapsed or heavily deformed host pipes where inversion risks failure.
- Push-in-Place:Mechanical insertion suits short liner lengths and manhole-to-manhole reaches where inversion equipment mobilization is uneconomical.
- Spiral Wound:Continuous PVC or HDPE strip winding creates structural liners without resin curing, appealing to utilities with chemical handling restrictions.
Contractor fleet investment concentrates in Inversion. Technology substitution is most active in Spiral Wound.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saertex multiCom's manufacturing complex in Saerbeck anchors European liner production capacity and sets quality benchmarks for UV-cured systems exported worldwide. Regulatory enforcement patterns and utility procurement priorities diverge sharply across national markets, creating distinct competitive arenas for trenchless rehabilitation contractors.
United States
EPA consent decrees under the Clean Water Act compel municipal sewer overflow elimination, expanding CIPP project pipelines across aging infrastructure networks. The agency's lead and copper rule revisions mandate lining for potable water systems, accelerating procurement from certified contractors. Chicago and Los Angeles metropolitan utilities anchor demand concentration, with both cities prioritizing UV-cured liners for medium-diameter applications below 800mm.
Germany
DWA standards enforced by state water authorities and KBA certification requirements elevate product quality benchmarks and filter qualified contractors across utility networks. Saertex multiCom's Saerbeck facility supplies high-performance textile liners competing on structural strength specifications. The Ruhr industrial corridor and Bavarian municipal utilities drive specification adoption for LED-UV systems in diameters where speed outweighs capital cost premiums.
France
ANSM resin leaching protocols impose strict migration testing that extends product approval timelines for styrene-based polyester formulations in drinking water applications. Public health regulators enforce full chemical constituent analysis beyond traditional organoleptic parameters. The Île-de-France region and Lyon metropolitan utility networks capture specification preference for pre-validated epoxy vinyl ester liners from qualified European suppliers.
India
Smart city initiatives and AMRUT funding create procurement pipelines for trenchless sewer rehabilitation across Delhi, Mumbai, and Bangalore metropolitan utilities. Central government infrastructure programs prioritize non-disruptive pipe renewal in dense urban corridors where open-cut excavation disrupts commerce. Contractor capability gaps in certified UV equipment operation create entry barriers that favor partnerships with experienced international specialists.
United Kingdom
Thames Water and Anglian Water bundle inspection, cleaning, and lining under multi-year outcome guarantees that transfer infiltration risk to contractors. Performance-based rehabilitation contracts displace unit-rate procurement, favoring integrated service providers with captive inspection and data analytics capabilities. London and Southeast England utility networks anchor specification adoption for slip-lining methods in trunk sewer rehabilitation where flow capacity preservation dominates technical requirements.
Global Cured-In-Place Pipe Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment manufacturers align with regional installation contractors to secure fleet placement and specification lock-in. The vendor base organizes around three distinct tiers: integrated service providers delivering inspection-through-lining workflows, specialized liner fabricators supplying resin-impregnated textiles to third-party installers, and regional contractors operating captive equipment fleets under license arrangements. Technology licensing agreements and multi-year framework contracts with water utilities constitute the primary competitive moves reshaping market access.
Among North American integrated service providers, Insituform Technologies and Aegion Corporation exemplify the full-service archetype spanning inspection, cleaning, and CIPP installation. Saertex multiCom occupies a distinct position as a European fabricator specializing in high-performance textile liners. These three anchors illustrate how competitive positioning diverges between contractors capturing municipal procurement volume and suppliers commanding premium specifications through material science differentiation.
| Leading Market Players |
|---|
| Insituform Technologies |
| Layne Inliner |
| Perma-Liner Industries |
| Inland Pipe Rehabilitation |
| Saertex multiCom |
| Ashimori Industry |
| Aegion Corporation |
| Trelleborg |
| Michels Corporation |
| Others |
Supply & Pricing Matrix
France's ANSM resin leaching protocols gate both qualified supply and premium-tier pricing access, filtering liner manufacturers through extended migration testing timelines while allowing pre-validated epoxy vinyl ester formulations to command specification premiums in drinking water contracts.
Pricing Analysis
Distributor margins compress project economics for regional contractors lacking direct mill relationships. Three-tier pricing structure across premium, standard, and economy levels separates NSF/ANSI 61 certified UV-cured systems from uncertified thermal cure alternatives and basic ambient cure offerings. Cost compression in the economy tier is intensifying because municipal procurement cycles favor lowest-bid awards. Water utilities exhibit lowest price sensitivity given regulatory compliance mandates, while emerging market contractors face acute margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with German UV cure equipment manufacturers, where LED-UV system production concentrates in Saerbeck and creates supply bottlenecks for contractors elsewhere. Raw material flows draw from polyester textile mills in Germany, epoxy resin producers in the United States, and glass fiber suppliers in China. Tariff exposure on Chinese glass fiber imports elevates input cost volatility. Distribution runs through licensed regional contractors operating captive installation fleets under technology transfer agreements with European equipment fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by the demand-shift toward NSF/ANSI 61 certified liners for potable water rehabilitation, where compliance premiums displace commodity procurement.
For Market Incumbents: To counter certified installer scarcity that constrains fleet expansion, deepen backward integration into resin formulation to capture margin from chemistry differentiation, while adding LED-UV training capacity in North American vocational partnerships to lock contractor pipeline access. For New Entrants and Emerging Players: Industrial plant operators in petrochemical corridors represent an underserved buyer archetype willing to absorb steam cure premiums for rapid return-to-service guarantees. Target this segment through equipment lease-to-own structures that lower capital barriers, paired with process piping expertise partnerships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional installation contractors lacking captive inspection capabilities. The five-to-ten year viability window favors integrated service providers bundling data analytics with lining execution. Watch for EPA consent decree acceleration in mid-sized US utilities as the inflection signal for municipal procurement volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captures margin from epoxy vinyl ester chemistry differentiation demanded by ANSM protocols. |
| LED-UV Training Academy Partnerships | Addresses certified installer scarcity constraining contractor fleet expansion in North America. |
| Multi-Year Outcome Guarantee Contracts | Mirrors Thames Water performance-based procurement transferring infiltration risk to contractors. |
| NSF/ANSI 61 Certification Investment | Opens potable water specification access previously blocked by migration testing barriers. |
| Digital Inspection Platform Acquisition | Enables predictive liner specification shifting value from installation to asset management. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal procurement officers, UV equipment operations managers, resin chemistry R&D directors, and trenchless contracting executives with secondary validation through EPA consent decree filings, DWA certification registries, ANSM migration test protocols, and municipal bond issuance documents for infrastructure rehabilitation. Bottom-up project pipeline aggregation and top-down utility budget analysis provided cross-verification.
Historical reference periods anchored the projection horizon to documented rehabilitation spending cycles and regulatory enforcement waves across the analysis window. Segmentation modeling spanned curing technology, end-user risk profile, application regulatory intensity, and installation method equipment specialization. CAGRs derived from utility capital plan trajectories and industrial facility maintenance scheduling patterns, with resin price elasticity and certified labor supply curves as sector-specific inputs.
Underlying measurement precision varies by segment; UV cure adoption rates and municipal procurement volumes carry tighter precision than industrial plant maintenance timing. Forecasts reflect assumptions about regulatory enforcement continuity and resin chemistry approval timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Compressed Air Pipe Market
Pipes and Tubes
Reinforced Thermoplastic Pipes Market
Pipes and Tubes
Portugal PVC Pipes Market
Pipes and Tubes
Qatar PVC Pipe Market
Pipes and Tubes
Aluminium Tubes for OPC Drum Market
Pipes and Tubes
Pipe Market
Pipes and Tubes
Global PEX (Cross-Linked Polyethylene) Market
Pipes and Tubes
Fttx Pipes Market
Pipes and Tubes
North America PVC Pipes Market
Pipes and Tubes
Steel Tubes Market
Pipes and Tubes
HDPE Corrugated Pipe Market
Pipes and Tubes
Pipe and Tube Cutters Market
Pipes and Tubes
Global Fiberglass Pipe Market
Pipes and Tubes
FRP Pipes and Tanks Market
Pipes and Tubes
Global Fluoropolymer Tubing Market
Pipes and Tubes
Hydrogen Tube Skids Market