
 Gas Fittings and Components Market | 2026-2036
Gas Fittings and Components Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Fittings and Components Market Foresight
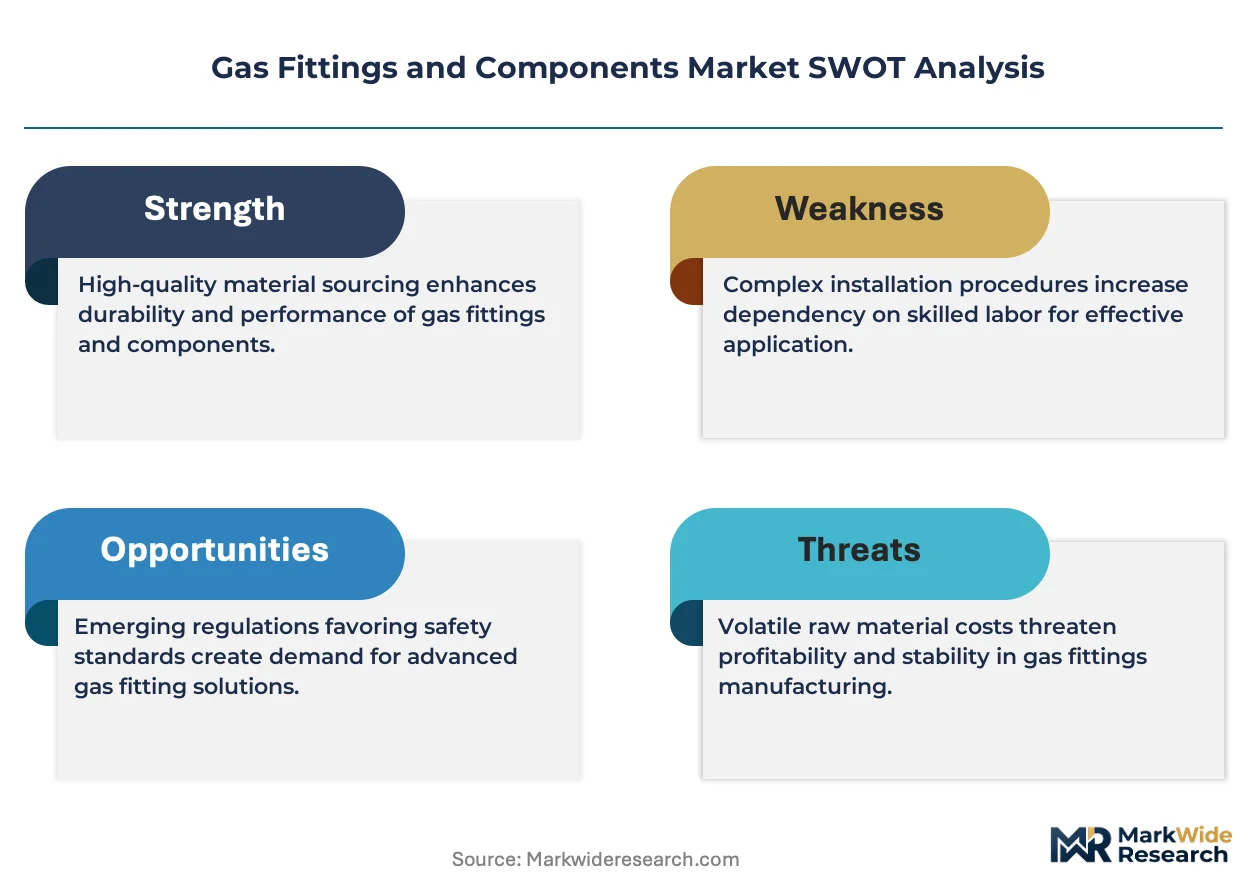
The EU Green Deal is consolidating demand for low-emission gas infrastructure across European chemical processing and HVAC systems. Parker Hannifin leverages its fluid systems portfolio to anchor specification-grade fitting supply for industrial process piping. Swagelok specializes in precision-engineered stainless steel connectors that sustain premium positioning in leak-critical applications. Victaulic competes through grooved mechanical joining systems that dominate large-diameter commercial gas distribution installations.
Gas fittings and components encompass valves, couplings, adapters, connectors, elbows, and tees manufactured from stainless steel, brass, copper, carbon steel, plastic, or aluminum, typically rated for pressure classes spanning 150 psi to 6000 psi depending on application criticality. These assemblies channel natural gas, propane, or process gases through residential, commercial, and industrial piping networks while maintaining seal integrity under thermal cycling and vibration. Stainless steel fittings command the strongest margin pools due to corrosion resistance mandates in chemical processing and offshore oil and gas transmission, while brass connectors retain volume leadership in residential gas systems where cost sensitivity shapes procurement. Plastic fittings represent the fastest-expanding material category in HVAC applications as building codes relax metal-only requirements for low-pressure distribution.
EMA, REACH, and the EU F-Gas Regulation collectively tighten material compliance and leakage-rate thresholds for gas handling equipment sold across Europe, forcing manufacturers to certify connector designs against updated pressure-equipment directives. EPA and OSHA standards in the United States impose parallel requirements on industrial gas piping integrity, creating dual-jurisdiction compliance burdens for multinational suppliers. Stakeholders must monitor evolving methane-emission protocols and pressure-equipment safety classifications to anticipate specification shifts before they harden into procurement mandates.
Market Dynamics
The EU F-Gas Regulation is compressing leakage-rate tolerances and forcing wholesale redesign of connector architectures across European industrial gas infrastructure. Manufacturers must now certify assemblies against tightened pressure-equipment directives or face exclusion from specification-grade procurement channels.
Growth Catalysts
- REACH compliance mandates:Chemical processing clusters in Germany are retrofitting legacy piping with low-emission stainless steel fittings to satisfy updated material-safety thresholds.
- Offshore platform corrosion resistance:North Sea oil and gas operators are specifying super-duplex stainless connectors for subsea manifolds exposed to hydrogen sulfide and chloride attack.
- HVAC plastic substitution:Building code relaxations in residential construction are accelerating polypropylene fitting adoption for low-pressure natural gas distribution.
Market Restraints
- Nickel price volatility:Stainless steel 316L feedstock costs swing with London Metal Exchange nickel futures, compressing margin pools for precision-machined fitting producers.
- Specialized forging concentration:Closed-die forging capacity for high-pressure gas fittings clusters in Northern Italy and Southwest Germany, creating single-source vulnerability.
- Threaded connection displacement:Grooved mechanical joining systems are eroding specification share for traditional NPT-threaded assemblies in commercial building applications.
Strategic Opportunities
- Hydrogen infrastructure buildout:Netherlands and Denmark pipeline operators are sourcing 700-bar rated fittings for hydrogen blending trials in existing natural gas networks.
- CE marking acceleration:Streamlined conformity assessment routes under updated pressure-equipment directives are reducing certification timelines for modular connector systems.
- Biogas digester expansion:Agricultural methane capture installations in France are creating demand for corrosion-resistant brass and stainless assemblies in farm-scale distribution.
Industry Challenges
- Orbital welding technician scarcity:High-purity gas systems require certified orbital TIG welders, and training pipeline gaps are extending installation timelines.
- Dual-jurisdiction compliance costs:Suppliers serving both EPA-regulated US facilities and EU pressure-equipment markets must maintain parallel testing and documentation regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Fittings and Components Market |
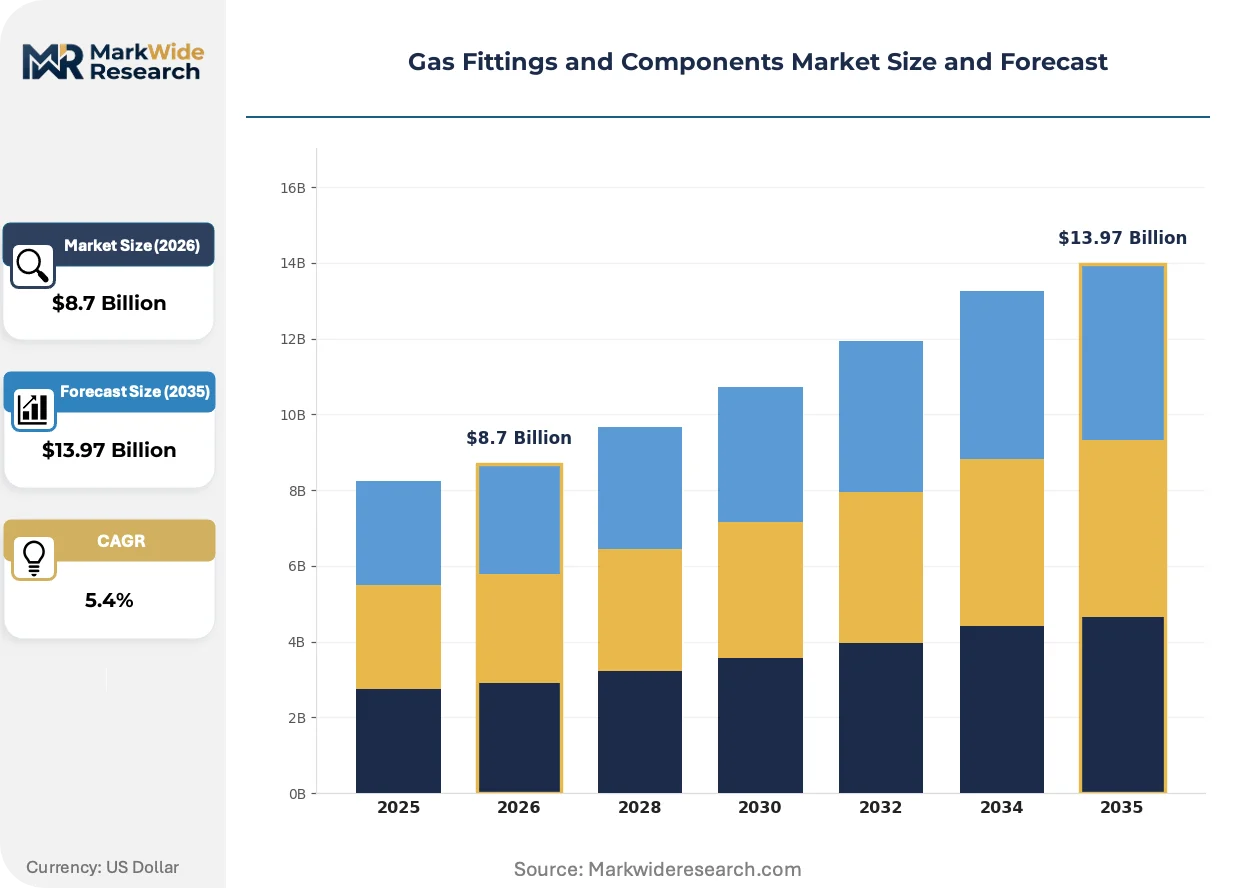
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Valves, Couplings, Adapters, Connectors, Elbows, Tees Material: Stainless Steel, Brass, Copper, Carbon Steel, Plastic, Aluminum Application: Residential Gas Systems, Commercial Gas Distribution, Industrial Process Piping, Chemical Processing, HVAC Systems, Oil & Gas Transmission End User: Construction Contractors, Manufacturing Plants, Utilities Providers, Energy Producers, Maintenance Services |
| Companies Covered | Parker Hannifin, Swagelok, Victaulic, Bonney Forge, Crane Co., Tylok International, Assure Parts, Regency Gas Hoses, Dormont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Fittings and Components Market Shifts & Advancements
Material substitution and joining-method evolution are restructuring competitive positioning across specification-grade and commodity fitting tiers. Regulatory leakage mandates and hydrogen infrastructure readiness are converging to reward connector designs that exceed baseline pressure ratings.
Compression-type tube fittings with dual-ferrule sealing architecture are overtaking traditional flare and cone-and-thread designs in analytical instrumentation and semiconductor gas delivery. Pharmaceutical manufacturers in Switzerland and Ireland are specifying these assemblies for ultra-high-purity process gases. The technology is compressing market share for legacy brazed connections in leak-critical applications.
The EU F-Gas Regulation's tightened leakage-rate thresholds are mandating redesigned gasket materials and face-seal geometries across industrial process piping. Connector manufacturers must now validate assemblies against ISO 19880-3 hydrogen compatibility standards alongside legacy natural gas certifications. Chemical processing clusters in Germany and Belgium are first movers in specifying these dual-certified fittings.
Specification-grade buyers are consolidating vendor relationships around integrated fluid-system suppliers capable of delivering pre-tested subassemblies rather than discrete components. Engineering-procurement-construction firms in the Netherlands are awarding multi-year framework agreements to single-source fluid systems partners. This concentration is most visible in offshore oil and gas and hydrogen pilot projects where liability integration matters.
Gas Fittings and Components Market Segmentation
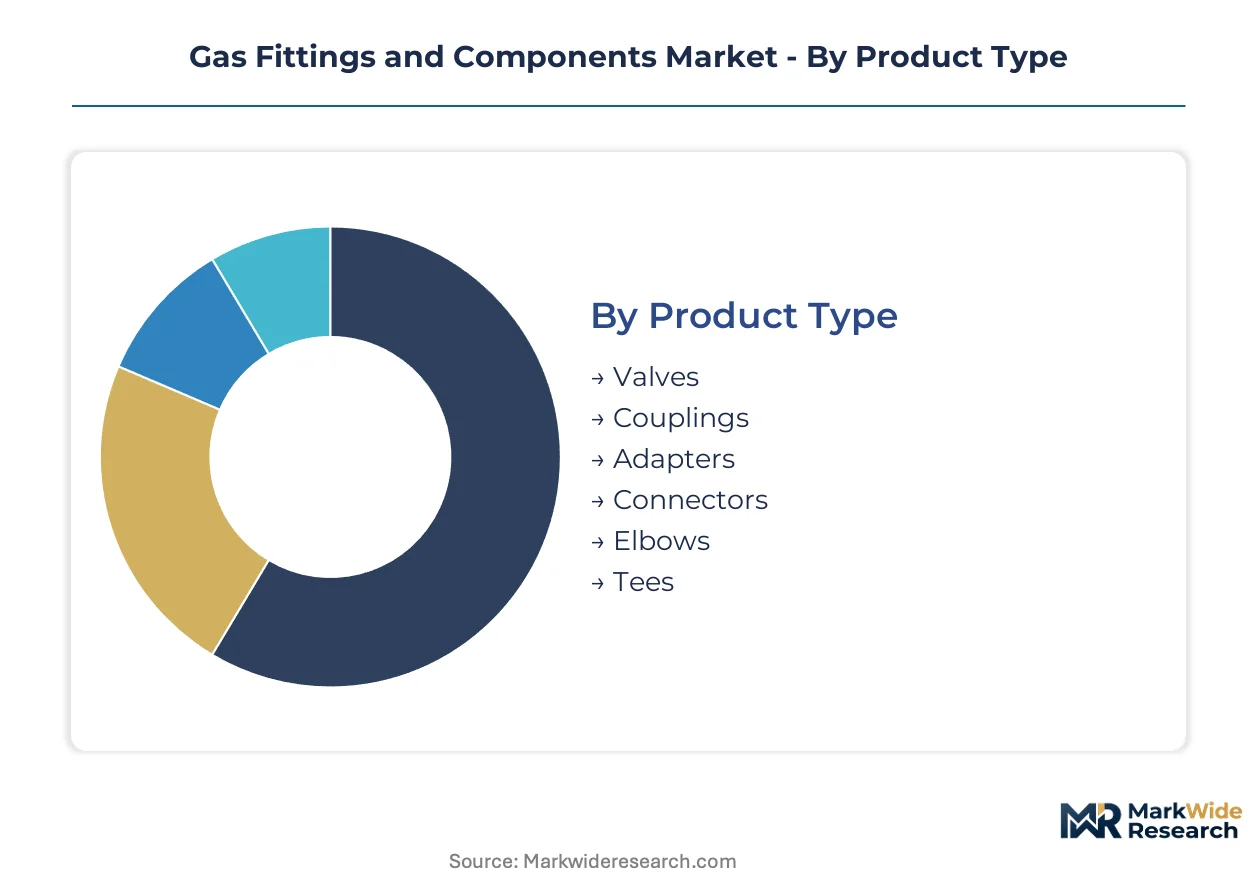
Gas fittings and components segment across multiple technical and commercial dimensions that shape procurement patterns. Specification-grade buyers prioritize material certification and pressure ratings, while residential contractors emphasize cost efficiency and code compliance. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization dominates.
Product Type:
Standardization intensity varies sharply across this category, with commodity-threaded items at one pole and precision-sealed assemblies at the other.
- Valves:Ball, gate, and needle configurations regulate flow in high-pressure industrial manifolds. German chemical processing clusters specify metal-seated ball valves for hydrogen sulfide service, driving demand for super-duplex stainless castings.
- Couplings:Rigid and flexible variants join pipe sections while accommodating thermal expansion and vibration. Grooved mechanical couplings from Victaulic dominate large-diameter commercial installations in Dutch distribution networks.
- Adapters:Transition fittings bridge disconnection standards between NPT, BSP, and metric thread forms. These assemblies resolve interoperability headaches in multinational equipment integration projects.
- Connectors:Compression, flare, and face-seal architectures deliver leak-tight performance in analytical instrumentation. Swiss pharmaceutical manufacturers specify dual-ferrule stainless designs for ultra-high-purity gas delivery.
- Elbows:45-degree and 90-degree directional changes route piping through constrained mechanical spaces. Carbon steel elbows retain cost advantage in residential construction where pressure cycling is minimal.
- Tees:Branching fittings distribute flow to multiple downstream legs in distribution headers. These components see heavy specification in North Sea platform manifold assemblies.
Most installed capacity flows through Valves. Expansion is steepest in Connectors.
Material:
Cost tier stratification separates premium corrosion-resistant alloys from commodity metals and polymers.
- Stainless Steel:Austenitic and duplex grades withstand chloride attack and thermal cycling in offshore environments. North Sea operators specify 316L and super-duplex connectors for subsea manifolds exposed to hydrogen sulfide.
- Brass:Copper-zinc alloys machine easily and resist dezincification in moderate-pressure residential service. French agricultural biogas digesters deploy brass fittings for farm-scale methane distribution networks.
- Copper:Native conductivity suits grounding applications and medical gas systems where bacterial growth resistance matters. Copper sweat fittings retain niche position in legacy healthcare infrastructure.
- Carbon Steel:Lower alloy content delivers cost efficiency in non-corrosive, low-pressure commercial applications. Carbon steel dominates standard-pressure HVAC distribution in cost-sensitive construction segments.
- Plastic:Polypropylene and PVDF assemblies reduce weight and eliminate galvanic corrosion in aggressive chemical exposure. Building code relaxations accelerate plastic adoption in residential low-pressure natural gas distribution.
- Aluminum:Lightweight extrusions serve aerospace and portable equipment applications where mass reduction outweighs strength penalties. Aluminum fittings occupy specialized niches in cryogenic and weight-critical systems.
Volume leadership sits with Brass. Margin expansion concentrates in Stainless Steel.
Application:
Customer maturity separates specification-grade industrial buyers from price-sensitive residential contractors.
- Residential Gas Systems:Low-pressure distribution networks serving single-family and multi-family dwellings. Belgian and Dutch building codes increasingly permit plastic fittings in these installations, displacing legacy brass and copper.
- Commercial Gas Distribution:Mid-pressure infrastructure for office buildings, retail, and hospitality. Grooved mechanical joining systems from specialized suppliers dominate this segment in large-diameter Dutch commercial projects.
- Industrial Process Piping:High-integrity assemblies for continuous manufacturing operations. German automotive and chemical plants specify Parker Hannifin fluid systems for pre-tested subassembly delivery.
- Chemical Processing:Corrosion-resistant connectors for aggressive acid, base, and solvent service. REACH compliance mandates are retrofitting legacy piping in German chemical clusters with low-emission stainless alternatives.
- HVAC Systems:Climate control distribution for heating, ventilation, and air conditioning. Polypropylene fittings are expanding fastest here as metal-only requirements relax across European jurisdictions.
- Oil & Gas Transmission:High-pressure, high-integrity infrastructure for upstream and midstream hydrocarbon movement. Super-duplex stainless connectors command premium positioning in North Sea platform specifications.
Procurement volume peaks in Residential Gas Systems. Specification intensity concentrates in Chemical Processing.
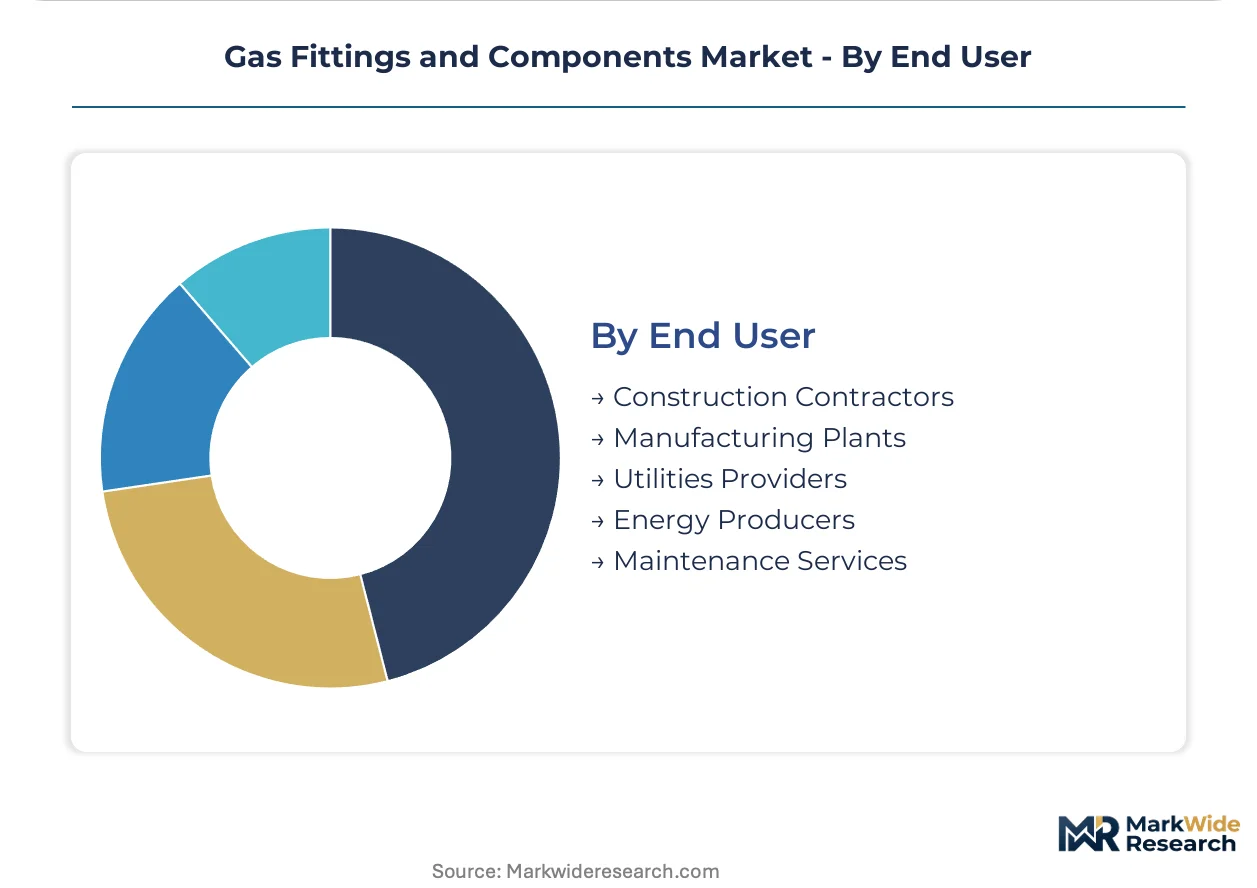
End User:
Supply chain access separates integrated fluid-systems buyers from component-level procurement.
- Construction Contractors:Project-based buyers prioritizing code compliance and installation speed over long-term durability. These stakeholders drive plastic fitting adoption in residential and light commercial segments.
- Manufacturing Plants:Continuous-process operators requiring predictive maintenance and minimal unplanned downtime. German automotive manufacturers source pre-tested subassemblies from single-source fluid systems partners.
- Utilities Providers:Regulated infrastructure owners with corrosion-resistance mandates and extended asset-life requirements. These buyers are expanding stainless steel procurement for network replacement programs.
- Energy Producers:Oil, gas, and power generators operating in high-pressure, high-temperature, or corrosive environments. North Sea platform operators specify super-duplex connectors for hydrogen sulfide exposure.
- Maintenance Services:Aftermarket repair and replacement specialists requiring rapid availability of standardized components. These buyers consolidate vendor relationships around distributors with deep inventory positions.
Framework agreement concentration is highest among Manufacturing Plants. Spot procurement dominance persists with Construction Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The gas fittings industry traces its modern scale to German industrialization, where precision machining for chemical process piping established specification-grade manufacturing standards that spread through European supply chains.
Germany
Ludwigshafen and Leverkusen chemical processing clusters drive specification-grade stainless steel fitting volumes for corrosion-resistant infrastructure. REACH compliance mandates are retrofitting legacy piping systems with low-emission connector designs. Bavarian automotive plants source pre-tested fluid system subassemblies from integrated suppliers.
United States
Gulf Coast petrochemical corridors and Permian Basin midstream operators specify high-pressure connectors for natural gas and hydrogen blending pilot programs. EPA methane-emission protocols are tightening procurement standards for leak-critical assemblies. Houston-area engineering-procurement-construction firms dominate framework agreement concentration for offshore platform specifications.
Netherlands
Rotterdam port industrial zones and North Sea platform supply bases anchor demand for super-duplex stainless connectors in hydrogen sulfide service. EU F-Gas Regulation leakage-rate thresholds are accelerating certification of dual-certified hydrogen-compatible fittings. Dutch distribution network operators are sourcing 700-bar rated assemblies for hydrogen blending trials.
France
Auvergne-Rhône-Alpes chemical manufacturing and Paris Basin agricultural biogas digesters create parallel demand streams for corrosion-resistant brass and stainless assemblies. ECHA material-safety thresholds are reshaping specification patterns for farm-scale methane capture installations. Lyon-area pharmaceutical manufacturers specify ultra-high-purity compression fittings for analytical instrumentation.
United Kingdom
Aberdeen offshore oil and gas service bases and Teesside chemical processing clusters sustain premium demand for pressure-rated subsea manifolds. Health and Safety Executive pressure-equipment directives align with EU standards post-Brexit, maintaining certification continuity. North Sea platform operators are specifying super-duplex connectors for hydrogen sulfide and chloride exposure.
Gas Fittings and Components Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification and pressure-rating tiers, with specification-grade stainless steel suppliers commanding wider spreads than brass residential contractors. The vendor base stratifies between integrated fluid-systems providers delivering pre-tested subassemblies and component-level fabricators serving spot procurement channels. Three archetypes dominate: precision-engineered specialists, grooved mechanical joining system providers, and diversified industrial conglomerates with fluid power portfolios. Competitive moves concentrate on strategic partnerships for hydrogen infrastructure certification and geographic expansion through distributor network consolidation.
Among precision-engineered specialists, Swagelok exemplifies the premium-tier positioning built on dual-ferrule sealing architecture for leak-critical applications. Parker Hannifin anchors the diversified industrial archetype with integrated fluid systems capabilities spanning specification-grade process piping. Victaulic occupies the mechanical joining segment with grooved coupling systems that have displaced traditional threaded assemblies in large-diameter commercial installations.
| Leading Market Players |
|---|
| Parker Hannifin |
| Swagelok |
| Victaulic |
| Bonney Forge |
| Crane Co. |
| Tylok International |
| Assure Parts |
| Regency Gas Hoses |
| Dormont |
| Others |
Supply & Pricing Matrix
REACH compliance mandates across German chemical processing clusters are forcing specification-grade buyers toward low-emission stainless steel fittings, compelling suppliers to absorb nickel feedstock volatility and recalibrate pricing models around material certification tiers rather than volume scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates super-duplex stainless connectors for North Sea platforms from commodity brass residential assemblies and polypropylene HVAC alternatives. Price differentiation hinges on pressure-equipment certification grade and corrosion-resistance specification, with CE-marked hydrogen-compatible fittings commanding widest spreads. Cost compression in standard-pressure carbon steel tiers is intensifying because building code relaxations accelerate plastic substitution. Construction contractors exhibit highest price sensitivity, while Dutch hydrogen pipeline operators prioritize performance over unit cost.
Supply Chain Analysis
Domestic-content requirements in EU pressure-equipment directives are reshaping sourcing patterns, favoring Northern Italian and Southwest German forging capacity over Asian alternatives. Closed-die forging for high-pressure assemblies concentrates in Germany, Italy, and France, with nickel and chromium feedstock drawing from South African and Indonesian mining operations. Single-source vulnerability in specialized forging creates structural risk for specification-grade procurement. Distribution runs through engineering-procurement-construction firms in the Netherlands and distributor networks serving maintenance services across Belgium and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as hydrogen infrastructure readiness and EU F-Gas leakage mandates shift procurement toward dual-certified, premium-grade connector designs.
For Market Incumbents: Anticipate displacement of traditional NPT-threaded assemblies by grooved mechanical joining systems in commercial building applications. Defend specification-grade positioning through backward integration into super-duplex stainless forging capacity in Southwest Germany. Prioritize ISO 19880-3 hydrogen compatibility certification ahead of procurement mandate hardening. For New Entrants and Emerging Players: E-commerce distribution channels targeting aftermarket maintenance services offer lowest barrier to entry, bypassing entrenched EPC framework agreements. Agricultural biogas digester installations in France present underdefended white space with corrosion-resistant brass demand. Target spot procurement channels through inventory-heavy distributor partnerships rather than direct specification battles. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-engineered specialists holding dual-ferrule sealing patents and hydrogen certification readiness. Five-to-ten-year viability favors vendors with integrated fluid-systems capabilities serving pharmaceutical and semiconductor gas delivery. Watch for Netherlands hydrogen blending trial expansion as inflection signal for 700-bar rated fitting demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Compatibility Certification | ISO 19880-3 validation secures access to Dutch and German hydrogen blending procurement channels. |
| Backward Integration into Forging | Captive super-duplex stainless capacity insulates margin pools from London Metal Exchange nickel volatility. |
| Pre-tested Subassembly Delivery | Integrated fluid-systems partnerships with German automotive plants reduce installation timeline risk. |
| Plastic Fitting Portfolio Expansion | Polypropylene adoption in Belgian residential construction captures building code relaxation upside. |
| Orbital Welding Training Pipeline | Certified technician scarcity in high-purity systems creates service revenue attachment opportunity. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and procurement leads at German chemical processing clusters, maintenance directors at North Sea platform operators, and distributor channel partners across the Netherlands — were reconciled against customs and trade data, pressure-equipment directive filings, and SEC disclosures from listed industrial conglomerates. Bottom-up fitting volume estimates by material grade and application were cross-validated through top-down infrastructure spending analysis across European hydrogen pilot programs.
Historical shipment patterns were cross-referenced against expert panel assessments of REACH compliance retrofit timelines and hydrogen infrastructure buildout acceleration. The analytical framework segments by product type, material grade, pressure rating tier, end-use industry, and regional regulatory cluster across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating nickel price volatility scenarios and specification-grade buyer consolidation trends.
The model assumes a particular technology adoption path; alternative pathways for compression-type dual-ferrule sealing architecture would alter the outlook if flare or face-seal designs regain specification share. Forecasts reflect documented assumptions regarding EU F-Gas enforcement timing and hydrogen blending regulatory clarity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
Cryogenic Pipes Market
Pipes and Tubes
Industrial Tubes Market
Pipes and Tubes
Metal Pipe Market
Pipes and Tubes
Steel Roll-On Tube Market
Pipes and Tubes
India Process Piping Market
Pipes and Tubes
Saw Pipes Market
Pipes and Tubes
Compressed Air Pipe Market
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
Plastic Pipes and Fittings Market
Pipes and Tubes
Coiled Tubing Manufacturing Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
Steel Pipes and Tubes Market
Pipes and Tubes
FEP Tubing Products Market