
 Couplings Market | 2026-2036
Couplings Market Size, Share, and Industry Trends Forecast 2026-2036
Couplings Market Analysis
Oil and gas pipeline infrastructure is expanding its share of high-performance coupling procurement, while traditional manufacturing demand stabilizes. Siemens AG leverages its electrification portfolio to cross-sell integrated drive-coupling systems across energy projects. SKF Group anchors its position through bearing-coupling bundling that reduces client procurement complexity. KTR Systems GmbH specializes in torsionally flexible designs that dominate wind turbine drivetrain specifications.
Couplings are mechanical devices that connect rotating shafts to transmit torque while accommodating misalignment, with flexible variants typically employing elastomeric elements or metallic membranes rated for angular offsets up to several degrees and torque ranges spanning sub-newton-meter precision instruments to multi-meganewton-meter marine propulsion systems. Their primary industrial purpose centers on protecting downstream equipment from vibration, shock loading, and thermal expansion while maintaining rotational synchronization. Flexible couplings lead product type demand due to their misalignment tolerance and maintenance accessibility in continuous-process industries. Steel material grades command the strongest margin pools where fatigue resistance and high-temperature performance justify alloy premiums. Aerospace end-user specifications drive the most stringent certification requirements and longest qualification cycles.
ISO 10494 governs turbine coupling testing protocols, while API 671 and API 610 establish petroleum and petrochemical sector requirements for special-purpose and pump couplings respectively, with compliance mandatory for upstream project qualification. The EPA enforces emissions-related equipment reliability standards that indirectly mandate coupling redundancy in fugitive-methane-critical rotating equipment. Stakeholders must monitor evolving carbon-border adjustment mechanisms and their cascading effect on steel sourcing costs and regional manufacturing competitiveness.
Market Dynamics
API 671 and ISO 10494 certification requirements are compressing supplier qualification timelines while simultaneously extending procurement cycles for critical rotating equipment in oil and gas infrastructure.
Growth Catalysts
- API 671 Compliance Mandates:Petroleum sector operators in the US Gulf Coast region require special-purpose couplings meeting stringent fatigue and material traceability standards for upstream project qualification.
- Germany:Precision manufacturing clusters around Stuttgart and Munich anchor premium coupling procurement from automotive OEM supply chains demanding torsionally flexible designs.
- Wind Turbine Drivetrain Scaling:Multi-megawatt offshore installations deploy high-torque flexible couplings rated for angular misalignment tolerance exceeding three degrees under variable loading.
Market Restraints
- Alloy Steel Price Volatility:Nickel and chromium input costs fluctuate with energy-intensive smelting operations concentrated in Chinese and Indonesian supply basins.
- Specialized Foundry Concentration:Large-diameter steel coupling forging capacity clusters in select German, Japanese, and South Korean facilities with limited geographic redundancy.
- Elastomer Temperature Ceiling:Polyurethane and rubber flexible elements degrade above 120°C, restricting deployment in high-temperature process pump applications.
Strategic Opportunities
- India:Domestic wind energy capacity additions under CEA grid integration mandates create demand for localized coupling assembly and testing infrastructure.
- Digital Twin Integration:Condition monitoring sensors embedded in coupling hubs enable predictive maintenance contracts unifying hardware supply with SaaS analytics.
- EU Carbon Border Adjustment Mechanism:CBAM phase-in creates first-mover advantage for European mills with verified low-emission steel production and ISO 14064-certified traceability.
Industry Challenges
- Metallurgical Specialist Shortage:Fatigue analysis and non-destructive testing expertise for high-cycle turbine applications concentrates among aging workforce cohorts in mature industrial economies.
- Legacy System Integration:Retrofit projects in brownfield petrochemical facilities require custom adapter designs accommodating obsolete shaft configurations without full line shutdown.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Couplings Market |
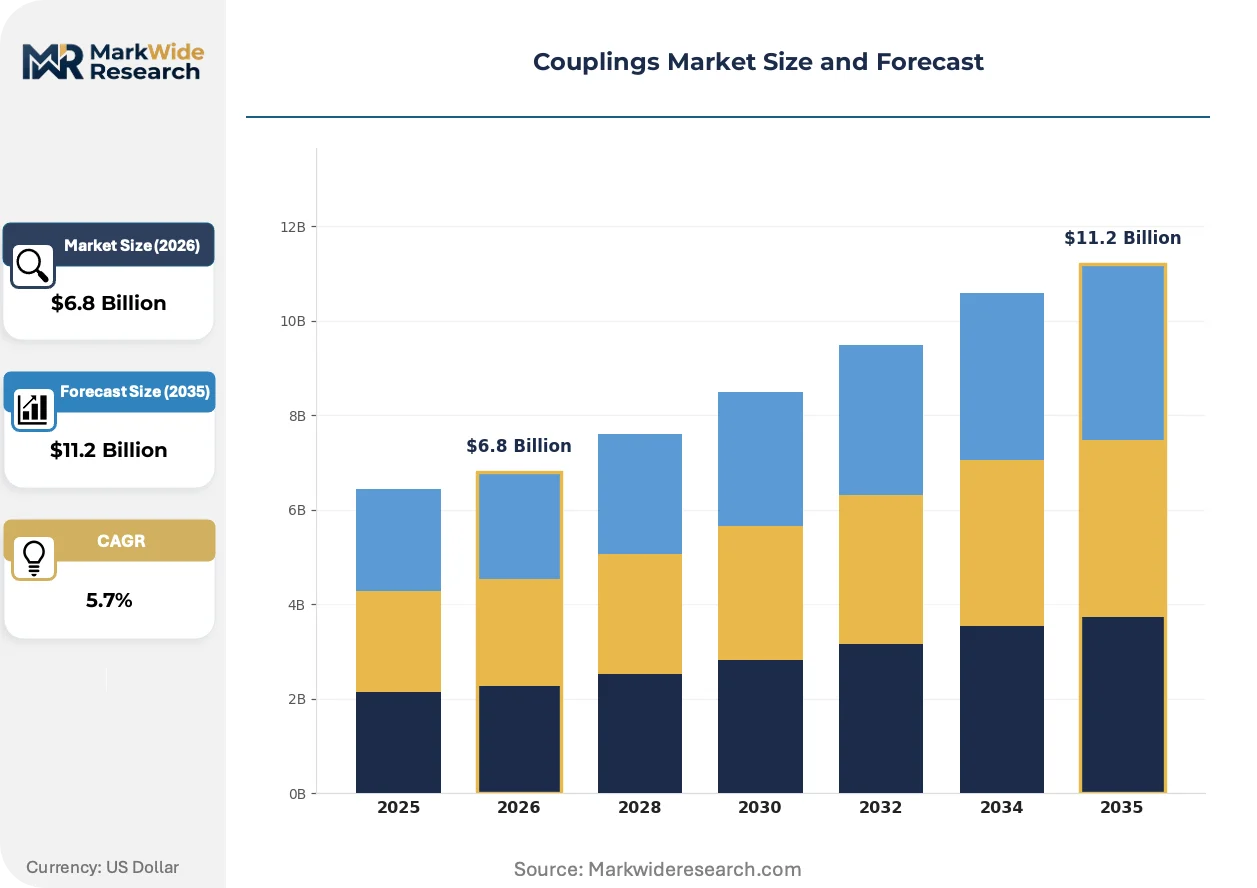
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Couplings, Flexible Couplings, Fluid Couplings, Membrane Couplings Material: Steel, Aluminum, Plastic, Composite End User: Manufacturing, Oil & Gas, Automotive, Aerospace Application: Industrial Machinery, Pumps, Conveyors, Generators |
| Companies Covered | Altra Industrial Motion Corp., Siemens AG, SKF Group, ABB Ltd, Rexnord Corporation, Voith GmbH & Co. KGaA, John Crane, KTR Systems GmbH, Tsubakimoto Chain Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Couplings Market Emerging Trajectories
Material science advances and embedded sensor architectures are compressing the traditional separation between mechanical power transmission and predictive maintenance ecosystems.
Membrane disc couplings fabricated from Inconel or maraging steel alloys are unifying high-torque capacity with zero-backlash precision in multi-axis machine tool spindles. Japanese and German machine builders specify these for five-axis machining centers where thermal expansion compensation must maintain sub-arcminute angular positioning. The technology is unifying formerly separate coupling and precision motion control supplier categories into integrated drivetrain partnerships.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are phasing out PTFE-based bearing coatings historically used in chemical process couplings. European pump OEMs reformulate dry-running seal support systems with ceramic or graphite alternatives. Specialty chemical facilities in Germany and the Netherlands face accelerated retooling timelines to maintain CE marking compliance for rotating equipment exports.
Consolidated procurement frameworks now bundle coupling specification with adjacent rotating equipment purchases. Oil and gas operators in the US Permian Basin negotiate master service agreements covering pumps, motors, and couplings under unified warranty terms. Channel intermediaries with testing and field service capabilities capture margin pools previously distributed across separate mechanical and electrical distributors.
Couplings Market Segmentation
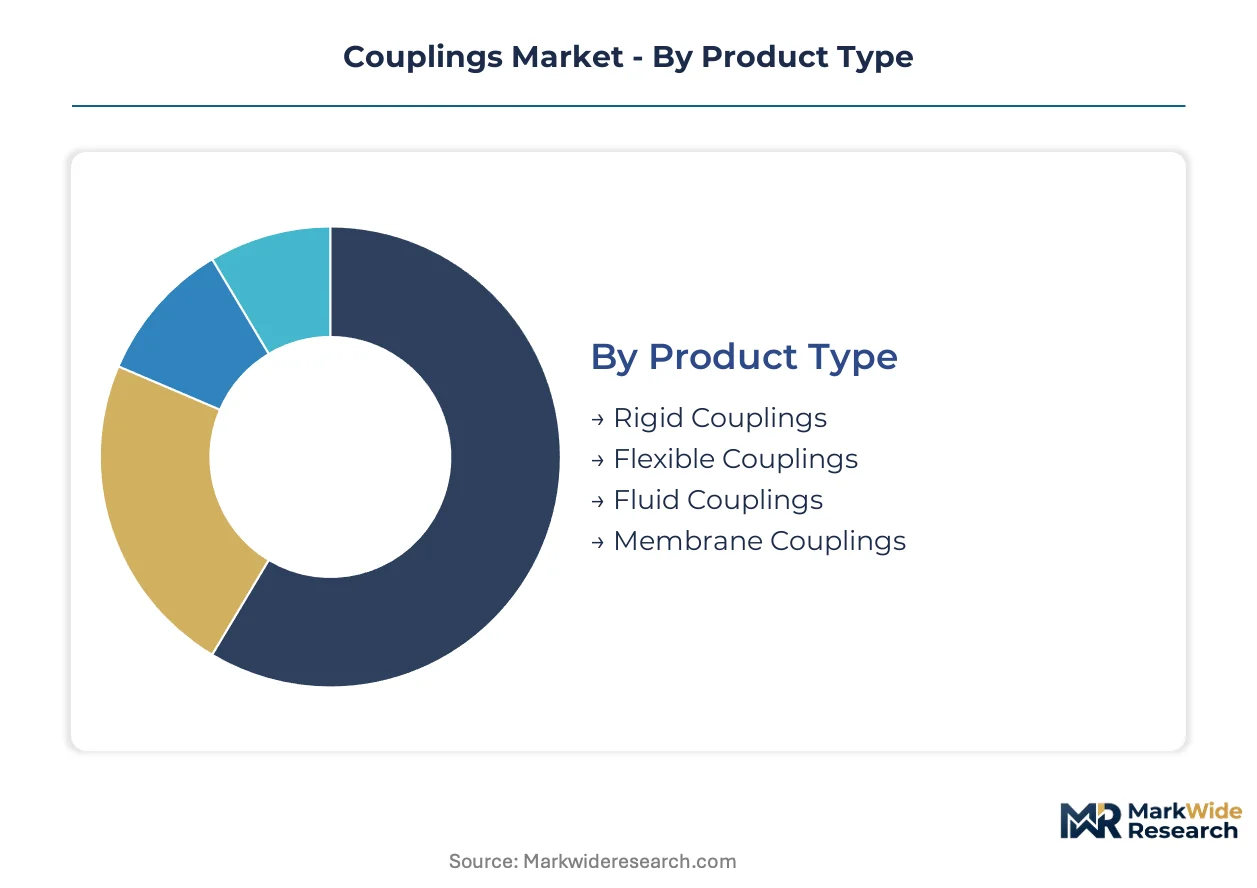
Coupling selection dictates maintenance intervals, failure modes, and total lifecycle cost across rotating equipment fleets. Procurement teams segment specifications by torque rating, misalignment tolerance, and environmental exposure rather than unit price alone. Each segmentation axis reveals distinct margin structures and supplier qualification barriers.
Product Type:
Capital intensity escalates sharply with torque capacity and precision requirements, with specialized metallic designs demanding dedicated forging and heat-treatment infrastructure.
- Flexible Couplings:Elastomeric or metallic elements accommodate angular misalignment up to several degrees while damping torsional vibration. Demand concentrates in German automotive OEM supply chains and US Permian Basin pump installations where thermal expansion and foundation settling create alignment drift. API 671 fatigue certification extends procurement cycles but locks in premium pricing for qualified suppliers.
- Membrane Couplings:Disc packs fabricated from Inconel or maraging steel deliver zero-backlash torque transmission for turbine and precision spindle applications. Japanese machine tool builders and European offshore wind developers specify these for multi-megawatt drivetrains where maintenance access is prohibitively expensive. The segment requires vacuum heat-treatment and non-destructive testing capabilities that concentrate among aging specialist foundries.
- Rigid Couplings:Sleeve and clamp designs provide fixed shaft connection for precisely aligned systems in HVAC and light industrial machinery.
- Fluid Couplings:Hydrodynamic torque converters enable soft-start acceleration for mining conveyors and marine propulsion systems.
Flexible designs absorb the bulk of installed capacity; membrane variants are expanding most quickly.
Material:
Alloy selection determines fatigue life, temperature ceiling, and corrosion resistance in process environments.
- Steel:Carbon and alloy grades span from general-purpose C45 to NiCrMo turbine specifications requiring full metallurgical traceability. German precision manufacturing clusters and Japanese shipyards anchor demand for vacuum-degassed forgings with ultrasonic certification. REACH and impending EU Carbon Border Adjustment Mechanism compliance costs favor mills with ISO 14064-verified low-emission production.
- Aluminum:Die-cast and machined housings serve aerospace auxiliary drives and automotive lightweighting initiatives where mass reduction offsets lower stiffness. Boeing and Airbus Tier 1 suppliers specify 7075-T6 and 2024-T4 grades with lot-controlled mechanical testing.
- Plastic:Glass-reinforced polyamide and PEEK accommodate chemical exposure and electrical isolation in analytical instrumentation and food processing.
- Composite:Carbon fiber-epoxy shafts with metallic hubs emerge in racing drivetrains and specialized test equipment.
Steel dominates revenue contribution; aluminum applications are climbing the fastest.
End User:
Specification authority resides with rotating equipment OEMs in capital-intensive sectors, while aftermarket procurement flows through maintenance contractors.
- Oil & Gas:Upstream operators mandate API 671 and ISO 10494 compliance for special-purpose couplings in gas compression and power recovery trains. US Gulf Coast LNG projects and Middle Eastern offshore developments drive qualification demand for full material traceability and fatigue-rated designs.
- Aerospace:Airframe and engine manufacturers impose the longest qualification cycles and most stringent non-destructive testing protocols. FAA and EASA certification requirements for critical flight control and propulsion systems limit qualified supplier pools to established specialty houses.
- Manufacturing:General industrial machinery procurement emphasizes interchangeability and rapid delivery over custom engineering.
- Automotive:Tier 1 drivetrain suppliers specify torsionally flexible designs for engine-test stands and hybrid transmission validation.
Oil & Gas absorbs the bulk of high-value procurement; aerospace applications command the steepest expansion trajectory.
Application:
Operating duty cycle and accessibility determine whether standard catalog designs suffice or custom engineering becomes economical.
- Pumps:ANSI and API process pump specifications create standardized coupling envelopes across petrochemical and water treatment installations. German pump OEMs bundle coupling selection with rotating equipment packages to optimize hydraulic and mechanical resonance matching.
- Generators:Synchronous and induction machine couplings must accommodate thermal expansion differentials between turbine and generator shafts. Grid-scale wind and gas turbine projects in India under CEA integration mandates are localizing assembly and testing infrastructure.
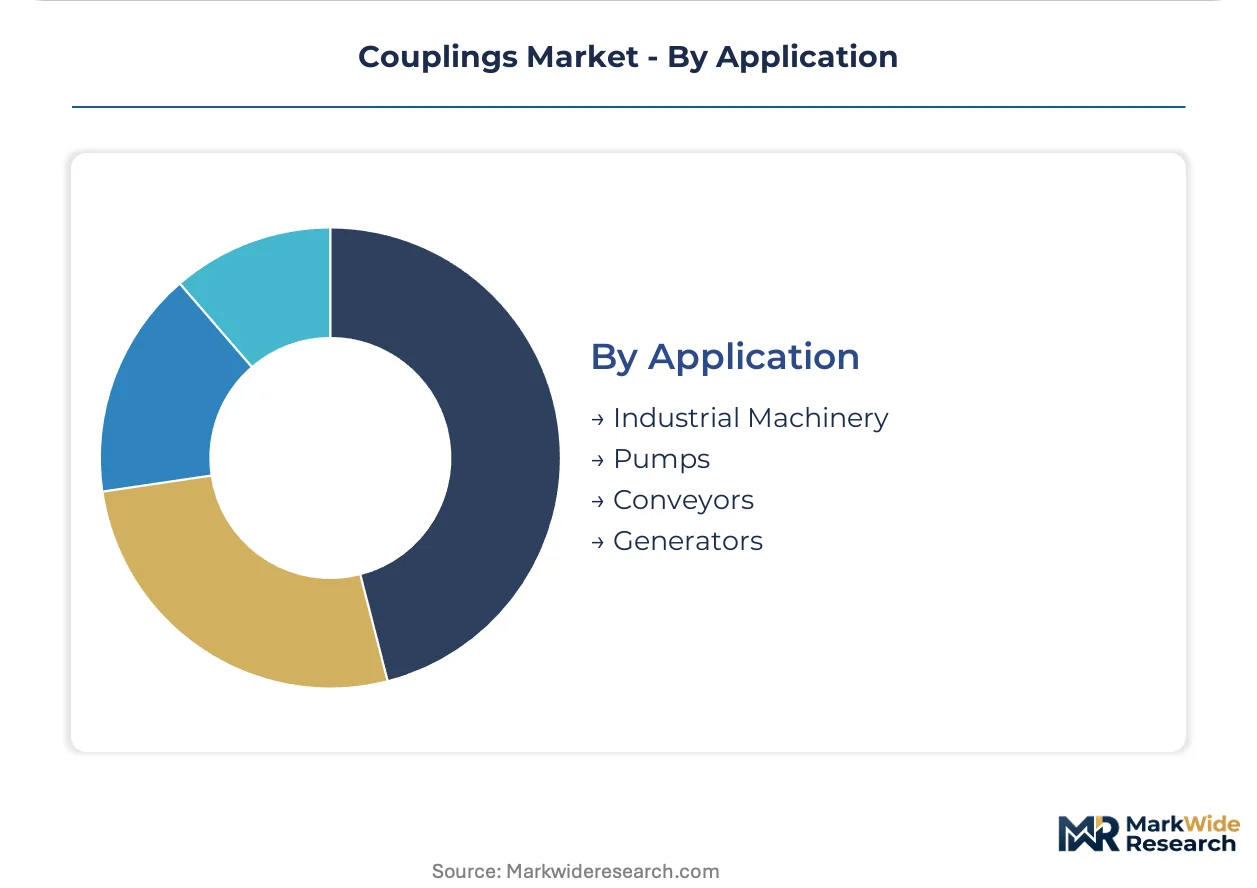
- Industrial Machinery:General-purpose flexible couplings serve compressors, mixers, and machine tools with moderate torque and alignment precision.
- Conveyors:Bulk material handling systems prioritize overload protection through shear-pin or fluid coupling designs.
Pump applications anchor established revenue; generator couplings are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coupling production concentrates in German, Japanese, and South Korean forging facilities, while consumption spreads across oil and gas basins, automotive manufacturing corridors, and renewable energy installations worldwide. This geographic split creates freight cost premiums for large-diameter steel forgings and qualification bottlenecks for project-critical turbine specifications.
United States
Permian Basin operators and Gulf Coast LNG developers drive API 671 special-purpose coupling procurement with mandatory fatigue certification and full material traceability. EPA emissions reliability standards indirectly mandate coupling redundancy in fugitive-methane-critical rotating equipment. Houston anchors the largest concentration of oilfield service procurement teams specifying integrated pump-motor-coupling packages.
Germany
Automotive OEM supply chains around Stuttgart and Munich demand torsionally flexible designs with sub-arcminute precision for engine test stands and hybrid transmission validation. REACH Annex XVII restrictions on PFAS-bearing coatings accelerate reformulation of dry-running seal support systems in chemical process applications. Ruhr Valley specialty foundries maintain vacuum heat-treatment capacity for NiCrMo turbine specifications.
China
Domestic wind turbine OEMs scale multi-megawatt drivetrain assembly under MIIT industrial upgrading mandates, creating localized demand for high-torque flexible coupling testing infrastructure. Dual carbon goals tighten steel sourcing requirements for grid-scale renewable projects. Yangtze River Delta precision manufacturing clusters import German and Japanese membrane coupling technology for five-axis machine tool integration.
India
CEA grid integration mandates for wind energy capacity additions drive generator coupling localization in Gujarat and Tamil Nadu assembly facilities. BIS certification requirements for rotating equipment create qualification barriers for imported forged components. Domestic pump OEMs in Pune and Coimbatore bundle coupling selection with ANSI and API process equipment packages.
Japan
Machine tool builders specify Inconel membrane couplings for thermal expansion compensation in five-axis machining centers requiring sub-arcminute angular positioning. METI industrial technology roadmaps prioritize predictive maintenance sensor integration in mechanical power transmission components. Nagoya and Osaka manufacturing corridors anchor demand for zero-backlash precision coupling designs.
Couplings Market Vendor Landscape
Top-tier vendors anchor premium-tier certification and qualification services, while mid-scale specialists occupy regional fabrication and aftermarket maintenance niches. The vendor base stratifies across three tiers: integrated drivetrain suppliers with bearing-coupling bundling capabilities, standalone coupling specialists with dedicated forging and heat-treatment infrastructure, and regional distributors with field service and testing competencies. Dominant competitive moves include backward integration into alloy steel forging capacity and strategic partnerships embedding condition monitoring sensors in coupling hubs.
Within the integrated industrial technology tier, Siemens AG and ABB Ltd exemplify cross-selling architectures that unify electrification portfolios with mechanical power transmission components. SKF Group anchors the bearing-coupling bundling archetype, reducing procurement complexity for rotating equipment fleets. KTR Systems GmbH occupies a specialist position in torsionally flexible designs, with its German GmbH structure indicating precision engineering lineage.
| Leading Market Players |
|---|
| Altra Industrial Motion Corp. |
| Siemens AG |
| SKF Group |
| ABB Ltd |
| Rexnord Corporation |
| Voith GmbH & Co. KGaA |
| John Crane |
| KTR Systems GmbH |
| Tsubakimoto Chain Co. |
| Others |
Supply Flow & Price Mechanics
Nickel and chromium alloy surcharges flow from Indonesian smelters through German forging mills to API 671-certified coupling tiers, with vacuum-degassed steel premiums widening spreads between fatigue-rated turbine specifications and standard pump grades. Buyers in the US Gulf Coast LNG sector absorb alloy cost passthroughs while automotive OEMs in Stuttgart negotiate volume lock-ins against spot volatility.
Pricing Analysis
Margin tightening in premium turbine couplings reflects vacuum heat-treatment capacity scarcity at Ruhr Valley specialty foundries. Three-tier pricing structure across API 671-certified, ISO 10494-compliant, and standard industrial grades segments buyers by qualification burden. Cost-down pressure on economy-tier flexible couplings accelerates as Chinese wind OEMs localize assembly under MIIT mandates. Aftermarket procurement teams at Permian Basin operators prove least price-sensitive, prioritizing material traceability over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from US LNG developers and European wind farm EPCs force qualification of second-source forging capacity beyond dominant German, Japanese, and South Korean suppliers. NiCrMo alloy feedstock draws from Chinese and Indonesian nickel basins, with Inconel membrane disc blanks resting on aerospace-certified mill rolls. Single-source vulnerability concentrates in large-diameter vacuum heat-treatment chambers above two meters. Distribution runs through rotating equipment OEM bundling agreements and oilfield service master service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized foundry capacity for NiCrMo turbine specifications operates at effective saturation, propping pricing power for qualified suppliers against commoditized flexible coupling imports.
For Market Incumbents: Anchor defensive positioning through captive vacuum heat-treatment capacity additions in Germany or South Korea, insulating against foundry bottleneck risk. Deepen API 671 certification moats by embedding condition monitoring sensors in coupling hubs, converting hardware sales into predictive maintenance SaaS contracts. Defend against Chinese wind OEM vertical integration by locking Indian CEA-mandated projects into long-term service agreements. For New Entrants and Emerging Players: Launch via aftermarket refurbishment and field service networks in India's Gujarat and Tamil Nadu wind corridors, bypassing capital-intensive forging barriers. Target underqualified ANSI pump coupling segments in North American water treatment utilities where API certification is not mandated. Penetrate through digital twin integration partnerships with industrial IoT platforms, offering predictive analytics as the primary value anchor. For Investors and Strategic Acquirers: CEA grid integration mandate acceleration in India is the leading indicator that localized coupling assembly infrastructure will command scarcity premiums over imported forgings. Five-to-ten year viability favors acquiring mid-scale specialists with existing BIS certification and heat-treatment relationships rather than greenfield forging investments. Watch for MEMS sensor cost curves crossing thresholds that enable mass embedding in standard industrial couplings as the inflection signal for platform consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Heat-Treatment | Captures margin pools concentrated in aging Ruhr Valley specialist foundries. |
| API 671 Certification Investment | Locks in premium pricing from US Gulf Coast LNG project procurement teams. |
| Condition Monitoring Sensor Embedding | Unifies hardware supply with SaaS predictive maintenance contracts for rotating equipment fleets. |
| Indian Assembly Localization | Positions for CEA-mandated wind energy capacity additions in Gujarat and Tamil Nadu. |
| REACH-Compliant Coating Reformulation | Maintains CE marking access as Annex XVII restrictions phase out PTFE-bearing formulations. |
Methodological Framework
Independent corroboration across API 671 certification databases, ISO 10494 turbine testing records, and REACH Annex XVII regulatory filings underwrites the qualitative findings on material compliance trends. Primary interviews with maintenance directors at Permian Basin operators, procurement leads at German automotive OEMs, and aftermarket service heads at Indian wind farm developers combined with secondary validation from customs trade data, SEC filings of listed industrial technology suppliers, and CEA grid integration mandate documentation. Bottom-up coupling unit demand estimates and top-down rotating equipment capex allocations were cross-referenced for triangulation.
Comparable-period anchoring used historical API 671 procurement cycle data and wind turbine drivetrain installation records to calibrate the projection horizon. The analytical framework modeled demand across product type, material grade, end-use sector, and application duty cycle dimensions. CAGRs were derived from segment-level growth rate reconciliation against macro industrial production indices. Forecast inputs incorporated MIIT industrial upgrading mandates, CEA localization requirements, and evolving EU Carbon Border Adjustment Mechanism compliance cost assumptions.
The model assumes a particular technology adoption path for embedded sensor architectures; alternative pathways for wireless vibration monitoring would alter the outlook for predictive maintenance contract penetration. Forecasts reflect assumptions on alloy price stabilization and foundry capacity expansion timelines. Deviation in nickel supply disruption frequency or API specification revision timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Heat-Insulation Boards for Industrial Equipment Market
Industrial Materials
Crimped Wire Brushes Market
Industrial Materials
Plastic Molds Market
Industrial Materials
Lip Seals Market
Industrial Materials
Static Mixer Market
Industrial Materials
Cork Material Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Industrial Brushes Market
Industrial Materials
Mineral Wool Market
Industrial Materials
Magnet Rings Market
Industrial Materials
US Industrial Fasteners Market
Industrial Materials
Global Melamine Faced Chipboard (MFC) Market
Industrial Materials
Hose Reinforcement Wire Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
Global Medical Plastics Extrusion Market
Industrial Materials
Vinyl Extrusion Equipment Market