
 Aerospace Insurance Market | 2026-2036
Aerospace Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Insurance Market Intelligence
Enhanced hull-value tiers for next-generation narrow-body fleets is collapsing legacy pricing benchmarks across commercial aviation lines. Munich Re Specialty leverages its global facultative network to sustain leadership in wide-body hull placements. AXA XL anchors its competitive stance through integrated airline risk engineering services that span fleet valuation and loss prevention. Global Aerospace competes aggressively in the general aviation segment, where premium granularity rewards specialized underwriting expertise.
Aerospace insurance constitutes risk transfer instruments designed to indemnify physical damage to aircraft hulls, liability exposure from passenger and third-party claims, and product defects in aviation manufacturing, with coverage limits calibrated to airframe replacement values that routinely exceed $100 million per unit and liability towers structured across multiple excess layers. Aviation hull coverage dominates premium generation due to escalating replacement costs for composite-intensive airframes, while passenger liability lines experience structural pressure from jurisdictional claim inflation in multiple legal venues. Product liability segments serve airframe and engine OEMs against latent defect allegations, with multi-year policy terms gaining preference among manufacturers seeking rate stability across development cycles.
The FAA mandates minimum liability thresholds under Part 205 that directly determine baseline coverage architecture for US-registered operators, while EASA's continuing airworthiness directives reshape risk profiles and corresponding premium adjustments for European fleet holders. Lloyd's of London and the International Civil Aviation Organization supply supplementary standard-setting frameworks that govern cross-border reinsurance placement and claims resolution protocols. Stakeholders must monitor evolving cyber-physical exposures from connected avionics systems as these perimeters attract limited historical loss data and compressed underwriting cycles.
Market Dynamics
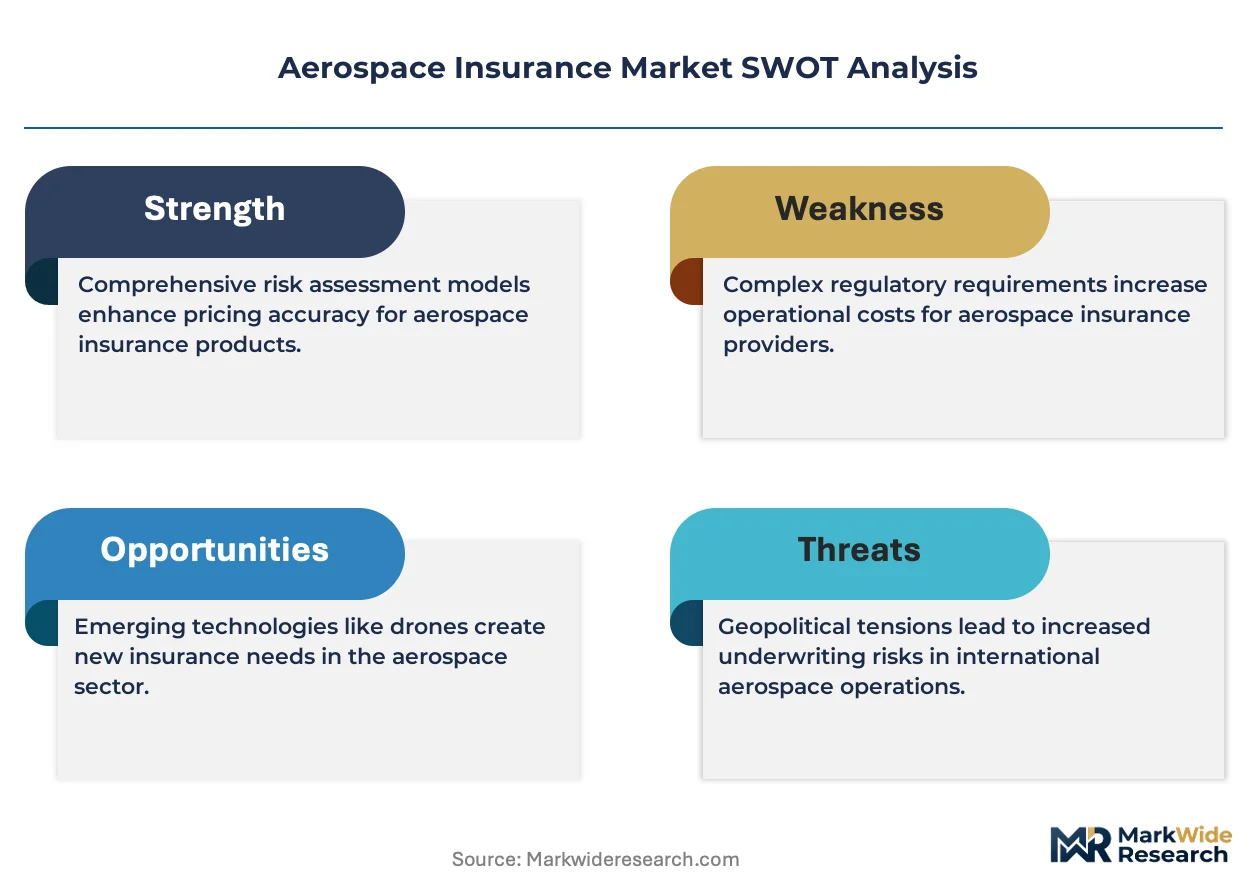
The FAA's updated Part 135 safety mandates are compressing underwriting cycles and forcing carriers to recalibrate risk models for regional operators, while composite-intensive airframes escalate hull replacement valuations beyond historical actuarial baselines.
Growth Catalysts
- Commercial Fleet Expansion:Accelerated narrow-body deliveries from Airbus and Boeing facilities are expanding insured hull values across legacy carrier and low-cost airline portfolios.
- Part 205 Liability Minimums:FAA-mandated coverage thresholds for US-registered operators are establishing baseline premium floors that sustain revenue generation across liability towers.
- Connected Avionics Penetration:Cyber-physical exposure from satellite-linked flight systems is creating demand for specialized endorsements that traditional hull policies do not address.
Market Restraints
- Titanium Supply Concentration:Russian and Chinese smelter dominance in aerospace-grade titanium sponge creates input cost volatility that ripples through airframe replacement valuations.
- Composite Repair Scarcity:Limited certified MRO capacity for carbon-fiber airframe damage extends claim resolution timelines and inflates loss adjustment expenses.
- EASA Airworthiness Directives:Continuing regulatory mandates for European fleet holders force mid-term coverage amendments that disrupt multi-year policy pricing stability.
Strategic Opportunities
- Unmanned Aerial Systems:Beyond-visual-line-of-sight commercial drone operations in US agricultural and logistics verticals remain underpenetrated by specialized aviation underwriters.
- Parametric Weather Products:Index-based coverage for hurricane and hail damage to parked aircraft eliminates claims adjustment friction for regional operators in Florida and Gulf Coast clusters.
- EU Green Deal Alignment:Sustainable aviation fuel transition incentives are creating premium discount structures for operators meeting emissions benchmarks under the bloc's regulatory framework.
Industry Challenges
- Aerospace Actuary Shortage:Specialized talent capable of modeling composite airframe degradation curves and cyber-physical loss scenarios commands compensation premiums that squeeze underwriting margin.
- Multi-Jurisdictional Claims Resolution:Passenger liability exposure spanning FAA, EASA, and ICAO regulatory zones creates coverage gap disputes that delay settlement and erode reinsurer confidence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Insurance Market |
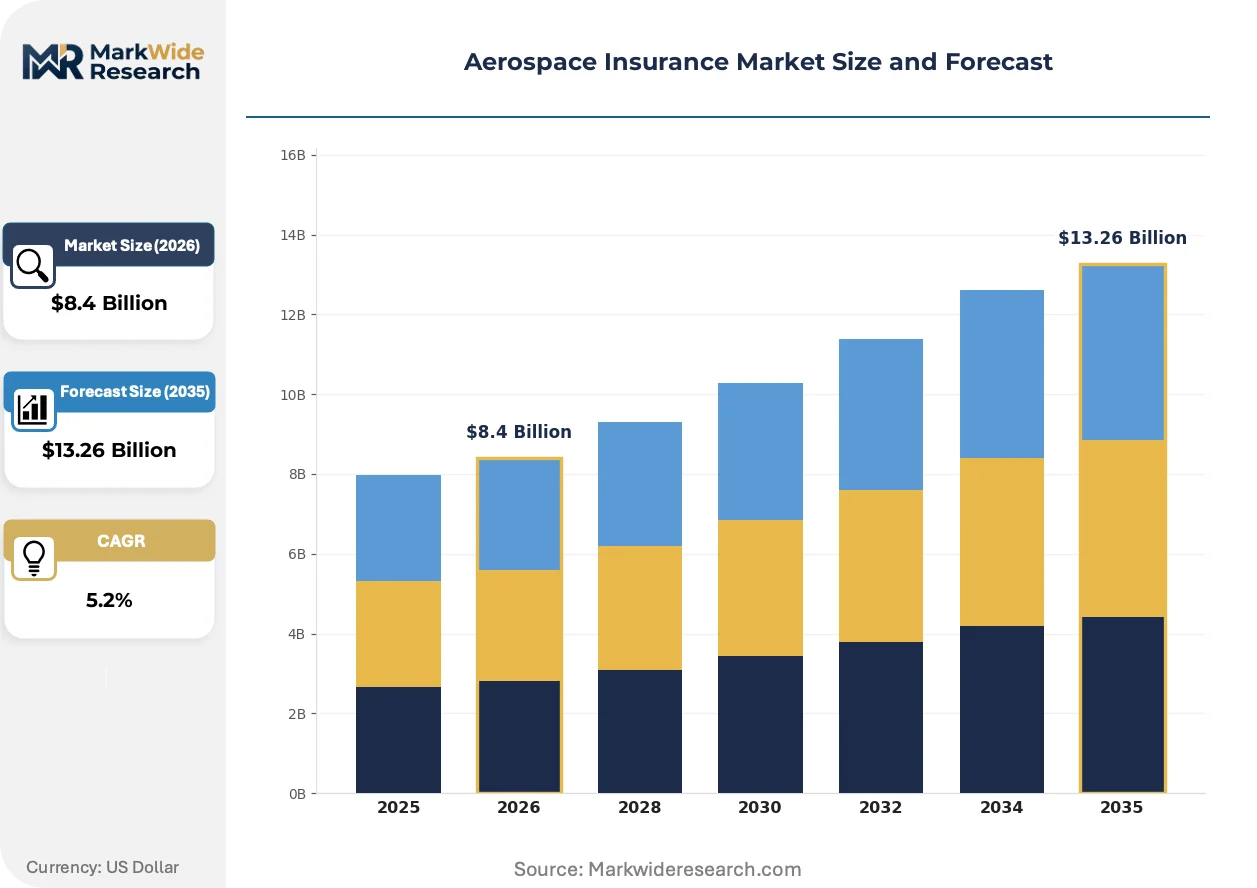
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aviation Hull, Aircraft Liability, Passenger Liability, Product Liability Coverage Type: Comprehensive, Third Party, Ground Risk, All Risks End User: Commercial Airlines, Private Operators, Cargo Carriers, Maintenance Organizations Policy Term: Short-Term, Long-Term, Annual, Multi-Year |
| Companies Covered | AXA XL, Munich Re Specialty, Global Aerospace, Tokio Marine HCC, Starr International Company, American International Group, USAIG, Allianz, Chubb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Insurance Market Strategic Shifts & Innovations
Digital twin technology and satellite telemetry are compressing the information asymmetry between underwriters and insured operators, enabling real-time risk pricing that displaces annual renewal cycles.
Parametric insurance structures are fragmenting traditional indemnity models across the general aviation segment. These instruments trigger automatic payout based on verified flight data anomalies rather than post-incident damage assessment. Fractional ownership platforms and on-demand charter operators are adopting these products fastest, drawn by immediate liquidity and eliminated claims disputes. The shift is compressing demand for conventional hull-adjusted loss settlement across light-jet and rotorcraft portfolios.
EU Green Deal aviation sustainability mandates are reshaping coverage architecture for European fleet holders. Operators demonstrating verified sustainable aviation fuel consumption receive preferential premium treatment under emerging EASA-aligned underwriting guidelines. The regulatory pressure is concentrating product development resources at Lloyd's syndicates and continental reinsurers with established carbon accounting capabilities. Narrow-body operators serving intra-European routes face the steepest compliance-driven coverage restructuring.
Carrier procurement of insurance is rotating from broker-mediated annual placement toward direct digital binding for supplemental coverage layers. Low-cost airlines with standardized fleets and centralized risk management functions are bypassing traditional intermediaries for excess liability towers. The disintermediation is most visible in the United States, where Southwest and Allegiant have established captive digital placement channels for hull deductible buy-down policies.
Aerospace Insurance Market Segmentation
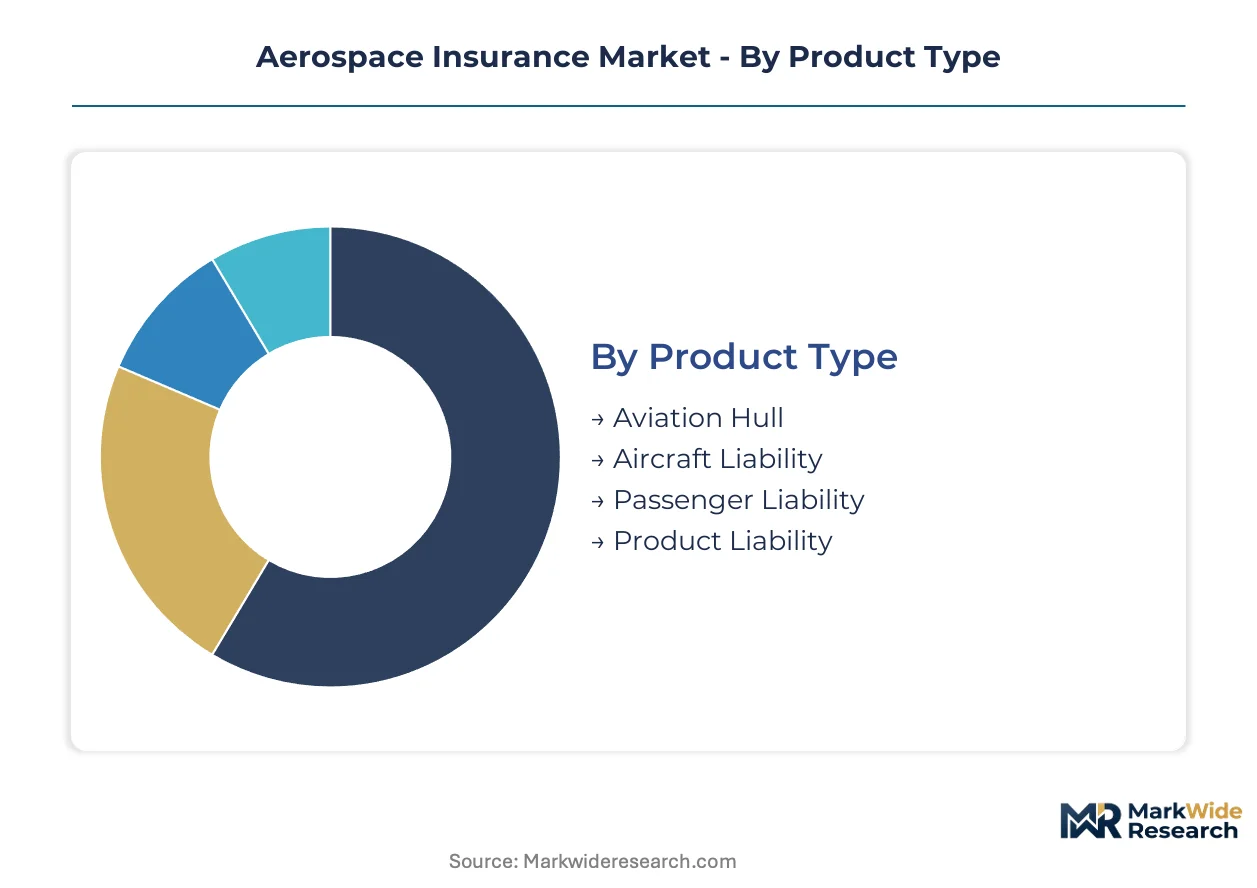
Aerospace insurance segmentation reflects distinct risk transfer architectures calibrated to airframe value tiers, operational profiles, and regulatory jurisdictions. Underwriters structure coverage limits and premium mechanics around these divisions, with hull valuations and liability towers commanding separate underwriting specializations.
Product Type:
FAA Part 205 mandates minimum liability thresholds that shape baseline coverage architecture for US-registered operators, while EASA airworthiness directives drive premium recalibration across European fleet portfolios.
- Aviation Hull:Physical damage coverage indemnifies airframe replacement costs that routinely exceed $100 million for composite-intensive narrow-bodies. Legacy carriers and low-cost airlines in the United States concentrate demand here as new aircraft deliveries accelerate fleet valuations.
- Aircraft Liability:Third-party bodily injury and property damage protection responds to ground incidents and mid-air collisions. Regional operators face tightening underwriting standards under FAA Part 135 safety mandates that compress risk assessment cycles.
- Passenger Liability:Bodily injury coverage for transported persons faces structural pressure from jurisdictional claim inflation across multiple legal venues.
- Product Liability:Latent defect protection serves airframe and engine OEMs with multi-year policy terms gaining preference among manufacturers seeking rate stability.
Aviation Hull handles the majority of throughput; Product Liability is gaining share fastest as OEMs extend coverage terms across development cycles.
Coverage Type:
Cost tier differentiation separates premium-grade comprehensive placement from stripped-down ground risk products, with hull value concentration driving the steepest premium gradients.
- Comprehensive:All-inclusive protection spanning hull physical damage, third-party liability, and passenger claims in a unified policy structure. Full-service carriers with diversified route networks anchor demand for this tier.
- Third Party:Liability-only coverage excluding hull physical damage serves operators with self-insured retention programs or captive structures.
- Ground Risk:Damage protection while aircraft is stationary, taxiing, or during maintenance operations. MRO facilities and parked fleet operators in hurricane-exposed Florida and Gulf Coast clusters concentrate demand for this segment.
- All Risks:Broad peril coverage with minimal exclusions commands premium placement for high-value wide-body fleets.
Comprehensive coverage dominates premium volume; Ground Risk is expanding most quickly as parametric weather products penetrate regional operator portfolios.
End User:
Application-specific risk profiles separate high-frequency commercial operations from sporadic private usage, with flight hour volume and route density determining underwriting approach.
- Commercial Airlines:Scheduled passenger carriers with standardized narrow-body fleets drive bulk premium generation through centralized risk management functions.
- Private Operators:Fractional ownership platforms and on-demand charter services are adopting parametric structures fastest, drawn by immediate liquidity and eliminated claims disputes.
- Cargo Carriers:Dedicated freighter operators with overnight hub operations face distinct exposure profiles from passenger airlines.
- Maintenance Organizations:MRO facilities handling composite airframe repair require specialized coverage for hangar keeper liability and defective workmanship exposure.
Commercial Airlines anchor premium volume; Private Operators show the steepest adoption curve for digital binding and parametric alternatives.
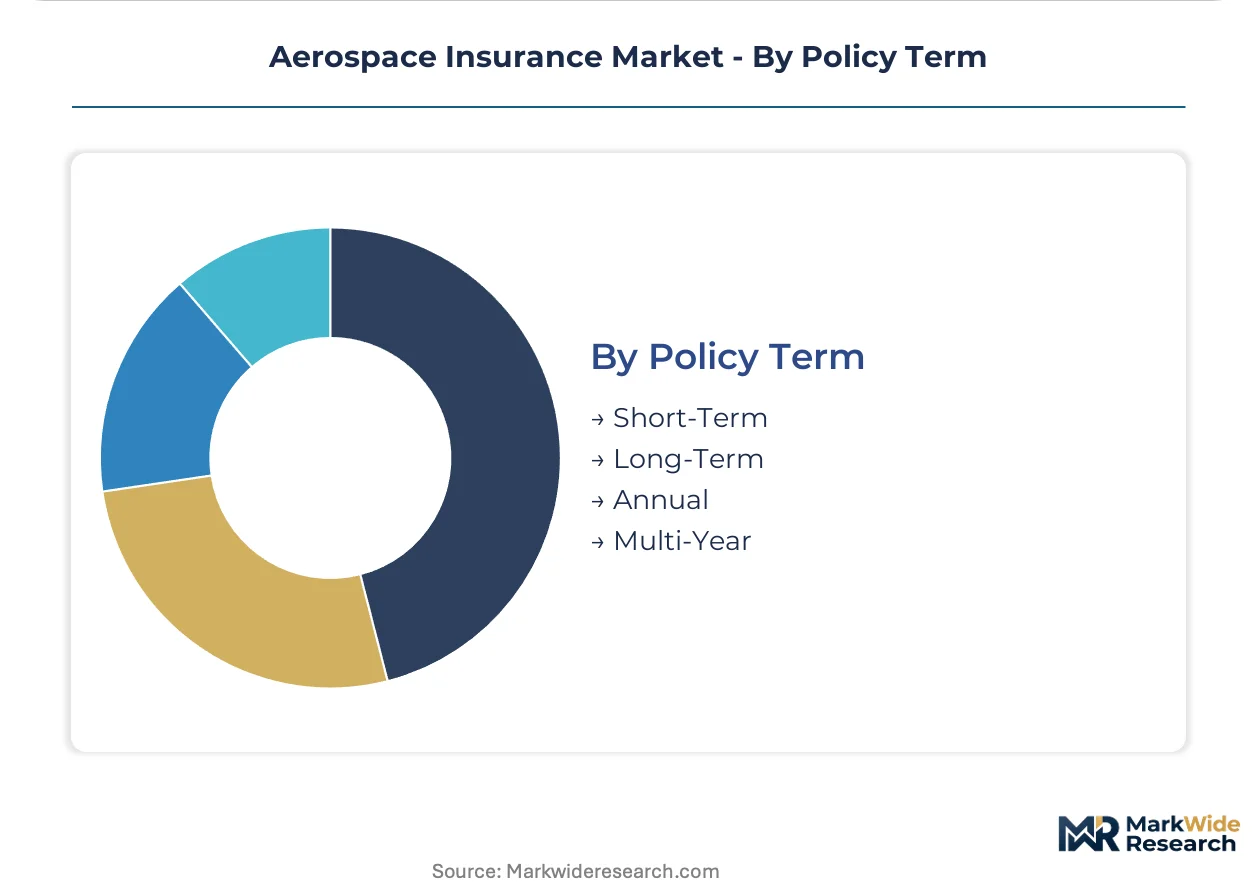
Policy Term:
Customer type and fleet maturity determine term preference, with manufacturers and legacy carriers diverging from seasonal operators on duration strategy.
- Short-Term:Seasonal coverage for agricultural aviation and airshow operators with irregular flight schedules.
- Long-Term:Multi-year placement preferred by OEMs seeking rate stability across product development cycles.
- Annual:Standard renewal cycle for commercial airlines with stable fleet compositions.
- Multi-Year:Extended terms gaining traction among operators with EASA-aligned sustainability commitments under EU Green Deal frameworks.
Annual policies handle the majority of transaction volume; Multi-Year terms are climbing the fastest as regulatory compliance extends planning horizons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balance in aerospace insurance tilts toward premium outflows from emerging fleet operators to established underwriting centers in mature aviation markets. The United States retains surplus position through Lloyd's syndicate participation and domestic carrier capacity, while Asian operators increasingly source coverage from London and European markets.
United States
Legacy carriers and low-cost airlines concentrate hull-value demand as Boeing and Airbus deliveries accelerate fleet renewal cycles. FAA Part 135 safety mandates tighten underwriting standards for regional operators, compressing risk assessment timelines. Dallas-Fort Worth and Atlanta anchor commercial aviation clusters where centralized risk management functions drive bulk premium generation.
Germany
Lufthansa Group's fleet standardization creates concentrated demand for comprehensive coverage architectures across narrow-body and wide-body portfolios. EASA airworthiness directives force mid-term policy amendments that disrupt multi-year pricing stability. Hamburg's aerospace manufacturing corridor sustains product liability placement from airframe and engine OEMs seeking rate stability.
United Kingdom
Lloyd's of London syndicates dominate global facultative reinsurance placement for high-value hull and excess liability towers. ICAO standard-setting frameworks originating from Montreal influence London market claims resolution protocols. The City of London insurance cluster processes cross-border premium flows from Middle Eastern and Asian fleet operators.
China
COMAC C919 deliveries expand domestic fleet insurance demand as operators localize coverage placement away from London markets. MIIT aviation manufacturing standards reshape product liability exposure for domestic airframe producers. Shanghai's Pudong aviation zone concentrates MRO facilities requiring specialized hangar keeper liability coverage.
United Arab Emirates
Emirates and Etihad wide-body fleets generate premium volume for all-risks coverage with minimal exclusions on high-value aircraft. GCAA regulatory alignment with EASA frameworks facilitates European reinsurer participation in local placement. Dubai International Financial Centre hosts regional underwriting capacity serving African and South Asian operators.
Aerospace Insurance Market Key Industry Players
Concentration sits with global reinsurance conglomerates and specialized aviation underwriters that command facultative networks and proprietary risk engineering capabilities. The market structure divides between integrated multi-line carriers with balance-sheet capacity and boutique syndicates with technical underwriting expertise. Two strategic archetypes dominate: scale-driven reinsurers leveraging global distribution and specialized Lloyd's syndicates capturing niche hull-value tiers. Competitive moves center on portfolio diversification into unmanned aerial systems and parametric product development.
Within the integrated carrier tier, Munich Re Specialty and AXA XL exemplify scale-driven underwriting architectures that span facultative placement and risk engineering services. Global Aerospace occupies a specialist position in general aviation segments where premium granularity rewards technical expertise. These three entities anchor competitive dynamics across commercial airline, general aviation, and product liability verticals.
| Leading Market Players |
|---|
| AXA XL |
| Munich Re Specialty |
| Global Aerospace |
| Tokio Marine HCC |
| Starr International Company |
| American International Group |
| USAIG |
| Allianz |
| Chubb |
| Others |
Cost & Logistics Intelligence
Facultative placement scale at Lloyd's syndicates and continental reinsurers concentrates underwriting capacity in London, Frankfurt, and Singapore, creating tiered price floors that escalate with hull-value thresholds and compress margins for regional carriers lacking direct market access.
Pricing Analysis
Commercial airline risk managers anchor pricing negotiations through centralized procurement functions that aggregate fleet-wide coverage across multiple hull-value tiers. Pricing stratifies across comprehensive, third-party, and ground-risk levels, with premium differentiation driven by EASA airworthiness certification status and sustainable aviation fuel consumption benchmarks. Cost compression in general aviation lines is intensifying because parametric weather products eliminate traditional loss-adjustment overhead. Low-cost carriers with standardized narrow-body fleets demonstrate highest price sensitivity, while legacy carriers with wide-body exposure show lowest sensitivity due to limited alternative placement options for excess liability towers.
Supply Chain Analysis
Titanium sponge smelter concentration in Russia and China underwrites input cost volatility that propagates through airframe replacement valuations and corresponding hull-coverage limits. Composite pre-preg manufacturing draws from Japan, the United States, and Germany, while certified MRO capacity for carbon-fiber repair rests on facilities in Singapore, the United Arab Emirates, and Germany. Single-source vulnerability in aerospace-grade titanium supply creates coverage recalibration triggers when smelter disruptions inflate replacement timelines. Distribution runs through broker-mediated annual placement for primary layers, with direct digital binding penetrating supplemental coverage for low-cost operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among commercial airline procurement consortiums that aggregate fleet coverage across multiple operators, fragmenting traditional broker intermediation and compressing placement fees.
For Market Incumbents: Shield core hull-value tiers by deepening proprietary risk engineering capabilities that parametric entrants cannot replicate, particularly for composite-intensive airframes requiring specialized degradation modeling. Fortify facultative reinsurance relationships in London and Singapore to defend placement access against emerging digital carriers. Vertical integration into satellite telemetry partnerships provides data asymmetry that sustains real-time pricing advantages over annual renewal competitors. For New Entrants and Emerging Players: Anchor in unmanned aerial systems coverage for beyond-visual-line-of-sight agricultural and logistics operations across Florida and Gulf Coast clusters, where traditional aviation underwriters maintain minimal presence. Target fractional ownership platforms and on-demand charter operators with parametric structures that deliver immediate liquidity and eliminate claims adjustment friction. A direct digital binding go-to-market angle bypasses broker resistance that incumbent carriers exploit to block channel access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Lloyd's syndicates with established facultative networks and multi-year manufacturer liability placements that lock in rate stability across product development cycles. Long-term viability over the projection horizon favors acquirers of specialized general aviation underwriters with technical expertise in rotorcraft and light-jet portfolios. Monitor EASA airworthiness directive frequency as the inflection indicator for forced mid-term policy amendments that disrupt pricing stability and create distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Index-based weather coverage eliminates claims friction for Gulf Coast regional operators. |
| Digital Binding Platform Launch | Direct placement channels bypass broker intermediation for low-cost airline supplemental layers. |
| Sustainability Certification Alignment | EU Green Deal premium discounts attract narrow-body operators on intra-European routes. |
| Facultative Network Expansion | Singapore and Dubai underwriting capacity captures Asian and Middle Eastern fleet growth. |
| Cyber-Physical Endorsement Development | Satellite-linked avionics coverage addresses connected flight system exposures outside traditional hull policies. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airline risk managers, aviation underwriters at Lloyd's syndicates, reinsurance placement specialists, and MRO facility operations directors. Secondary validation drew from FAA Part 135 and Part 205 regulatory filings, EASA airworthiness directive databases, Lloyd's market data, and customs records tracking aerospace-grade titanium trade flows. Bottom-up fleet valuation modeling and top-down premium aggregation were triangulated to reconcile coverage limit estimates with carrier-reported placement volumes.
Across the analysis window, projections incorporate segmentation across product type, coverage tier, end-user category, and policy term duration. CAGRs were derived from hull-value escalation curves tied to composite airframe replacement costs and liability tower expansion patterns. Forecast inputs include new aircraft delivery schedules from Airbus and Boeing, EASA regulatory amendment frequencies, and parametric product penetration rates in general aviation segments.
Decision-makers should treat outputs as directional under stable regulatory enforcement and uninterrupted titanium supply assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as FAA Part 135 safety mandate stringency and EASA Green Deal implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Denmark Property and Casualty Insurance Market
Insurance
Global Property and Casualty Reinsurance Market
Insurance
China Liability Insurance Market
Insurance
Africa Insurance Market
Insurance
Global Livestock Insurance Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
Asia-Pacific Travel Insurance Market
Insurance
Cyber Liability Insurance Market
Insurance
Consumer Electronics Extended Warranty Market
Insurance
United States Commercial Insurance Market
Insurance
Africa Microinsurance Market
Insurance
Business Travel Accident Insurance Market
Insurance
MENA Health and Medical Insurance Market
Insurance
Logistics Insurance Market
Insurance
China Parametric Insurance Market
Insurance
Gap Insurance Market