
 Renters Insurance Market | 2026-2036
Renters Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Renters Insurance Market Outlook
Urban millennials entering rental housing is reorganizing buyer composition in the renters insurance landscape. State Farm Mutual Automobile Insurance leverages its captive agent network to sustain dominance in traditional policy distribution. Lemonade differentiates through AI-driven claims processing and instant underwriting. Allstate anchors its position with bundled product ecosystems spanning auto and property lines.
Renters insurance is a property and casualty contract that indemnifies tenants against loss or damage to personal belongings, liability exposure, and additional living expenses when a covered peril renders a leased dwelling uninhabitable. Policies typically specify per-occurrence limits, named peril schedules, and deductible thresholds calibrated to replacement cost or actual cash value methodologies. Personal property coverage occupies the largest premium pool, while pay-as-you-go premium structures are gaining traction among digitally native customer segments. Monthly policy duration formats compete most aggressively for student and young professional cohorts seeking flexibility without annual lock-in.
The National Association of Insurance Commissioners coordinates state-level rate and form oversight, while the Consumer Financial Protection Bureau monitors marketing and disclosure practices affecting tenant borrowers. State regulators enforce dwelling fire and liability reserve requirements that shape carrier capital deployment and product availability. Stakeholders must monitor how climate risk modeling revisions and algorithmic pricing scrutiny will alter underwriting appetite and distribution economics.
Market Dynamics
Digital-first distribution platforms are compressing policy acquisition cycles from days to minutes, forcing incumbent carriers to restructure agent commissions and legacy IT architectures to remain competitive.
Growth Catalysts
- Multi-family housing construction:Apartment completions in the United States hit generational highs, expanding the addressable tenant base requiring mandated or voluntary coverage.
- AI-driven underwriting engines:Machine learning models now process risk signals from IoT sensors and credit data, slashing quote-to-bind time for digitally native applicants.
- Tenant protection mandates:State-level legislation in California, New York, and Texas increasingly requires landlords to verify or facilitate renters insurance as a lease condition.
Market Restraints
- Catastrophe reinsurance costs:Climate-driven loss severity in Florida and Gulf Coast states has doubled reinsurance treaty pricing, compressing carrier margins on standard policies.
- Legacy core system debt:Mainframe-dependent insurers face integration friction when connecting to API-first distribution partners, delaying product launches by 12-18 months.
- Regulatory fragmentation:The National Association of Insurance Commissioners coordinates state-level rate filings, but 50 separate approval processes inflate compliance overhead for national carriers.
Strategic Opportunities
- Gig economy housing mobility:Short-term rental platforms and co-living operators in Germany and the United Kingdom create demand for flexible, pay-per-month policies unattached to annual leases.
- Embedded distribution partnerships:Property management software vendors and proptech platforms now offer insurance at lease signing, capturing tenants at peak intent moments.
- Smart home incentive programs:Water leak detection and fire prevention IoT devices trigger premium discounts, aligning carrier loss prevention with tenant adoption of connected hardware.
Industry Challenges
- Actuarial talent scarcity:Pricing teams with expertise in granular geographic risk modeling and behavioral data science command premium compensation, constraining mid-tier carrier expansion.
- Claims fraud detection latency:Real-time image verification and social media cross-referencing require substantial AI infrastructure investment to reduce false-positive rates without alienating legitimate claimants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renters Insurance Market |
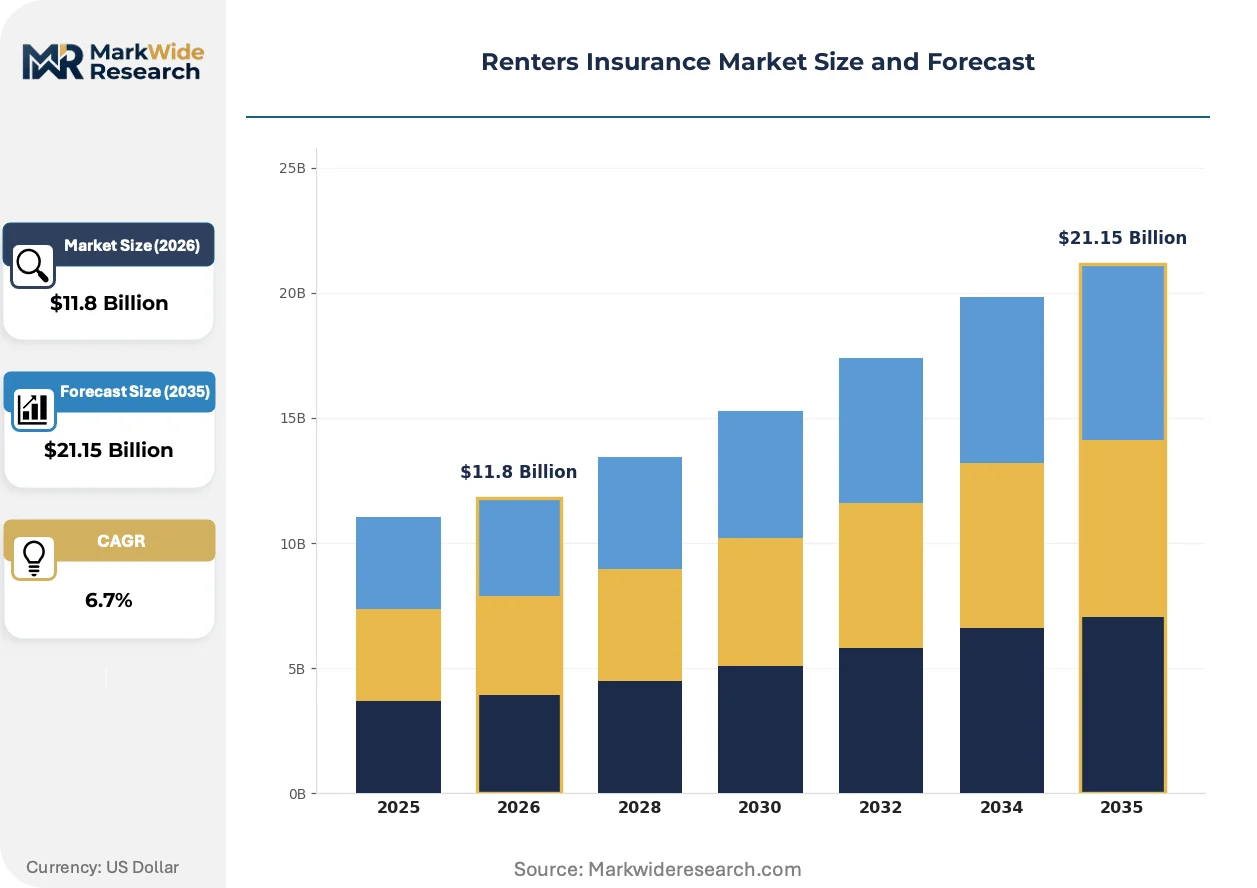
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Personal Property, Liability, Additional Living Expenses, Loss of Use Policy Duration: Monthly, Annual, Multi-Year, Short-Term Premium Type: Fixed Premium, Variable Premium, Pay-As-You-Go, Bundled Customer Type: Students, Young Professionals, Families, Seniors |
| Companies Covered | State Farm Mutual Automobile Insurance, Allstate, Travelers Companies, Lemonade, USAA, Geico, Nationwide, Progressive, Farmers Insurance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renters Insurance Market Strategic Shifts
Claims processing automation and parametric coverage structures are redefining customer expectations for speed and transparency, while behavioral data integration reshapes risk selection methodologies.
Telematics-enabled property monitoring is miniaturizing. Compact moisture and temperature sensors now transmit real-time dwelling condition data to carrier cloud platforms. Student housing operators and multifamily REITs are deploying these devices at scale across portfolios. This sensor density is miniaturizing the granularity of risk pricing, enabling unit-level premiums that vary by floor, building age, and occupancy patterns rather than zip-code averages.
The EU AI Act imposes algorithmic transparency requirements on automated underwriting decisions affecting European policyholders. Carriers must document training data provenance and enable human review of declined applications. Cross-border insurers with Dublin or Luxembourg headquarters are restructuring model governance frameworks to satisfy these mandates while maintaining pricing precision.
Tenants now expect instant policy binding through mobile interfaces with minimal data entry. This channel preference shift displaces telephone and paper applications among applicants under 35. Direct-to-consumer platforms and embedded insurance APIs capture this cohort, while captive agent networks lose share among first-time renters in metropolitan markets.
Renters Insurance Market Segmentation
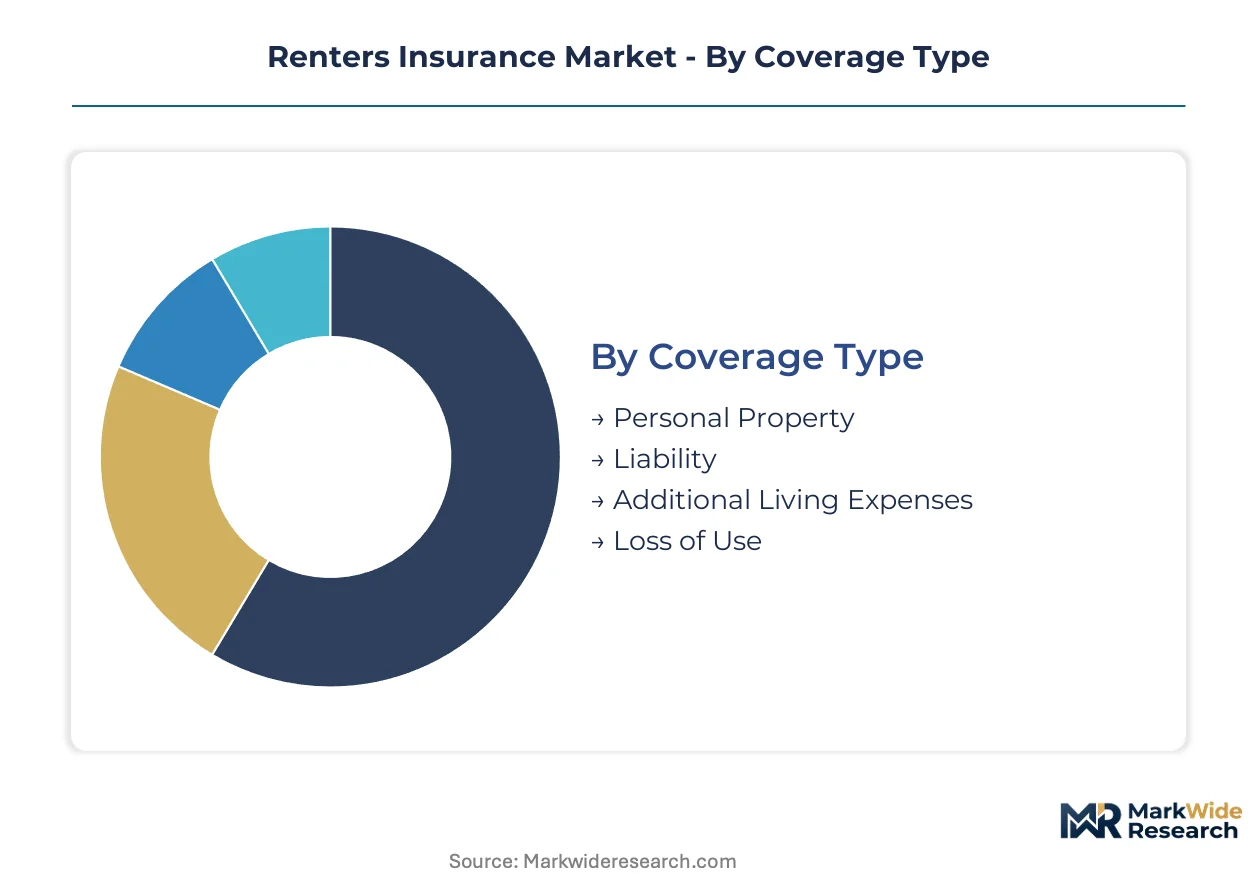
Renters insurance carriers calibrate product architecture around four distinct segmentation axes. Coverage type and policy duration determine capital deployment and claims reserve structures, while premium mechanics and customer demographics shape distribution channel selection and marketing spend allocation.
Coverage Type:
Personal property coverage flows through direct-to-consumer digital channels, while liability riders concentrate in agent-mediated sales requiring explanation of legal exposure limits.
- Personal Property:Core indemnity contract protecting against theft, fire, and water damage to tenant possessions. Demand concentrates in urban multifamily clusters where replacement cost valuations exceed tenant savings buffers. Students and young professionals drive volume through mobile-first binding platforms.
- Liability:Third-party injury and property damage protection triggered by tenant negligence. Apartment operators in California and Texas mandate this coverage as lease conditions, embedding policies through property management software at signing moments.
- Additional Living Expenses:Temporary housing reimbursement when perils render units uninhabitable. Climate-vulnerable Gulf Coast states show elevated attachment rates as hurricane awareness spreads among long-term tenants.
- Loss of Use:Income replacement for landlords when tenant-caused damage interrupts rental revenue streams. Commercial property investors in student housing REITs purchase this rider at portfolio scale.
Personal property dominates installed base. Liability is where expansion concentrates.
Policy Duration:
Duration selection correlates with housing tenure security, with shorter formats commanding premium pricing per unit of coverage but reducing customer lifetime value volatility.
- Monthly:Revolving contracts enabling cancellation without penalty. Gig economy workers and co-living residents in Berlin and London prefer this flexibility, accepting 15-20% higher per-month rates.
- Annual:Standard 12-month term aligning with residential lease cycles. US carriers embed auto-renewal clauses capturing 70%+ retention without active re-enrollment friction.
- Multi-Year:Extended commitments locking rates against inflation. Price-sensitive families in rent-controlled jurisdictions select this format to hedge premium escalation.
- Short-Term:Coverage windows under 30 days for sublease and vacation rental scenarios. Airbnb hosts in Barcelona and Amsterdam activate these policies per booking through platform-integrated APIs.
Annual contracts anchor carrier cash flow predictability. Monthly formats are climbing the fastest among digitally native applicants.
Premium Type:
Premium structure determines data collection intensity and underwriting automation feasibility, with variable and usage-based models requiring IoT infrastructure investment.
- Fixed Premium:Static rate throughout policy term regardless of behavioral changes. Traditional carriers favor this simplicity for legacy system compatibility and predictable loss ratio modeling.
- Variable Premium:Rates adjusting based on credit score fluctuations or claims history. FCRA compliance requirements in the US limit deployment to applicants consenting to ongoing monitoring.
- Pay-As-You-Go:Usage-adjusted pricing tied to verified occupancy days or sensor-reported risk conditions. Lemonade and similar insurtechs pilot this format with smart home device partnerships.
- Bundled:Discounted multi-line packaging with auto or life coverage. Allstate and State Farm leverage captive agent relationships to cross-sell these combinations at policy inception.
Fixed premium holds majority share. Pay-as-you-go is gaining share fastest among tech-forward customer segments.
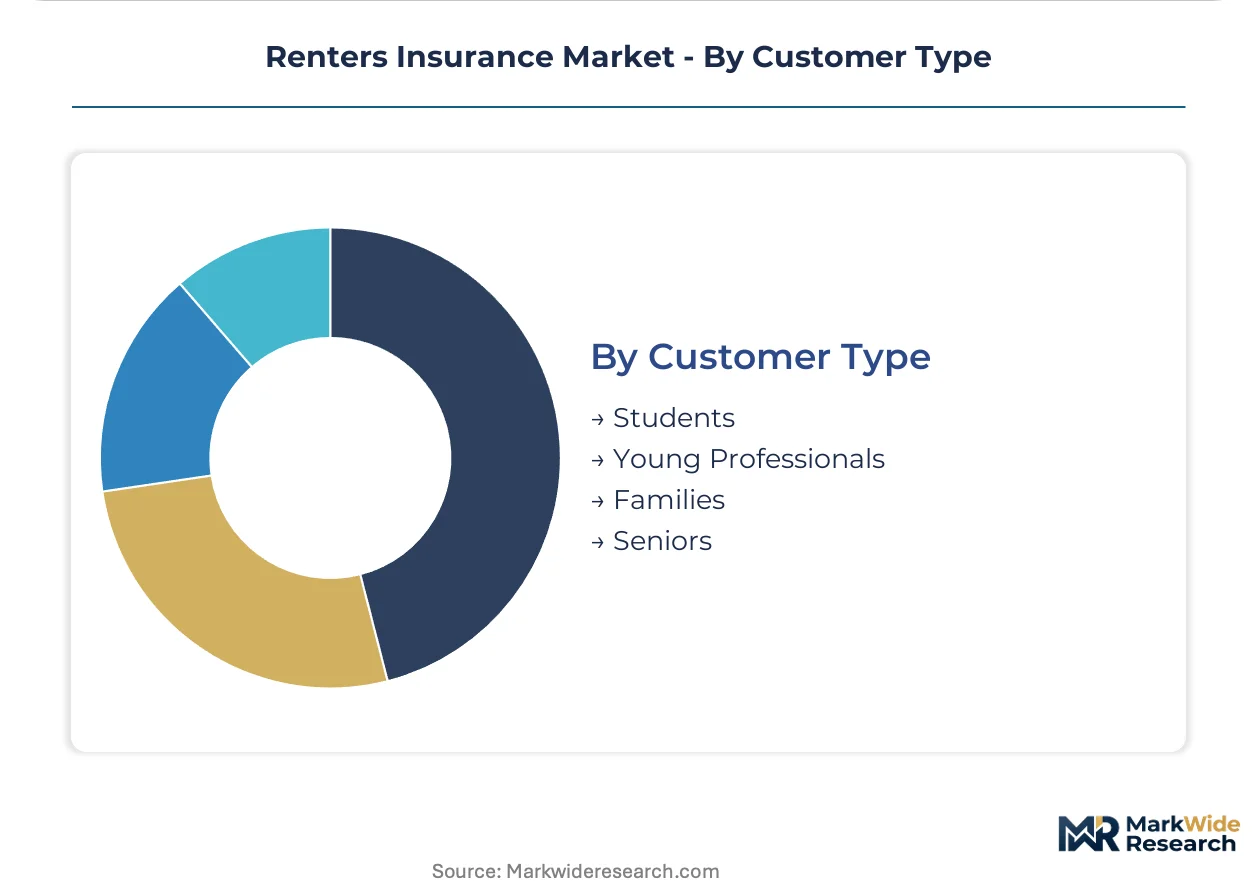
Customer Type:
Demographic targeting shapes marketing channel mix, with students reached through university partnerships and families through real estate agent referrals.
- Students:First-time renters requiring basic coverage at minimal cost. University housing offices in Massachusetts and Illinois facilitate group purchasing programs with simplified underwriting.
- Young Professionals:Urban millennials prioritizing mobile binding speed over price optimization. This cohort shows highest acceptance of AI-driven claims chatbots and digital document submission.
- Families:Multi-income households seeking higher personal property limits and umbrella liability stacking. Suburban markets around Dallas and Atlanta concentrate this demand.
- Seniors:Downsizing empty-nesters transitioning from homeowner to renter status. This segment requires education on coverage differences, sustaining agent-mediated distribution in Florida retirement communities.
Young professionals dominate new policy acquisition velocity. Families represent the steepest expansion trajectory as household formation accelerates in Sun Belt metros.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States carriers export policy frameworks and underwriting technology to English-speaking markets, while European insurtechs license digital distribution platforms to Asian partners seeking rapid deployment.
United States
Multi-family housing construction in Texas and Florida drives tenant base expansion, while California and New York enforce lease-mandated coverage verification. The National Association of Insurance Commissioners coordinates state-level rate oversight, though 50 separate filing processes inflate compliance overhead. Miami-Dade and Harris County apartment clusters concentrate embedded insurance partnerships at lease signing.
Germany
Gig economy housing mobility in Berlin and Munich creates demand for flexible monthly policies unattached to annual leases. The country's national insurance regulator enforces solvency reserve requirements that shape carrier capital deployment. Frankfurt and Hamburg co-living operators deploy smart home sensors enabling unit-level risk pricing by floor and building age.
United Kingdom
Short-term rental platforms in London and Manchester activate per-booking coverage through API-integrated proptech partnerships. The Financial Conduct Authority monitors marketing disclosure practices affecting tenant borrowers. Birmingham student housing REITs purchase loss-of-use riders at portfolio scale, embedding policies through property management software.
Canada
Urban millennials entering Toronto and Vancouver rental markets prioritize mobile binding speed over price optimization. Health Canada oversees consumer protection frameworks intersecting with tenant insurance marketing. Montreal and Calgary multifamily developers integrate insurance offers at pre-leasing phases, capturing tenants at peak intent moments.
Australia
Climate-vulnerable Queensland and New South Wales tenants show elevated attachment rates for additional living expenses coverage as cyclone awareness spreads. The Australian Prudential Regulation Authority enforces liability reserve requirements affecting product availability. Sydney and Melbourne proptech platforms now offer insurance at lease signing, compressing policy acquisition cycles from days to minutes.
Renters Insurance Market Competitive Environment
Listed leaders compete with private specialists across distribution channel dominance, with publicly traded carriers commanding agent networks while venture-backed insurtechs capture direct-to-consumer velocity. The market structures around three tiers: legacy mutuals with captive agent infrastructure, digital-first platforms with AI-driven underwriting, and mutual associations serving affinity memberships. Consolidation pressure intensifies as carriers acquire insurtech capabilities and embedded distribution partnerships reshape customer acquisition economics.
Within the legacy mutual tier, State Farm Mutual Automobile Insurance and USAA exemplify agent-mediated distribution models sustained through decades-long customer relationships. Allstate occupies a position bridging traditional and digital channels, while Lemonade represents the insurtech archetype with instant underwriting and claims automation. Travelers Companies and Progressive sit within the commercial-personal hybrid segment, leveraging multi-line bundling to defend policyholder lifetime value.
| Leading Market Players |
|---|
| State Farm Mutual Automobile Insurance |
| Allstate |
| Travelers Companies |
| Lemonade |
| USAA |
| Geico |
| Nationwide |
| Progressive |
| Farmers Insurance |
| Others |
Value Chain & Pricing Dynamics
Annual policy contracts with embedded auto-renewal clauses lock in tenant retention and premium visibility for US carriers, while monthly revolving formats in European co-living markets trade price predictability for flexibility. This contract-structure divergence shapes how carriers deploy capital across legacy IT systems and API-first distribution partnerships.
Pricing Analysis
Legacy carrier pricing anchored in zip-code actuarial tables faces compression from next-generation unit-level risk models using IoT sensor data. Three-tier pricing structure across premium, standard, and economy levels stratifies by coverage depth and deductible thresholds, with gig economy tenants in Berlin and London showing highest price sensitivity. Cost compression in the standard tier is intensifying because embedded distribution partnerships at lease signing capture tenants at peak intent moments. Family segments in Sun Belt metros demonstrate lowest price sensitivity, accepting higher premiums for multi-year rate locks.
Supply Chain Analysis
Policy fulfillment lead times have compressed from days to minutes as cloud-native core systems displace mainframe-dependent architectures. Reinsurance capacity concentrates in Bermuda, London, and Zurich, while underwriting talent clusters in Hartford, New York, and Chicago. Carrier loss ratios hinge on catastrophe modeling software and climate risk data feeds. Single-source vulnerability runs through legacy mainframe vendors delaying product launches. Distribution runs through captive agent networks, direct-to-consumer platforms, and embedded property management software partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tenant buyer power is concentrating through property management software consolidation, with three platform vendors now controlling lease-signing workflow access for over forty percent of US multifamily units.
For Market Incumbents: Secure exclusive embedded distribution partnerships with property management software vendors before insurtech competitors capture lease-signing moments. Accelerate migration from mainframe core systems to API-first architectures to reduce integration friction with proptech partners. State Farm Mutual Automobile Insurance and Allstate must defend agent-mediated channels against Lemonade's instant underwriting by bundling auto-renewal incentives with loyalty discounts. For New Entrants and Emerging Players: NAIC state filing fast-track through reciprocity agreements enables rapid multi-state expansion without fifty separate approval processes. White-space targets include pay-as-you-go policies for gig economy housing mobility in Germany and the United Kingdom, plus short-term coverage APIs for Airbnb hosts in Barcelona and Amsterdam. The most penetrable segment is monthly revolving contracts for co-living residents, accessed through direct-to-consumer mobile binding with minimal data entry. For Investors and Strategic Acquirers: Capital is best deployed toward insurtechs with proven AI claims automation and existing embedded distribution partnerships, positioned for carrier acquisition or strategic alliance. Long-term viability over the next decade rests on regulatory adaptability as algorithmic pricing scrutiny intensifies and climate risk modeling revisions alter underwriting appetite. Monitor NAIC rate filing rejection rates as the inflection indicator for regulatory headwinds affecting expansion economics.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Distribution Partnership | Captures tenants at lease-signing peak intent through property management software integration. |
| AI Claims Automation Deployment | Reduces false-positive rates while accelerating settlement speed for digitally native applicants. |
| IoT Sensor Incentive Program | Aligns carrier loss prevention with tenant adoption of water leak and fire detection devices. |
| Multi-Line Bundling Expansion | Leverages captive agent relationships to cross-sell auto and property coverage at policy inception. |
| Regulatory Reciprocity Investment | Accelerates multi-state rate approval through NAIC coordinated filing frameworks. |
Study Parameters
Desk research of NAIC rate filing databases, SEC carrier 10-K disclosures, and proptech platform partnership announcements preceded structured interviews with chief underwriting officers, claims operations directors, property management software executives, and reinsurance treaty brokers. Primary fieldwork with these stakeholders was validated against secondary sources including state insurance department enforcement actions, embedded insurance API documentation, and IoT sensor deployment data from multifamily REITs. Bottom-up policy volume estimates triangulated with top-down premium pool calculations.
Variance decomposition across coverage type, policy duration, premium structure, and customer demographic dimensions shaped the analytical framework over the projection horizon. Modeled segmentation included personal property limits, liability attachment rates, and geographic risk clustering by state regulatory framework. CAGRs were derived from trend extrapolation of tenant base expansion, premium rate trajectories, and loss ratio assumptions. Industry-specific inputs incorporated catastrophe reinsurance pricing cycles and embedded distribution partnership penetration rates.
Underlying assumptions cover stable NAIC coordination of state-level rate oversight, with deviation risk concentrated in climate-driven loss severity revisions and algorithmic pricing regulatory scrutiny. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Finance and Financial Planning
Global Financial Wellness Software Market
Personal Finance and Financial Planning
Financial Calculators Market
Personal Finance and Financial Planning
Personal Finance Software Market
Personal Finance and Financial Planning
Household Finances Market
Personal Finance and Financial Planning
Credit Scores, Credit Reports and Credit Check Services Market
Personal Finance and Financial Planning
Global Financial Planning Software Market
Personal Finance and Financial Planning
Debt Settlement Market
Personal Finance and Financial Planning
Account Planning Tool Market
Personal Finance and Financial Planning
Global Personal Finance Tools and Market
Personal Finance and Financial Planning
China Financial Planning Software Market
Personal Finance and Financial Planning
Global Personal Loans Market