
 Potassium Feldspar Market | 2026-2036
Potassium Feldspar Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Feldspar Market Analysis
Glass manufacturing demand is shifting toward specialized container and solar glass grades, pulling premium feldspar specifications. SCR Sibelco NV leverages its integrated mining-to-distribution network across European ceramic hubs. Quarzwerke Group sustains long-term supply contracts with German sanitaryware producers. The Quartz Corp. anchors North American supply through its Spruce Pine operations in North Carolina.
Potassium feldspar is an alkali aluminosilicate mineral with K2O content typically ranging from 10% to 14%, serving primarily as a fluxing agent that lowers melting temperatures in glass and ceramic formulations. Industrial grades derive from pegmatite and feldspathic sand deposits processed through crushing, grinding, and magnetic separation to achieve iron content below 0.1% for whiteware applications. The ground product type commands the largest volume share due to its direct use in standard ceramic body formulations, while micronized grades in powder form capture expanding margin pools from technical ceramics and engineered glass coatings. Glass manufacturing remains the dominant end-use industry by tonnage, though ceramics applications in India and Vietnam are generating faster volume growth from infrastructure investment.
EPA mining waste standards in the United States and REACH chemical registration requirements in Europe constrain extraction expansion and product classification for export markets. India's CEA environmental clearance protocols and BIS quality certification for ceramic raw materials are reshaping supplier qualification criteria for domestic manufacturers. Stakeholders must monitor evolving silica dust exposure limits and carbon intensity disclosures that could restructure competitive access across major producing jurisdictions.
Market Dynamics
China's MEE environmental enforcement on feldspar mining is redistributing supply chain control toward India and Turkey, forcing ceramic manufacturers to requalify alternative ore sources under tighter iron-content specifications.
Growth Catalysts
- India PLI scheme for ceramics:Production-linked incentives for sanitaryware and tile manufacturing in Gujarat and Rajasthan are expanding captive feldspar consumption by domestic processors.
- Solar glass capacity expansion:Photovoltaic panel manufacturers in Vietnam and Malaysia are pulling premium low-iron feldspar grades for tempered glass substrates.
- REACH chemical registration harmonization:Streamlined EU import classification for processed feldspathic sands is reducing customs friction for Turkish exporters.
Market Restraints
- Energy cost volatility:Natural gas and diesel prices for grinding operations in European processing plants compress margin recovery during price negotiations.
- Deposit depletion in mature mines:Pegmatite ore quality degradation in traditional Spanish and Portuguese extraction sites raises beneficiation costs.
- Substitute flux materials:Nepheline syenite from Canadian deposits competes directly in container glass formulations where color latitude permits.
Strategic Opportunities
- Underpenetrated African ceramic markets:Nigeria and Egypt's emerging tile production clusters lack established local feldspar supply, creating import substitution potential.
- Technical ceramics convergence:Piezoelectric and semiconductor substrate applications are opening micronized powder specifications at 5-10 micron particle sizes.
- Digital procurement platforms:B2B marketplaces for industrial minerals are disintermediating traditional trader networks in Southeast Asian sourcing.
Industry Challenges
- Geologist and mining engineer scarcity:Specialized pegmatite exploration expertise is concentrating among retiring professionals in established producing regions.
- BIS certification timelines:Indian ceramic raw material quality approvals require 12-18 month validation cycles that delay new supplier onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Feldspar Market |
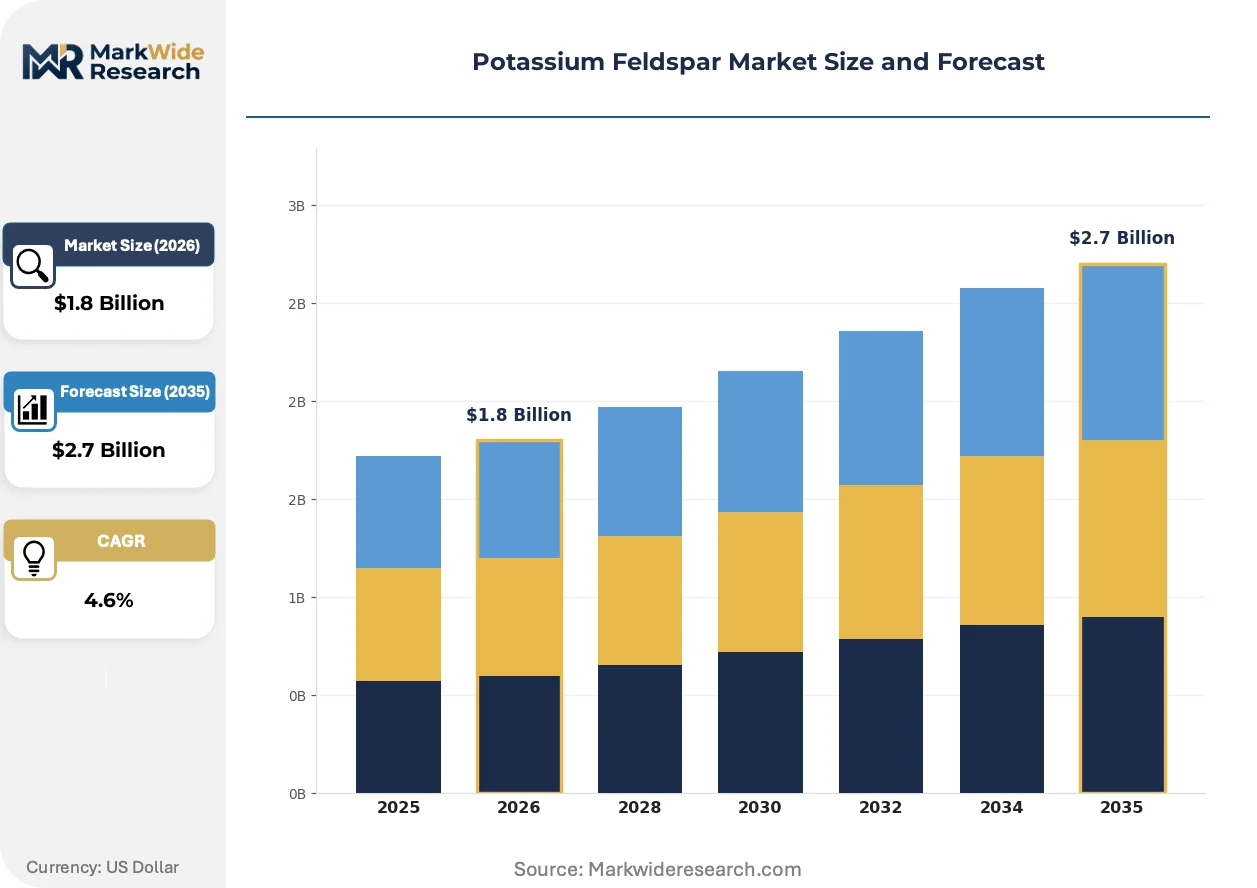
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground, Spruce, Feldspathic Sand, Potash End Use Industry: Glass Manufacturing, Ceramics, Construction, Paints Form: Powder, Granules, Lumps, Micronized Packaging Type: Bag, Bulk, Drum, Container |
| Companies Covered | Pacer Minerals LLC, Quarzwerke Group, iMinerals Inc., Global Minechem Corp., Minerali Industriali Srl, Kaolin EAD, The Quartz Corp., Snow White Minerals Pvt. Ltd., SCR Sibelco NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Feldspar Market Emerging Trajectories
Processing technology and environmental compliance systems are restructuring competitive advantage away from raw ore access toward beneficiation precision and carbon-accounted supply chains.
Sensor-based ore sorting is automating pre-concentration at mine sites. European and Turkish operators are installing X-ray transmission and laser-induced breakdown spectroscopy units to reject iron-bearing minerals before grinding. This technology is automating labor-intensive hand-sorting while raising run-of-mine yields by fifteen to twenty percentage points, compressing unit costs for export-grade material.
EU CSRD corporate sustainability reporting directives now mandate Scope 3 emissions disclosure for ceramic raw material inputs. German and Italian sanitaryware producers are demanding carbon footprint certificates from feldspar suppliers, with non-compliant shipments facing procurement exclusion. Turkish exporters are responding by installing solar-powered drying systems and third-party verified carbon accounting.
Long-term offtake contracting is displacing spot-market purchasing for premium grades. Solar glass and technical ceramics manufacturers in South Korea and Taiwan are locking three-to-five-year supply agreements with fixed volume floors and price escalation clauses tied to energy indices. This shift concentrates procurement leverage among buyers with certified quality requirements and balance-sheet capacity for prepayment structures.
Potassium Feldspar Market Segmentation
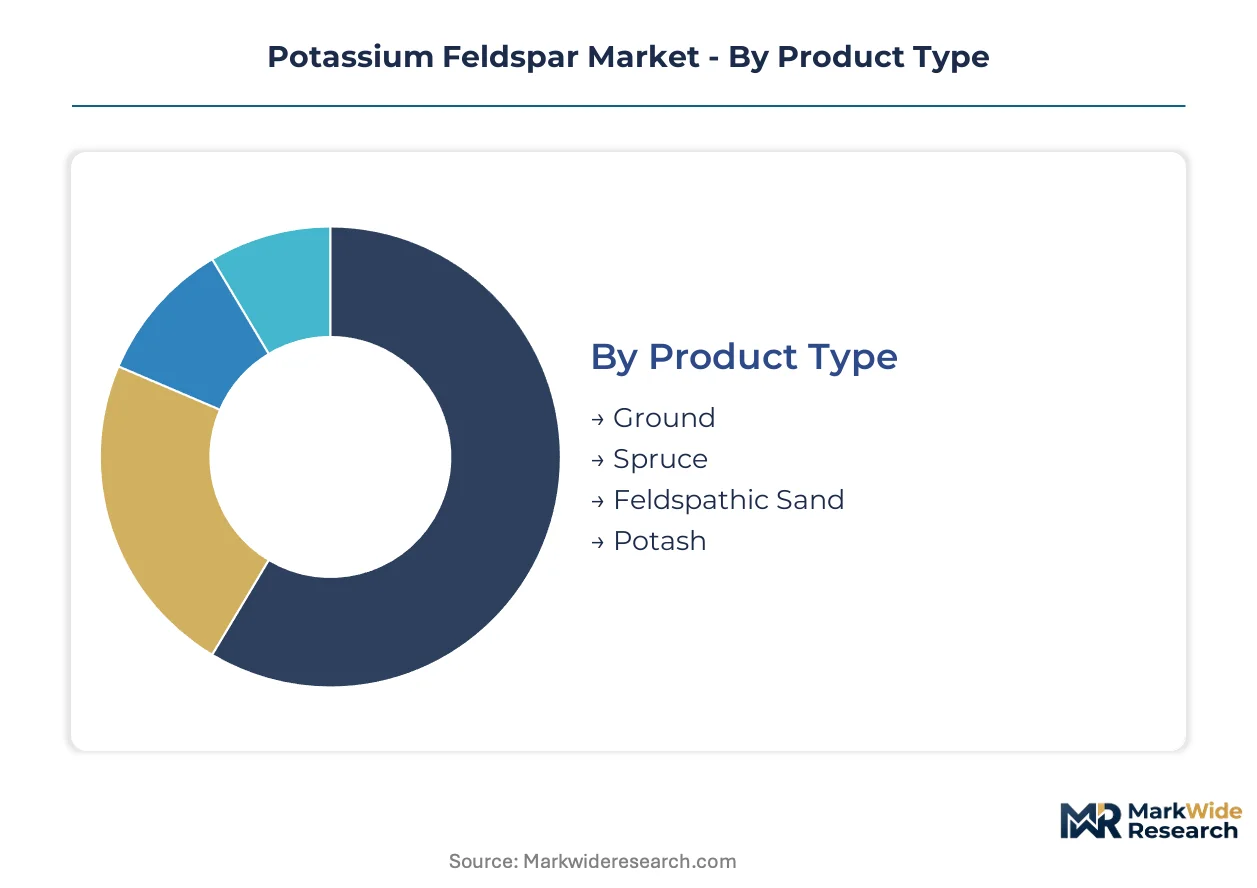
Potassium feldspar supply chains fragment across four critical dimensions that determine processing economics and customer qualification requirements. Product type and end-use specifications dominate procurement decisions, while form and packaging configurations shape logistics costs and inventory management strategies for ceramic and glass manufacturers.
Product Type:
Supply concentration in pegmatite mining districts directly shapes which product types command premium pricing and which face substitution pressure from alternative flux sources.
- Ground:Standard crushed and milled feldspar with particle sizes typically 200-325 mesh serves as the workhorse input for ceramic body formulations across India's Rajasthan-Gujarat cluster. Demand concentrates in mid-range sanitaryware and floor tile production where iron content tolerance permits 0.1-0.15% thresholds, though Chinese environmental enforcement on mining operations is tightening raw ore availability for this grade.
- Spruce:High-purity pegmatite feldspar from specific North Carolina deposits carries K2O content exceeding 11% with iron below 0.08%, qualifying it for premium container glass and solar glass substrates. Procurement from The Quartz Corp.'s Spruce Pine operations anchors North American supply for technical glass manufacturers demanding certified low-iron consistency.
- Feldspathic Sand:Naturally occurring sand deposits with 7-10% K2O content processed through wet classification and magnetic separation offer lower-cost flux alternatives for colored glass and construction materials where whiteness specifications relax.
- Potash:Chemically refined potassium feldspar concentrates with K2O above 14% serve specialty fertilizer and chemical applications outside mainstream ceramic and glass channels, with supply tied to potash mining byproduct streams rather than dedicated feldspar extraction.
Today's leader: Ground. Tomorrow's challenger: Spruce.
End Use Industry:
Application-driven specification divergence creates distinct margin tiers, with technical glass and engineered ceramics pulling premium grades while commodity construction absorbs cost-optimized alternatives.
- Glass Manufacturing:Container, flat, and solar glass formulations consume the largest tonnage volumes, with solar glass expansion in Vietnam and Malaysia driving demand for ultra-low-iron specifications below 0.05% that command significant price premiums over standard container grades.
- Ceramics:Sanitaryware, tiles, and tableware applications across India's PLI-supported production hubs in Gujarat and Rajasthan generate the fastest volume expansion, with BIS quality certification requirements reshaping supplier qualification timelines for domestic processors.
- Construction:Concrete additives, road base materials, and filler applications absorb lower-grade feldspathic sands where color and purity constraints minimize, with procurement decisions driven primarily by delivered cost rather than chemical specification.
- Paints:Functional filler applications in industrial coatings demand controlled particle size distribution and brightness values, with micronized grades penetrating this segment as titanium dioxide extenders.
Glass Manufacturing captures current volume dominance. Ceramics climbs the fastest as India's infrastructure investment accelerates.
Form:
Processing intensity and transportation economics divide the form landscape, with powder and micronized grades capturing value-added margins while lumps and granules minimize beneficiation costs.
- Powder:Finely ground material below 75 microns serves direct pressing and spray-drying operations in ceramic tile manufacturing, with bulk density and flow characteristics determining handling system compatibility.
- Granules:Sized fractions between 1-5 millimeters facilitate controlled melting in glass furnace batch formulations, with particle size consistency reducing segregation during transport and storage.
- Lumps:Run-of-mine or minimally crushed ore above 10 millimeters supplies grinding operations at ceramic and glass plants with captive beneficiation capacity, minimizing supplier processing costs but maximizing customer freight expenses.
- Micronized:Sub-10 micron particle sizes produced through jet milling or stirred media grinding open technical ceramics, semiconductor substrates, and engineered coating applications with specification thresholds inaccessible to standard grinding circuits.
Powder maintains form leadership. Micronized gains share fastest from technical ceramics convergence.
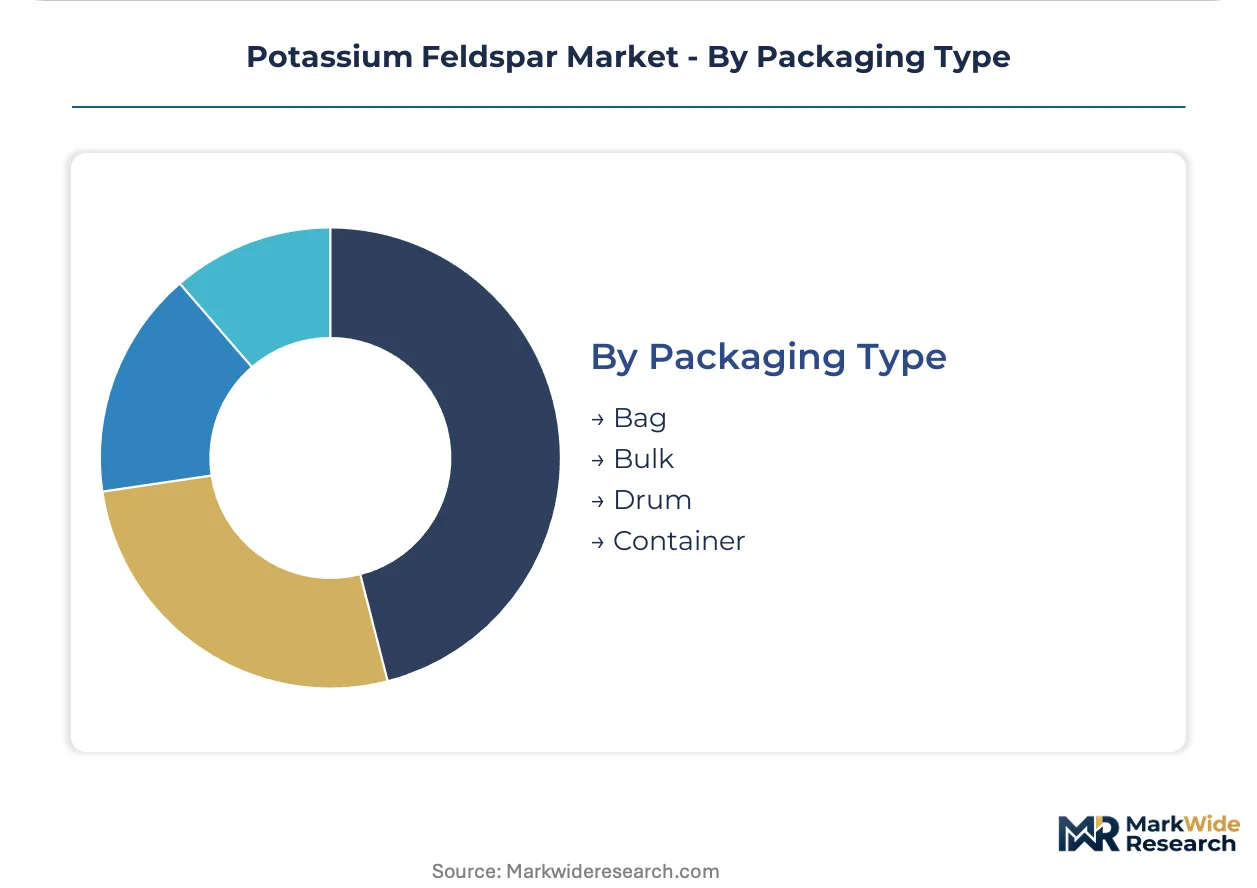
Packaging Type:
Logistics configuration and customer scale determine packaging selection, with bulk systems dominating high-volume ceramic clusters while bagged and containerized shipments serve dispersed or international procurement.
- Bag:25-50 kilogram multi-wall paper or polypropylene bags serve small and mid-sized ceramic processors lacking pneumatic unloading infrastructure, with palletized configurations facilitating warehouse handling.
- Bulk:Pneumatic tanker or hopper truck delivery minimizes packaging costs and handling labor for large-scale tile and glass manufacturers in concentrated production clusters, requiring dedicated unloading systems at customer sites.
- Drum:Steel or fiber drums containing 200-250 kilograms protect moisture-sensitive micronized grades during ocean freight, with sealed configurations preventing caking and contamination for technical ceramic applications.
- Container:Twenty-foot and forty-foot bulk containers with liner bags enable intermodal shipment to inland destinations lacking direct bulk vessel access, bridging bulk economics with distributed customer geography.
Bulk commands volume leadership. Container configurations expand fastest for Turkish and Indian export growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing potassium feldspar production toward jurisdictions with lower compliance costs. China's MEE environmental enforcement is accelerating this migration.
China
MEE environmental inspections have shuttered numerous small-scale feldspar mines in Hunan and Fujian provinces. The dual carbon goals mandate carbon intensity disclosures that smaller operators cannot meet. Ceramic manufacturers in Guangdong are requalifying Indian and Turkish ore sources to replace disrupted domestic supply.
India
CEA environmental clearance protocols and BIS quality certification requirements are reshaping supplier qualification for domestic ceramic processors. The PLI scheme for sanitaryware and tile manufacturing is expanding captive feldspar consumption across Gujarat and Rajasthan. The Bhilwara-Sirohi mining belt in Rajasthan is attracting beneficiation investment from exporters serving Southeast Asian glass manufacturers.
Turkey
REACH chemical registration harmonization is reducing customs friction for Turkish feldspathic sand exports into EU ceramic hubs. Eskisehir and Kutahya provinces host concentrated pegmatite mining districts with expanding wet-processing capacity. German sanitaryware producers are locking long-term offtake agreements with Turkish suppliers holding third-party verified carbon accounting.
United States
EPA mining waste standards constrain greenfield extraction expansion while favoring established operations with grandfathered permits. The Spruce Pine district in North Carolina anchors North American supply for technical glass manufacturers demanding ultra-low-iron specifications. Container glass producers in Ohio and Pennsylvania are negotiating prepayment structures with certified suppliers to secure volume floors.
Vietnam
Solar glass capacity expansion is pulling premium low-iron feldspar grades for tempered photovoltaic substrates. The Binh Duong and Dong Nai industrial zones host emerging ceramic tile clusters with underdeveloped local feldspar supply. Manufacturers are importing Indian ground feldspar through Ho Chi Minh City port infrastructure.
Potassium Feldspar Market Vendor Landscape
Long-term offtake contracting dominates the current landscape as buyers seek supply security amid regulatory disruption. The vendor base concentrates among integrated mining-to-distribution networks and specialized beneficiation operators serving premium technical specifications. Three archetypes define competitive positioning: integrated multinationals with captive ore reserves, regional processors with flexible toll-milling arrangements, and micronization specialists serving technical ceramics. Capacity expansion in Turkish wet-processing facilities and backward integration by Indian ceramic manufacturers into Rajasthan mining assets represent the dominant competitive vectors.
Within the integrated multinational tier, SCR Sibelco NV and The Quartz Corp. exemplify mining-to-distribution network control across European and North American ceramic hubs. Quarzwerke Group occupies a position among German-based processors sustaining long-term supply relationships with sanitaryware manufacturers. These three entities represent contrasting geographic anchoring strategies while sharing reliance on certified quality systems and carbon-accounted supply chains.
| Leading Market Players |
|---|
| Pacer Minerals LLC |
| Quarzwerke Group |
| iMinerals Inc. |
| Global Minechem Corp. |
| Minerali Industriali Srl |
| Kaolin EAD |
| The Quartz Corp. |
| Snow White Minerals Pvt. Ltd. |
| SCR Sibelco NV |
| Others |
Supply Flow & Price Mechanics
India's PLI-supported ceramic manufacturers in Gujarat and Rajasthan operate on long-term offtake contracting that compresses spot-market liquidity and anchors pricing power with certified suppliers holding BIS quality credentials.
Pricing Analysis
Distributor margins for Turkish feldspathic sand exports into EU ceramic hubs typically run 8-12 percent above direct mine-gate pricing, though REACH-registered suppliers capture additional premia through reduced customs friction. Three-tier pricing structure across premium Spruce-grade, standard ground, and economy feldspathic sand tiers separates solar glass specifications from construction-grade tolerance. Pricing pressure stems from energy cost volatility in European grinding operations, with natural gas and diesel expenses compressing margin recovery during contract renegotiations. Small and mid-sized ceramic processors lacking pneumatic unloading infrastructure exhibit highest price sensitivity, while solar glass manufacturers in Vietnam and Malaysia accept significant premia for ultra-low-iron consistency below 0.05 percent.
Supply Chain Analysis
India's CEA environmental clearance protocols and domestic-content preferences in government-backed infrastructure projects are reshaping procurement patterns toward Rajasthan-Gujarat mining belt sources. Supply concentration rests on India, Turkey, and China's Hunan-Fujian provinces, with Chinese MEE enforcement accelerating migration toward Indian and Turkish alternatives. Raw material dependencies include pegmatite ore quality, diesel fuel for grinding operations, and magnetic separation reagents. Single-source vulnerability concentrates around The Quartz Corp.'s Spruce Pine operations for North American ultra-low-iron supply. Distribution runs through pneumatic tanker delivery to concentrated ceramic clusters, with containerized shipments bridging bulk economics for dispersed Southeast Asian buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's tightening MEE environmental compliance costs and India's PLI-scheme production subsidies, with regulatory cost differentials exceeding beneficiation expense gaps.
For Market Incumbents: Lock in long-term offtake agreements with solar glass manufacturers in Vietnam and Malaysia before Turkish wet-processing capacity expansion floods premium-grade supply. Secure backward integration into Rajasthan mining assets to defend against emerging Indian ceramic manufacturers integrating upstream. Invest in third-party verified carbon accounting systems to meet EU CSRD Scope 3 disclosure mandates from German and Italian sanitaryware producers.
For New Entrants and Emerging Players: Technical ceramics manufacturers in South Korea and Taiwan represent the most penetrable buyer archetype, with micronized powder specifications at 5-10 micron particle sizes commanding expanding margin pools. Nigeria and Egypt's emerging tile production clusters lack established local feldspar supply, creating import substitution potential for containerized ground-grade shipments. Pursue BIS quality certification early to compress 12-18 month validation cycles that delay supplier onboarding for India's domestic processors.
For Investors and Strategic Acquirers: German sanitaryware producers are the most active acquirer in this space, locking prepayment structures with Turkish suppliers holding certified carbon accounting. The five-to-ten year viability window favors integrated mining-to-distribution networks over pure-play beneficiation operators. Target acquisition archetype: Turkish wet-processing facilities with REACH registration and solar-powered drying infrastructure. Watch for inflection when China's MEE enforcement extends from Hunan-Fujian to remaining domestic production zones.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Assets | Rajasthan's Bhilwara-Sirohi belt offers captive ore access for Gujarat ceramic processors expanding under PLI incentives. |
| Carbon Accounting Certification | Third-party verified Scope 3 disclosures secure procurement exclusion avoidance from EU CSRD-mandated German sanitaryware producers. |
| Long-term Supply Agreement | Three-to-five-year offtake contracts with fixed volume floors concentrate procurement leverage among solar glass manufacturers in Vietnam. |
| Micronization Capacity Expansion | Jet milling infrastructure for sub-10 micron particle sizes opens technical ceramics and semiconductor substrate applications. |
| Sensor-based Ore Sorting Installation | X-ray transmission and laser-induced breakdown spectroscopy units raise run-of-mine yields by fifteen to twenty percentage points. |
Methodological Framework
Bottom-up ceramics and glass manufacturing demand modeling reconciled against top-down pegmatite mining and feldspathic sand extraction tracking forms the analytical core of this study. Primary interviews with plant managers at Indian tile manufacturers, procurement leads at German sanitaryware producers, Turkish export coordinators, and technical R&D directors at micronization facilities combined with secondary validation from customs and trade data, BIS quality certification records, SEC 10-K filings of listed industrial mineral companies, and CEA environmental clearance databases. Triangulation between consumption-side volume estimates and production-side capacity assessments ensures consistency across the analytical envelope.
Input-output matrices map feldspar grade specifications through end-use conversion factors, with segmentation dimensions spanning product type, form, packaging configuration, and regional production hub. CAGRs derive from trend-line extrapolation of historical consumption patterns adjusted for regulatory displacement effects and infrastructure investment trajectories. Industry-specific forecast inputs include India's PLI scheme disbursement schedules and solar glass capacity buildout timelines across Vietnam and Malaysia.
Underlying measurement precision varies by segment; ground-grade and powder-form categories carry tighter precision than micronized technical ceramics applications due to fragmented supplier reporting. Forecasts reflect assumptions around MEE enforcement continuity, BIS certification timeline stability, and energy cost trajectory persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Titanates Market
Ceramics
Boiler Refractory Material Market
Ceramics
Global Pseudo Boehmite Market
Ceramics
Controlled Pore Metal Oxide Market
Ceramics
High Temperature Ceramics Market
Ceramics
Ball Clay Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
Zirconia Ceramics Market
Ceramics
Active Calcium Silicate Market
Ceramics
Global Industrial Clay Market
Ceramics
Global Alumina Market
Ceramics
Malaysia Ceramic Tiles Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
United States Ceramic Tiles Market