
 Collation Shrink Films Market | 2026-2036
Collation Shrink Films Market Size, Share, and Industry Trends Forecast 2026-2036
Collation Shrink Films Market Analysis
Polymer technician availability across European converter bases is unwinding capacity expansion timelines for collation-grade film lines. Berry Global leverages backward integration into resin compounding to secure low-density polyethylene supply for shrink applications. Mondi Group anchors its position through dedicated R&D centers in Austria that specialize in thin-gauge downgauging below 30 microns. Sealed Air Corporation competes by controlling distribution channels to beverage bottlers across North America and Latin America.
Collation shrink films are biaxially oriented or blown polyethylene-based films engineered with controlled shrink energy release, typically activating between 80°C and 120°C to form tight unitized packs around beverage containers, canned goods, or paper products. The manufacturing process employs either tubular water-quench or flat cast extrusion followed by orientation to achieve machine-direction and transverse-direction shrink balance. Polyethylene formulations dominate material type selection due to cost-positioning and recyclability alignment, while 50-micron thickness grades represent the mature volume anchor where margin pools have compressed from commoditization. Pharmaceutical packaging applications command premium positioning because batch traceability and cleanroom compatibility requirements filter out standard-grade suppliers.
EPA guidelines on volatile organic compound emissions from film extrusion operations shape equipment investment requirements for US-based producers. REACH restrictions on phthalate plasticizers and ECHA substance evaluations constrain PVC-containing collation alternatives across European converter decisions. FDA food-contact substance notifications govern polyethylene resin selection for beverage multipack applications in the United States. Stakeholders must monitor regulatory divergence between EU mechanical recycling quotas and US state-level extended producer responsibility laws as these frameworks will determine which material types and thickness specifications retain market access.
Market Dynamics
Beverage bottlers are compressing collation film specifications toward sub-30 micron gauges while Europe's F-Gas Regulation forces resin reformulation, creating simultaneous performance and compliance pressures on converter operations.
Growth Catalysts
- Downgauging mandates:Beverage multipack lines are demanding thinner films to reduce material intensity per thousand units, pushing converter R&D toward biaxial orientation advances that maintain load stability at reduced caliper.
- Mechanical recycling quotas:EU packaging regulations are requiring minimum recycled content thresholds, directing formulation shifts toward polyethylene grades compatible with post-consumer mechanical reprocessing streams.
- Rhine-Ruhr cluster expansion:Germany's packaging hub is consolidating bottling capacity, concentrating demand for high-throughput collation film supply within a 200-kilometer radius of Düsseldorf.
Market Restraints
- Resin supply concentration:Low-density polyethylene feedstock for shrink applications depends on a narrow base of European petrochemical complexes, exposing converters to naphtha-cracker turnaround schedules.
- Phthalate substitution friction:REACH restrictions on legacy plasticizers in competing PVC collation alternatives are forcing rapid formulation pivots without mature drop-in replacements for shrink performance.
- Polymer technician scarcity:Specialized extrusion and orientation process engineers are retiring faster than training pipelines replenish, extending commissioning timelines for new collation-grade film lines.
Strategic Opportunities
- Pharmaceutical secondary packaging:Cleanroom-compatible collation films for sterile medical device bundling remain underpenetrated, with batch-traceability requirements filtering out commodity-grade suppliers.
- US state EPR divergence:California and Maine extended producer responsibility frameworks are creating early-mover advantages for converters with verified recyclability certification ahead of federal harmonization.
- Digital printing integration:Convergence of shrink film substrates with direct-to-film inkjet systems enables variable-data multipack branding without separate label application steps.
Industry Challenges
- Multi-jurisdiction compliance layering:Simultaneous FDA food-contact notifications, EPA VOC emission permits, and state-level plastic content disclosures are extending product qualification timelines by 8-14 months.
- Legacy line retrofit complexity:Existing tubular water-quench extrusion assets require substantial modification to process next-generation metallocene polyethylene resins with narrower molecular weight distributions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collation Shrink Films Market |
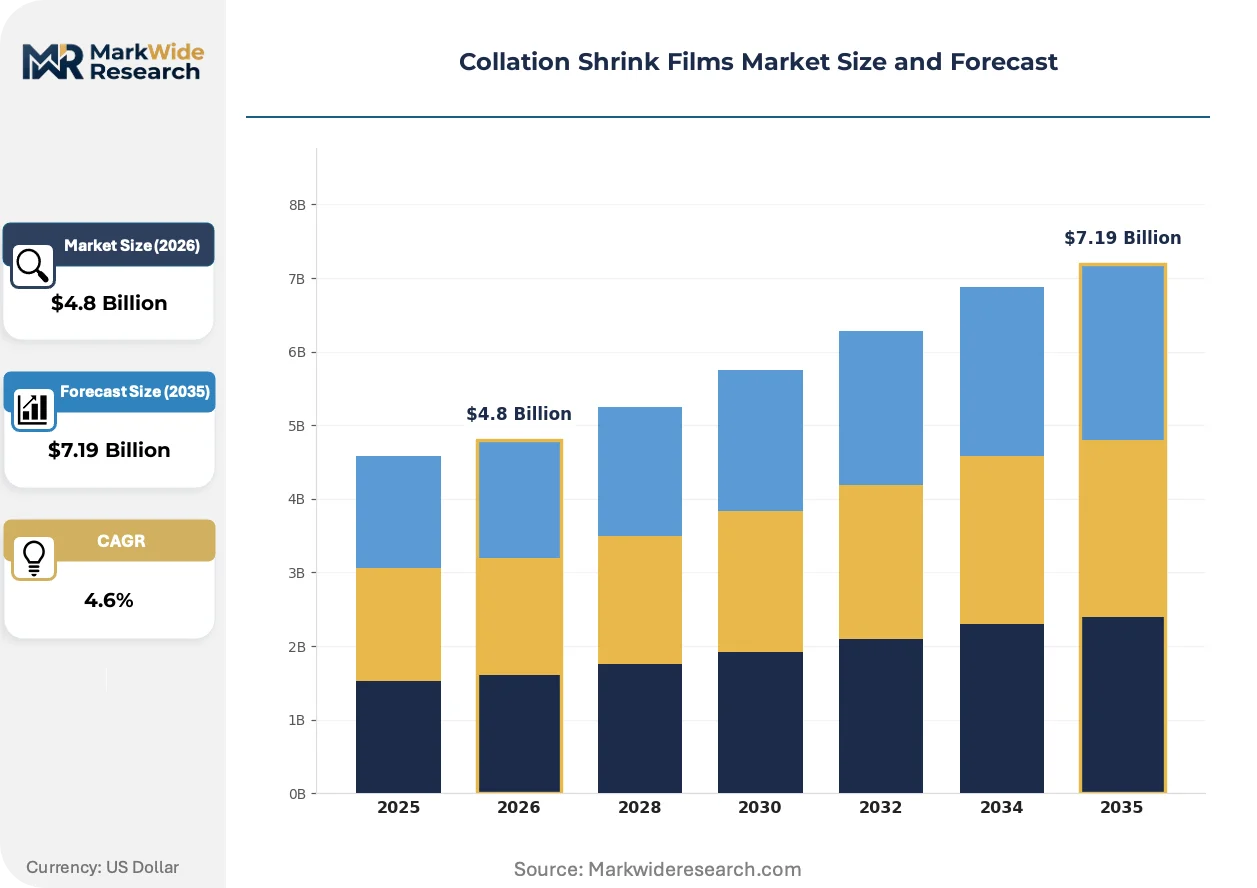
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polyvinyl Chloride, Polypropylene, PET Application: Food Packaging, Beverage Packaging, Consumer Goods, Pharmaceutical Packaging Thickness: 30 Microns, 50 Microns, 75 Microns, 100 Microns End User: Manufacturers, Retailers, Distributors, Online Sellers |
| Companies Covered | Amcor, Winpak Ltd., Berry Global, Syfan, Intertape Polymer Group, Sealed Air Corporation, Mondi Group, Super Olefins, Coveris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collation Shrink Films Market Emerging Trajectories
Active reformulation of shrink energy release profiles and regulatory-driven material substitutions are compressing traditional competitive moats while opening technical differentiation pathways for specialized converters.
Metallocene-catalyzed polyethylene resins with controlled molecular architecture are displacing conventional Ziegler-Natta grades in premium collation applications. Beverage bottlers with high-speed shrink tunnel operations are adopting these materials for their tighter shrink force curves and reduced residual stress. This displacement is compressing margin pools in commodity 50-micron segments while concentrating value capture in thin-gauge specialty formulations.
Europe's F-Gas Regulation is banning hydrofluorocarbon blowing agents in competing foam-based collation alternatives, redirecting unitization demand toward polyethylene shrink solutions. Industrial consequence includes accelerated capital redeployment from polystyrene foam tray lines into polyethylene film extrusion. Food retail chains in Germany and France are most affected, responding with packaging specification updates that exclude foam-based secondary packaging by 2027.
Consolidated beverage bottlers are unbundling after-sales technical service from film procurement contracts, treating shrink tunnel optimization as a separate spend category. Distributor relationships that historically combined supply and technical support are fragmenting, with engineering consultancies capturing the advisory layer. This pattern is most visible in North American bottling operations where private-equity-owned packaging groups are standardizing procurement across acquired regional brands.
Collation Shrink Films Market Segmentation
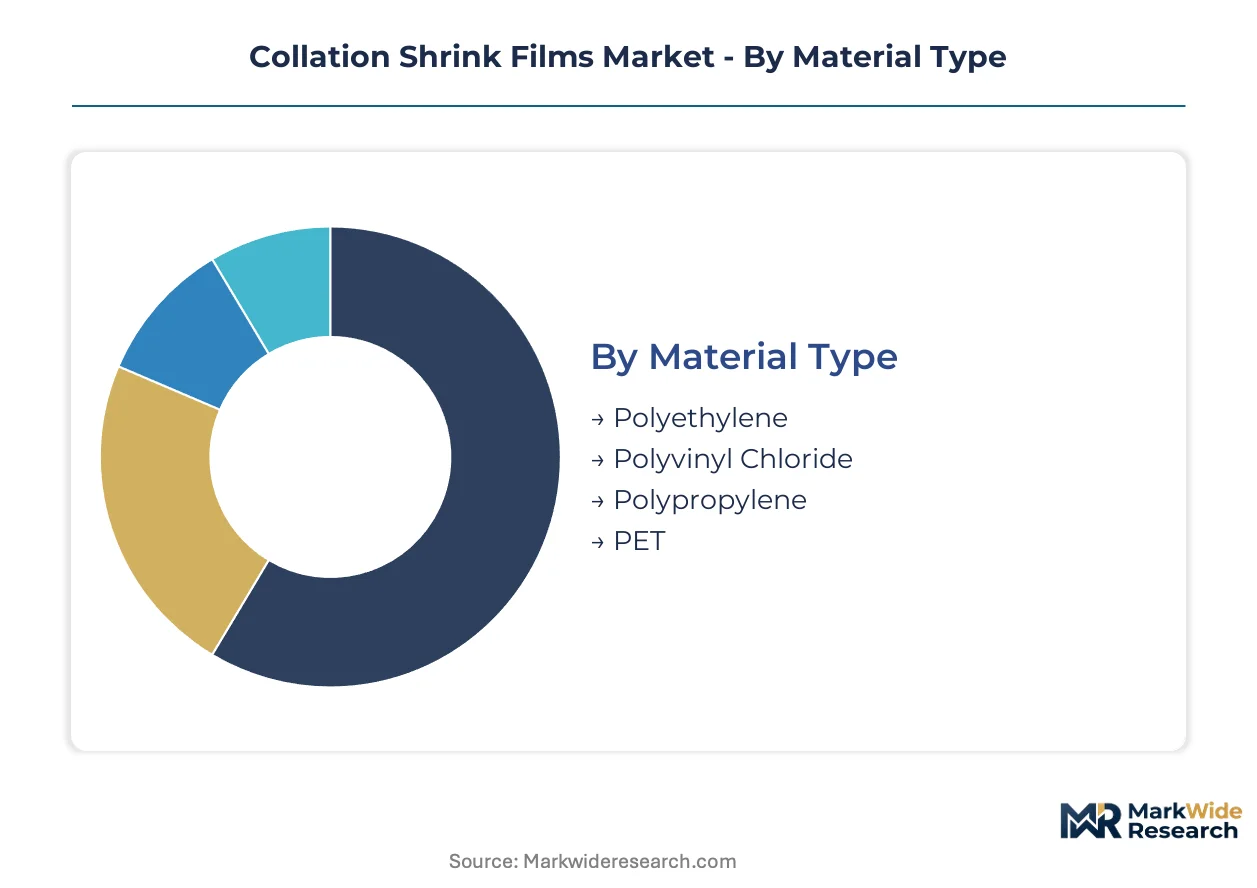
Segmentation in collation shrink films reveals how substitution pressures and regulatory constraints fragment competitive positioning across material chemistry and gauge specifications. Each dimension carries distinct margin profiles and compliance burdens that reshape converter investment priorities.
Material Type:
Polyethylene faces intensifying substitution threat from polypropylene in thin-gauge beverage applications, while PVC alternatives confront REACH-driven plasticizer reformulation costs.
- Polyethylene:Low-density and linear low-density grades dominate volume through cost positioning and mechanical recycling compatibility. Germany's F-Gas Regulation redirects foam-tray demand toward polyethylene shrink solutions in Rhine-Ruhr food retail chains.
- Polyvinyl Chloride:Legacy phthalate plasticizers face ECHA substance evaluation constraints, forcing rapid formulation pivots without mature drop-in replacements for shrink energy release profiles.
- Polypropylene:Cast film variants penetrate premium beverage multipacks seeking higher clarity and stiffness at sub-30 micron gauges.
- PET:Biaxially oriented grades command pharmaceutical secondary packaging where batch traceability requirements filter standard-grade suppliers.
Polyethylene retains volume leadership; PET holds the steepest expansion curve in regulated medical applications.
Application:
Cost tier stratification separates commodity beverage bundling from premium pharmaceutical unitization, with food retail driving downgauge mandates.
- Beverage Packaging:High-speed shrink tunnel operations demand metallocene-catalyzed polyethylene with tight shrink force curves. North American private-equity-owned bottling groups are unbundling technical service from procurement contracts.
- Food Packaging:Germany and France retail chains exclude polystyrene foam trays by 2027, redirecting unitization demand toward polyethylene film extrusion with accelerated capital redeployment.
- Consumer Goods:Electronics and household product multipacks favor printed collation films with direct-to-film inkjet compatibility for variable-data branding.
- Pharmaceutical Packaging:Cleanroom-compatible films for sterile medical device bundling remain underpenetrated, with batch-traceability requirements creating qualification barriers for commodity converters.
Beverage packaging anchors volume concentration; pharmaceutical applications capture the widest margin spreads.
Thickness:
Volume distribution concentrates where gauge reduction intersects load stability requirements, with sub-30 micron development consuming R&D resources.
- 50 Microns:Mature volume anchor where margin pools compressed from commoditization, serving standard beverage and canned goods unitization.
- 30 Microns:Biaxial orientation advances enable material intensity reduction per thousand units while maintaining pack integrity through controlled shrink energy release.
- 75 Microns:Heavy-duty applications for irregular-shaped consumer goods requiring higher puncture resistance and load stability.
- 100 Microns:Industrial bundling of construction materials and bulk paper products where mechanical protection outweighs material efficiency priorities.
50-micron grades retain volume leadership; 30-micron specifications gain share fastest as downgauging mandates tighten.
End User:
Customer type determines procurement sophistication, with consolidated manufacturers extracting technical service unbundling that fragments traditional distributor relationships.
- Manufacturers:Beverage bottlers and food processors drive specification tightening through direct converter relationships, compressing distributor margins.
- Retailers:German and French food retail chains impose packaging specification updates that exclude foam-based secondary packaging, reshaping converter product mix.
- Distributors:Traditional supply-and-technical-support bundles fragment as engineering consultancies capture advisory layers separately from film procurement.
- Online Sellers:E-commerce fulfillment operations generate emerging demand for printed collation films with brand differentiation and damage protection for multipack shipping.
Manufacturers retain procurement volume leadership; online sellers present the steepest demand expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's F-Gas Regulation anchors the regulatory framework reshaping collation shrink film specifications, forcing resin reformulation across multiple jurisdictions while beverage bottlers in Germany's Rhine-Ruhr cluster drive downgauge adoption.
Germany
Beverage bottlers in the Rhine-Ruhr corridor demand sub-30 micron collation films to reduce material intensity per thousand units. REACH restrictions on phthalate plasticizers constrain PVC alternative formulations, pushing converters toward metallocene-catalyzed polyethylene. Düsseldorf-centered packaging operations are consolidating procurement specifications, tightening supply requirements within a 200-kilometer radius.
United States
Private-equity-owned bottling groups across the Midwest and Southeast are unbundling technical service contracts from film procurement, fragmenting traditional distributor relationships. EPA guidelines on volatile organic compound emissions from extrusion operations shape equipment investment requirements for domestic producers. California and Maine extended producer responsibility frameworks create early-mover certification advantages ahead of potential federal harmonization.
France
Food retail chains are excluding polystyrene foam trays from secondary packaging specifications by 2027, redirecting unitization demand toward polyethylene shrink solutions. ECHA substance evaluations continue filtering legacy plasticizers from competing collation alternatives. Paris-based beverage distributors are accelerating specification updates to align with supermarket sustainability mandates.
China
Domestic beverage producers in the Yangtze River Delta are adopting thinner-gauge collation films to meet cost reduction targets amid compressed margin environments. The country's national environmental standards on industrial emissions influence extrusion equipment upgrade cycles. Shanghai-centered packaging converters are expanding biaxial orientation capacity to serve regional bottling operations.
India
Soft drink and bottled water manufacturers in Maharashtra and Gujarat are transitioning from corrugated secondary packaging to shrink-wrapped multipacks for distribution efficiency. Bureau of Indian Standards certification requirements for food-contact plastics govern resin selection decisions. Mumbai-Ahmedabad industrial corridors are attracting film extrusion investments to serve western India's beverage production concentration.
Collation Shrink Films Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the collation shrink films market, with backward integration into resin compounding distinguishing the upper tier from converters dependent on merchant polyethylene supply. The middle layer comprises regional extrusion specialists competing on gauge flexibility and shrink tunnel optimization services. Two dominant competitive moves are reshaping positioning: captive supply chain control over low-density polyethylene feedstock, and dedicated R&D investment in thin-gauge downgauging below 30 microns.
Among integrated packaging conglomerates, Berry Global exemplifies backward integration strategy through in-house resin compounding operations, while Mondi Group anchors the European specialist tier with Austrian-based research infrastructure. Sealed Air Corporation occupies a position bridging both tiers through distribution channel control across beverage bottling networks. These three entities represent distinct competitive archetypes: feedstock-secured volume producer, R&D-driven gauge innovator, and channel-integrated solution provider.
| Leading Market Players |
|---|
| Amcor |
| Winpak Ltd. |
| Berry Global |
| Syfan |
| Intertape Polymer Group |
| Sealed Air Corporation |
| Mondi Group |
| Super Olefins |
| Coveris |
| Others |
Supply Flow & Price Mechanics
Metallocene-catalyzed polyethylene displacement of conventional Ziegler-Natta grades simultaneously redraws supply geography toward specialized petrochemical complexes and compresses pricing power in commodity gauge segments. This substitution dynamic concentrates value capture in thin-gauge specialty formulations while eroding margins in mature 50-micron volume anchors.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between beverage bottlers and converters, with spot purchases limited to emergency volume fills during resin shortage periods. Three-tier pricing structure across premium metallocene grades, standard LLDPE formulations, and economy recycled-content blends reflects certification complexity and shrink tunnel optimization bundling. Pricing pressure stems from downgauging mandates that reduce material intensity per thousand units without proportional value recovery. Private-equity-owned bottling groups exhibit highest price sensitivity through centralized procurement standardization, while pharmaceutical secondary packaging buyers prioritize batch traceability over unit cost.
Supply Chain Analysis
Naphtha-cracker turnaround schedules at Rotterdam-Antwerp-Rhine-Ruhr petrochemical complexes create chokepoint vulnerability for European low-density polyethylene feedstock. Germany, Belgium, and the Netherlands anchor supply concentration for collation-grade resin compounding. Raw material dependencies center on ethylene monomer, metallocene catalyst systems, and post-consumer mechanical recycling feedstock streams. Single-source vulnerability runs through concentrated European cracker capacity with limited Atlantic import alternatives. Distribution feeds from converter extrusion lines through fragmented distributor networks toward bottler shrink tunnel operations, with technical service unbundling accelerating channel restructuring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Collation shrink films are approaching a platform-economics inflection where shrink tunnel optimization data and direct-to-film digital printing interoperability determine converter switching costs and buyer lock-in. The convergence of film substrate specifications with inkjet system compatibility creates ecosystem boundaries that reshape competitive moats.
For Market Incumbents: Shield margin pools in sub-30 micron gauge segments through captive R&D infrastructure for metallocene formulation mastery, while consolidating technical service capabilities that resist unbundling by private-equity bottling groups. Backward integration into resin compounding secures feedstock priority during naphtha-cracker turnaround periods. Certification investment in FDA food-contact substance notifications and EU mechanical recycling quota compliance erects qualification barriers against commodity converters. For New Entrants and Emerging Players: Anchor in pharmaceutical secondary packaging white space where cleanroom-compatible films and batch-traceability requirements filter out established commodity-grade suppliers. India's Maharashtra-Gujarat beverage production corridor presents the most penetrable geography as corrugated-to-shrink transition accelerates. Direct-to-film inkjet integration partnerships offer a go-to-market angle that bypasses traditional distributor technical service relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-owned packaging groups that have standardized procurement across acquired regional brands and fragmented technical service from film supply contracts. Long-term viability across the analysis window favors converters with verified recyclability certification ahead of extended producer responsibility framework expansion. Watch for EU mechanical recycling quota threshold announcements as the inflection signal that determines which material types retain market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive LDPE supply secures priority allocation during European cracker turnaround periods. |
| Thin-Gauge Downgauging R&D Investment | Sub-30 micron biaxial orientation capability captures downgauging mandate-driven specification shifts. |
| Direct-to-Film Digital Printing Partnership | Inkjet system interoperability creates ecosystem switching costs and variable-data branding revenue. |
| Pharmaceutical Cleanroom Certification | Batch-traceability qualification filters commodity competitors from premium margin medical device bundling. |
| Recyclability Verification Program | Mechanical recycling quota compliance ensures market access under EU packaging regulations. |
Methodological Framework
A standing panel of extrusion plant managers, beverage bottler procurement directors, shrink tunnel optimization engineers, and polymer formulation chemists provided ongoing calibration across primary interview rounds. Secondary validation drew from European Chemical Industry Council resin production data, SEC 10-K filings of listed packaging conglomerates, customs trade databases tracking polyethylene film cross-border flows, and EPA emission permit records for US extrusion operations. Bottom-up volume modeling triangulated against top-down value estimates from converter capacity announcements and bottler line expansion disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including material chemistry tier, gauge specification, application end-use, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to disclosed converter capacity utilization rates and bottler multipack line expansion schedules. Industry-specific forecast inputs incorporated F-Gas Regulation implementation timelines and REACH substance evaluation trajectories.
Material uncertainties — resin supply disruption from unplanned cracker outages, mechanical recycling quota threshold revisions, and phthalate plasticizer substitution breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation pacing and substitution elasticity that practitioners should keep alternative scenarios live as EU packaging framework negotiations and US state extended producer responsibility harmonization efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Middle East and Africa Airless Packaging Market
Packaging Barrier Films
Cling Films Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Barrier Bags Market
Packaging Barrier Films
Waterproof Packaging Market
Packaging Barrier Films
Sealant Web Films Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Perforated Packaging Film Market
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market
Packaging Barrier Films
Global Shrink Films Market
Packaging Barrier Films
Transport Protection Film Market