
 Human Immunodeficiency Virus Type 1 (HIV 1) Market | 2026-2036
Human Immunodeficiency Virus Type 1 (HIV 1) Market Size, Share, and Industry Trends Forecast 2026-2036
Human Immunodeficiency Virus Type 1 (HIV 1) Market Foresight
The FDA's streamlined breakthrough therapy designation is rebalancing how manufacturers justify clinical investment for novel antiretroviral modalities. Gilead Sciences leverages its nucleoside reverse transcriptase inhibitor portfolio to sustain manufacturing scale across multiple continents. ViiV Healthcare anchors long-acting injectable development through dedicated HIV-focused R&D infrastructure. Merck & Co. competes with differentiated integrase strand transfer inhibitor formulations that address resistance-concerned patient populations.
Human Immunodeficiency Virus Type 1 is a lentivirus of the Retroviridae family, characterized by RNA genome reverse transcription into host DNA, with virion particles measuring approximately 120 nm in diameter and encoding gag, pol, env, and six accessory genes; its primary commercial purpose centers on enabling sustained virologic suppression and preventing immunologic deterioration in infected individuals. Antiretroviral drugs command the dominant value pool as first-line regimen standardization locks in high-volume procurement contracts, while diagnostic kits represent the fastest-expanding segment as point-of-care nucleic acid testing displaces centralized laboratory workflows. Home care distribution channels are gaining structural traction where self-testing authorization and telemedicine prescribing laws have converged.
FDA, EMA, and WHO prequalification standards collectively determine which formulations gain access to national procurement programs and global donor funding mechanisms, with bioequivalence requirements for generic substitution creating tiered market access tiers. The EU AI Act and GDPR impose emerging compliance burdens on diagnostic platforms that process patient biomarker data through cloud-connected analyzers. Stakeholders must monitor how long-acting antiretroviral label expansions reshape patient adherence economics and whether manufacturing concentration in specific geographies introduces supply vulnerability during health security emergencies.
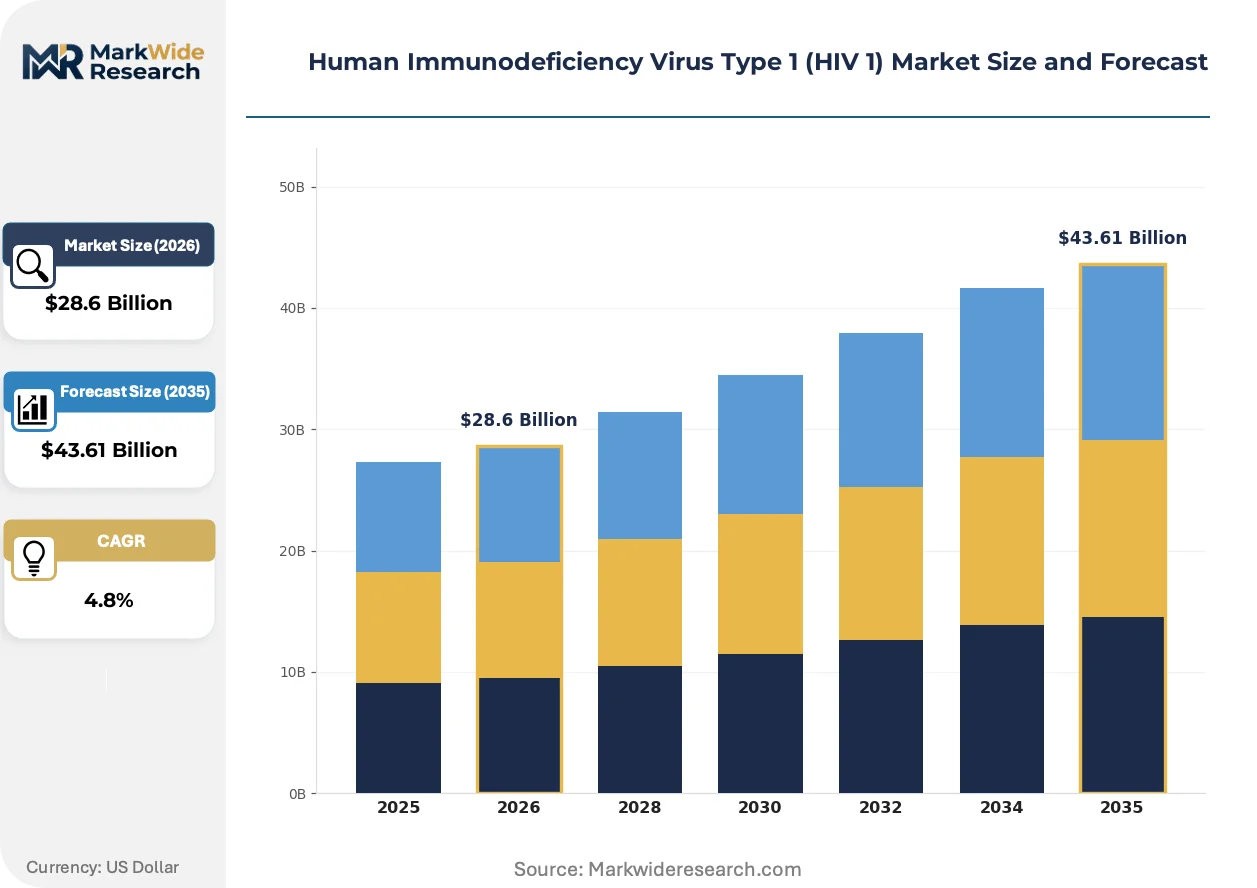
Market Dynamics
Long-acting injectable antiretrovirals are compressing dosing intervals from daily pills to monthly or quarterly administration, fundamentally restructuring patient adherence economics and pharmacy reimbursement models across major HIV treatment markets.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Accelerated approval pathways compress clinical development timelines for novel antiretroviral modalities, enabling faster market entry for innovative formulations.
- Point-of-Care Nucleic Acid Testing:Diagnostic kit manufacturers are displacing centralized laboratory workflows with portable analyzers that deliver same-day viral load results in resource-limited settings.
- Brazil National Treatment Scale-Up:The country's expanded antiretroviral access program is driving hospital-based therapeutic demand through integrated diagnostic-treatment procurement frameworks.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Manufacturing of key antiretroviral intermediates clusters in specific Asian geographies, creating supply vulnerability during health security emergencies.
- Cold Chain Requirements:Long-acting injectable formulations require sustained temperature-controlled distribution infrastructure that remains underdeveloped in sub-Saharan African markets.
- EMA Bioequivalence Standards:Stringent generic substitution requirements create tiered market access barriers that delay low-cost therapeutic entry in European procurement programs.
Strategic Opportunities
- Home Care Distribution Channels:Self-testing authorization and telemedicine prescribing laws in the United States are converging to enable direct-to-patient antiretroviral delivery models.
- WHO Prequalification Alignment:Harmonized quality standards for generic formulations unlock access to global donor funding mechanisms and national procurement programs in low-income countries.
- AI-Driven Adherence Monitoring:Machine learning platforms processing patient biomarker data through cloud-connected diagnostic analyzers are creating new service revenue streams.
Industry Challenges
- EU AI Act Compliance Burden:Diagnostic platforms processing patient biomarker data through cloud-connected analyzers face emerging GDPR and artificial intelligence governance requirements that extend certification timelines.
- Integrase Strand Transfer Inhibitor Resistance Surveillance:Manufacturers must maintain specialized laboratory networks to monitor emerging viral mutations that compromise therapeutic efficacy in treated populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Immunodeficiency Virus Type 1 (HIV 1) Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiretroviral Drugs, Diagnostic Kits, Enzyme Immunoassays, Biologics Application: Therapeutic, Preventive, Diagnostic, Routine Screening End User: Hospitals, Clinics, Laboratories, Home Care Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Direct Sales |
| Companies Covered | Gilead Sciences, ViiV Healthcare, Merck & Co., Bristol-Myers Squibb Company, Johnson & Johnson, AbbVie, Boehringer Ingelheim International GmbH, Janssen Pharmaceuticals, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Immunodeficiency Virus Type 1 (HIV 1) Market Shifts & Advancements
Antiretroviral development is pivoting from oral daily regimens toward extended-release formulations that fundamentally alter how patients interact with lifelong therapy management systems.
Long-acting cabotegravir-rilpivirine injectable suspensions are expanding into first-line maintenance therapy for virologically suppressed adults. Treatment-experienced patients in the United States and Western Europe are adopting these formulations at accelerating rates as reimbursement frameworks adapt to quarterly pharmacy visits. This technology is expanding into adherence-challenged populations previously managed through intensive case management, compressing the role of traditional directly observed therapy programs.
EMA's accelerated assessment pathway for medicines addressing unmet medical needs is shortening regulatory review periods for novel antiretroviral combinations. The policy compresses time-to-market for manufacturers investing in resistance-optimized formulations. European hospital pharmacies and outpatient clinics are responding by pre-positioning procurement contracts to capture early access benefits.
Patient self-administration of antiretroviral therapy is displacing clinic-dependent models as home testing authorization spreads. Retail pharmacy chains and mail-order distributors are capturing volume previously routed through hospital outpatient departments. This behavioral shift is most visible in the United States, where telemedicine prescribing laws enable remote therapeutic monitoring without mandatory clinical visits.
Human Immunodeficiency Virus Type 1 (HIV 1) Market Segmentation
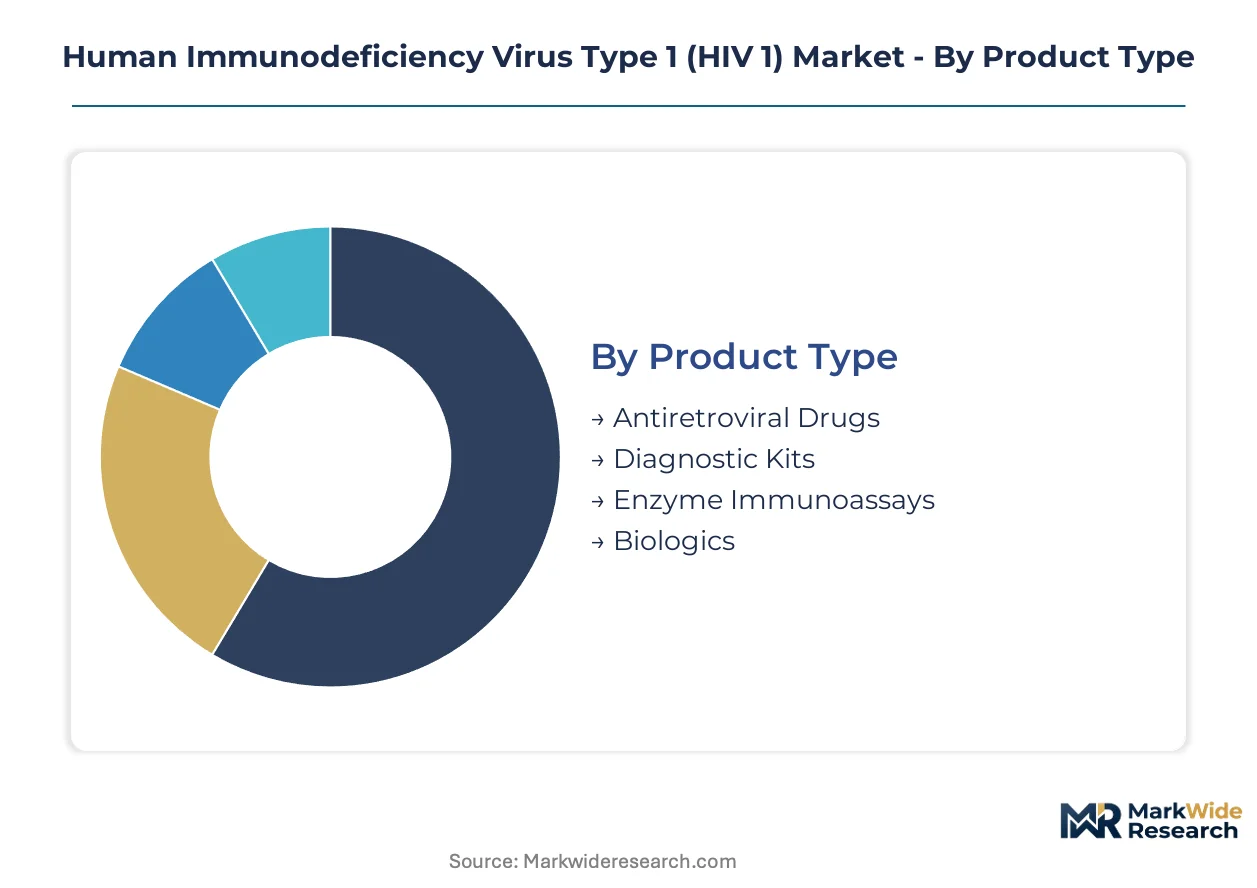
Segmentation in the HIV 1 market reflects divergent regulatory pathways and procurement economics. Product categories face distinct FDA, EMA, and WHO prequalification standards, while distribution channels operate under jurisdiction-specific pharmacy and telemedicine laws.
Product Type:
Certification burdens vary sharply across this category, with antiretroviral drugs requiring FDA new drug applications or abbreviated pathways, diagnostic kits needing CLIA waivers or CE-IVD marking, and biologics triggering specialized biosimilar frameworks.
- Antiretroviral Drugs:Nucleoside reverse transcriptase inhibitors, non-nucleoside reverse transcriptase inhibitors, protease inhibitors, and integrase strand transfer inhibitors constitute the dominant formulation classes. Hospital procurement programs in the United States and Brazil concentrate demand through volume-based tendering mechanisms that lock in multi-year supply agreements.
- Diagnostic Kits:Point-of-care nucleic acid testing platforms and rapid antibody detection systems enable same-day result delivery. Resource-limited settings in sub-Saharan African markets are displacing centralized laboratory workflows as WHO prequalification unlocks Global Fund procurement eligibility.
- Enzyme Immunoassays:Laboratory-based serological screening tools with established sensitivity specifications for blood bank and clinical reference applications.
- Biologics:Monoclonal antibodies and therapeutic vaccines under development through specialized biologics license application pathways.
Antiretroviral drugs sit at the top of the volume ranking, with diagnostic kits climbing the fastest.
Application:
Cost tier differentiation separates high-complexity therapeutic management from standardized prevention and screening programs, with reimbursement intensity declining across the spectrum.
- Therapeutic:Sustained virologic suppression regimens for treatment-naive and treatment-experienced patients. Hospital outpatient departments in South Africa and the United States capture the majority of prescription volume through integrated care programs.
- Preventive:Pre-exposure prophylaxis and post-exposure prophylaxis formulations for seronegative populations. Urban sexual health clinics in Western European markets are expanding prescription access through pharmacist-initiated protocols.
- Diagnostic:Viral load monitoring and resistance testing for treatment optimization. Reference laboratories maintain concentrated testing capacity due to equipment and personnel requirements.
- Routine Screening:Population-level serostatus ascertainment through community-based testing campaigns. Home self-testing authorization in the United States is redirecting volume from clinical sites to retail distribution.
Therapeutic applications command the largest revenue pool, with preventive use expanding most quickly.
End User:
Customer type determines procurement authority, with hospitals exercising centralized purchasing power while home care segments fragment across individual prescription fulfillment.
- Hospitals:Academic medical centers and public district hospitals managing complex antiretroviral resistance cases. Brazil's national health service consolidates procurement through federal tendering mechanisms that specify bioequivalence requirements.
- Clinics:Community health centers and sexual health facilities providing first-line therapy initiation. Federally qualified health centers in the United States qualify for drug pricing programs that compress acquisition costs.
- Laboratories:Reference and hospital-affiliated testing facilities processing viral load and genotyping assays. Cold chain infrastructure requirements limit geographic placement of high-complexity molecular diagnostics.
- Home Care:Self-administered therapy and testing models enabled by telemedicine prescribing laws. Mail-order pharmacy networks in the United States are capturing maintenance therapy volume through automated refill programs.
Hospitals retain the dominant procurement position, with home care gaining share fastest.
Distribution Channel:
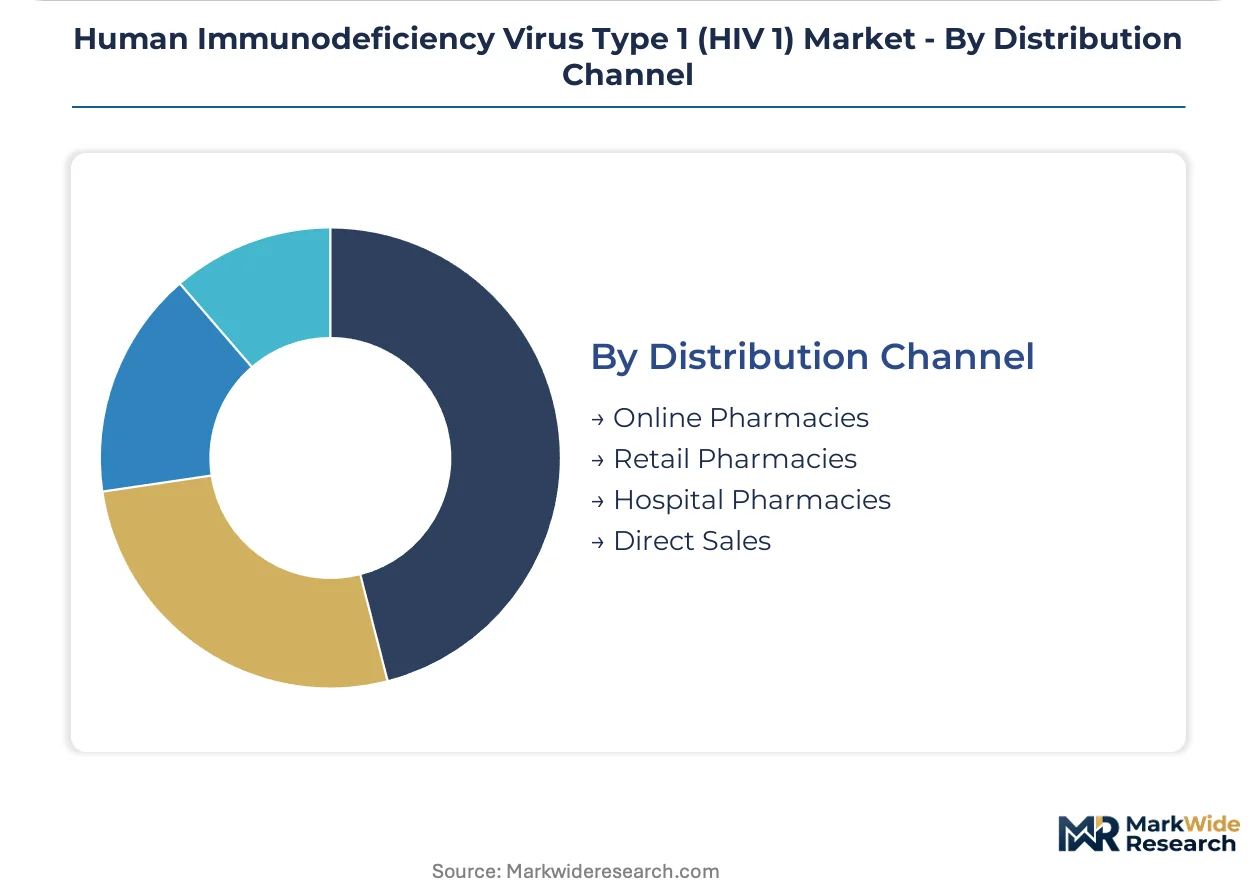
Supply concentration varies by channel, with hospital pharmacies captive to institutional formularies while retail and online channels compete on convenience and price transparency.
- Online Pharmacies:Mail-order and digital prescription fulfillment platforms with automated adherence packaging. United States-based specialty pharmacies manage prior authorization processing for complex antiretroviral regimens.
- Retail Pharmacies:Chain and independent community pharmacies with walk-in consultation services. Urban markets in South Africa leverage retail presence for same-day antiretroviral pickup.
- Hospital Pharmacies:Institution-based dispensing integrated with electronic health record systems. Academic medical centers maintain restricted distribution for investigational and high-cost formulations.
- Direct Sales:Manufacturer-to-institution contracting for large-volume procurement. National treatment programs in Brazil and South Africa utilize direct negotiation for first-line regimen standardization.
Hospital pharmacies handle the largest prescription volume, with online pharmacies showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized infectious disease clinicians and HIV research scientists concentrate in academic medical centers across five countries where national treatment programs drive procurement scale and regulatory innovation.
United States
FDA breakthrough therapy designations accelerate novel antiretroviral approvals, compressing development timelines for long-acting injectables. The Ryan White HIV/AIDS Program consolidates hospital outpatient purchasing through federally qualified health centers. Baltimore and San Francisco maintain concentrated research infrastructure where Johns Hopkins and UCSF anchor resistance surveillance networks.
Brazil
Federal tendering mechanisms through the national health service standardize first-line regimen procurement across 27 states. ANVISA bioequivalence requirements for generic substitution create tiered access frameworks that favor domestic manufacturers. São Paulo's hospital network captures the majority of therapeutic volume through integrated diagnostic-treatment programs.
South Africa
The national Department of Health scales antiretroviral access through district hospital networks serving 7.8 million people on treatment. WHO prequalification alignment unlocks Global Fund procurement for point-of-care diagnostic platforms. Gauteng province concentrates molecular testing capacity in Johannesburg academic medical centers processing viral load monitoring.
Germany
EMA accelerated assessment pathways shorten regulatory review for resistance-optimized formulations addressing treatment-experienced patients. The G-BA federal joint committee determines reimbursement levels for hospital-based antiretroviral dispensing. Berlin and Cologne host specialized outpatient clinics managing complex salvage therapy cases through integrated pharmacy services.
India
CDSCO manufacturing licenses for antiretroviral active pharmaceutical ingredients supply global procurement programs through WHO prequalified facilities. The National AIDS Control Organization distributes first-line regimens through 1,600 ART centers spanning 28 states. Hyderabad and Ahmedabad cluster generic formulation production for export to African and Southeast Asian markets.
Human Immunodeficiency Virus Type 1 (HIV 1) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three structural tiers. Large pharmaceutical groups leverage cross-therapeutic manufacturing infrastructure to sustain nucleoside reverse transcriptase inhibitor supply. Mid-scale biotechnology firms concentrate R&D investment on long-acting injectable platforms. Emerging generic manufacturers capture volume through WHO prequalification and national tender participation. Portfolio diversification and geographic licensing partnerships constitute the dominant competitive moves reshaping market access.
Within the diversified pharmaceutical tier, Gilead Sciences and Bristol-Myers Squibb occupy positions exemplifying manufacturing scale across multiple continents. ViiV Healthcare represents the pure-play specialist archetype, anchoring HIV-dedicated research infrastructure without cross-therapeutic portfolio distraction. These three entities collectively illustrate how regulatory strategy and therapeutic focus determine competitive positioning in antiretroviral development.
| Leading Market Players |
|---|
| Gilead Sciences |
| ViiV Healthcare |
| Merck & Co. |
| Bristol-Myers Squibb Company |
| Johnson & Johnson |
| AbbVie |
| Boehringer Ingelheim International GmbH |
| Janssen Pharmaceuticals |
| GlaxoSmithKline |
| Others |
Supply & Pricing Matrix
Federal tendering mechanisms in Brazil and volume-based procurement by South Africa's national health service are compressing margins for antiretroviral manufacturers while forcing supply consolidation toward WHO-prequalified facilities that can meet stringent bioequivalence standards at scale.
Pricing Analysis
The bundled-vs-unbundled service split separates diagnostic-therapy integration packages from standalone pharmaceutical procurement. Three-tier pricing structure across originator, WHO-prequalified generic, and non-prequalified generic levels tracks certification status and regulatory alignment. Pricing pressure stems from national treatment program scale-up in low-income markets where Global Fund eligibility dictates supplier selection. Price differentiation between hospital procurement tiers and retail pharmacy channels reflects volume scale and cold chain service bundling, with home care segments showing highest price sensitivity due to out-of-pocket exposure.
Supply Chain Analysis
Single-source vulnerability sits with active pharmaceutical ingredient manufacturing concentrated in India and China, where CDSCO and NMPA-licensed facilities feed global formulation networks. Key inputs include tenofovir intermediates, dolutegravir precursors, and long-acting injectable suspension polymers. Tariff exposure on temperature-controlled logistics equipment amplifies distribution costs for cold chain-dependent formulations. Distribution runs through hospital pharmacy networks for therapeutic regimens, direct manufacturer contracting for national programs, and specialty pharmacy channels for home care delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HIV 1 market functions as a regulatory compounder where FDA breakthrough therapy designations and EMA accelerated assessment pathways create demand inflection points that reward preemptive clinical investment.
For Market Incumbents: To counter long-acting injectable displacement of oral daily regimens, incumbents must secure backward integration into API manufacturing to defend margin position against generic erosion, while anchoring resistance surveillance networks that lock in treatment-experienced patient populations through specialized laboratory services. For New Entrants and Emerging Players: Capture adherence-challenged patient segments in United States telemedicine-enabled markets where self-administration authorization and mail-order pharmacy networks create direct-to-patient access without hospital formulary gatekeeping, leveraging point-of-care diagnostic bundling as entry wedge. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play HIV specialists possessing dedicated R&D infrastructure and long-acting formulation platforms, where regulatory milestone density over a multi-year horizon outpaces diversified pharmaceutical conglomerates. Watch for inflection in integrase strand transfer inhibitor resistance surveillance data signaling salvage therapy demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Injectable Development | FDA breakthrough designation compresses timelines for cabotegravir-rilpivirine label expansions into first-line maintenance. |
| Point-of-Care Diagnostic Integration | WHO prequalification unlocks Global Fund procurement for same-day viral load platforms in sub-Saharan Africa. |
| API Manufacturing Scale-Up | CDSCO-licensed facilities in Hyderabad anchor supply security for tenofovir and dolutegravir intermediates. |
| Telemedicine Prescribing Infrastructure | United States state law convergence enables automated refill programs through specialty pharmacy networks. |
| Resistance Surveillance Network Expansion | Johns Hopkins and UCSF anchor genotyping capacity that guides salvage therapy selection in treatment-experienced populations. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down API production tracking forms the analytical core, combining primary interviews with formulary directors, regulatory affairs leads, antiretroviral program managers, and GPO contracts managers against secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and national tender databases.
Input-output matrices map antiretroviral demand across treatment line, dosage form, administration route, and patient population dimensions, with CAGRs derived from regression analysis of procurement volume trajectories and pricing elasticity coefficients throughout the forecast period. Forecast inputs incorporate long-acting formulation adoption curves and point-of-care diagnostic displacement rates.
Regulatory approval delays, API supply disruptions, and reimbursement policy reversals are the dominant revision risks to modeled assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Mosquito-Borne Diseases Treatment Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Difficile Infections (Clostridium Difficile Associated Disease) Market
Infectious Disease
Gram Positive Bacterial Infections Market
Infectious Disease
Valley Fever Market
Infectious Disease
Actinomycosis Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Acute Viral Rhinosinusitis Treatment Market
Infectious Disease
Varicella Zoster Infection Treatment Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Direct-Acting Antiviral Medicines Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Pyomyositis Market
Infectious Disease
Burkholderia Infections Market