
 Retropharyngeal Abscess Market | 2026-2036
Retropharyngeal Abscess Market Size, Share, and Industry Trends Forecast 2026-2036
Retropharyngeal Abscess Market Outlook
Asset-light diagnostic leasing models is rewriting capital deployment for hospital microbiology labs. Abbott Laboratories leverages its point-of-care platform to reduce turnaround time for abscess culture identification. F. Hoffmann-La Roche AG anchors its position through automated PCR systems that sustain high-throughput pathogen detection. Bio-Rad Laboratories Inc. specializes in multiplex panels that differentiate aerobic and anaerobic isolates from deep neck specimens.
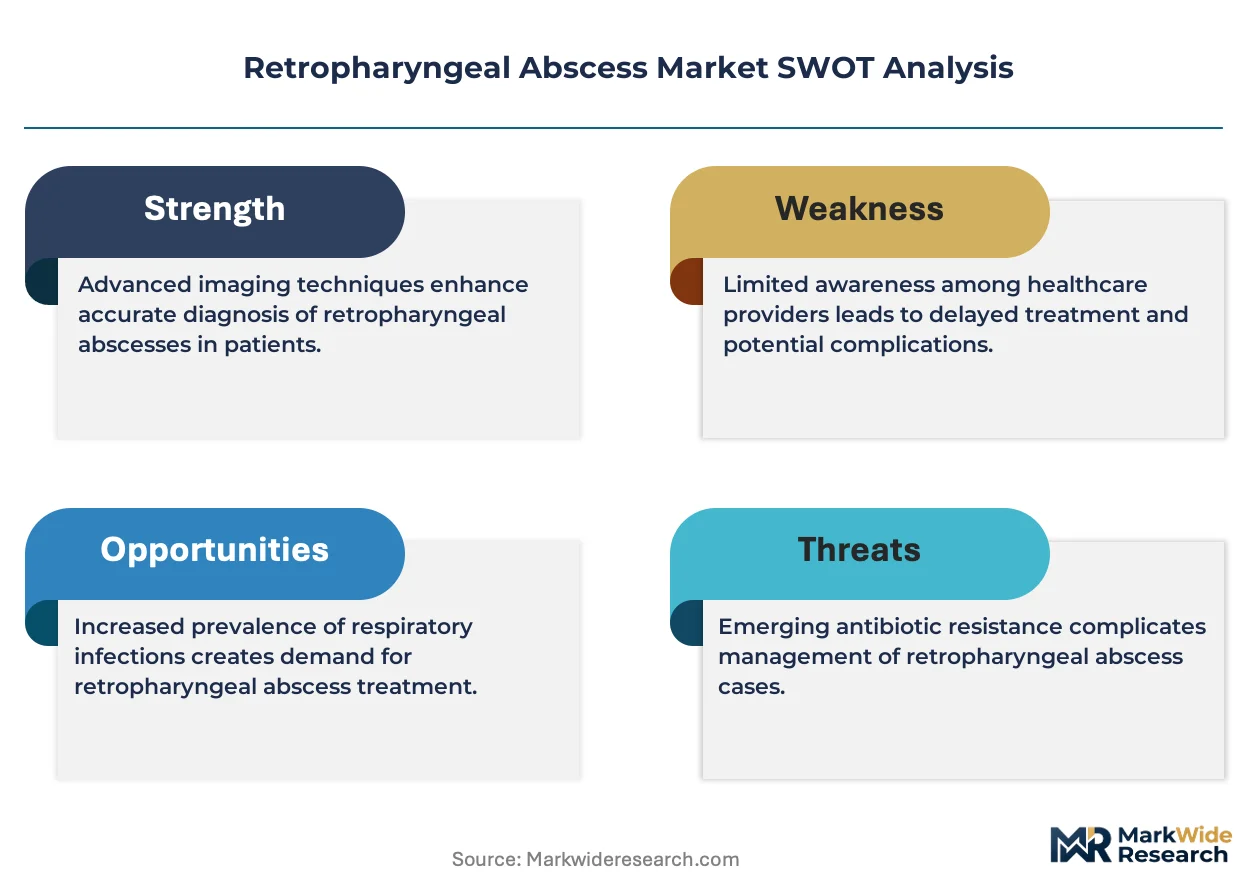
A retropharyngeal abscess constitutes a purulent collection within the potential space between the anterior cervical vertebrae and the posterior pharyngeal wall, typically arising from suppurative lymphadenitis of retropharyngeal nodes in children or direct extension from adjacent odontogenic sources in adults. The condition demands urgent airway protection, empiric broad-spectrum antibiotics targeting polymicrobial flora including Streptococcus pyogenes and respiratory anaerobes, and surgical drainage when fluctuance or airway compromise develops. Antibiotics generate the largest revenue pool among product types due to prolonged IV-to-oral stepdown protocols, while diagnostic imaging grows fastest as contrast-enhanced CT becomes standard for abscess localization and airway assessment. Emergency departments capture disproportionate margin contribution among end users given the acuity-driven reimbursement structure and mandatory specialist consultation requirements.
FDA antimicrobial stewardship mandates restrict empirical broad-spectrum antibiotic selection, pushing hospitals toward culture-directed therapy and rapid diagnostic adoption. ISO 15189 accreditation requirements for clinical microbiology laboratories elevate quality standards for abscess specimen processing and reporting. Stakeholders must monitor evolving resistance patterns in deep neck space isolates and align diagnostic platform investments with stewardship compliance thresholds.
Market Dynamics
FDA antimicrobial stewardship mandates are compressing empirical prescribing windows and forcing rapid diagnostic adoption across emergency departments managing deep neck space infections.
Growth Catalysts
- Stewardship Compliance Pressure:FDA antimicrobial stewardship programs mandate culture-directed therapy within 48 hours, accelerating hospital investment in rapid pathogen identification platforms for abscess specimens.
- Emergency Department Volume Concentration:Tertiary referral networks in the United States manage complex airway cases, creating dedicated deep neck infection protocols that standardize imaging and drainage procedures.
- Point-of-Care Platform Diffusion:Automated PCR systems deployed at bedside are reducing turnaround times for polymicrobial identification from deep neck specimens.
Market Restraints
- Antibiotic Pipeline Contraction:Novel agents targeting anaerobic respiratory flora face limited commercial incentives, restricting options for resistant polymicrobial infections.
- Imaging Access Disparities:Contrast-enhanced CT availability concentrates in urban academic centers, leaving rural emergency departments dependent on transfer protocols.
- Specialist Consultation Bottlenecks:Otolaryngology and anesthesia coverage gaps in community hospitals delay definitive airway management and surgical drainage.
Strategic Opportunities
- Underpenetrated Pediatric Protocols:India lacks standardized suppurative lymphadenitis pathways, creating white space for guideline implementation and diagnostic platform placement.
- Multiplex Panel Expansion:Differentiation of aerobic and anaerobic isolates from single deep neck specimens enables targeted therapy selection and stewardship compliance.
- Leasing Model Penetration:Asset-light diagnostic arrangements reduce capital barriers for mid-tier hospitals entering microbiology automation.
Industry Challenges
- Microbiology Skill Shortages:Clinical laboratories face recruitment gaps for anaerobic culture expertise, delaying accurate isolate identification.
- ISO 15189 Accreditation Burden:Quality management system implementation for abscess specimen processing demands sustained documentation investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retropharyngeal Abscess Market |
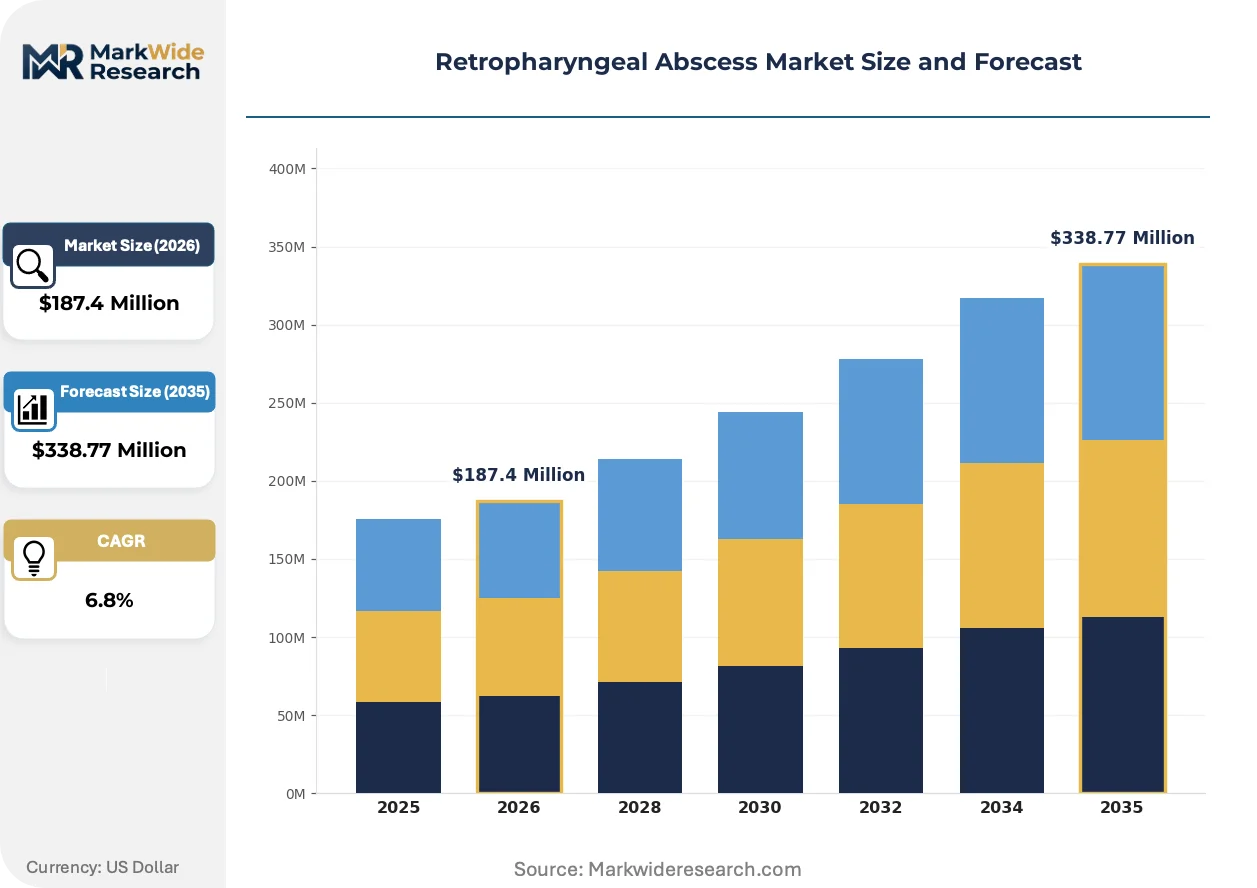
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Surgery, Diagnostic Imaging, Supportive Care End User: Hospitals, Outpatient Clinics, Emergency Departments, Urgent Care Centers Delivery Mode: Intravenous, Oral, Topical, Invasive Age Group: Pediatric, Adult, Geriatric, Others |
| Companies Covered | DiaSorin Inc., Bio-Rad Laboratories Inc., Abbott Laboratories, F. Hoffmann-La Roche AG, Johnson & Johnson, Medtronic, Merck KGaA, GlaxoSmithKline plc, Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retropharyngeal Abscess Market Strategic Shifts
Diagnostic velocity and stewardship compliance are converging to reshape capital deployment patterns across hospital microbiology operations.
Multiplex PCR panels targeting deep neck pathogens are collapsing the window between specimen collection and targeted antibiotic selection. Emergency departments with embedded platforms achieve same-shift identification of Streptococcus pyogenes and respiratory anaerobes. This compression eliminates empirical broad-spectrum coverage days and aligns prescribing with FDA stewardship thresholds.
EMA microbiological data submission requirements for new antibiotics are tightening evidentiary standards for polymicrobial infection indications. Developers must now demonstrate anaerobic coverage against validated deep neck space isolates. European hospital formularies are responding by restricting empirical carbapenem use pending rapid diagnostic results.
Academic medical centers are unbundling after-hours specialist consultation from bundled emergency reimbursement. Standalone tele-otolaryngology contracts now cover airway assessment for transferred deep neck infection cases. This arrangement concentrates margin capture at tertiary hubs while decompressing community hospital transfer decisions.
Retropharyngeal Abscess Market Segmentation
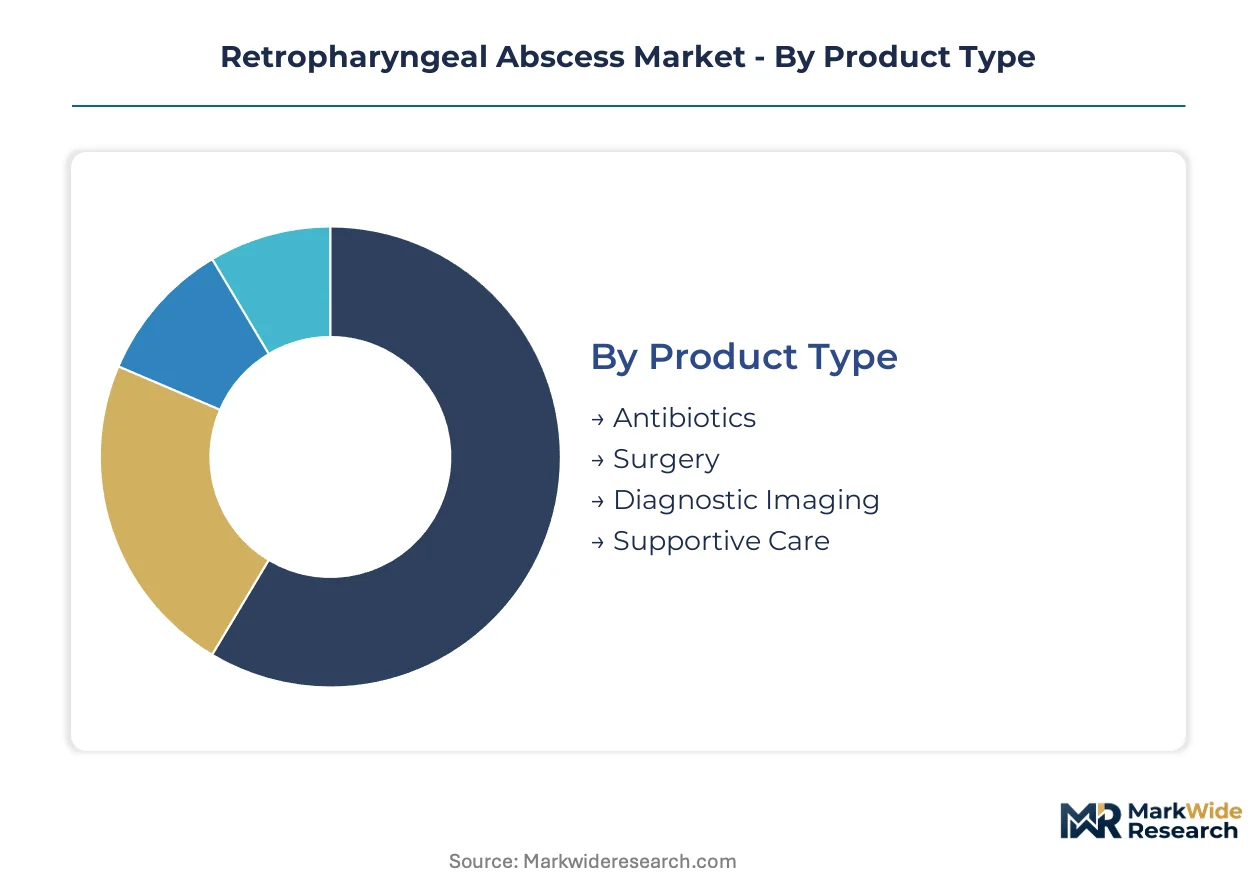
Retropharyngeal abscess management spans acute intervention through prolonged stepdown protocols, creating divergent replenishment cycles across product categories. Segmentation reveals where capital equipment investments concentrate versus consumable-driven recurring revenue streams.
Product Type:
Antibiotics turn over fastest through IV-to-oral conversion protocols, while surgical instruments cycle slowest through sterilization reuse. Diagnostic imaging platforms occupy the middle ground with 5-7 year replacement horizons.
- Antibiotics:Empiric broad-spectrum agents targeting Streptococcus pyogenes and respiratory anaerobes dominate initial therapy. United States tertiary centers drive demand through prolonged IV-to-oral stepdown protocols mandated by FDA antimicrobial stewardship programs.
- Diagnostic Imaging:Contrast-enhanced CT systems localize abscess collections and assess airway compromise. Emergency departments in urban academic centers capture disproportionate utilization as frontline sites for deep neck space infection triage.
- Surgery:Drainage procedures address fluctuance or airway compromise through transoral or transcervical approaches.
- Supportive Care:Airway management and nutritional support address secondary complications during acute phases.
Antibiotics dominate installed base through recurring prescription volumes. Diagnostic imaging is where expansion concentrates as contrast-enhanced CT becomes standard for abscess localization.
End User:
Margin capture stratifies sharply by acuity level, with highest-intensity settings commanding premium reimbursement structures.
- Emergency Departments:Frontline management of airway compromise and sepsis stabilization. United States tertiary referral networks standardize deep neck infection protocols that mandate specialist consultation and advanced imaging.
- Hospitals:Inpatient surgical drainage and IV antibiotic administration for complicated cases.
- Urgent Care Centers:Initial recognition and stabilization before transfer to higher-acuity settings.
- Outpatient Clinics:Follow-up care and oral antibiotic completion monitoring.
Emergency departments dominate installed base through acuity-driven procedure concentration. Hospital inpatient units are where expansion concentrates as transfer protocols formalize.
Delivery Mode:
Route selection follows clinical trajectory from acute stabilization through convalescence.
- Intravenous:Empiric therapy during acute phases with hospitalization. United States emergency departments initiate broad-spectrum coverage pending culture results under FDA stewardship mandates.
- Oral:Stepdown continuation after clinical improvement and pathogen identification.
- Invasive:Surgical drainage and airway interventions for complicated collections.
- Topical:Adjunctive applications in postoperative wound management.
Intravenous delivery dominates installed base through mandatory initial hospitalization. Oral conversion is where expansion concentrates as stewardship programs shorten IV duration.
Age Group:
Epidemiological patterns split between pediatric lymphatic origin and adult odontogenic extension.
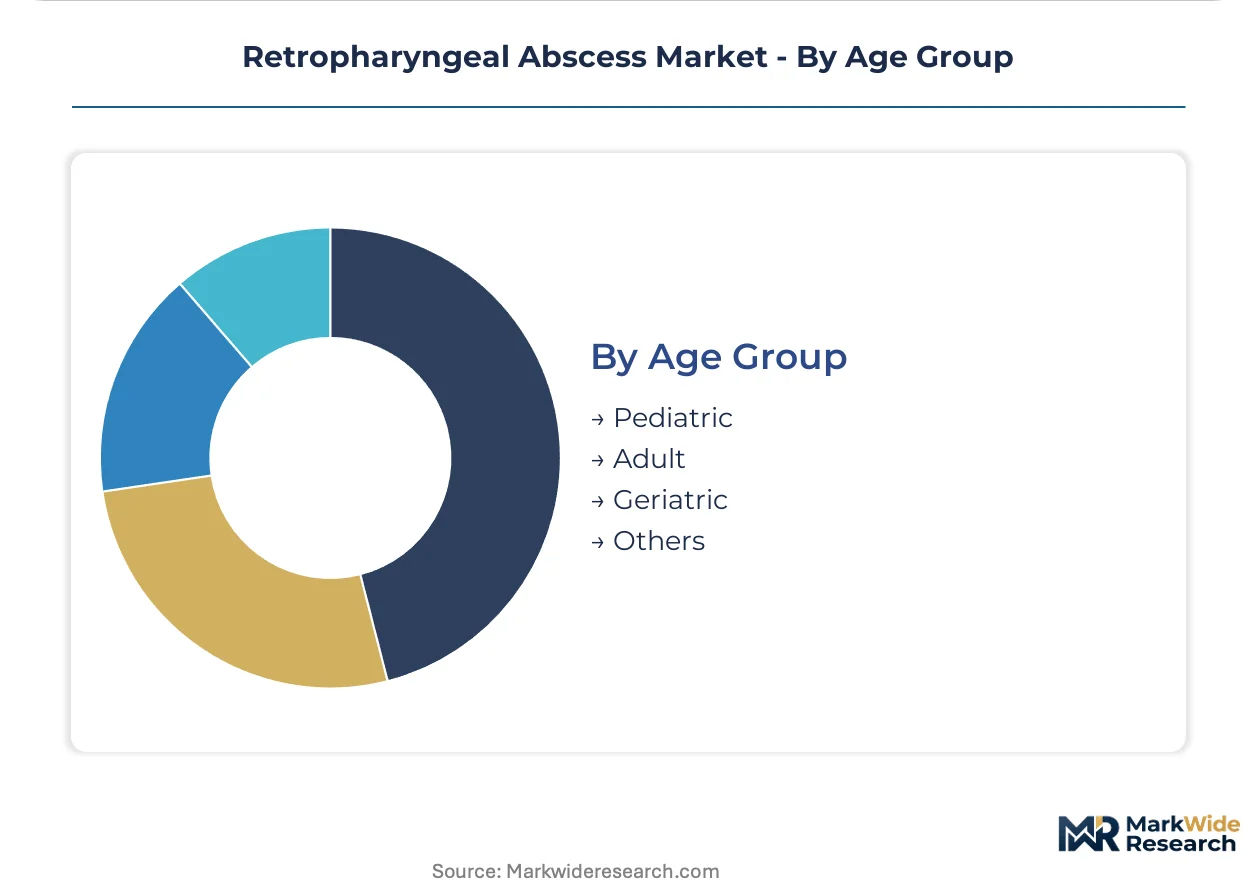
- Pediatric:Suppurative retropharyngeal lymphadenitis from upper respiratory infections. United States children's hospitals maintain dedicated airway teams for rapid sequence intubation protocols.
- Adult:Direct extension from odontogenic or pharyngeal sources.
- Geriatric:Atypical presentations with higher comorbidity burden.
- Others:Immunocompromised hosts with unusual pathogen profiles.
Pediatric cases dominate installed base through seasonal respiratory infection patterns. Adult presentations are where expansion concentrates as odontogenic sources persist in aging populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA antimicrobial stewardship mandates and EMA microbiological data requirements are redirecting hospital procurement budgets toward rapid diagnostic platforms across major healthcare markets.
United States
Tertiary referral networks in Boston, Houston, and Los Angeles manage complex airway cases through dedicated deep neck infection protocols. FDA antimicrobial stewardship programs mandate culture-directed therapy within 48 hours, accelerating point-of-care PCR adoption in emergency departments. The Southeast corridor from Atlanta to Miami concentrates pediatric case volume through children's hospital networks.
Germany
EMA microbiological data submission requirements for new antibiotics tighten evidentiary standards for polymicrobial infection indications. German hospital formularies restrict empirical carbapenem use pending rapid diagnostic results from automated PCR systems. The Rhine-Ruhr metropolitan cluster anchors diagnostic platform distribution into Central European healthcare networks.
India
Suppurative lymphadenitis in pediatric populations drives demand for standardized treatment pathways in underpenetrated markets. CDSCO regulatory frameworks for clinical microbiology laboratories elevate quality standards for abscess specimen processing. Maharashtra and Karnataka states concentrate private hospital investment in emergency department infrastructure.
Japan
PMDA oversight of antimicrobial resistance surveillance shapes hospital formulary decisions for deep neck space infections. METI industrial policy supports domestic manufacturing of automated diagnostic systems. The Kanto region surrounding Tokyo maintains the highest density of tertiary emergency departments with embedded microbiology platforms.
United Kingdom
NHS antimicrobial resistance strategies compress empirical prescribing windows in emergency departments managing airway compromise. MHRA guidance on rapid diagnostic validation accelerates procurement of multiplex PCR panels. The Greater Manchester and West Midlands hospital networks standardize deep neck infection transfer protocols.
Retropharyngeal Abscess Market Competitive Environment
On the supply side, the industry is tiered between multinational diagnostic conglomerates and specialized microbiology platform developers. Abbott Laboratories and F. Hoffmann-La Roche AG anchor the upper tier through integrated point-of-care and laboratory automation portfolios. Bio-Rad Laboratories Inc. and DiaSorin Inc. occupy specialist positions in multiplex pathogen detection. Competitive moves concentrate on diagnostic velocity improvements and antimicrobial stewardship compliance certification.
Among Swiss and German pharmaceutical-diagnostics conglomerates, F. Hoffmann-La Roche AG and Merck KGaA exemplify the integrated health science archetype spanning therapeutics and diagnostic platforms. Abbott Laboratories represents the American diversified medical technology model with emergency department point-of-care penetration. Bio-Rad Laboratories Inc. occupies the specialized life science research-to-clinical translation position within the competitive set.
| Leading Market Players |
|---|
| DiaSorin Inc. |
| Bio-Rad Laboratories Inc. |
| Abbott Laboratories |
| F. Hoffmann-La Roche AG |
| Johnson & Johnson |
| Medtronic |
| Merck KGaA |
| GlaxoSmithKline plc |
| Sanofi S.A. |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Antwerp pharmaceutical freight corridor channels diagnostic platform shipments from German and Swiss manufacturing hubs into emergency departments across Western Europe, with freight cost volatility compressing margins on mid-tier multiplex PCR systems while amplifying price spreads between ISO 15189-accredited premium instruments and non-certified alternatives.
Pricing Analysis
Certification level creates the primary spread between diagnostic platforms, with FDA-cleared and CE-IVD marked systems commanding three-tier pricing structure across premium, standard, and economy levels based on throughput capacity and anaerobic detection specificity. Price differentiation hinges on embedded software for antimicrobial stewardship compliance reporting, with integrated platforms capturing premium positioning. Cost compression in the standard tier is intensifying because hospital procurement committees consolidate vendor contracts under GPO frameworks. Pediatric emergency departments exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize performance over acquisition cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for optical components and thermal cycling modules essential to PCR platform manufacturing. Manufacturing concentrates in Germany, Switzerland, and the United States for finished diagnostic systems, with semiconductor components drawn from Taiwan and South Korea. Raw material dependencies span precision optics, rare-earth magnets for fluidic systems, and specialized plastics for consumable cartridges. Single-source vulnerability persists for high-resolution CCD sensors. Distribution runs through regional diagnostic equipment distributors with field service engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retropharyngeal abscess management represents a service-attach opportunity where consumable cartridge revenue and embedded software subscriptions expand faster than capital equipment sales, particularly as emergency departments adopt per-test leasing arrangements over outright platform purchases.
For Market Incumbents: Build switching-cost moats through antimicrobial stewardship compliance software that locks hospital formularies into integrated diagnostic-therapeutic workflows. Incumbent diagnostic conglomerates should deepen backward integration into anaerobic culture media production to secure consumable supply against emerging platform competitors. FDA 510(k) pathway expertise constitutes a defendable barrier given the evidentiary burden for polymicrobial detection claims.
For New Entrants and Emerging Players: Mid-market community hospitals in the United States Southeast and Midwest represent the most penetrable entry point, as these facilities lack embedded PCR platforms yet face identical FDA stewardship mandates as academic centers. A go-to-market angle anchored to asset-light leasing models with inclusive service contracts bypasses capital budget constraints that favor incumbent relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core microbiology divisions with established anaerobic culture expertise but subscale automation portfolios. Long-term viability rests on diagnostic velocity improvement and stewardship compliance certification as defensible positioning. The signal to watch is CDSCO regulatory acceleration in India, which would validate emerging market expansion strategies and trigger valuation repricing for platforms with tropicalized supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Stewardship Software Integration | FDA compliance dashboards embedded in diagnostic platforms lock hospital formularies into recurring subscription revenue streams. |
| Point-of-Care Platform Miniaturization | Bedside PCR systems reduce turnaround times for deep neck specimens below the 48-hour stewardship mandate threshold. |
| Leasing Model Penetration | Per-test arrangements with inclusive service contracts bypass capital budget barriers in mid-tier emergency departments. |
| Multiplex Panel Expansion | Single-specimen differentiation of aerobic and anaerobic pathogens enables targeted therapy selection and formulary restriction. |
| Emerging Market Regulatory Pathway Investment | CDSCO and PMDA pre-submission programs accelerate platform placement in underpenetrated pediatric lymphadenitis corridors. |
Study Parameters
Initial hypotheses were tested against primary input from emergency department directors, clinical microbiology laboratory managers, hospital procurement officers, and antimicrobial stewardship committee chairs and refined through secondary validation across FDA 510(k) databases, EMA scientific advice letters, hospital GPO contract filings, and CDSCO regulatory circulars. Bottom-up demand modeling triangulated against top-down market sizing from installed base estimates and replacement cycle analysis.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, end-user acuity tier, delivery mode, and age-group epidemiology. CAGRs were derived from logistic diffusion curves fitted to diagnostic platform adoption patterns and antibiotic prescribing volume trajectories. Forecast inputs incorporated EMA microbiological data submission requirements and FDA stewardship program enforcement timelines as regulatory demand shapers.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles and diagnostic equipment import tariffs would shift the trajectory. Forecasts reflect documented assumptions regarding PCR platform replacement horizons and antimicrobial resistance surveillance expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Italy Infectious Disease in-Vitro Diagnostics Market
Infectious Disease
Herpes Infection Treatment Market
Infectious Disease
Burkholderia Infections Market
Infectious Disease
Bronchitis Market
Infectious Disease
Arthropod Borne Viral Infections Market
Infectious Disease
Virology Market
Infectious Disease
Efavirenz Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Japanese Encephalitis Market
Infectious Disease
Global Pelvic Inflammatory Disease Therapeutics Market
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Norovirus Infection Treatment Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Global Veterinary Infectious Disease Diagnostics Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Valley Fever Market