
 Asia-Pacific Intraoral Scanners Market | 2026-2036
Asia-Pacific Intraoral Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Intraoral Scanners Market Insights
Sub-micron accuracy tier migration is unwinding legacy scanner deployments across the Asia-Pacific region. 3Shape A/S leverages its open-architecture software ecosystem to sustain chairside integration dominance in South Korea and Australia. Dentsply Sirona Inc. anchors premium positioning through proprietary CAD/CAM closed-loop systems that dominate Japanese university hospitals. MEDIT Corp. competes aggressively on price-performance ratios, extending wireless handheld penetration into Southeast Asian mid-market clinics.
Asia-Pacific intraoral scanners capture three-dimensional dental anatomy through confocal microscopy or structured light projection, achieving scan accuracies between 5 and 20 micrometers for crown-and-bridge fabrication and orthodontic aligner production. Handheld wireless variants now lead unit shipments across the region as clinicians prioritize ergonomic flexibility and reduced cable contamination risks in infection-sensitive environments. Orthodontics applications generate disproportionate value pools due to aligner therapy expansion, while dental clinics as an end-user channel command the steepest margin premiums relative to hospital procurement. Optical triangulation technology occupies the volume core, though structured light systems differentiate on speed for full-arch scanning in high-throughput Chinese laboratories.
Japan's PMDA enforces Class II medical device quality management system audits that elongate market entry timelines for non-domestic manufacturers, while Australia's TGA requires IEC 60601-1-2 electromagnetic compatibility certification as a precondition for reimbursement eligibility. China's NMPA implemented updated clinical evaluation pathways in 2021 that now accept overseas trial data for intraoral scanner registrations, reducing redundant local study burdens. Stakeholders must monitor how India's CDSCO forthcoming medical device rules harmonization with IMDRF standards reshapes import licensing requirements for Korean and Taiwanese scanner OEMs targeting South Asian expansion.
Market Dynamics
Sub-micron accuracy migration is compressing replacement cycles across the Asia-Pacific region as legacy optical triangulation systems face displacement by confocal microscopy platforms. This structural force reshapes vendor positioning and procurement criteria.
Growth Catalysts
- Japan's PMDA Class II streamlined pathways:Compressed quality management system audits for established manufacturers accelerate product clearance timelines, reducing time-to-revenue for compliant entrants targeting university hospital networks.
- Aligner therapy volume surge:Orthodontics applications now command premium scanner specifications as Chinese and Australian clear-aligner laboratories scale production capacity.
- Wireless handheld ergonomics:Cable-free scanner variants address infection control protocols in high-throughput Seoul and Singapore dental clinics, converting remaining wired-system holdouts.
Market Restraints
- Precision optics supply concentration:German and Japanese lens component suppliers control confocal microscopy sub-assemblies, exposing OEMs to input cost volatility and allocation constraints.
- Closed-loop CAD/CAM ecosystem lock-in:Proprietary scanner-mill integration in Japanese premium segments creates switching costs that slow open-architecture adoption.
- Calibration drift limitations:Structured light systems require frequent recalibration in humid Southeast Asian climates, elevating total cost of ownership relative to confocal alternatives.
Strategic Opportunities
- Vietnam and Indonesia mid-market penetration:Private dental chain expansion in Ho Chi Minh City and Jakarta creates demand for price-optimized wireless scanners with simplified workflows.
- China NMPA overseas data acceptance:2021 clinical evaluation pathway reforms eliminate redundant local trials for Korean and Taiwanese OEMs, compressing registration timelines.
- AI-powered real-time scan validation:Machine learning overlay integration with existing hardware platforms opens software-recurring revenue streams without full system replacement.
Industry Challenges
- Digital dentistry technician scarcity:Shortages of CAD/CAM-trained dental technicians in tier-two Chinese cities and Indian metro areas constrain scanner utilization rates and return-on-investment realization.
- IEC 60601-1-2 electromagnetic compatibility certification:Australia's TGA precondition for reimbursement eligibility elongates product launch timelines for non-compliant hardware variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Intraoral Scanners Market |
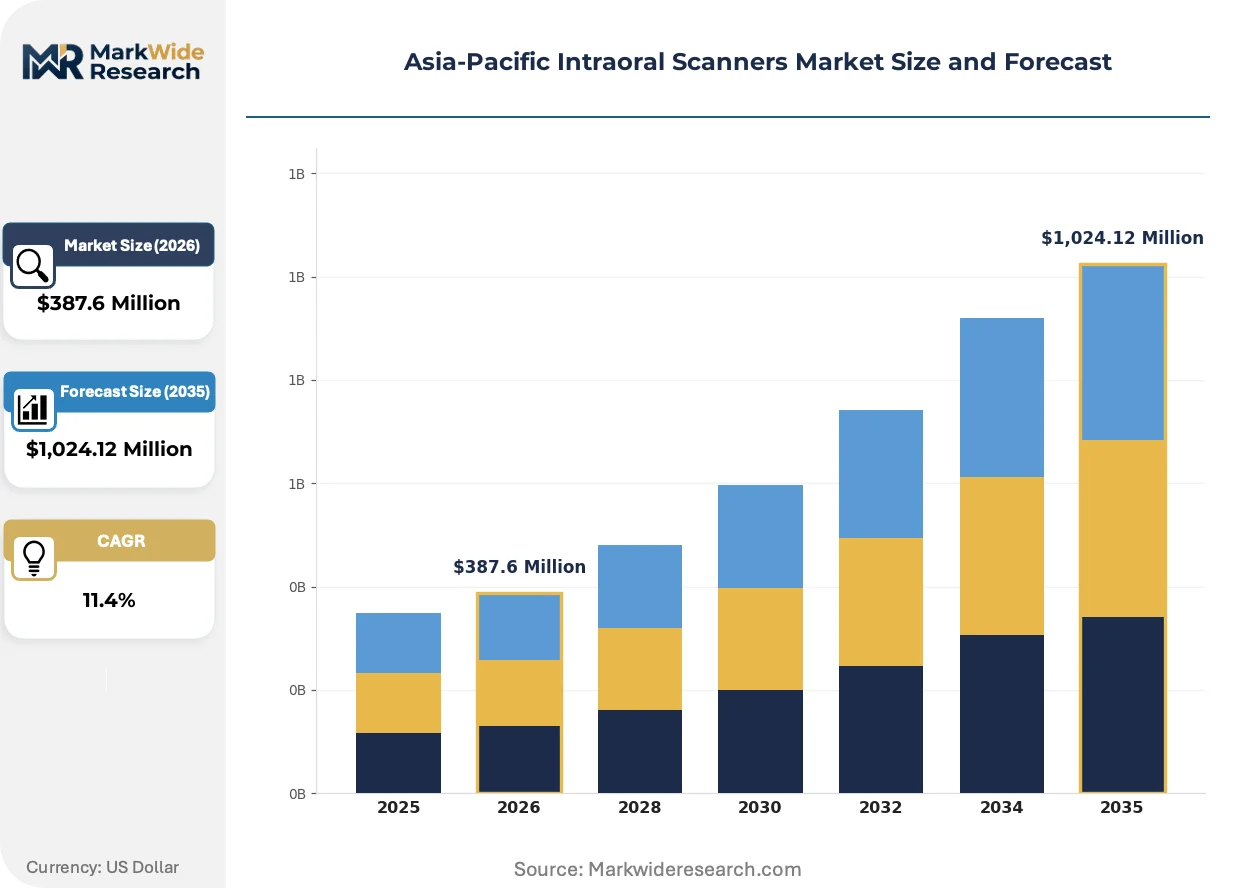
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Desktop, Mobile, Tabletop End User: Dental Clinics, Hospitals, Laboratories, Research Institutions Technology: Optical, Laser, Triangulation, Structured Light Application: Orthodontics, Restorative Dentistry, Implantology, Preventive Dentistry |
| Companies Covered | Planmeca Oy, Carestream Dental LLC, Dentsply Sirona Inc., Institut Straumann AG, Acteon, Align Technology Inc., MEDIT Corp., Envista Holdings Corporation, 3Shape A/S, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Intraoral Scanners Market Trends and Innovations
Scanner technology is fragmenting into accuracy-tiered product lines as confocal microscopy platforms bifurcate from legacy optical triangulation. Regulatory data reciprocity and procurement centralization reshape competitive entry patterns.
Confocal microscopy is bifurcating the Asia-Pacific hardware base. This technology achieves sub-10-micron accuracy for crown-and-bridge fabrication through active depth scanning. Premium Japanese university hospitals and Australian specialist prosthodontics practices are adopting it aggressively. The structural consequence is compressing margin pools for mid-tier structured light systems while elevating software ecosystem importance.
China's NMPA overseas clinical trial data acceptance is reshaping registration economics. This policy eliminates redundant local studies for intraoral scanner Class II approvals. Korean and Taiwanese OEMs targeting Chinese expansion are redirecting regulatory budgets toward post-market surveillance rather than duplicative efficacy trials. The segment most affected is mid-market wireless handhelds where speed-to-market determines distribution partnerships.
Private dental chain procurement centralization is consolidating vendor relationships. Large Chinese and Australian dental groups now mandate single-source scanner standardization across clinic networks. This displaces individual practitioner purchasing autonomy that previously supported fragmented brand landscapes. The geography where this is most visible is China's tier-one cities where MY Dental and瑞尔齿科 operate multi-hundred-clinic footprints.
Asia-Pacific Intraoral Scanners Market Segmentation
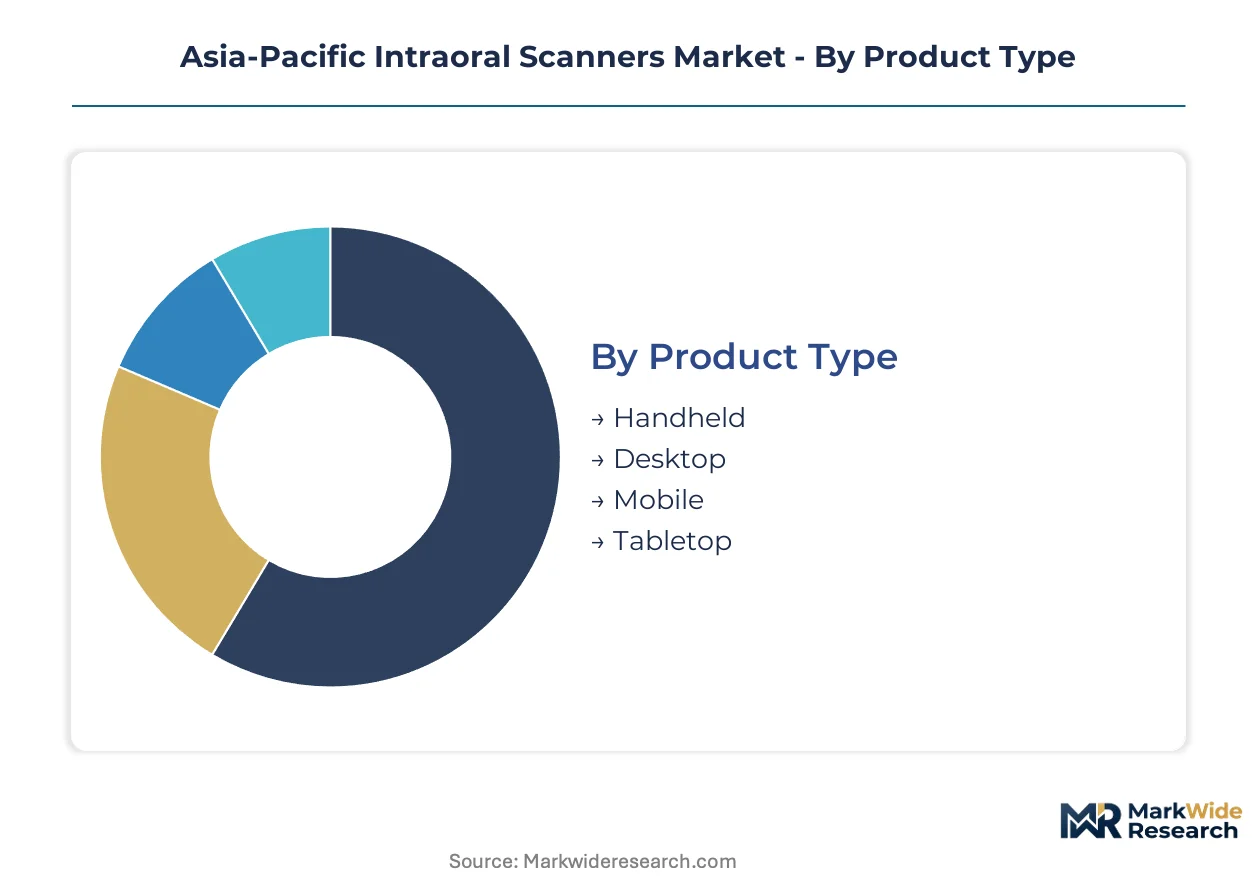
Intraoral scanner segmentation in Asia-Pacific reflects divergent procurement economics across clinical settings. Product form factors, imaging technologies, and application workflows each create distinct margin profiles and replacement cadences that vendors must navigate.
Product Type:
Channel mix varies sharply by form factor, with dental clinics driving handheld volume while laboratories anchor desktop and tabletop installations.
- Handheld:Wireless ergonomic designs dominate chairside adoption in Seoul and Singapore high-throughput clinics. Cable-free configurations address infection control protocols while enabling operator mobility during full-arch capture sequences.
- Desktop:Fixed-position units with integrated display systems concentrate in Australian prosthodontics practices and Japanese university hospitals where precision calibration remains stationary. These installations support multi-operator workflows with centralized hardware maintenance.
- Mobile:Battery-powered cart-based systems serve outreach dental programs across Indonesian archipelago clinics and rural Indian tier-three cities where permanent infrastructure is limited.
- Tabletop:Compact footprint units with simplified calibration protocols target mid-market Vietnamese and Philippine private chains seeking entry-level digital workflow adoption without dedicated technical staff.
Handheld scanners dominate installed base. Tabletop configurations are where expansion concentrates.
End User:
Customer type determines specification tier and purchasing centralization, with private chains consolidating procurement differently than institutional buyers.
- Dental Clinics:Private chain networks across China's tier-one cities mandate single-source scanner standardization, displacing individual practitioner autonomy. MY Dental and瑞尔齿科 operate multi-hundred-clinic footprints that negotiate volume procurement terms.
- Hospitals:Japanese university hospital networks anchor premium positioning through proprietary CAD/CAM closed-loop systems. PMDA Class II quality management system audits elongate vendor qualification timelines for institutional procurement.
- Laboratories:Chinese clear-aligner production facilities in Shenzhen and Hangzhou scale structured light systems for high-throughput full-arch scanning. These installations prioritize speed over sub-micron accuracy for aligner thermoforming workflows.
- Research Institutions:Korean and Australian academic dental schools drive confocal microscopy adoption for crown-and-bridge fabrication studies, generating technology validation data that influences downstream clinical procurement.
Dental clinics command the steepest margin premiums. Laboratories are expanding most quickly.
Technology:
Imaging modality creates a cost-performance hierarchy that segments across humidity-sensitive Southeast Asian climates and precision-demanding Northeast Asian markets.
- Optical:Confocal microscopy platforms achieve sub-10-micron accuracy through active depth scanning. Premium Japanese university hospitals and Australian specialist prosthodontics practices adopt these aggressively for crown-and-bridge fabrication.
- Laser:Time-of-flight systems penetrate mid-market segments in Thailand and Malaysia where cost constraints limit confocal adoption. These configurations trade marginal accuracy for reduced component complexity and maintenance intervals.
- Triangulation:Legacy optical triangulation occupies volume core across established Chinese dental chains. Sub-micron accuracy migration is compressing replacement cycles as these systems face displacement.
- Structured Light:Pattern projection systems differentiate on speed for full-arch scanning in high-throughput Chinese laboratories. Frequent recalibration requirements in humid Southeast Asian climates elevate total cost of ownership relative to confocal alternatives.
Optical technology anchors premium tier positioning. Structured light systems are gaining share fastest in laboratory channels.
Application:
Workflow specialization drives specification divergence, with orthodontics commanding distinct scanner requirements versus restorative or implant procedures.
- Orthodontics:Clear-aligner therapy volume surge commands premium scanner specifications as Chinese and Australian laboratories scale production capacity. Full-arch capture speed and soft-tissue exclusion algorithms determine vendor selection.
- Restorative Dentistry:Crown-and-bridge fabrication demands sub-10-micron accuracy tiers that bifurcate hardware procurement. Japanese and Australian markets concentrate here with prosthodontics-driven replacement cycles.
- Implantology:Surgical guide production requires integration with CBCT datasets and specialized scan bodies. Korean implant manufacturers drive domestic scanner specification standards that influence regional procurement.
- Preventive Dentistry:Monitoring and documentation applications in pediatric and geriatric clinics utilize entry-tier accuracy specifications. Indian metro area preventive programs represent emerging volume as digital record mandates expand.
Restorative dentistry dominates current installed value. Orthodontics applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Korean scanner manufacturers export wireless handheld systems to Vietnamese and Indonesian dental chains, establishing supply corridors that bypass traditional Japanese distribution hierarchies. This trade dynamic reshapes procurement patterns across Southeast Asian mid-markets.
China
Clear-aligner production facilities in Shenzhen and Hangzhou scale structured light systems for high-throughput laboratory workflows. NMPA's 2021 clinical evaluation pathway reforms accept overseas trial data, compressing registration timelines for Korean and Taiwanese OEMs. Tier-one cities host multi-hundred-clinic dental chains that mandate single-source scanner standardization.
Japan
University hospital networks anchor premium positioning through proprietary CAD/CAM closed-loop systems. PMDA Class II quality management system audits elongate vendor qualification timelines for institutional procurement. Tokyo and Osaka prosthodontics practices drive confocal microscopy adoption for crown-and-bridge fabrication.
South Korea
Domestic implant manufacturers establish scanner specification standards that influence regional procurement patterns. MFDS medical device registration frameworks align with international standards, facilitating export-oriented production. Seoul high-throughput clinics prioritize wireless ergonomic designs that address infection control protocols.
Australia
Specialist prosthodontics practices adopt sub-10-micron accuracy confocal platforms aggressively. TGA requires IEC 60601-1-2 electromagnetic compatibility certification as precondition for reimbursement eligibility. Sydney and Melbourne dental groups consolidate procurement across clinic networks.
Vietnam
Private dental chain expansion in Ho Chi Minh City generates demand for price-optimized wireless scanners with simplified workflows. The country's national medical device regulator harmonizes import licensing with ASEAN medical device directive frameworks. Mid-market clinics bypass wired-system legacy infrastructure entirely.
Asia-Pacific Intraoral Scanners Market Competitive Landscape
Listed leaders compete with private specialists across software ecosystem integration and hardware accuracy tiers. Market structure concentrates around three to five dominant vendors controlling premium segments, while mid-market fragmentation persists among price-optimized entrants. Strategic archetypes include open-architecture platform builders, proprietary closed-loop integrators, and wireless handheld specialists. Competitive moves center on M&A for software capabilities and geographic expansion into Southeast Asian mid-markets.
Within the open-architecture tier, 3Shape A/S and MEDIT Corp. represent contrasting positioning approaches. Dentsply Sirona Inc. anchors premium-tier proprietary integration. These three entities exemplify how vendor strategy fragments across software ecosystem philosophy rather than hardware specification alone.
| Leading Market Players |
|---|
| Planmeca Oy |
| Carestream Dental LLC |
| Dentsply Sirona Inc. |
| Institut Straumann AG |
| Acteon |
| Align Technology Inc. |
| MEDIT Corp. |
| Envista Holdings Corporation |
| 3Shape A/S |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day confocal microscopy lens lead times from German and Japanese suppliers concentrate upstream pricing power among premium-tier scanner OEMs serving Japanese university hospitals and Australian prosthodontics practices. This component scarcity elevates input cost pass-through capability for vendors with established supplier relationships while compressing margins for mid-market entrants sourcing through distribution intermediaries.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates confocal microscopy platforms with sub-10-micron accuracy from structured light systems and legacy optical triangulation units. Certification tier under Japan's PMDA Class II quality management system audits and volume scale through Chinese dental chain procurement centralization drive widening spreads between tiers. Cost compression in mid-market wireless handhelds is intensifying because Korean and Taiwanese OEMs exploit NMPA overseas data acceptance to accelerate speed-to-market. Price sensitivity concentrates among Vietnamese and Indonesian private dental chains seeking entry-level digital workflow adoption.
Supply Chain Analysis
Strategic stockpiling of precision optics sub-assemblies characterizes vendor inventory strategy as confocal microscopy platforms displace legacy systems across the Asia-Pacific region. Component manufacturing concentrates in Germany, Japan, and South Korea. Scanner assembly draws from Taiwanese semiconductor foundries for image processing chipsets, Chinese aluminum extrusion facilities for ergonomic housings, and Korean battery cell manufacturers for wireless handheld power systems. Single-source vulnerability in German and Japanese lens component suppliers exposes OEMs to allocation constraints during demand surges. Distribution runs through authorized dealer networks in developed markets and direct sales teams penetrating Southeast Asian mid-market expansion corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific intraoral scanners market sits at an inflection where sub-micron accuracy migration compresses replacement cycles and NMPA regulatory reciprocity accelerates competitive entry timelines for Korean and Taiwanese OEMs.
For Market Incumbents: Fortify software ecosystem lock-in through AI-powered real-time scan validation overlays that generate recurring revenue without full hardware replacement cycles. Deepen backward integration into confocal microscopy lens supply relationships to defend margin position against input cost volatility from German and Japanese component suppliers. Channel control through exclusive distribution partnerships with expanding Chinese dental chains remains critical as procurement centralization displaces individual practitioner autonomy. For New Entrants and Emerging Players: Anchor in Vietnam and Indonesia mid-market penetration where private dental chain expansion in Ho Chi Minh City and Jakarta generates demand for price-optimized wireless scanners with simplified calibration protocols. Target tabletop configurations for entry-level digital workflow adoption among Philippine and Vietnamese clinics lacking dedicated technical staff. A direct-to-practitioner digital marketing and remote training go-to-market angle bypasses entrenched distribution hierarchies that incumbent vendors control. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because software ecosystem integration determines vendor survival as hardware accuracy tiers commoditize. Acquisition targets should emphasize open-architecture CAD/CAM compatibility and established regulatory clearance portfolios across PMDA, NMPA, and TGA frameworks. The signal to watch is dental laboratory M&A activity indicating vertical integration pressure that reshapes scanner specification standards.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | AI-powered real-time scan validation opens recurring revenue streams without full system replacement. |
| Reimbursement Strategy | TGA IEC 60601-1-2 certification unlocks Australian reimbursement eligibility and institutional procurement access. |
| Hospital System Partnership | Japanese university hospital networks anchor premium positioning through proprietary CAD/CAM closed-loop integration. |
| CE Marking Pathway | ASEAN medical device directive harmonization streamlines Vietnamese and Indonesian import licensing requirements. |
| Geographic Expansion | Korean wireless handheld exports establish supply corridors bypassing traditional Japanese distribution hierarchies. |
Research Methodology
A standing panel of prosthodontics clinicians, hospital purchasing committee chairs, biomedical engineers at clear-aligner production facilities, and GPO contracts managers provided ongoing calibration throughout the study period. Primary interview findings combined with secondary validation from PMDA medical device registration databases, NMPA clinical evaluation pathway documentation, TGA electromagnetic compatibility certification records, and dental laboratory procurement contract filings. Bottom-up installed base estimates triangulated against top-down market size calculations across product type, end user, technology, application, and country-level regulatory cluster segmentation dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product form factor adoption curves, imaging technology replacement cadences, end-user procurement centralization patterns, application workflow specialization trends, and country-specific regulatory reciprocity developments. CAGRs were derived from segmented growth trajectory analysis incorporating orthodontics aligner therapy volume expansion, wireless handheld ergonomic conversion rates, and confocal microscopy platform displacement dynamics.
Material uncertainties — precision optics supply allocation constraints, PMDA audit timeline variability, and NMPA policy implementation consistency — sit outside the modeled envelope. Forecasts reflect assumptions regarding dental technician training pipeline expansion and private dental chain capital expenditure continuity. Revision becomes warranted when confocal microscopy component lead times exceed sustainable production planning horizons or when regulatory reciprocity agreements materially alter registration economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Gastrointestinal Devices Market
Medical Devices
Gracey Curette Market
Medical Devices
Internal Trauma Fixation Device Market
Medical Devices
Pen Injectors Market
Medical Devices
Medical Bionic Implants and Exoskeletons Market
Medical Devices
Ophthalmic Microscopes Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market
Medical Devices
Battery-Operated Lactate Meter Market
Medical Devices
India Hemostats Market
Medical Devices
Global Pathological Microscopes Market
Medical Devices
Artificial Ventilation and Anesthesia Masks Market
Medical Devices
Italy Ophthalmic Devices Market
Medical Devices
Latin America Insulin Delivery Devices Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Germany Ophthalmic Devices Market