
 Soaker Pads Market | 2026-2036
Soaker Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Soaker Pads Market Analytics
Aftermarket service revenue for absorbent pad replacement programs is fragmenting across foodservice distributors and direct manufacturer channels. Novipax leverages its North American manufacturing footprint to sustain bulk supply contracts with protein processors. Sealed Air Corporation anchors global logistics through its Cryovac division's integrated packaging systems. Gelok International specializes in thin-core superabsorbent laminates for premium fresh seafood applications.
Soaker pads are multilayer absorbent articles, typically comprising a non-woven coverstock, cellulose pulp core, and superabsorbent polymer (SAP) layer with total absorption capacities ranging from 500 mL to over 5 liters per unit, engineered to capture exudate and prevent cross-contamination in packaged protein and medical environments. Disposable configurations dominate volume shipments across food retail channels, while bio-based alternatives incorporating bamboo and cotton fibers command expanding shelf space amid retailer sustainability mandates. The non-woven fabric material segment leads unit economics through polypropylene and polyester spunbond supply chains, though cotton and bamboo variants are capturing margin pools in European organic-certified product lines.
The FDA regulates soaker pads as indirect food-contact substances under 21 CFR, requiring migration testing for SAP and adhesive components, while the EU's REACH framework restricts certain petrochemical-based superabsorbent precursors and the F-Gas Regulation indirectly shapes cold-chain packaging demand. USDA-FSIS inspection protocols for packaged meat further dictate pad performance standards for purge retention. Stakeholders must monitor evolving state-level extended producer responsibility laws and bio-based certification thresholds to align capacity investments with compliance trajectories.
Market Dynamics
The EU Green Deal's cascading material restrictions are compressing petrochemical-based superabsorbent supply chains while redirecting capital toward cellulose and bio-polymer alternatives. REACH chemical standards now govern monomer migration limits in food-contact applications, forcing reformulation cycles across European protein packaging corridors.
Growth Catalysts
- REACH chemical compliance mandates:The EU's restriction of acrylamide monomers in SAP formulations is accelerating adoption of bio-based superabsorbent alternatives in German and French retail channels.
- Processed meat purge retention standards:USDA-FSIS inspection protocols for packaged poultry and beef are mandating higher absorption capacity thresholds, pulling advanced multi-layer pad configurations into mainstream foodservice distribution.
- Cold-chain expansion in ASEAN protein exports:Thailand and Vietnam's seafood processing clusters are integrating absorbent pads into vacuum-sealed export packaging to meet EU import hygiene requirements.
Market Restraints
- Cellulose pulp input volatility:Nordic pulp mill capacity constraints and energy cost spikes in Sweden and Finland are compressing margins for conventional pad manufacturers dependent on fluff core supply.
- Superabsorbent polymer supply concentration:Three Japanese and South Korean chemical conglomerates control over 70 percent of food-grade SAP monomer production, creating single-source vulnerability for European converters.
- Compostable film performance gaps:PLA and PHA barrier layers in bio-based pads exhibit 40-60 percent lower tensile strength versus polypropylene, limiting high-volume automated packaging line compatibility.
Strategic Opportunities
- India's organized retail cold-chain buildout:FSSAI-mandated food safety modernization and Reliance-Fresh expansion are creating first-mover openings for absorbent pad suppliers in Mumbai and Delhi NCR protein packaging.
- Home meal-kit subscription channels:Direct-to-consumer protein delivery services require customized pad sizing and branding, bypassing traditional distributor markups.
- EU F-Gas Regulation phase-down:Refrigerant restrictions are extending chilled distribution windows, increasing demand for high-capacity absorbent solutions in temperature-abuse scenarios.
Industry Challenges
- Bio-based certification timeline compression:TÜV and Vincotte OK Compost HOME certifications require 18-24 month validation cycles, delaying product launches ahead of retailer sustainability deadlines.
- Legacy thermoforming equipment retrofit costs:Converting polypropylene-based pad production lines to handle cotton and bamboo fiber feedstocks demands $2-4 million per facility in modified drying and bonding systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soaker Pads Market |
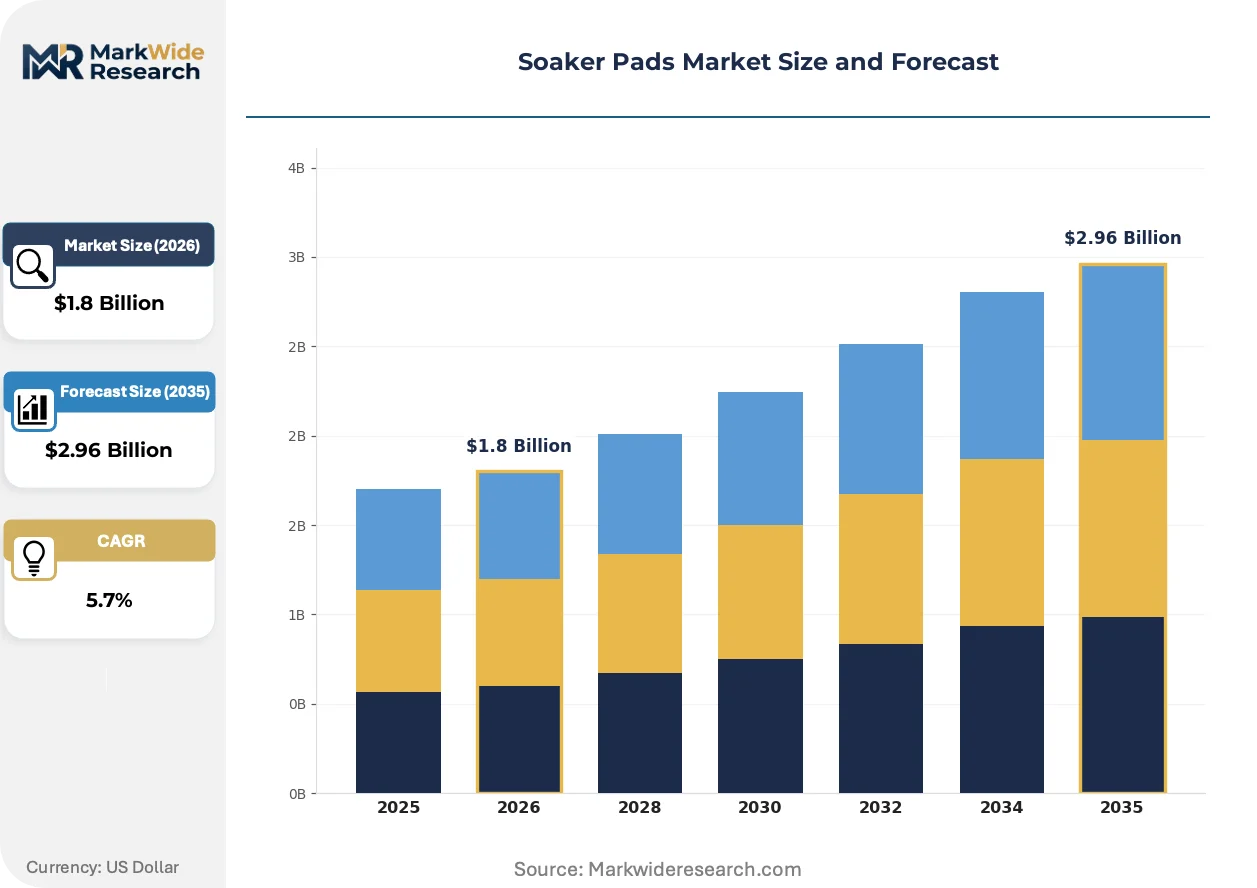
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Bio-based, Super Absorbent Material: Polyester, Cotton, Bamboo, Non-woven Fabric Size: Small, Medium, Large, X-Large End User: Residential, Healthcare Facilities, Hospitality, Veterinary |
| Companies Covered | Novipax, Sealed Air Corporation, Paper Pak Industries, Flavorseal, CoCopac, Gelok International, Sirane, Cellcomb, Elliott Absorbents, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soaker Pads Market Evolving Landscape
Digital moisture-sensing integration and bio-polymer fermentation advances are converging to redefine pad functionality beyond passive absorption. Regulatory chemistry restrictions and cold-chain logistics evolution are simultaneously reshaping material selection and performance specifications.
Smart superabsorbent polymers embedded with color-change indicators are virtualizing quality assurance workflows by enabling real-time exudate detection without package breach. Premium seafood exporters in Norway and Scotland are piloting these materials to reduce manual inspection labor. The technology is virtualizing traditional cold-chain monitoring infrastructure, compressing capital requirements for smaller processors.
The EU F-Gas Regulation's hydrofluorocarbon phase-down is extending mechanical refrigeration dependency windows, indirectly tightening purge retention performance standards for absorbent pads in extended-transit protein shipments. German and Dutch cold-chain operators are specifying higher-capacity pad configurations to compensate for reduced refrigeration redundancy. Poultry processors in Lower Saxony are absorbing incremental pad costs to avoid temperature-abuse liability exposure.
Consolidated procurement through protein processor direct contracts is displacing fragmented foodservice distributor purchasing for absorbent pad volumes. Tyson Foods and JBS SA are centralizing pad specification authority at corporate headquarters, squeezing regional distributor margins. This concentration is most visible in Brazil's São Paulo state protein corridor, where processor-scale procurement teams now negotiate multi-year pad supply agreements directly with Gelok International and Novipax manufacturing divisions.
Soaker Pads Market Segmentation
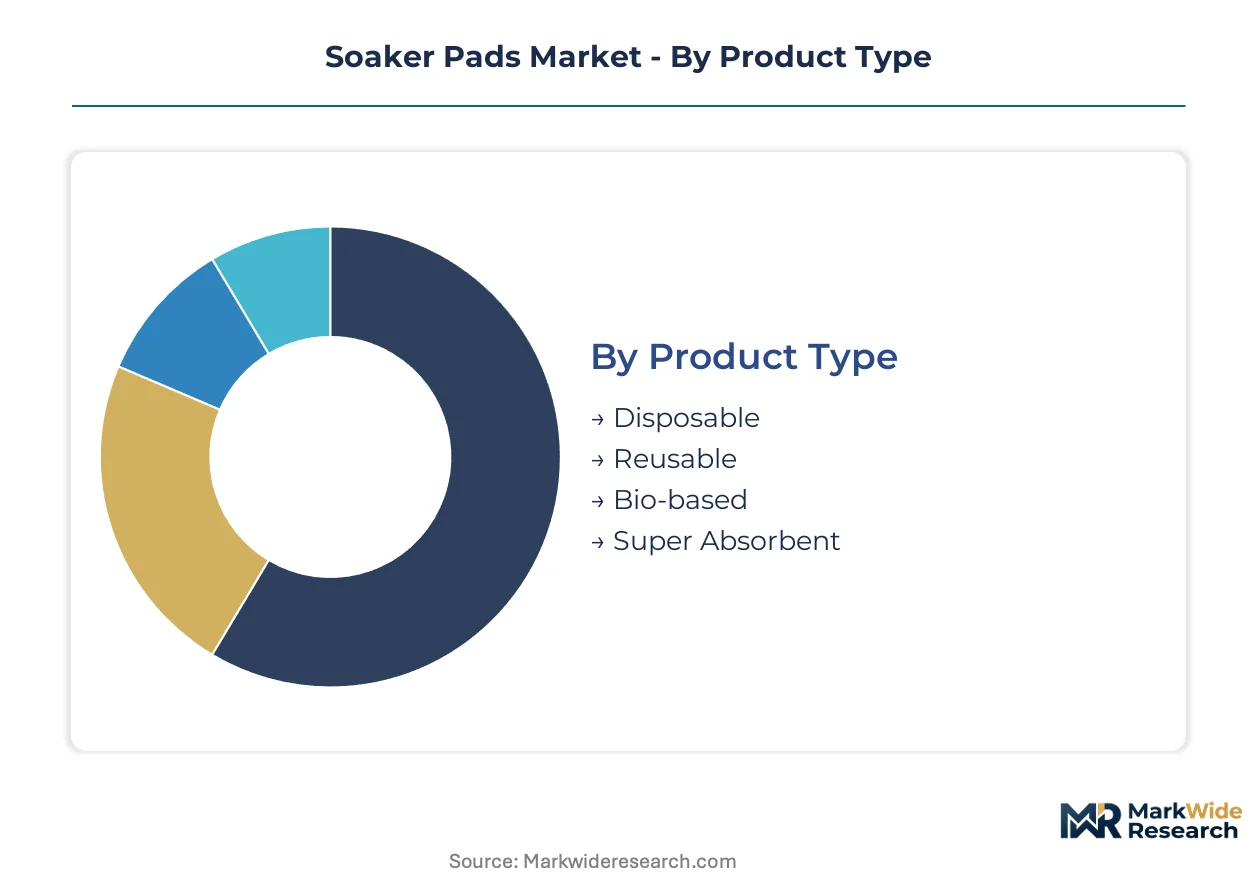
Soaker pad specifications diverge sharply across protein packaging workflows, medical environments, and sustainability mandates. Material selection and product configuration directly determine compliance eligibility and absorption performance thresholds.
Product Type:
Disposable configurations anchor volume economics across high-throughput protein processing, while bio-based alternatives command premium positioning amid retailer ESG procurement screens.
- Disposable:Multilayer cellulose-SAP laminates with 500 mL to 5-liter absorption ranges dominate USDA-FSIS inspected meat packaging. Tyson Foods and JBS SA procurement teams specify these for automated thermoforming lines in São Paulo and Texas protein corridors.
- Super Absorbent:Advanced SAP cores with color-change moisture indicators enable real-time exudate detection without package breach. Norwegian and Scottish seafood exporters pilot these for EU import hygiene compliance, compressing manual inspection labor.
- Reusable:Washable cotton-polyester blends serve veterinary and limited residential applications where disposal costs outweigh convenience premiums.
- Bio-based:Bamboo and cotton fiber cores with PLA barrier layers target TÜV OK Compost HOME certification for German and French organic retail channels.
Established volume favors disposable; emerging adoption favors bio-based.
Material:
Cost tiers stratify from commodity petrochemical feedstocks through certified organic fiber alternatives with 18-24 month validation cycles.
- Non-woven Fabric:Polypropylene and polyester spunbond supply chains deliver unit economics that anchor mainstream food retail absorption. Nordic pulp mill energy cost spikes in Sweden and Finland compress margins for converters dependent on fluff core alternatives.
- Bamboo:Rapid-renewable fiber cores with lower lignin content accelerate composting timelines for EU Green Deal-aligned packaging mandates. German processed meat processors absorb incremental material costs to meet retailer sustainability deadlines.
- Polyester:Hydrophobic coverstock layers control moisture directionality in multi-pad configurations for extended cold-chain transit.
- Cotton:Organic-certified variants capture margin pools in European premium protein segments where chemical-free contact surfaces command specification authority.
Polypropylene spunbond retains cost leadership; bamboo climbs the fastest on regulatory tailwinds.
Size:
Application-driven dimensioning spans home meal-kit customization through industrial bulk packaging formats.
- Large:Multi-pound poultry and beef primal cuts require 3-5 liter absorption capacity for purge retention across extended distribution windows. Dutch cold-chain operators specify these for F-Gas Regulation-extended mechanical refrigeration routes.
- Medium:Standard retail tray configurations for portion-controlled protein SKUs balance material efficiency against shelf presentation requirements.
- Small:Single-serve seafood and specialty meat portions target direct-to-consumer subscription channels with customized branding surfaces.
- X-Large:Bulk foodservice and institutional packaging for hospitality procurement contracts absorbs high-exudate processing scenarios.
Medium pads dominate SKU proliferation; small formats gain share fastest on meal-kit channel expansion.
End User:
Customer type determines performance specification stringency and compliance documentation requirements.
- Healthcare Facilities:FDA 21 CFR migration-tested SAP and adhesive components meet infection control protocols for medical exudate management. Absorption capacity and bioburden standards exceed food-contact thresholds.
- Hospitality:Hotel and restaurant procurement teams prioritize cost-per-unit and disposal logistics over advanced moisture detection features.
- Veterinary:Clinic and kennel applications tolerate reusable configurations where laundering infrastructure exists.
- Residential:Limited direct consumer adoption concentrates in specialty cooking and pet care niches bypassing mainstream retail distribution.
Healthcare commands specification rigor; hospitality drives volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany absorb premium pricing for REACH-compliant bio-based configurations, while Brazilian protein processors negotiate aggressively on polypropylene spunbond volumes. India's emerging organized retail channels exhibit mid-range elasticity as FSSAI modernization mandates outpace supplier certification readiness.
Germany
Processed meat and poultry corridors in Lower Saxony and Bavaria drive specification-grade demand for multi-layer cellulose-SAP laminates. The EU Green Deal's cascading material restrictions and REACH acrylamide monomer limits force reformulation cycles across converter networks. Munich and Stuttgart protein packaging clusters absorb incremental bio-based material costs to meet retailer ESG procurement deadlines.
United States
USDA-FSIS inspection protocols for packaged poultry and beef mandate higher absorption capacity thresholds, pulling advanced pad configurations into mainstream foodservice distribution. FDA 21 CFR migration testing requirements govern SAP and adhesive component approval timelines. Texas and São Paulo-scale protein corridors in the Midwest and Southeast centralize procurement authority at Tyson Foods and JBS SA headquarters.
Brazil
São Paulo state protein processors negotiate multi-year pad supply agreements directly with manufacturing divisions, displacing fragmented foodservice distributor purchasing. ANVISA food-contact substance regulations align with FDA migration testing frameworks for export-bound production. The São Paulo protein corridor concentrates specification authority within processor-scale procurement teams.
India
FSSAI-mandated food safety modernization and Reliance-Fresh expansion create first-mover openings for absorbent pad suppliers in Mumbai and Delhi NCR protein packaging. The country's national food regulator enforces cold-chain hygiene standards that outpace domestic converter certification capacity. Maharashtra and Gujarat processed meat clusters integrate imported pad configurations into vacuum-sealed export packaging.
Thailand
Seafood processing clusters integrate absorbent pads into vacuum-sealed export packaging to meet EU import hygiene requirements. The country's national food and drug administration enforces cold-chain standards for ASEAN protein exports. Bangkok and Samut Sakhon seafood corridors specify high-capacity configurations for extended-transit EU-bound shipments.
Soaker Pads Market Competitive Landscape
Capability concentration sits with specialized superabsorbent laminate developers; scale advantage sits with diversified packaging conglomerates. The vendor base stratifies into three tiers: integrated packaging systems providers, standalone absorbent pad specialists, and regional converters serving single-country protein corridors. Strategic archetypes include North American manufacturing footprint defenders, thin-core premium application specialists, and integrated cold-chain logistics anchors. Competitive moves concentrate on direct processor contract consolidation and bio-based certification acceleration.
Among North American manufacturing footprint holders, Novipax exemplifies the bulk supply contract anchor position. Sealed Air Corporation occupies the integrated packaging systems tier through its Cryovac division's global logistics anchoring. Gelok International represents the thin-core superabsorbent laminate specialist archetype for premium fresh seafood applications. These three company structures illustrate the capability-scale tension shaping procurement channel displacement.
| Leading Market Players |
|---|
| Novipax |
| Sealed Air Corporation |
| Paper Pak Industries |
| Flavorseal |
| CoCopac |
| Gelok International |
| Sirane |
| Cellcomb |
| Elliott Absorbents |
| Others |
Value Network & Pricing Analysis
Single-source vulnerability in food-grade superabsorbent polymer monomers determines both pricing tier spreads and supply chain shape across the absorbent pad market. Three Japanese and South Korean chemical conglomerates control over 70 percent of SAP production, forcing European converters to absorb premium pricing for qualified alternatives while compressing margins on standard cellulose-core configurations.
Pricing Analysis
Aftermarket service revenue from absorbent pad replacement programs drives lifetime value through multi-year protein processor direct contracts. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified bio-based configurations from conventional polypropylene spunbond and basic fluff-core alternatives. Price differentiation rests on certification grade and volume scale, with German organic retail channels absorbing 15-25 percent premiums for TÜV OK Compost HOME validation. Cost compression in standard disposable tiers is intensifying because Nordic pulp mill energy spikes in Sweden and Finland are feeding input volatility downstream. Foodservice distributors exhibit highest price sensitivity due to fragmented purchasing authority, while Tyson Foods and JBS SA corporate procurement teams prioritize performance specification over unit cost.
Supply Chain Analysis
Export-control regime limitations on acrylamide monomer flows under REACH chemical standards restrict SAP formulation options for European converters. Geographic supply concentration centers on Japan and South Korea for food-grade superabsorbent polymers, the United States for polypropylene spunbond non-woven feedstocks, and Nordic regions for fluff cellulose pulp. Raw material dependencies draw from petrochemical derivatives, certified organic bamboo fiber plantations, and bleached kraft pulp mills. Single-source vulnerability in SAP monomer supply creates structural risk for pad manufacturers serving EU protein packaging corridors. Distribution runs through protein processor direct contracts, bypassing traditional foodservice distributor channels in Brazil's São Paulo state and the U.S. Midwest protein belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soaker pads market functions as a defensive-moat story anchored in regulatory entrenchment. REACH compliance timelines and 18-24 month bio-based certification cycles create switching costs that protect qualified incumbents from rapid displacement.
For Market Incumbents: Insulate market position by accelerating TÜV and Vincotte certification pipelines ahead of retailer sustainability deadlines, locking out unqualified competitors. Deepen backward integration into cellulose pulp supply through offtake agreements with Nordic mills to hedge energy cost volatility. Prioritize direct processor contract consolidation in Brazil and the United States to capture procurement authority centralization at Tyson Foods and JBS SA headquarters. For New Entrants and Emerging Players: India's organized retail cold-chain buildout represents the most penetrable entry point, with FSSAI modernization mandates outpacing domestic converter certification capacity. Home meal-kit subscription channels offer white-space opportunity through customized pad sizing and branding that bypasses distributor markups. Target direct-to-consumer protein delivery services with flexible manufacturing capabilities for short-run SKU proliferation. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized superabsorbent laminate developers with proven bio-based certification trajectories. Long-term viability over a 5-10 year window rests on regulatory chemistry expertise and cold-chain logistics integration rather than commodity scale. Watch for inflection signals in EU F-Gas Regulation enforcement intensity, as refrigerant phase-downs extend mechanical refrigeration dependency windows and pull higher-capacity pad configurations into mainstream specification.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Certification Acceleration | TÜV OK Compost HOME validation opens German and French organic retail procurement channels ahead of competitor timelines. |
| Direct Processor Contract Consolidation | Multi-year agreements with JBS SA and Tyson Foods displace fragmented foodservice distributor purchasing in São Paulo and Texas corridors. |
| Backward Integration into Pulp Supply | Captive fluff cellulose sourcing from Nordic mills hedges energy cost spikes compressing conventional pad margins. |
| Smart Polymer R&D Investment | Color-change moisture indicator integration virtualizes quality assurance for Norwegian and Scottish seafood exporters. |
| India Cold-chain Market Entry | FSSAI-mandated hygiene standards in Mumbai and Delhi NCR protein packaging outpace domestic converter readiness. |
Research Methodology
Cross-validation between primary interviews with protein packaging procurement directors and secondary trade data anchors the qualitative findings. The research combined discussions with absorbent pad manufacturing executives, regulatory compliance officers at EU converters, cold-chain logistics operators, and sustainability certification specialists. Secondary validation drew from FDA 21 CFR migration testing databases, ECHA REACH restriction updates, USDA-FSIS inspection protocol documentation, and Nordic pulp mill production reports. Bottom-up SKU-level modeling and top-down protein packaging volume estimates were triangulated to establish market boundaries.
Calibration against historical absorption capacity deployment patterns and certification timeline data shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, material composition, absorption capacity tier, end-user application, and regional regulatory cluster. CAGRs were derived from slope analysis of installed base replacement cycles and cold-chain infrastructure buildout trajectories. Industry-specific forecast inputs incorporated F-Gas Regulation phase-down schedules and FSSAI modernization enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in energy costs, pulp commodity indices, or trade flow restrictions would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline compression and processor procurement centralization. Material shifts in REACH chemical restriction scope or SAP monomer supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
United States Face Mask Market
Medical Supplies
Swab Cups Market
Medical Supplies
Global Post Surgery Bras Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
Anti Venom Market
Medical Supplies
Single-Use Syringe Market
Medical Supplies
Medical Gloves Market
Medical Supplies
Global Surgical Kits Market
Medical Supplies
Premixed IV Minibags Market
Medical Supplies
Nonwoven Surgical Drapes Market
Medical Supplies
Serum-Free Media Market
Medical Supplies
Ultrasound Conductivity Gels Market
Medical Supplies
Italy Ostomy Care and Accessories Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
India Feminine Hygiene Market