
 Europe Specialty Gas Market | 2026-2036
Europe Specialty Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Specialty Gas Market Analytics
Project finance tied to on-site gas generation and long-term take-or-pay contracts is rewriting competitive entry requirements for mid-scale suppliers. Air Liquide SA leverages integrated air separation and helium recycling assets to sustain pricing power across French and German semiconductor clusters. Linde PLC anchors its position through captive krypton and xenon recovery from steel plant off-gases, while Messer SE and Co. KGaA competes via regional pipeline networks and distributed cylinder filling capacity in Central Europe.
Specialty gases comprise high-purity elemental and compound gases, along with calibrated mixtures, manufactured to impurity thresholds below one part per billion for processes where contamination causes catastrophic yield loss. Production employs cryogenic distillation, pressure swing adsorption, and catalytic purification to achieve semiconductor-grade specifications. High-purity gases dominate value capture due to purification complexity and captive demand from EUV lithography, while gas mixtures represent the fastest-expanding segment as analytical laboratories and pharmaceutical quality control adopt multi-component calibration standards. Electronics manufacturing absorbs the largest volume share, though pharmaceutical applications command superior margins through batch-specific certification requirements.
EMA and REACH constrain fluorinated greenhouse gas formulations, compelling reformulation of etching and chamber-cleaning blends. The EU F-Gas Regulation mandates phasedown quotas that redirect procurement toward reclaimed and recycled alternatives, tightening supply for virgin material. Stakeholders must monitor regulatory threshold revisions and build reclaimed gas handling infrastructure before compliance deadlines harden market access barriers.
Market Dynamics
EUV lithography's penetration into sub-3nm node production is concentrating noble gas demand around ASML's supplier ecosystem, forcing purification technology upgrades and captive supply investments across the Benelux corridor.
Growth Catalysts
- EU F-Gas Regulation phase-down:Mandated hydrofluorocarbon quotas redirect procurement toward reclaimed and recycled fluorinated alternatives, expanding infrastructure investment.
- Semiconductor node shrinkage:Advanced lithography processes below 5nm require ultra-high-purity xenon, neon, and krypton with impurity thresholds below one part per billion.
- Pharmaceutical batch certification:EMA-mandated quality control standards drive demand for multi-component calibration gas mixtures in analytical laboratories.
Market Restraints
- Noble gas supply concentration:Ukraine and Russian feedstock disruptions constrain neon and krypton availability for European purification facilities.
- Helium feedstock dependence:US Bureau of Land Management reserve auctions and Qatar liquefaction capacity govern European helium pricing volatility.
- REACH compliance burden:ECHA substance registration requirements extend certification timelines for novel fluorinated etching blends.
Strategic Opportunities
- Eastern European fab expansion:Poland and Romania semiconductor manufacturing investments lack established captive gas supply, opening on-site generation contracts.
- Steel off-gas recovery infrastructure:Linz and Dortmund metallurgical facilities vent krypton and xenon recoverable through membrane separation.
- CSRD disclosure mandates:Corporate sustainability reporting requirements incentivize Scope 3 emissions reduction through recycled gas procurement.
Industry Challenges
- Cryogenic purification engineering talent:Specialized expertise in sub-ppb impurity removal exceeds available workforce supply in Central Europe.
- Batch-specific certification timelines:Pharmaceutical-grade mixture validation under EMA guidelines extends delivery cycles beyond standard industrial contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Specialty Gas Market |
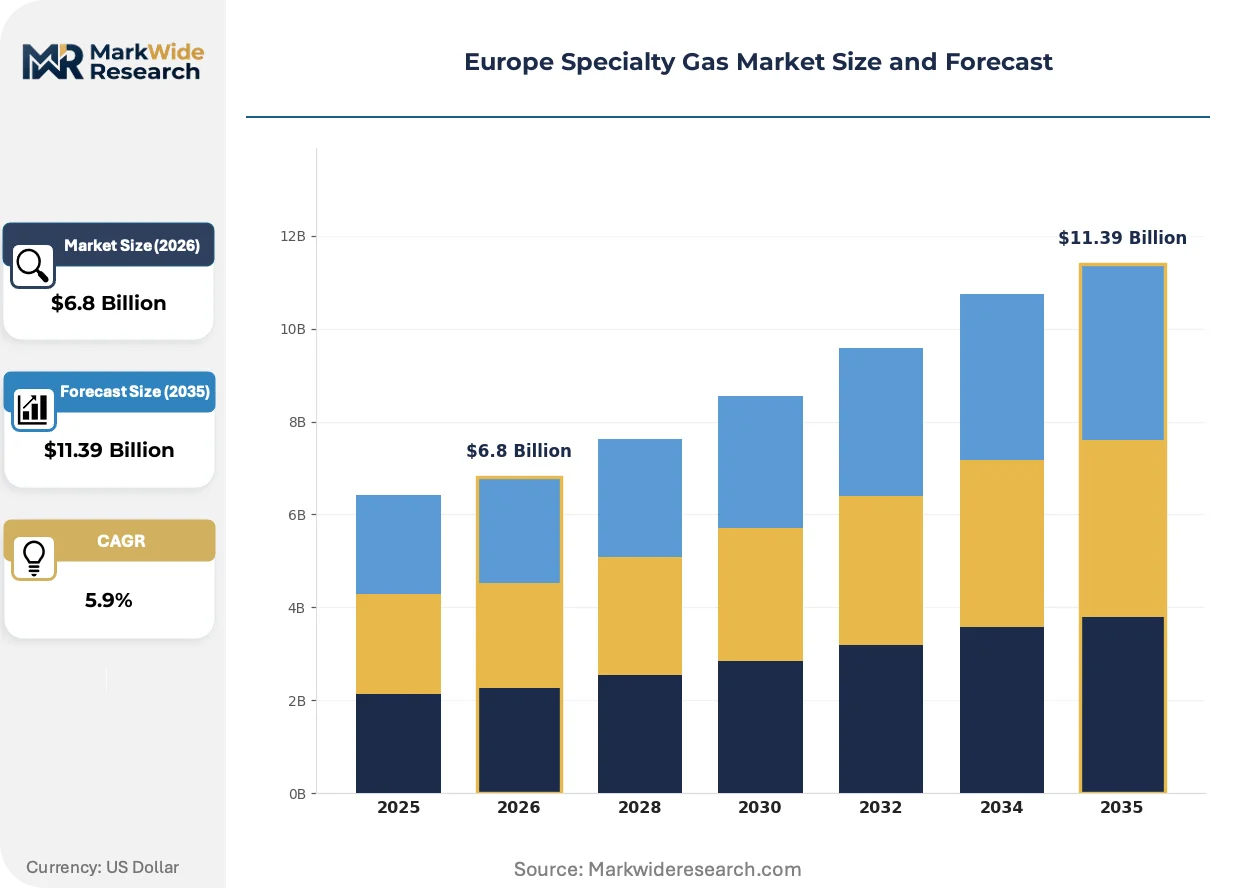
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Purity Gases, Liquefied Gases, Gas Mixtures, Specialty Chemicals Application: Electronics Manufacturing, Laboratories, Food Processing, Pharmaceuticals End User: Semiconductor Industry, Research Institutions, Beverage Industry, Healthcare Providers Distribution Channel: Direct Sales, Online Platforms, Distributors, Retail Stores |
| Companies Covered | Air Liquide SA, Linde PLC, Air Products and Chemicals Inc, Messer SE and Co. KGaA, Resonac Holdings Corp, Taiyo Nippon Sanso Corp, SOL Spa, Westfalen AG, BUSE KSW GmbH & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Specialty Gas Market Evolving Landscape
Hybrid purification architectures are compressing the trade-off between centralized bulk production and distributed point-of-use quality, reshaping capital deployment across the European supply base.
Membrane-cryogenic hybridization is advancing noble gas recovery from industrial off-gases. German steel producers are piloting this approach at Dortmund and Duisburg facilities. The technology is hybridizing supply chain economics by enabling mid-scale suppliers to source feedstock independently of Ukrainian neon imports.
REACH authorization procedures for per- and polyfluoroalkyl substances are tightening fluorinated precursor availability. ECHA's restriction roadmap forces reformulation of chamber-cleaning blends toward shorter-chain alternatives. Semiconductor fabs in the Netherlands and Ireland face accelerated qualification timelines for replacement chemistries.
Take-or-pay contracting is displacing spot procurement for high-volume electronics customers. German and French semiconductor clusters now demand decade-long supply agreements with embedded price escalation clauses. This shift concentrates volume commitments among integrated air separation operators with balance-sheet capacity for captive infrastructure.
Europe Specialty Gas Market Segmentation
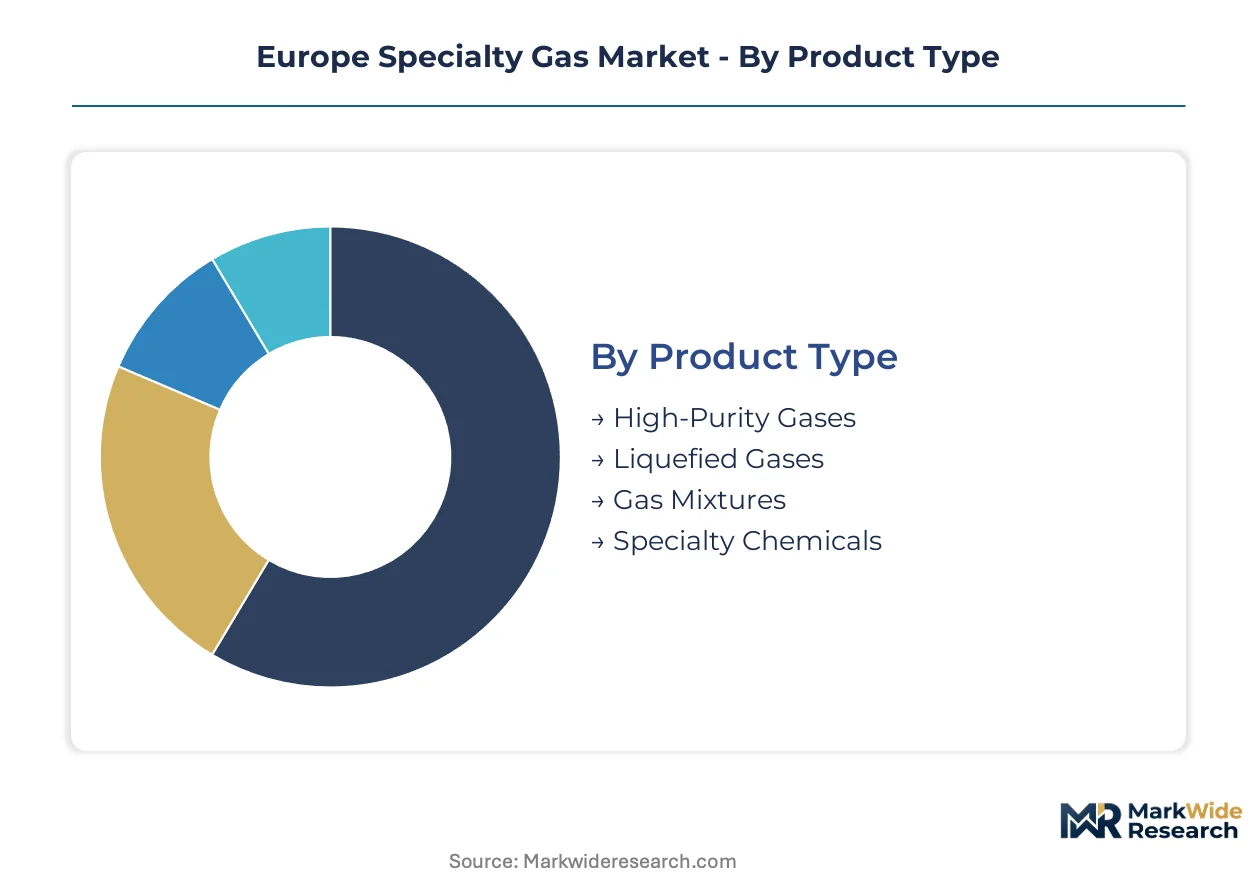
Segmentation in the European specialty gas market reveals how purification complexity and regulatory compliance create distinct value tiers. Each dimension—product chemistry, application criticality, and supply chain configuration—shapes procurement patterns and margin structures differently.
Product Type:
Mature purification technologies dominate commodity gas categories, while emerging hybrid architectures are compressing the gap between centralized bulk production and point-of-use quality.
- High-Purity Gases:Elemental gases refined to sub-ppb impurity thresholds through cryogenic distillation and catalytic scrubbing. EUV lithography fabs in the Netherlands and Germany anchor demand for xenon, neon, and krypton at these specifications, with ASML's supplier ecosystem enforcing captive supply requirements that exclude spot market sourcing.
- Gas Mixtures:Calibrated multi-component blends manufactured for analytical precision and process repeatability. Pharmaceutical quality control laboratories across France and Switzerland drive fastest expansion here, as EMA-mandated batch certification requires increasingly complex reference standards with documented traceability chains.
- Liquefied Gases:Cryogenic liquids stored and transported in vacuum-insulated vessels for high-density delivery. Bulk nitrogen and oxygen liquefaction serves steel and chemical clusters in the Ruhr and Antwerp.
- Specialty Chemicals:Fluorinated precursors and reactive gas formulations for etching and chamber cleaning. REACH authorization constraints are tightening availability of per- and polyfluoroalkyl substances, forcing reformulation toward shorter-chain alternatives.
High-purity gases handle the majority of throughput; gas mixtures are expanding most quickly on share.
Application:
Application segmentation tracks contamination sensitivity, with process-criticality determining specification grade and contract structure.
- Electronics Manufacturing:Semiconductor fabrication consumes the largest volume share, with sub-3nm node production requiring ultra-high-purity noble gases for EUV source chambers. German and Dutch fabs now demand decade-long take-or-pay contracts with embedded price escalation clauses.
- Pharmaceuticals:Batch-specific certification under EMA guidelines extends delivery cycles and commands premium pricing. Analytical method validation drives demand for multi-component calibration mixtures with documented uncertainty budgets.
- Laboratories:Research and quality control facilities require reference standards and carrier gases for chromatography and spectroscopy. Academic and industrial R&D spending patterns influence procurement cyclicality.
- Food Processing:Modified atmosphere packaging and cryogenic freezing applications utilize food-grade nitrogen and carbon dioxide. Carbonation systems for beverage production represent stable, volume-driven demand.
Electronics manufacturing absorbs the dominant volume position; pharmaceuticals achieves the steepest margin expansion trajectory.
End User:
End user segmentation reflects captive supply infrastructure penetration, with integrated air separation operators concentrating around high-volume semiconductor clusters.
- Semiconductor Industry:Leading-edge fabs in the Benelux corridor and Saxony operate on-site gas generation or pipeline-connected bulk supply. EUV lithography penetration below 5nm nodes concentrates noble gas demand among ASML's qualified supplier network.
- Research Institutions:Universities and national laboratories purchase cylinder quantities through framework agreements. Funding cycles and grant timelines introduce procurement seasonality.
- Healthcare Providers:Medical oxygen and nitrous oxide for anesthesia and respiratory therapy. Hospital procurement through group purchasing organizations emphasizes supply security over unit cost.
- Beverage Industry:Carbon dioxide for carbonation and nitrogen for dispensing systems. Regional brewery and soft-drink bottling operations favor distributed cylinder filling networks.
Semiconductor industry commands the largest contract values; healthcare providers deliver the most predictable demand profile.
Distribution Channel:
Channel structure in Europe specialty gas markets stratifies by volume scale and service intensity, with direct sales consolidating around high-volume electronics customers.
- Direct Sales:Long-term contracts with on-site generation, pipeline delivery, or dedicated bulk tank installations. German and French semiconductor clusters increasingly require embedded maintenance and purification upgrade services.
- Distributors:Regional cylinder filling and logistics networks serving mid-scale industrial and laboratory customers. Central European coverage remains fragmented among national operators.
- Online Platforms:E-procurement portals for standard-grade gases and consumables. Limited penetration in high-purity categories due to certification and handling requirements.
- Retail Stores:Welding supply outlets and hardware channels for hobbyist and small contractor segments. Lowest specification grades with minimal service attachment.
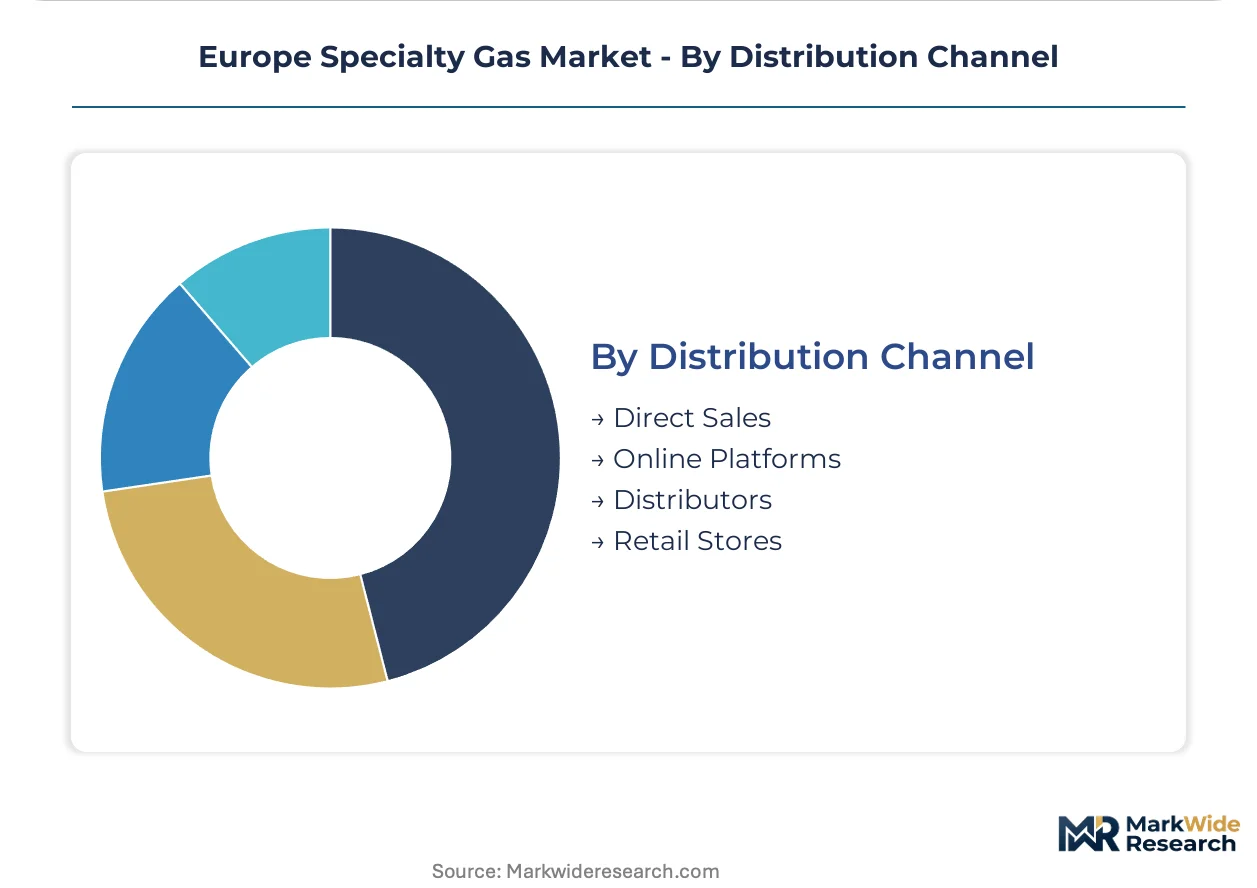
Direct sales captures the dominant share of revenue; distributors maintain the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Benelux corridor where ASML's lithography ecosystem anchors captive noble gas supply, while Central European suppliers compete on distributed cylinder networks at thinner margins.
Germany
Semiconductor fabs in Dresden and Munich drive xenon and krypton demand for EUV lithography below 5nm nodes. The EU F-Gas Regulation mandates hydrofluorocarbon phase-down quotas that redirect procurement toward reclaimed fluorinated alternatives. The Ruhr industrial cluster hosts steel off-gas recovery pilots at Dortmund and Duisburg facilities, enabling membrane-cryogenic hybridization for independent feedstock sourcing.
Netherlands
ASML's Veldhoven headquarters anchors a qualified supplier network enforcing sub-ppb purity standards for lithography gases. ECHA's REACH authorization roadmap tightens per- and polyfluoroalkyl substance availability, forcing accelerated qualification of shorter-chain chamber-cleaning chemistries. The Eindhoven-Brabant corridor concentrates on-site gas generation investments from integrated air separation operators.
France
Pharmaceutical quality control laboratories in Paris and Lyon expand demand for multi-component calibration mixtures under EMA-mandated batch certification. The CSRD disclosure framework incentivizes Scope 3 emissions reduction through recycled gas procurement. The Greater Paris semiconductor cluster secures decade-long take-or-pay contracts with embedded price escalation clauses.
Belgium
Antwerp's chemical hub liquefies bulk nitrogen and oxygen for steel and petrochemical clusters, while specialty purification facilities serve lithography supply chains. The EU Green Deal carbon border adjustments pressure feedstock sourcing transparency. The Port of Antwerp-Bruges logistics complex enables cryogenic liquid distribution across the Low Countries.
Poland
Emerging semiconductor manufacturing investments in Wrocław and Warsaw lack established captive gas infrastructure, opening on-site generation contract opportunities. National development funds target EU cohesion policy support for industrial gas distribution networks. The Silesian metallurgical belt vents recoverable krypton and xenon currently unexploited by membrane separation technology.
Europe Specialty Gas Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in purification and feedstock recovery. The European specialty gas market consolidates around integrated air separation operators with balance-sheet capacity for decade-long infrastructure commitments, while mid-scale regional suppliers fragment across cylinder filling and distribution logistics. Three archetypes dominate: captive on-site generators with semiconductor fab partnerships, industrial gas majors leveraging steel off-gas recovery, and national distributors with dense cylinder network coverage. Competitive dynamics center on vertical integration into noble gas recovery and strategic partnerships for EUV lithography qualification.
Within the integrated platform tier, Air Liquide SA and Linde PLC exemplify operators combining air separation assets with captive recycling infrastructure. Messer SE and Co. KGaA occupies a position among regional specialists competing through distributed pipeline networks and Central European cylinder filling capacity. These three entities represent distinct strategic postures: the French operator leverages helium recycling and semiconductor cluster proximity; the UK-domiciled major anchors krypton and xenon recovery from metallurgical off-gases; the German limited partnership competes on geographic coverage and mid-scale contract flexibility.
| Leading Market Players |
|---|
| Air Liquide SA |
| Linde PLC |
| Air Products and Chemicals Inc |
| Messer SE and Co. KGaA |
| Resonac Holdings Corp |
| Taiyo Nippon Sanso Corp |
| SOL Spa |
| Westfalen AG |
| BUSE KSW GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Ukrainian and Russian neon feedstock concentration upstream funnels margin capture toward Benelux purification facilities and ASML-qualified suppliers downstream. Long-term take-or-pay contracting for EUV-grade noble gases locks in decade-long price escalation clauses that insulate integrated operators from spot volatility.
Pricing Analysis
Configured-to-order pricing for semiconductor-grade xenon, neon, and krypton commands substantial premiums over standard industrial cylinder grades. Three-tier pricing structure across captive on-site supply, bulk liquid delivery, and packaged cylinder distribution reflects purification depth and certification burden. Pricing pressure stems from EMA-mandated batch certification extending pharmaceutical mixture delivery cycles without corresponding cost pass-through. Semiconductor fabs demonstrate least price sensitivity due to catastrophic yield loss from contamination, while food processing buyers prioritize unit cost over specification grade.
Supply Chain Analysis
Feedstock disruption exposure between Ukraine and European purification facilities dominates supply chain risk assessment. Cryogenic distillation capacity concentrates in Germany, the Netherlands, and France, drawing from Ukrainian neon, Qatari helium, and domestic steel off-gas krypton recovery. Single-source vulnerability runs through ASML's qualified supplier network for sub-ppb lithography gases. Distribution runs through pipeline-connected bulk supply for semiconductor clusters, regional cylinder filling networks for mid-scale industrial users, and vacuum-insulated tanker logistics for cryogenic liquids.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe specialty gas market tracks a cyclical recovery anchored to semiconductor capital expenditure cycles and EU F-Gas Regulation compliance deadlines.
For Market Incumbents: Build captive purification moats through membrane-cryogenic hybridization investments at steel off-gas recovery sites. Linde PLC's Dortmund and Duisburg pilots demonstrate the defensive value of independent krypton and xenon feedstock. Air Liquide SA should extend helium recycling assets to counter US Bureau of Land Management auction volatility. Threat substitution from reclaimed fluorinated alternatives under REACH authorization timelines demands accelerated qualification infrastructure.
For New Entrants and Emerging Players: Eastern European semiconductor greenfield sites in Poland and Romania represent the most penetrable entry point for on-site gas generation contracts. The Silesian metallurgical belt's unexploited krypton and xenon venting offers independent feedstock sourcing for membrane separation pilots. Pharmaceutical quality control laboratories in secondary cities lack established calibration mixture suppliers, opening EMA-certified service angles. Go-to-market positioning as REACH-compliant reformulation partners for fluorinated etching blends bypasses incumbent certification advantages.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional cylinder distributors lacking captive purification infrastructure. Long-term viability over a five-to-ten year horizon favors operators with integrated air separation and noble gas recovery capabilities. Acquisition targets should demonstrate qualified supplier status within ASML's ecosystem or embedded maintenance contracts with decade-long tenors. Watch EU F-Gas Regulation threshold revisions as the inflection signal for reclaimed gas infrastructure valuation step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Steel Off-Gas Recovery Infrastructure | Membrane-cryogenic hybridization at Dortmund and Linz facilities reduces Ukrainian neon dependence. |
| Long-term Take-or-Pay Contracting | Decade-long agreements with German and Dutch semiconductor fabs lock in pricing power and volume commitments. |
| REACH-Compliant Reformulation | Shorter-chain fluorinated alternatives for chamber-cleaning blends secure continued fab access under ECHA restrictions. |
| Helium Recycling Asset Expansion | Circular recovery infrastructure counters US BLM reserve auction volatility and Qatar liquefaction capacity constraints. |
| Eastern European On-Site Generation | Polish and Romanian fab investments lack established captive supply, opening greenfield contract opportunities. |
Research Methodology
Operator-level perspectives from plant managers at air separation facilities, procurement leads at semiconductor fabs, EMA regulatory affairs specialists, and steel mill gas recovery engineers anchored the qualitative base. Primary interview findings triangulated against secondary sources including ECHA substance registration databases, EU F-Gas Regulation compliance filings, SEC 10-K disclosures from listed industrial gas operators, and Cefic chemical industry trade data. Bottom-up volume modeling across purification capacity and top-down macroeconomic anchoring ensured cross-validation.
Scenario-bracketing around semiconductor capital expenditure cycles and REACH authorization timelines structured the analytical framework across the analysis window. Segmentation dimensions modeled include gas chemistry type, application criticality tier, distribution channel configuration, and regional regulatory cluster. CAGRs derived from installed base growth rates, node shrinkage penetration curves, and fluorinated gas phase-down quotas. Forecast inputs incorporated EUV lithography adoption trajectories and steel off-gas recovery technology deployment schedules.
Macroeconomic conditions sit as an overlay; deviation in semiconductor demand, energy input costs, or geopolitical feedstock access would shift the trajectory. Forecasts reflect documented assumptions regarding purification technology maturation and regulatory deadline adherence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Helium Gas Market
Industrial Gases
Semiconductor Gases Market
Industrial Gases
Neon Gas for Laser Market
Industrial Gases
Global Laboratory Gas Generators Market
Industrial Gases
High Purity Gas Market
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
Global Nitrogen Market
Industrial Gases
Xenon Gas Market
Industrial Gases
Industrial Gas Regulator Market
Industrial Gases
Oxygen Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Middle-East and Africa Syngas Market
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
Global Argon Market
Industrial Gases
Syngas Market
Industrial Gases
Acetylene Gas Market